
 Canada POS Terminal Market | 2026-2036
Canada POS Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
Canada POS Terminal Market Outlook
Buyer concentration across Canadian mid-market retail chains is rebalancing as independent hospitality operators and regional grocery cooperatives expand terminal procurement. NCR Corporation leverages its established banking relationships to sustain deployment momentum across credit union networks. Samsung Electronics Co., Ltd. anchors the mobile POS segment through Android-based hardware with integrated payment modules. Ingenico Group SA differentiates via EMV certification depth that controls access to tier-one merchant accounts.
A POS terminal is an electronic device combining secure payment processing hardware, cryptographic modules, and connectivity interfaces to authenticate and settle card-based transactions at the point of sale. These systems typically incorporate PCI PTS-certified pin pads, thermal receipt printers, and ARM-based processors operating at frequencies above 1 GHz to ensure sub-three-second transaction authorization. Mobile POS and contactless technology are expanding fastest as Canadian merchants prioritize countertop footprint reduction and tap-to-pay speed, while fixed POS remains the mature revenue base where margin pools concentrate in extended service contracts. Cloud-based deployment is gaining share as SaaS models shift capital expenditure to predictable operating budgets for franchise operators.
Payments Canada sets the operational framework for clearing and settlement infrastructure, while the Office of the Privacy Commissioner enforces PIPEDA compliance that shapes terminal data-handling architectures. Health Canada and provincial regulators influence healthcare segment procurement through patient-data security requirements that restrict cloud-connected devices in clinical settings. Stakeholders must monitor how forthcoming open-banking regulations alter terminal software stack requirements and authentication protocols.
Market Dynamics
Payments Canada's contactless mandate is forcing a wholesale hardware refresh across Canadian merchant fleets, compressing replacement cycles from seven years to under four as tap-to-pay becomes the default transaction method.
Growth Catalysts
- Contactless Mandate:Payments Canada's tap-to-pay requirements are eliminating mag-stripe fallback options, compelling merchants to upgrade to NFC-capable terminals before legacy sunset deadlines.
- Quick-Service Restaurant Expansion:Canadian QSR chains are deploying countertop-minimalist terminals to accelerate throughput during peak hours, prioritizing sub-two-second authorization speeds.
- Cloud SaaS Migration:Franchise operators are abandoning on-premise software licenses for subscription-based terminal management, converting capital expenditure into predictable operating budgets.
Market Restraints
- EMV Certification Bottlenecks:Ingenico and Verifone control tier-one certification pathways, creating 12-18 month approval queues that freeze out smaller hardware vendors from major merchant accounts.
- Semiconductor Supply Concentration:ARM-based processor fabrication concentrates in Taiwan, exposing Canadian terminal OEMs to geopolitical supply disruptions and foundry allocation constraints.
- PIPEDA Compliance Architecture:The Office of the Privacy Commissioner's data-handling rules require on-device encryption modules that add $40-60 per unit to bill-of-materials costs.
Strategic Opportunities
- Healthcare Vertical Penetration:Provincial patient-data security requirements currently restrict cloud-connected devices in clinical settings, creating a captive market for air-gapped terminal solutions.
- Open Banking Convergence:Account-to-account payment rails under development by Payments Canada will demand new authentication protocols, opening software stack upgrade cycles.
- Mobile POS Expansion:Samsung's Android-based integrated modules are capturing independent hospitality operators who rejected traditional countertop footprints.
Industry Challenges
- Legacy System Integration:Regional grocery cooperatives operate 1990s-era ERP backends that require costly middleware development to interface with modern PCI PTS 6.x terminals.
- Cryptographic Module Sourcing:Qualified Security Assessor shortages are extending hardware certification timelines, delaying product launches beyond planned refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada POS Terminal Market |
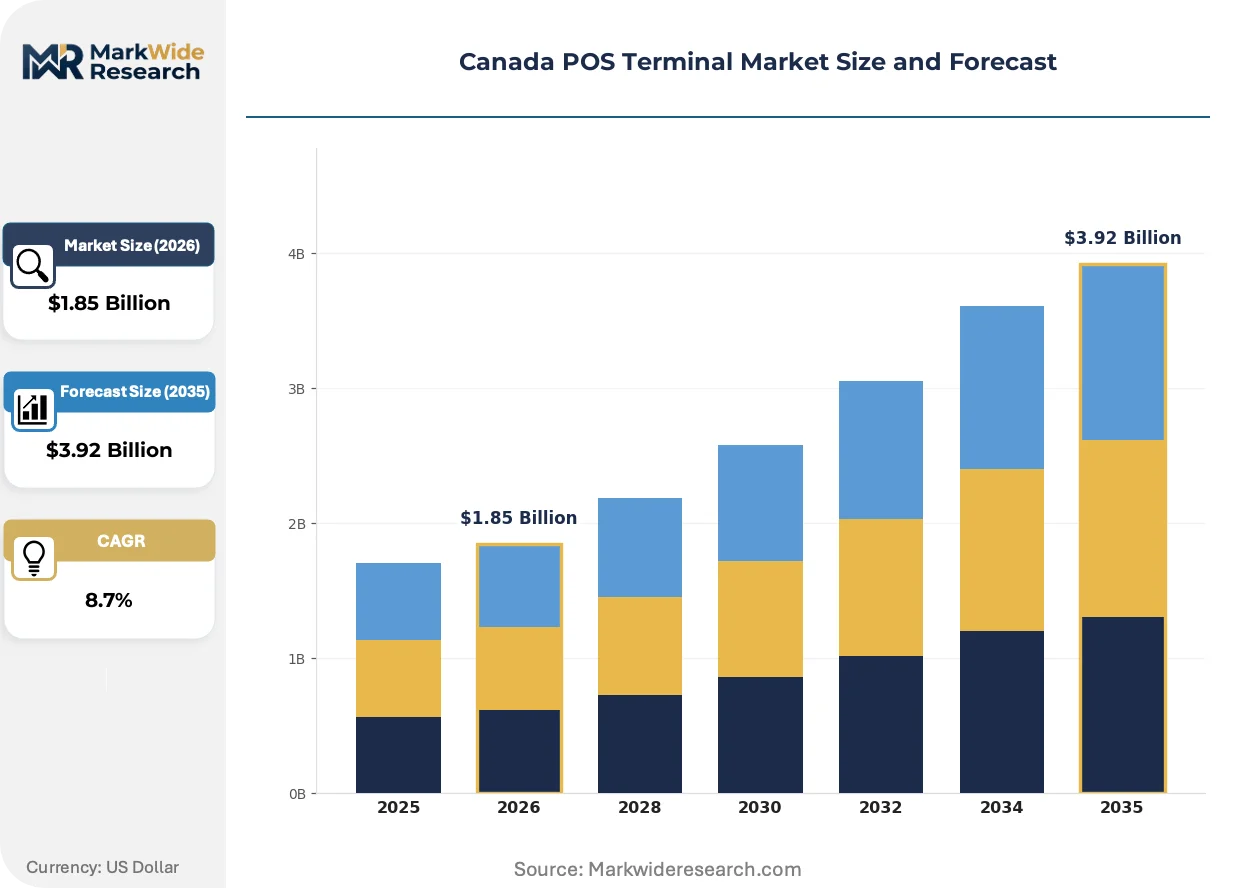
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Self-Service Kiosk, Integrated Terminal Technology: Contactless, EMV, NFC, Bluetooth End User: Retail, Hospitality, Entertainment, Healthcare Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Panasonic Corporation, NCR Corporation, Samsung Electronics Co., Ltd., Verifone Systems Inc., Fujitsu Ltd., Ingenico Group SA, NEC Corporation, PAX Technology, HP Development Company LP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada POS Terminal Market Strategic Shifts
Terminal architecture is fragmenting into componentized layers as merchants demand flexibility across payment rails, form factors, and software ecosystems without full hardware replacement.
SoftPOS technology is modularizing smartphone and tablet hardware into payment acceptance devices through downloadable applications and NFC antenna accessories. Independent coffee chains and pop-up retail operators are adopting these solutions fastest, avoiding dedicated terminal procurement entirely. This convergence is compressing addressable market volume for traditional countertop hardware while expanding software and security licensing revenue pools.
PIPEDA enforcement by the Office of the Privacy Commissioner is tightening data residency requirements for transaction logs and biometric authentication records. Terminal manufacturers must now architect on-device storage with Canadian cloud backup options, eliminating US-only data center dependencies. Healthcare and government procurement segments are responding by mandating domestic encryption key custody in RFP specifications.
Independent hospitality operators are consolidating purchasing through buying cooperatives that negotiate fleet-scale pricing previously reserved for tier-one retail chains. These aggregators are unbundling after-sales service contracts from hardware procurement, selecting third-party maintainers based on response-time SLAs rather than OEM relationships. Ontario's Greater Toronto Area exhibits this pattern most visibly, where restaurant associations pool terminal orders across hundreds of member establishments.
Canada POS Terminal Market Segmentation
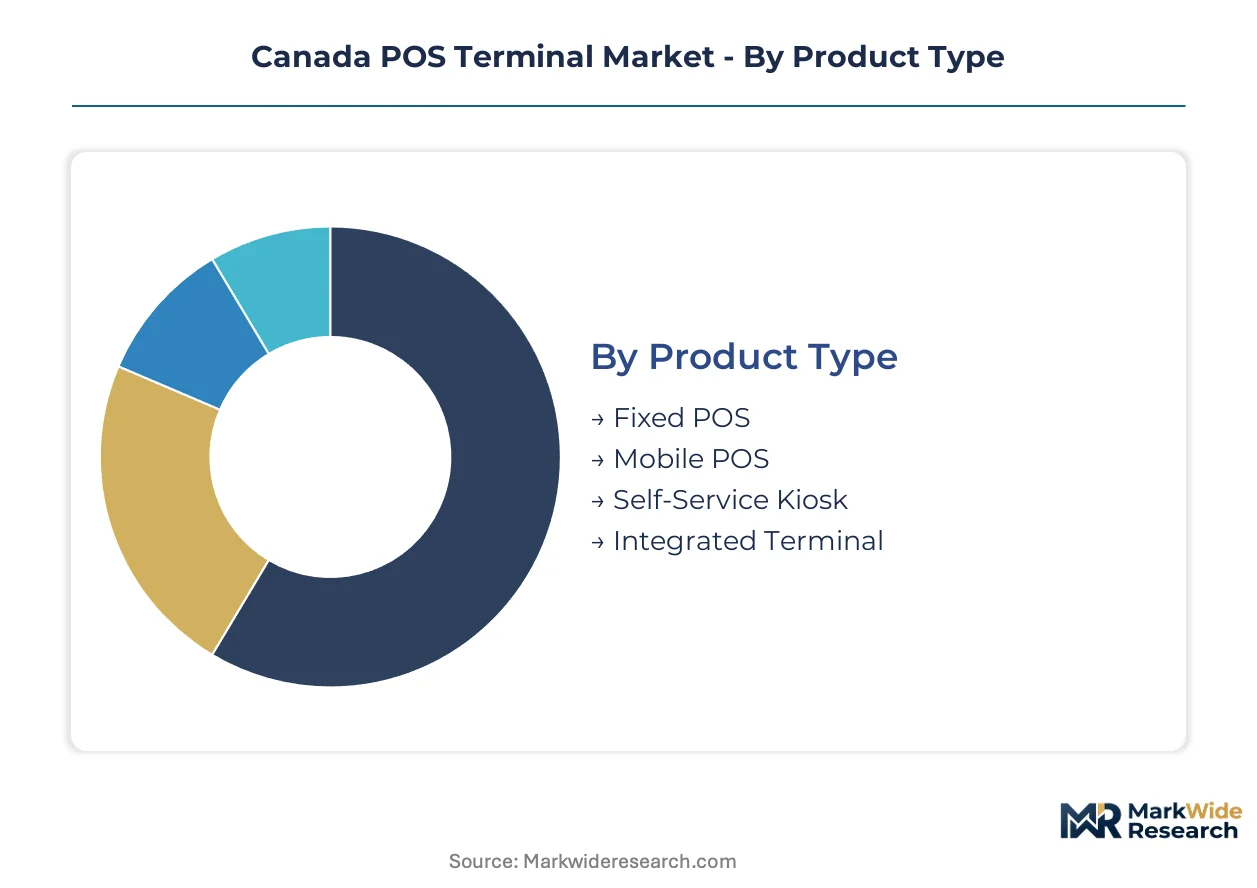
Canadian merchants select terminal architectures based on countertop constraints, transaction velocity requirements, and franchise-scale fleet management needs. Procurement patterns diverge sharply between independent operators prioritizing footprint minimalism and national chains demanding centralized terminal orchestration.
Product Type:
Hardware selection hinges on mobility requirements versus throughput optimization, with countertop real estate costs in Ontario's dense retail corridors driving form-factor decisions.
- Fixed POS:Stationary terminals with tethered pin pads and integrated receipt printers dominate grocery and big-box deployments. Ontario's regional grocery cooperatives maintain these systems for seven-year replacement cycles, though Payments Canada's contactless mandate is compressing refresh timelines.
- Mobile POS:Battery-powered Android tablets with detachable payment modules capture independent hospitality operators in Quebec and British Columbia. Samsung's integrated hardware-software stack eliminates countertop footprint entirely, accelerating adoption among coffee chains and food trucks.
- Self-Service Kiosk:Freestanding units with customer-facing touchscreens and integrated card readers serve QSR drive-through lanes and cinema box offices. Deployment concentrates in Alberta's oil-sand worker accommodation facilities and Toronto Pearson International Airport retail clusters.
- Integrated Terminal:All-in-one systems combining payment processing, inventory management, and customer analytics appeal to mid-market retail chains. These units carry premium bill-of-materials costs but reduce middleware integration complexity for 1990s-era ERP backends.
Volume sits with Fixed POS; growth tilts toward Mobile POS.
Technology:
Certification depth and interoperability standards determine vendor access to tier-one merchant accounts, creating technology-tier stratification.
- Contactless:NFC-enabled tap-to-pay protocols now dominate transaction authorization speeds under two seconds. Payments Canada's mandate elimination of mag-stripe fallback has made this capability non-negotiable across all new terminal procurements.
- EMV:Chip-card authentication with cryptographic verification remains mandatory for card-present transactions. Ingenico and Verifone control certification pathways, creating twelve-to-eighteen-month approval queues that constrain hardware vendor entry.
- NFC:Near-field communication modules enable smartphone wallet acceptance and transit card integration. Toronto Transit Commission fare system compatibility has become a procurement specification for downtown Toronto retail deployments.
- Bluetooth:Wireless pairing protocols connect peripheral pin pads to tablet-based terminals. Independent coffee chains leverage this technology to position customer-facing readers at drive-through windows while retaining staff tablets indoors.
Revenue concentrates in EMV; expansion accelerates fastest in Contactless.
End User:
Vertical-specific data-handling requirements and patient-privacy regulations create segment-captive procurement patterns.
- Retail:High-volume transaction processing with inventory synchronization dominates grocery and apparel deployments. The Greater Toronto Area's dense retail corridors drive fleet-scale terminal orders with unified fleet management requirements.
- Hospitality:Tableside payment acceptance and tip-adjustment workflows shape restaurant and hotel specifications. Independent operators in Vancouver and Montreal are consolidating purchasing through buying cooperatives that negotiate fleet-scale pricing.
- Entertainment:Seasonal demand spikes and outdoor venue durability requirements influence cinema and stadium procurements. These deployments prioritize ruggedized hardware with extended temperature operating ranges.
- Healthcare:Provincial patient-data security requirements restrict cloud-connected devices in clinical settings, creating demand for air-gapped terminal solutions. Health Canada oversight shapes encryption module specifications and data residency architectures.
Procurement volume clusters in Retail; Healthcare exhibits the steepest expansion trajectory as regulatory compliance creates upgrade imperatives.
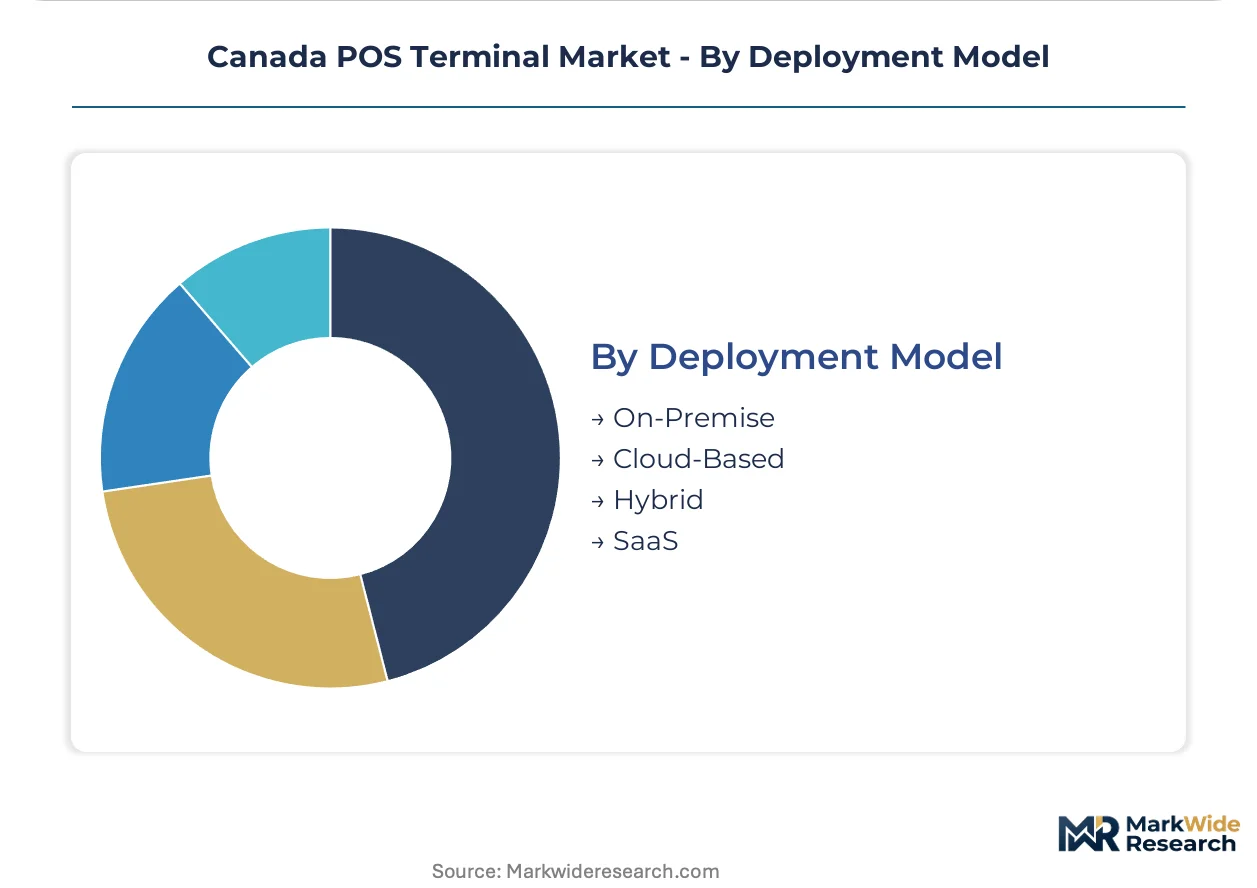
Deployment Model:
Capital structure preferences and IT resource availability determine cloud-versus-on-premise architecture selection.
- On-Premise:Perpetual software licenses with local server infrastructure persist among legacy grocery cooperatives with dedicated IT staff. These deployments minimize recurring subscription costs but require internal security patch management.
- Cloud-Based:Browser-accessible terminal management portals with automatic software updates appeal to franchise operators lacking technical personnel. The Office of the Privacy Commissioner's PIPEDA enforcement now mandates Canadian data center residency for transaction logs.
- Hybrid:Split architectures with local transaction processing and cloud-based reporting balance latency sensitivity with centralized oversight. Regional retail chains in Calgary and Ottawa favor this model for multi-location visibility without full internet dependency.
- SaaS:Subscription-based terminal management converts capital expenditure into predictable operating budgets, accelerating adoption among quick-service restaurant franchisees. These contracts typically bundle hardware, software, and payment processing into per-transaction fees.
Installed base remains On-Premise; new deployment share is climbing fastest in SaaS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's silicon foundry feedstock pipelines anchor Canadian terminal hardware assembly, with Greater Toronto Area distribution centers channeling ARM-based processors into domestic OEM production lines.
Ontario
Greater Toronto Area retail corridors drive fleet-scale terminal deployments across grocery cooperatives and QSR chains. Payments Canada's contactless mandate compresses replacement cycles from seven years to under four. Toronto Pearson International Airport retail clusters concentrate self-service kiosk installations serving transient worker populations.
Quebec
Montreal's independent hospitality operators consolidate purchasing through restaurant association buying cooperatives. The Office of the Privacy Commissioner's PIPEDA enforcement shapes data residency architectures for cloud-connected terminals. Battery-powered Android tablets with detachable payment modules capture coffee chain deployments across downtown Montreal.
British Columbia
Vancouver's dense restaurant corridors prioritize countertop-minimalist terminals for tableside payment acceptance. Health Canada oversight restricts cloud-connected devices in provincial healthcare procurement, creating demand for air-gapped solutions. Independent food truck operators adopt Samsung's integrated hardware-software stack for zero-footprint deployments.
Alberta
Oil-sand worker accommodation facilities drive ruggedized self-service kiosk installations with extended temperature operating ranges. Regional retail chains in Calgary favor hybrid deployment architectures balancing local transaction processing with cloud-based reporting. Franchise operators abandon on-premise software licenses for subscription-based terminal management.
Atlantic Canada
Halifax and St. John's credit union networks sustain NCR Corporation deployment momentum through established banking relationships. Provincial patient-data security requirements in Nova Scotia and Newfoundland restrict terminal procurement to on-device encryption modules. Regional grocery cooperatives operate legacy ERP backends requiring costly middleware development for modern PCI PTS 6.x terminal integration.
Canada POS Terminal Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mobile-first and SoftPOS architectures. The vendor base stratifies across three tiers: multinational electronics conglomerates with integrated semiconductor supply chains, specialized payment hardware OEMs with EMV certification depth, and software-centric challengers modularizing smartphone hardware into acceptance devices. Competitive positioning hinges on certification queue access, foundry allocation security, and Canadian data center residency for PIPEDA compliance.
Within the multinational tier, Panasonic Corporation and Fujitsu Ltd. anchor hardware supply relationships with tier-one merchant accounts. Samsung Electronics Co., Ltd. exemplifies the mobile-first vector through Android-based integrated modules capturing independent hospitality operators. NCR Corporation occupies a distinct position leveraging banking relationships across credit union networks. These three entities represent divergent strategic archetypes: component-integrated manufacturing, mobile ecosystem leverage, and financial services channel dominance.
| Leading Market Players |
|---|
| Panasonic Corporation |
| NCR Corporation |
| Samsung Electronics Co., Ltd. |
| Verifone Systems Inc. |
| Fujitsu Ltd. |
| Ingenico Group SA |
| NEC Corporation |
| PAX Technology |
| HP Development Company LP |
| Others |
Value Chain & Pricing Dynamics
Payments Canada's contactless mandate elimination of mag-stripe fallback options is compressing merchant refresh cycles and forcing supply chains to prioritize NFC module availability over cost optimization, elevating pricing power for EMV-certified vendors.
Pricing Analysis
After-sales service bundling separates tier-one deployments from independent operator procurements, with NCR Corporation and Ingenico Group SA commanding premium positioning through multi-year maintenance contracts while buying cooperatives negotiate unbundled hardware-only pricing. Three-tier pricing structure across premium, standard, and economy levels reflects EMV certification depth, countertop footprint, and cloud-connectivity architecture. Cost compression in the standard tier is intensifying because Samsung's Android-integrated modules eliminate middleware licensing fees. Franchise operators exhibit highest price sensitivity, whereas healthcare procurement segments prioritize domestic encryption key custody over unit economics.
Supply Chain Analysis
Greater Toronto Area distribution centers channel ARM-based processors from Taiwan and South Korea into domestic OEM assembly lines, with final-mile logistics feeding Quebec and British Columbia retail corridors. Canadian terminal production draws from Taiwan semiconductor foundries, South Korea memory component suppliers, and China peripheral manufacturing. Single-source vulnerability concentrates in Taiwan's advanced node fabrication, exposing hardware vendors to geopolitical allocation constraints. Distribution runs through hub-and-spoke patterns anchored by Ontario assembly facilities with regional satellite warehouses serving provincial grocery cooperative networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada POS Terminal Market competition is becoming a vertical-integration race, with incumbent vendors pursuing captive control over EMV certification pathways and cloud data center residency to defend margin pools.
For Market Incumbents: Lock in certification queue priority by deepening relationships with Payments Canada and Qualified Security Assessors, insulating against SoftPOS challengers modularizing smartphone hardware. Defend position by acquiring Canadian data center capacity for PIPEDA-compliant transaction log residency, neutralizing privacy regulation as a competitive wedge.
For New Entrants and Emerging Players: PIPEDA enforcement by the Office of the Privacy Commissioner in Canada opens a window for air-gapped terminal architectures in provincial healthcare procurement. Target Atlantic Canada credit union networks and Nova Scotia clinical settings with on-device encryption modules. Pursue buying cooperative partnerships in Montreal and Vancouver restaurant associations to bypass tier-one merchant account barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with EMV certification specialists given Payments Canada's open-banking protocol development and authentication stack upgrade cycles. Long-term viability favors vendors with foundry allocation security and Canadian cloud infrastructure. Monitor SoftPOS adoption rates among independent coffee chains as inflection indicator for traditional hardware volume displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Certification Depth Investment | Controls access to tier-one merchant accounts through Payments Canada pathways. |
| Canadian Data Center Residency | Enables PIPEDA compliance for cloud-connected terminal management portals. |
| SoftPOS Platform Development | Captures independent hospitality operators rejecting countertop footprints. |
| Healthcare Vertical Specialization | Addresses Health Canada encryption requirements for air-gapped clinical deployments. |
| Buying Cooperative Channel Partnership | Unlocks fleet-scale pricing for aggregated independent restaurant procurement. |
Study Parameters
Multi-period observation of terminal refresh cycle compression, contactless transaction velocity, and cloud SaaS migration rates anchored the trend analysis, supplemented by interviews with Payments Canada policy officers, credit union procurement directors, QSR franchise operations managers, and healthcare IT compliance leads. Secondary validation drew from Payments Canada clearing and settlement reports, Office of the Privacy Commissioner enforcement disclosures, Health Canada medical device guidance, and provincial patient-data security frameworks. Bottom-up terminal deployment counts across Ontario, Quebec, and British Columbia retail corridors were triangulated against top-down OEM revenue segmentation.
Input-output matrices modeled hardware unit shipments against subscription revenue conversion, segmentation dimensions spanning product type, technology certification tier, end-user vertical, and deployment architecture. CAGRs were derived from logistic diffusion curves fitted to contactless mandate compliance deadlines and franchise operator SaaS adoption patterns. Industry-specific forecast inputs included EMV certification queue durations and foundry allocation constraints for ARM-based processors.
The model assumes a particular technology adoption path; alternative pathways for SoftPOS smartphone-based acceptance would alter the outlook through accelerated countertop hardware displacement. Forecasts reflect assumptions regarding Payments Canada mandate timelines and semiconductor supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Digital Remittance Service Market
Payments
Egypt Mobile Payments Market
Payments
Poland Payments Market
Payments
Argentina Payments Market
Payments
Europe Real Time Payments Market
Payments
Enterprise Payment Software Market
Payments
Accelerator Card Market
Payments
Global Gift Card Market
Payments
Vietnam Payments Market
Payments
Remote Deposit Capture Market
Payments
Tanzania Mobile Money Market
Payments
Global Accounts Payable Software Market
Payments
Online Charging System (OCS) Market
Payments
India RTP Market
Payments
North America Mobile Payments Market
Payments
India Gift Card and Incentive Card Market