
 Auto Finance Market | 2026-2036
Auto Finance Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Finance Market Analysis
Loan origination revenue is reconfiguring how auto finance providers allocate capital between direct lending and dealership floorplan services. Ally Financial leverages its digital platform to streamline credit decisioning across the United States. Toyota Financial Services anchors its competitive position through captive financing tied to vehicle sales channels. Capital One differentiates via data-driven risk scoring that targets near-prime borrower segments.
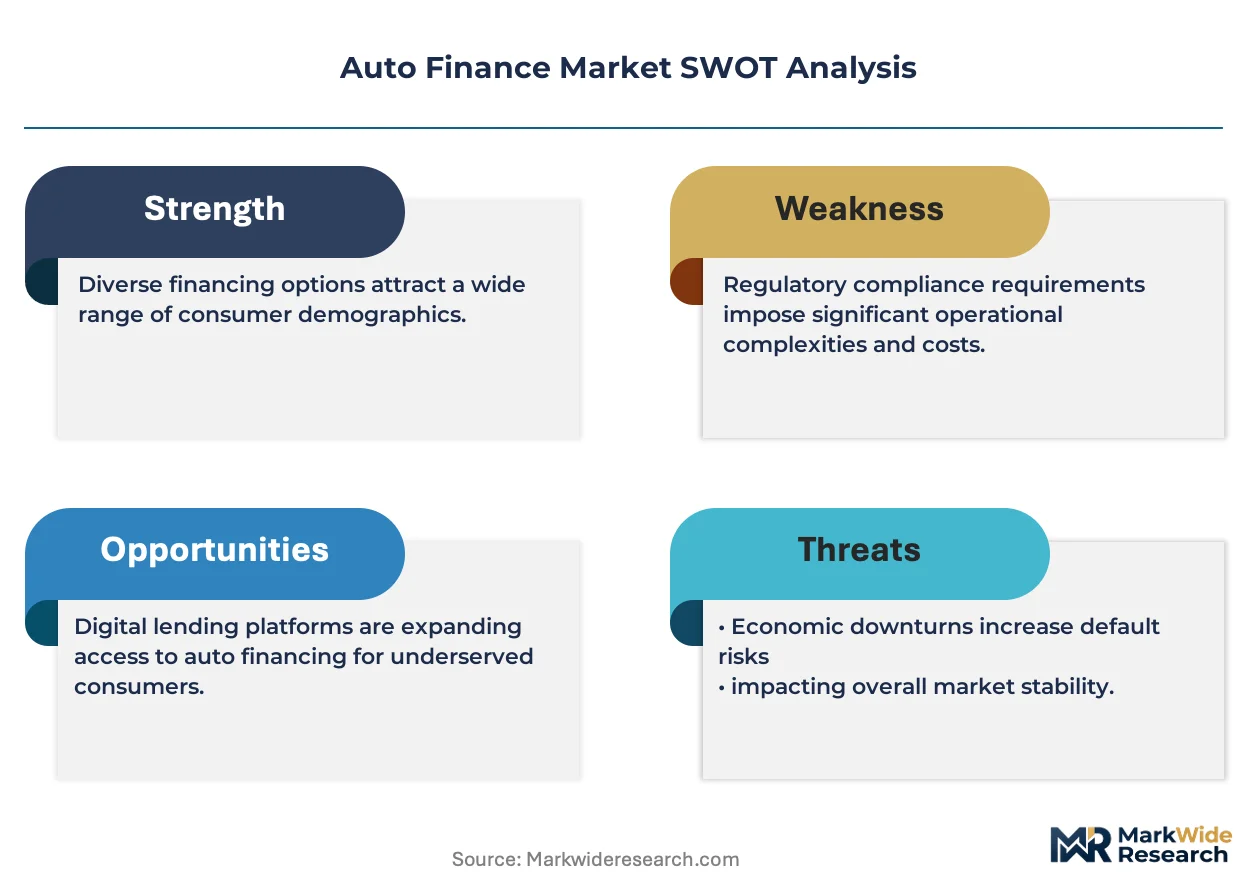
Auto finance encompasses credit instruments and lease structures used to fund vehicle acquisition, typically involving interest rate terms of 36 to 72 months and collateralized by the underlying automobile. The sector enables consumers and commercial entities to convert large capital expenditures into periodic cash outflows. Lease structures within the Finance Option category command elevated margins due to residual value management complexity. Electric Vehicles within the Vehicle Type dimension attract preferential rate structures as battery depreciation curves reshape lender risk models.
The US Consumer Financial Protection Bureau mandates standardized disclosure protocols for auto lending transactions. The European Banking Authority imposes capital reserve requirements on vehicle asset-backed securities. The Reserve Bank of India regulates non-banking finance company exposure limits for commercial vehicle lending. Stakeholders must monitor how central bank rate trajectories alter net interest margin sustainability across origination channels.
Market Dynamics
Residual value uncertainty for battery electric vehicles is forcing lenders to rebuild risk models around depreciation curves that diverge sharply from internal combustion engine collateral. This structural recalculation touches every layer of origination, securitization, and portfolio management.
Growth Catalysts
- Captive finance integration:OEM-affiliated lenders leverage vehicle sales data to pre-approve borrowers at point of sale, compressing decision timelines from days to minutes.
- India's RBI exposure limit expansion:The central bank's relaxed caps on non-banking finance companies for commercial vehicle lending unlocks fleet operator credit access.
- Embedded telematics:Real-time vehicle tracking enables usage-based underwriting and dynamic residual value adjustments throughout the loan term.
Market Restraints
- Lithium-ion battery replacement cost volatility:Uncertain second-life battery valuations complicate end-of-lease residual forecasting for electric vehicle portfolios.
- US CFPB disclosure mandate complexity:Standardized lending document requirements increase compliance overhead for smaller regional banks and credit unions.
- Semiconductor supply concentration:Taiwan and South Korea chip fabrication bottlenecks extend vehicle delivery timelines, delaying loan activation and interest accrual.
Strategic Opportunities
- German electric vehicle subsidy alignment:Federal purchase incentives and tax-advantaged leasing structures create preferential rate environments for battery electric financing.
- Subscription-to-ownership conversion:Flexible short-term vehicle access programs serve as lead generation pipelines for traditional term financing products.
- Blockchain-enabled smart contracts:Automated collateral registration and payment settlement reduce title transfer friction across cross-border lease portfolios.
Industry Challenges
- Data science talent scarcity:Predictive modeling for electric vehicle residual values demands scarce skill sets combining automotive engineering and quantitative finance expertise.
- Legacy core system integration:Mainframe-based loan servicing platforms require expensive middleware development to connect with digital origination channels and telematics data feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Finance Market |
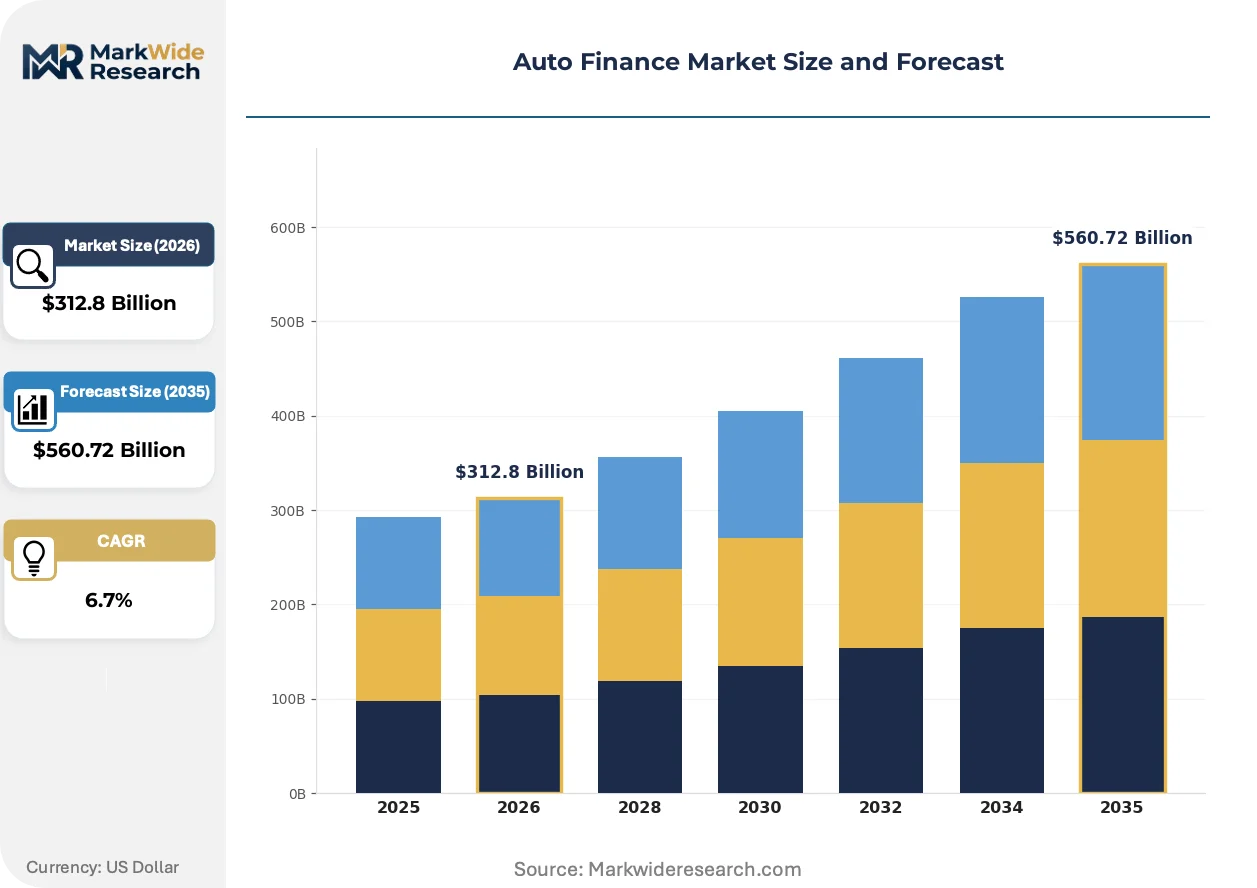
| Market Size in 2026 | $312.8 Billion |
| Market Size in 2035 | $560.72 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Finance Option: Lease, Loan, Hire Purchase, Balloon Payment Customer Type: Individual, Business, Fleet, Dealership Payment Method: Cash Payment, Installments, Direct Debit, Credit Card Vehicle Type: New Cars, Used Cars, Electric Vehicles, SUVs |
| Companies Covered | Ally Financial, Capital One, Bank of America, Ford Motor Credit Company, GM Financial, Toyota Financial Services, Volkswagen Financial Services, Daimler Financial Services, Wells Fargo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Finance Market Emerging Trajectories
Artificial intelligence is restructuring how auto finance providers assess creditworthiness, moving beyond static FICO scores toward dynamic behavioral signals. This shift enables finer risk stratification but demands new governance frameworks.
Machine learning underwriting is migrating from rule-based credit scoring toward real-time income verification through bank account aggregation and employment data APIs. Subprime and near-prime lenders adopt these tools fastest to compete with prime-rate incumbents. The technology is compressing the spread between risk-adjusted pricing tiers by revealing hidden creditworthiness in thin-file borrowers.
The European Banking Authority's capital reserve requirements for vehicle asset-backed securities now mandate granular loan-level disclosure and stress testing against macroeconomic shocks. Issuers must demonstrate portfolio resilience to interest rate spikes and unemployment surges. German and French auto finance subsidiaries face the steepest compliance curves as they securitize the largest European ABS volumes.
Fleet procurement patterns are fragmenting from centralized national contracts toward regional operating lease arrangements managed through digital platforms. Small and mid-size fleet operators gain access to terms previously reserved for enterprise accounts. This behavior shift concentrates fastest in the United Kingdom and Netherlands where mobility-as-a-service providers intermediate vehicle supply.
Auto Finance Market Segmentation
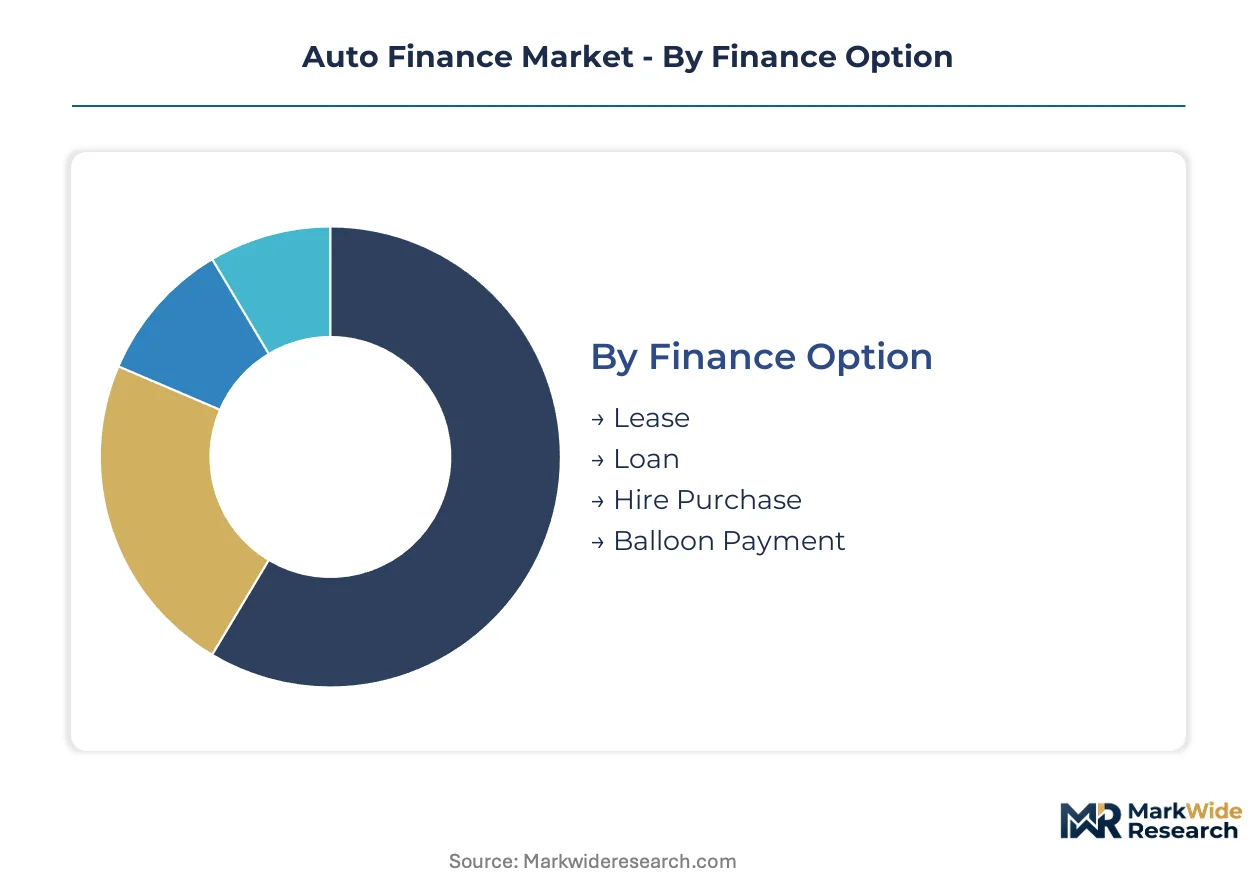
Auto finance segmentation reveals how capital allocation strategies diverge across collateral types, customer risk profiles, and payment infrastructure. Lenders calibrate product design, pricing tiers, and servicing technology stacks to each segment's cash flow patterns and residual value characteristics.
Finance Option:
The use-case spectrum spans from ownership-transfer structures to temporary access arrangements, each demanding distinct underwriting frameworks and balance sheet treatments.
- Lease:Closed-end and open-end lease structures transfer residual value risk to the lessor while preserving lessee flexibility. German fleet operators concentrate demand here, drawn by tax-advantaged treatment and battery electric vehicle subsidy alignment that compresses monthly payments.
- Loan:Direct and indirect installment credit remains the dominant origination channel across United States and Indian markets. Simple interest amortization appeals to individual borrowers seeking equity buildup, though rising central bank rates squeeze net interest margins for regional bank portfolios.
- Hire Purchase:Title retention structures dominate United Kingdom commercial vehicle financing, with final balloon payments aligned to asset depreciation schedules. Small business borrowers favor the VAT recovery mechanics embedded in these contracts.
- Balloon Payment:Deferred principal structures concentrate in Australian and South African markets where seasonal income patterns favor lower periodic obligations. Refinancing risk at term end requires active borrower monitoring.
The dominant share belongs to Loan structures, while Lease is closing the gap fastest as fleet electrification accelerates residual value management specialization.
Customer Type:
Cost tier differentiation separates mass-market individual borrowers from sophisticated commercial entities with consolidated credit facilities and telematics-enabled underwriting.
- Individual:Retail borrowers access credit through dealership captive finance arms or direct bank channels, with FICO-based pricing stratification. Near-prime segments attract fintech-enabled income verification tools that compress approval timelines.
- Business:Corporate borrowers negotiate master loan agreements with covenant structures tied to fleet size and utilization metrics. United States middle-market companies leverage equipment finance expertise from regional banks.
- Fleet:National and regional operators command preferential rates through volume commitments and embedded telematics data sharing. United Kingdom and Netherlands mobility-as-a-service intermediaries are fragmenting procurement toward shorter operating lease terms.
- Dealership:Floorplan financing and consumer credit referral fees constitute dual revenue streams for vehicle retailers. Inventory carrying costs rise with semiconductor supply bottlenecks extending delivery timelines.
Individual borrowers command the largest origination volume, though Fleet is expanding most quickly as commercial electrification programs scale.
Payment Method:
Application-driven infrastructure requirements separate legacy cash handling from automated digital collection systems with embedded fraud detection.
- Cash Payment:Lump-sum settlement persists in emerging markets with underdeveloped credit infrastructure and among high-net-worth individuals seeking simplicity. Indian non-banking finance companies accommodate this preference through branch networks.
- Installments:Fixed periodic payments remain the standard structure across all major markets, with 36-to-72-month terms dominating collateralized auto lending. Early repayment penalties vary by jurisdiction.
- Direct Debit:Automated bank account withdrawal reduces servicing costs and default rates through frictionless collection. European markets mandate SEPA compliance for cross-border lease portfolios.
- Credit Card:Down payment and ancillary product financing through card networks concentrates in United States subprime segments where revolving credit access supplements term loan structures.
Installments retain the foundational position, while Direct Debit is climbing the fastest as real-time payment rails proliferate.
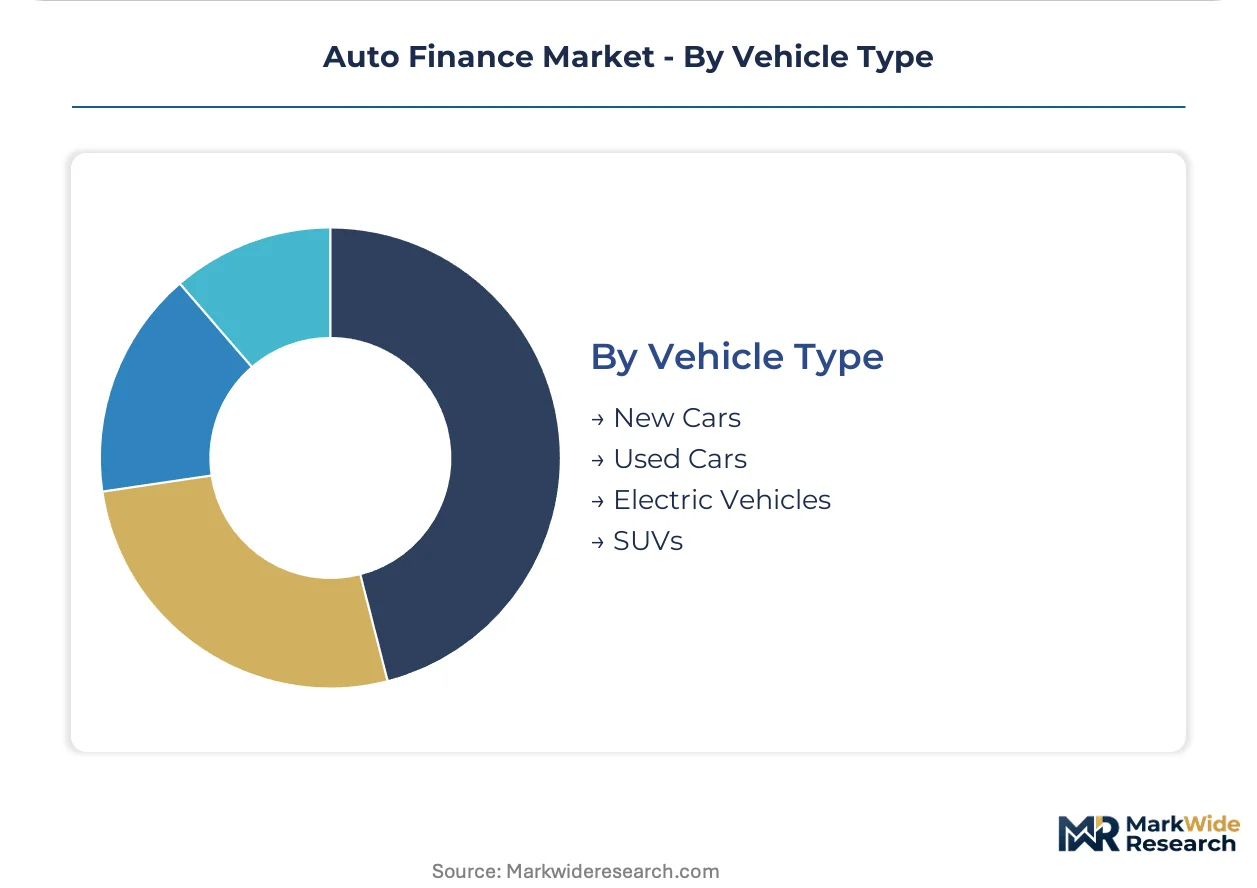
Vehicle Type:
Margin profiles diverge sharply between mature internal combustion collateral and battery electric vehicles with unproven residual value curves.
- New Cars:Captive finance arms anchor origination through point-of-sale pre-approval and manufacturer subvention programs. Toyota Financial Services and Ally Financial compete on digital platform integration.
- Used Cars:Higher interest rate spreads compensate for information asymmetry around vehicle condition and prior maintenance. Independent dealers rely on third-party vehicle history aggregation.
- Electric Vehicles:Battery depreciation uncertainty forces lenders to rebuild risk models around divergent collateral curves. German federal purchase incentives create preferential rate environments for battery electric financing.
- SUVs:Segment concentration in United States and Chinese markets supports residual value stability through liquid secondary channels. Leasing penetration exceeds sedan categories due to stronger value retention.
New Cars dominate origination value, while Electric Vehicles is gaining share fastest as subsidy alignment and fleet electrification reshape lender portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Auto finance origination concentrates in economies with mature automotive manufacturing bases and developed consumer credit infrastructure. Lender portfolios in these markets face divergent pressures from electrification mandates, central bank rate trajectories, and evolving residual value models for battery electric collateral.
United States
Captive finance arms dominate point-of-sale origination through pre-approval integration with dealership networks. The Consumer Financial Protection Bureau enforces standardized lending disclosure protocols that elevate compliance costs for regional banks and credit unions. Detroit's automotive cluster anchors floorplan financing volume, though semiconductor supply bottlenecks extend vehicle delivery timelines and delay loan activation.
Germany
Federal purchase incentives and tax-advantaged leasing structures create preferential rate environments for battery electric vehicle financing. The European Banking Authority mandates granular loan-level disclosure and stress testing for vehicle asset-backed securities. Munich and Stuttgart host the densest concentration of OEM-affiliated lenders managing electrified fleet portfolios.
China
Domestic brands accelerate captive finance penetration through digital platforms tied to direct-to-consumer sales channels. The central bank regulates non-banking finance company exposure limits while promoting green credit allocation for new energy vehicles. Shanghai and Guangzhou anchor the largest volumes of electric vehicle lease origination.
India
The Reserve Bank of India's relaxed caps on non-banking finance companies unlock fleet operator credit access for commercial vehicle procurement. Rural branch networks accommodate cash payment preferences alongside installment structures. Pune and Chennai concentrate manufacturing-linked financing activity for domestic and export-oriented production.
United Kingdom
Mobility-as-a-service providers fragment fleet procurement toward shorter operating lease terms managed through digital platforms. The Financial Conduct Authority scrutinizes discretionary commission arrangements in motor finance. Birmingham and Manchester emerge as regional hubs for mid-size fleet operator credit aggregation.
Auto Finance Market Vendor Landscape
Captive finance subsidiaries and independent consumer banks split the market between manufacturer-tied distribution and direct lending channels. Consolidation characterizes the upper tier where automotive OEMs control origination through point-of-sale integration, while fragmentation persists among regional banks competing for near-prime segments. Two archetypes dominate: balance-sheet lenders optimizing net interest margin through deposit-funded structures, and capital-markets-dependent originators maximizing fee income from securitization. Competitive moves concentrate on embedded telematics integration and subscription-to-ownership pipeline development.
Within the captive finance tier, Toyota Financial Services and Volkswagen Financial Services exemplify manufacturer-anchored origination models. Ally Financial occupies a position bridging captive and independent archetypes through its digital platform infrastructure. Capital One represents the data-driven independent lender archetype targeting risk-based pricing differentiation.
| Leading Market Players |
|---|
| Ally Financial |
| Capital One |
| Bank of America |
| Ford Motor Credit Company |
| GM Financial |
| Toyota Financial Services |
| Volkswagen Financial Services |
| Daimler Financial Services |
| Wells Fargo |
| Others |
Supply Flow & Price Mechanics
Taipei anchors semiconductor fabrication capacity that feeds vehicle telematics modules and digital cockpit systems, with foundry allocation constraints compressing margins for tier-two auto finance providers dependent on embedded hardware subsidies. This supply chokepoint ripples through residual value calculations as delayed vehicle deliveries defer loan activation and interest accrual across captive finance portfolios.
Pricing Analysis
The US Consumer Financial Protection Bureau dictates the pricing tier structure through standardized disclosure mandates that elevate compliance overhead for smaller regional banks. Three-tier pricing structure across prime, near-prime, and subprime levels reflects FICO-based risk stratification and telematics-enabled income verification tools. Cost compression in the subprime segment is intensifying because fintech-enabled competitors compress approval timelines and erode traditional spread advantages. Fleet operators exhibit the least price sensitivity due to volume commitments and embedded data sharing, while individual retail borrowers demonstrate acute rate responsiveness to basis-point shifts.
Supply Chain Analysis
Foundry concentration in Taiwan and South Korea controls chip fabrication for vehicle control units, battery management systems, and infotainment platforms. Raw material dependencies span lithium carbonate from Chile and Australia, cobalt from the Democratic Republic of Congo, and nickel from Indonesia. Single-source vulnerability in advanced node semiconductors threatens production schedules for electric vehicle platforms with software-defined architectures. Distribution runs through OEM captive finance arms at point-of-sale, with indirect bank channels and digital direct-to-consumer platforms fragmenting downstream access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Auto finance functions as a service-attach opportunity where residual value management and telematics-enabled underwriting layers expand faster than hardware-centric origination. Subscription-to-ownership conversion programs and usage-based insurance bundling now outpace traditional term loan growth.
For Market Incumbents: Harden captive finance integration against fintech-enabled near-prime disruptors by embedding real-time income verification APIs and dynamic behavioral scoring. Deepen backward integration into telematics data infrastructure to preserve residual value forecasting accuracy as battery electric vehicle depreciation curves diverge from internal combustion collateral. Consolidate floorplan servicing relationships with dealership networks facing semiconductor-driven inventory carrying cost pressures.
For New Entrants and Emerging Players: Pursue white-space concentration in mid-size fleet operating leases across the United Kingdom and Netherlands, where mobility-as-a-service intermediaries fragment procurement toward shorter terms with limited incumbent coverage. Target near-prime individual borrowers underserved by traditional FICO-dependent underwriting through bank account aggregation and employment data API integration. Lead with digital-first subscription-to-ownership conversion platforms that generate term financing pipeline volume.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors balance-sheet lenders with deposit-funded structures and embedded telematics capabilities over capital-markets-dependent originators exposed to ABS spread volatility. Long-term viability hinges on predictive modeling infrastructure for electric vehicle residual values combining automotive engineering and quantitative finance expertise. Monitor central bank rate trajectory inflections and lithium-ion battery second-life valuation clarity as portfolio repricing signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Telematics Integration | Enables usage-based underwriting and dynamic residual adjustments throughout loan terms. |
| Subscription-to-Ownership Pipeline | Converts flexible short-term access programs into traditional term financing origination volume. |
| Captive Finance Platform Expansion | Compresses credit decision timelines from days to minutes at point-of-sale through OEM data integration. |
| Battery Electric Vehicle Risk Model Development | Rebuilds collateral valuation frameworks around divergent depreciation curves for electrified portfolios. |
| Cross-Border Smart Contract Infrastructure | Automates collateral registration and payment settlement across international lease portfolios. |
Methodological Framework
Initial hypotheses were tested against primary input from captive finance executives, dealership operations managers, fleet procurement directors, and regulatory compliance officers and refined through secondary validation. Sources included SEC 10-K filings from listed auto finance providers, vehicle registration databases, central bank exposure limit disclosures, and asset-backed securities prospectuses. Bottom-up origination volume modeling and top-down macroeconomic scenario analysis were triangulated to establish market sizing boundaries.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning finance option, customer type, payment method, and vehicle propulsion architecture. CAGRs were derived from regression analysis against vehicle sales forecasts and central bank rate trajectory assumptions. Electric vehicle subsidy alignment and semiconductor supply recovery timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by fintech-enabled near-prime lenders or battery electric vehicle residual value shocks would shift outcomes beyond modeled ranges. Quarterly review of central bank policy trajectories, lithium-ion battery replacement cost indices, and telematics penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Commercial Loan Software Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Alternative Lending Platform Market
Loans and Leasing
Finance Lease Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Renting and Leasing Test and Measurement Equipment Market
Loans and Leasing
Alternative Lending Market
Loans and Leasing
Global Mortgage/Loan Brokers Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Unsecured Business Loans Market
Loans and Leasing
Europe Crowd Lending and Crowd Investing Market
Loans and Leasing
Loan Servicing Software Market
Loans and Leasing
Car Leasing Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market