
 Singapore Remittance Market | 2026-2036
Singapore Remittance Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Remittance Market Insights
Market Context with Strategic Players
Migrant worker remittances to South and Southeast Asian corridors is shifting toward real-time digital rails. Instarem leverages API-first infrastructure to capture business-to-business cross-border volume. Wise sustains consumer-grade pricing transparency across its Singapore-originated corridors. DBS Bank anchors institutional trust through its digibank remittance stack for retail and SME segments.
Technical Definition and Structural Segments
Remittance denotes cross-border fund transfers initiated by individuals or entities, typically cleared through correspondent banking networks, card schemes, or licensed e-money issuers, with settlement latency ranging from minutes to three business days depending on rail selection. Its commercial purpose centers on labor-exporting economies where diaspora earnings constitute household income and foreign exchange reserves. Bank transfers retain the largest value share among service types, though mobile wallets represent the fastest-expanding segment as telco-fintech partnerships deepen last-mile access in recipient markets. Expat and migrant worker categories dominate customer type segmentation, while businesses generate higher per-transaction values with lower frequency.
Regulatory Framework and Outlook
The Monetary Authority of Singapore enforces the Payment Services Act, requiring remittance licensees to maintain segregated customer funds and comply with anti-money laundering protocols. The Association of Banks in Singapore coordinates industry standards for correspondent banking due diligence. Stakeholders must monitor how Singapore's central bank calibrates digital payment token regulations, as stablecoin remittance pilots could redraw competitive boundaries between licensed banks and fintech operators.
Market Dynamics
The Monetary Authority of Singapore's Payment Services Act is compressing licensing timelines for digital remittance operators while mandating stricter segregation of customer funds, forcing incumbent banks and fintech challengers to converge on real-time settlement infrastructure.
Growth Catalysts
- Mobile wallet penetration:Smartphone adoption across Indonesia and Malaysia is expanding last-mile access for unbanked recipients, with telco-fintech partnerships reducing cash-out friction in rural corridors.
- Payment Services Act licensing:The Monetary Authority of Singapore's streamlined digital payment token framework is accelerating stablecoin pilot approvals for licensed remittance operators.
- Migrant worker concentration:Bangladeshi, Indian, and Filipino labor flows through Singapore sustain outbound transaction volumes with high repeat-frequency characteristics.
Market Restraints
- Correspondent banking concentration:Reliance on a limited pool of clearing banks for USD-SGD corridors creates settlement latency risks during liquidity stress events.
- FX margin compression:Narrowing spreads on INR, BDT, and PHP currency pairs are squeezing operator revenue per transaction without proportional volume offsets.
- AML compliance burden:Enhanced due diligence requirements under the Payment Services Act are extending customer onboarding timelines and elevating operational overhead for smaller licensees.
Strategic Opportunities
- Stablecoin settlement rails:USD-pegged digital currency pilots are integrating with licensed e-money issuer networks to compress cross-border settlement from T+2 to near-real-time.
- SME B2B corridors:Underpenetrated business remittance segments linking Singapore to Vietnamese and Thai manufacturing hubs offer higher per-transaction value capture.
- API infrastructure monetization:White-label remittance-as-a-service platforms are enabling non-financial platforms to embed cross-border payment capabilities without direct licensing.
Industry Challenges
- Legacy core banking integration:Incumbent financial institutions face middleware complexity when connecting real-time payment APIs to decades-old batch-processing systems.
- Talent scarcity in compliance engineering:Shortage of professionals versed in both Payment Services Act technical requirements and machine-learning-based transaction monitoring is constraining scaling capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Remittance Market |
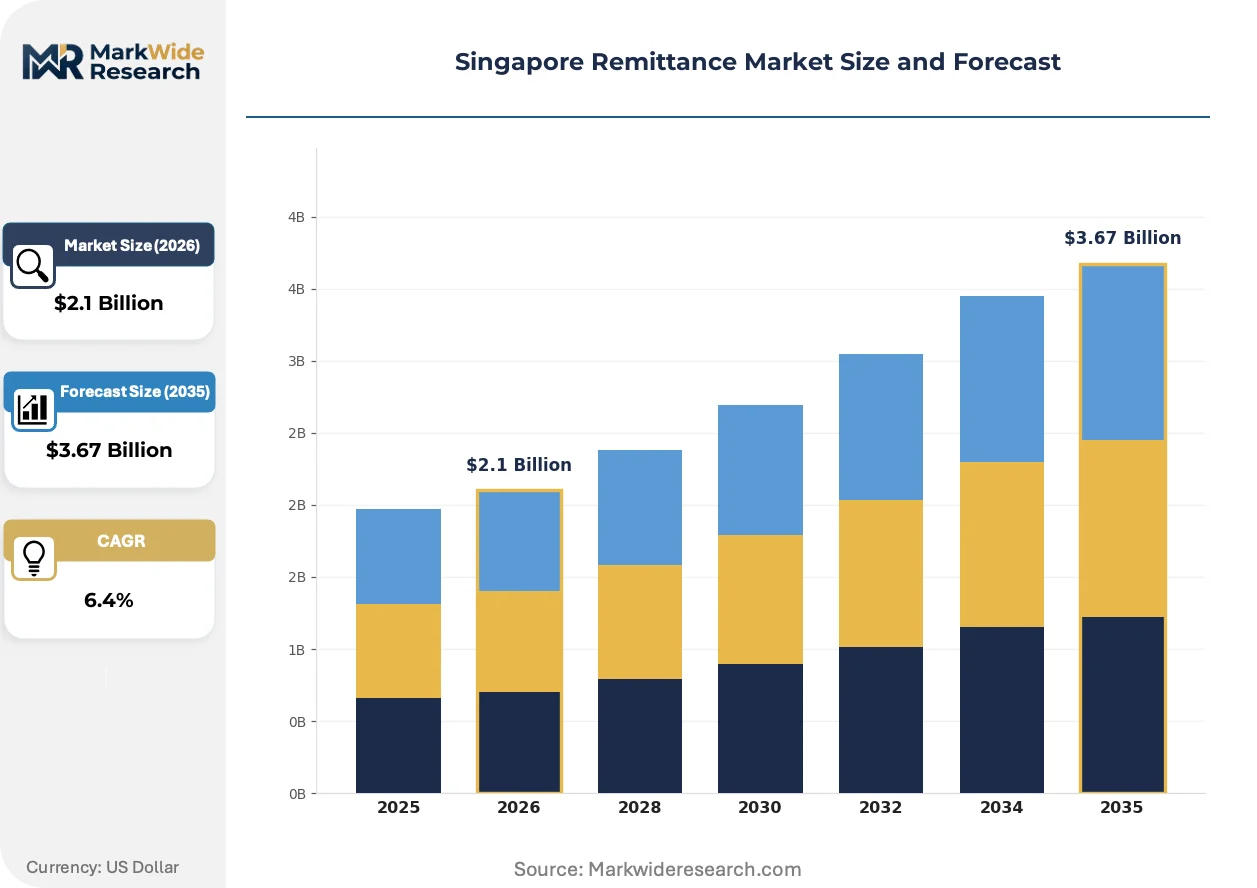
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Bank Transfers, Mobile Wallets, Cash Pick-Up, Online Transfers Customer Type: Expats, Migrant Workers, International Students, Businesses Transfer Method: Direct Deposit, Cash Transfer, Digital Payment, Prepaid Cards Currency Type: SGD, USD, AUD, EUR |
| Companies Covered | Instarem, DBS Bank, Nium, SingX, 2C2P, Wise, Airwallex, Thunes, Xendit, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Remittance Market Trends and Innovations
Real-time payment infrastructure is displacing batch-based correspondent banking as the dominant settlement modality, with API-first architectures enabling embedded finance models that dissolve traditional channel boundaries between originators and recipients.
Blockchain-based settlement rails are integrating with licensed e-money issuer networks to enable programmable compliance and atomic settlement for cross-border corridors. DBS Bank and select fintech operators are piloting these integrations for Philippines and Indonesia corridors, compressing settlement windows from hours to seconds while embedding regulatory reporting directly into transaction logic. This convergence is forcing traditional wire-transfer operators to reprice services or cede volume.
The Monetary Authority of Singapore's evolving stablecoin regulatory framework is mandating reserve attestation and redemption standards for digital payment token issuers. Licensed remittance operators must now demonstrate one-to-one asset backing and daily liquidity reporting, elevating compliance infrastructure costs but creating regulatory clarity that attracts institutional capital. Smaller fintech challengers face capital barriers to entry under these requirements.
Recipient-side behavior is fragmenting away from cash pickup toward direct-to-wallet crediting, with Indonesian and Malaysian mobile wallet users now expecting instant notification and utility bill payment integration. Remittance senders in Singapore are selecting operators based on recipient convenience features rather than headline FX rates alone. This preference shift is most pronounced among Filipino domestic helpers transferring funds to family members in Metro Manila and provincial centers.
Singapore Remittance Market Segmentation
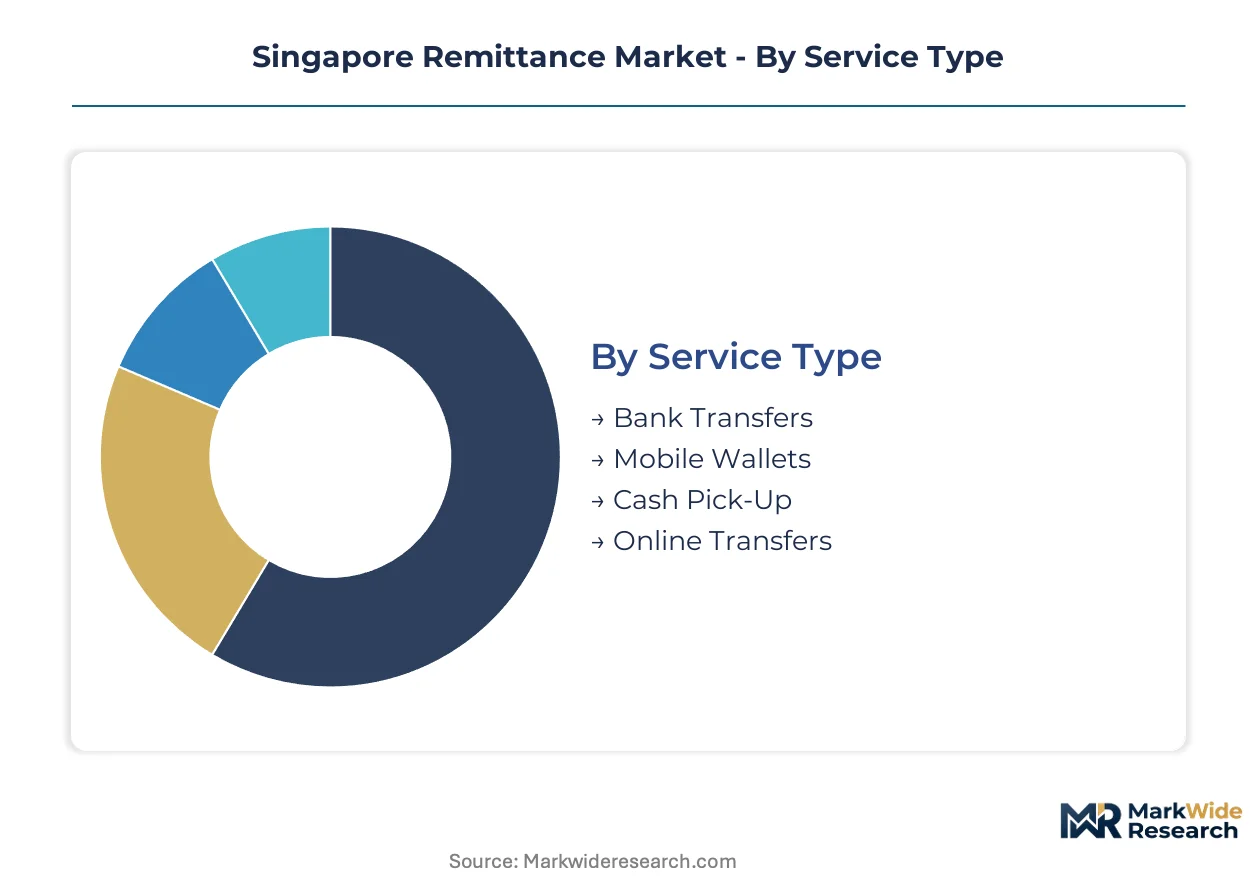
Remittance operators in Singapore calibrate product architecture across four intersecting dimensions. Service type determines settlement rail economics, while customer type shapes compliance intensity and repeat-frequency patterns.
Service Type:
Supply concentration among licensed e-money issuers and correspondent banking networks dictates which rails capture transaction volume.
- Bank Transfers:Traditional correspondent banking infrastructure clears high-value transactions through SWIFT messaging with T+1 to T+3 settlement windows. DBS Bank and OCBC anchor this segment for Bangladeshi and Indian corridor flows where recipient trust in formal banking persists.
- Mobile Wallets:Real-time crediting to GrabPay, GoPay, and Touch 'n Go eWallets compresses settlement to under 60 seconds. Telco-fintech partnerships in Indonesia and Malaysia are displacing cash pickup for unbanked recipients in rural provinces.
- Cash Pick-Up:Agent networks remain essential for Filipino domestic helpers sending to provincial centers with limited digital infrastructure. Cebuana Lhuillier and M Lhuillier agent locations in the Philippines sustain corridor-specific demand.
- Online Transfers:Web-platform-initiated transactions without branch visitation appeal to time-constrained expats in Singapore's central business district. API integrations with recipient-side mobile wallets enable seamless last-mile delivery.
Bank transfers absorb the bulk of installed capacity; mobile wallets are expanding most quickly.
Customer Type:
Cost tier differentiation separates high-frequency low-value senders from low-frequency high-value corporate users.
- Migrant Workers:Bangladeshi construction workers and Filipino domestic helpers generate repeat monthly transactions averaging SGD 300-800. These senders prioritize low FX margins and recipient convenience over settlement speed.
- Expats:Professionals from India, Australia, and Europe transfer larger sums quarterly for property investments or family support. This segment tolerates higher fees in exchange for regulatory certainty and transparent pricing.
- International Students:Tuition and living expense remittances from Singapore-based students exhibit seasonal spikes aligned with academic calendars. Parents in India and China constitute the originating party in most flows.
- Businesses:SME importers and service exporters generate the highest per-transaction values with lowest frequency. Vietnamese and Thai manufacturing payment corridors remain underpenetrated relative to consumer remittance density.
Migrant workers absorb the bulk of installed capacity; businesses are climbing the fastest as B2B corridors digitize.
Transfer Method:
Application context determines whether senders prioritize speed, cost, or recipient flexibility.
- Direct Deposit:Funds credit directly to recipient bank accounts in India, Bangladesh, and the Philippines. This method dominates salary remittance flows where recipients maintain formal banking relationships.
- Cash Transfer:Physical cash pickup at agent locations persists for corridors with low banking penetration. Rural Indonesian and Philippine provinces retain this requirement despite mobile wallet expansion.
- Digital Payment:Wallet-to-wallet and account-to-wallet transfers leverage Singapore's PayNow integration with regional real-time payment systems. Thailand's PromptPay and Malaysia's DuitNow linkages are deepening.
- Prepaid Cards:Remittance-loaded cards for recipient spending at POS terminals and ATMs. This method addresses unbanked recipients without smartphone access in specific Philippine and Indonesian sub-regions.
Direct deposit absorbs the bulk of installed capacity; digital payment is gaining share fastest through API-enabled corridor expansion.
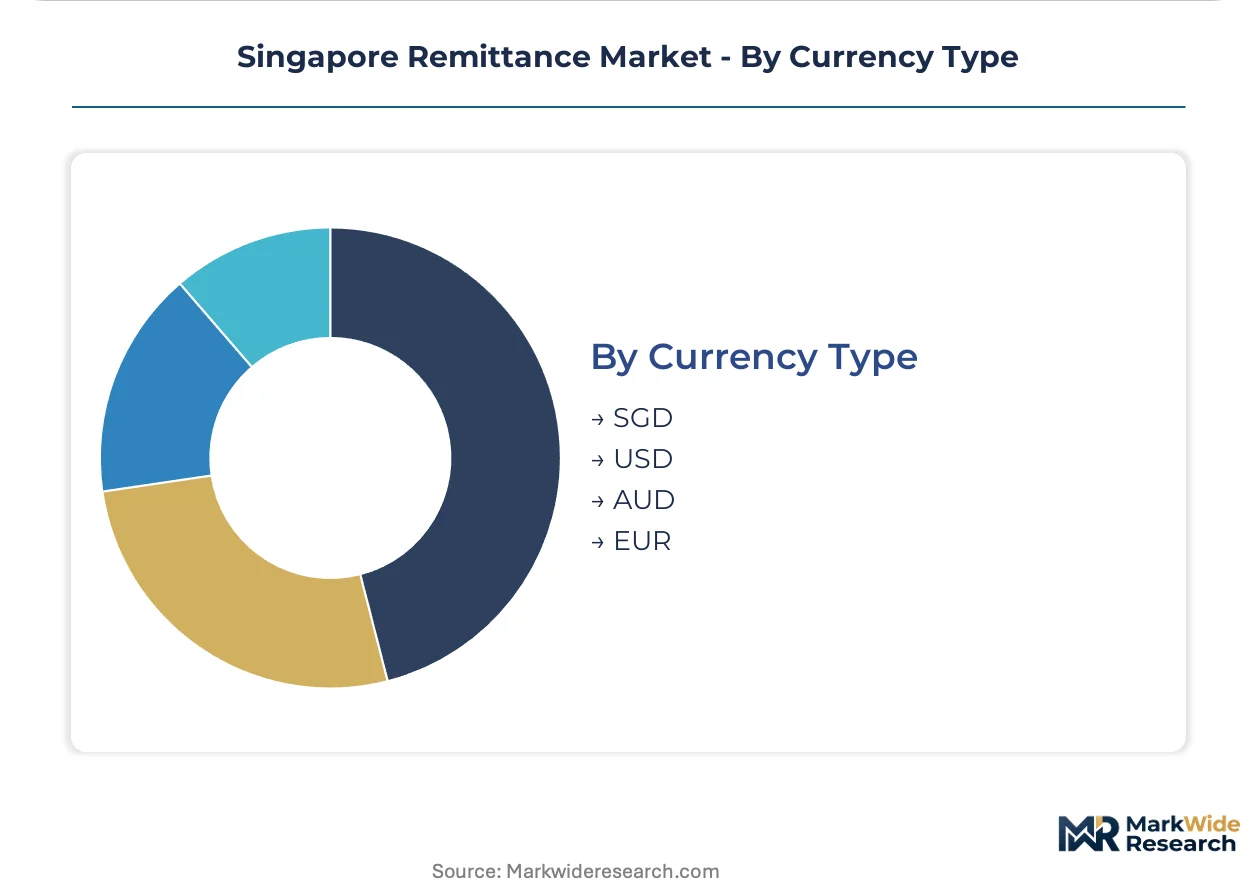
Currency Type:
Volume concentration in SGD-denominated origination shapes operator treasury management and hedging requirements.
- SGD:Singapore dollar origination dominates outbound flows given the country's status as the sending jurisdiction. Operators maintain SGD liquidity buffers at the Monetary Authority of Singapore's regulated thresholds.
- USD:Dollar-denominated remittances appeal to recipients in dollarized economies and those seeking currency stability. Correspondent banking concentration in USD-SGD pairs creates settlement latency risks during stress events.
- AUD:Australian dollar flows concentrate among expat professionals with property or family obligations in Australia. Limited corridor competition relative to USD and SGD elevates FX margin capture.
- EUR:Euro remittances serve European expats and businesses with continental payment obligations. SEPA integration enables next-day settlement for compliant transactions.
SGD absorbs the bulk of installed capacity; USD is climbing the fastest as stablecoin pilots introduce programmable dollar settlement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jurong Innovation District and one-north tech corridor concentrate Singapore's fintech licensing activity, with the Monetary Authority of Singapore's regulatory sandbox accelerating digital payment token approvals for corridor operators targeting Southeast Asian recipient markets.
Bangladesh
Migrant construction workers in Singapore sustain high-frequency remittance flows averaging SGD 400 monthly to Dhaka and Chittagong divisions. Bangladesh Bank's liberalized mobile financial services regulations enable bKash and Nagad wallet interoperability with Singapore-licensed operators. Sylhet Division receives disproportionate volume given historic labor migration patterns from that region.
India
Indian expatriate professionals and domestic workers generate Singapore's largest remittance corridor by absolute value, with Tamil Nadu, Kerala, and Maharashtra as primary destination states. Reserve Bank of India's liberalized remittance scheme under the Foreign Exchange Management Act permits inward flows through authorized dealer banks and payment system operators. Chennai and Mumbai financial centers anchor recipient-side banking infrastructure for these flows.
Indonesia
Domestic helpers from Java and Sumatra transfer funds to family members in Jakarta, Surabaya, and Medan metropolitan zones. Bank Indonesia's BI-FAST real-time payment system integration with Singapore's PayNow compresses settlement latency to under 60 seconds. Batam and Bintan special economic zones benefit from proximity-driven corridor density with reduced FX friction.
Philippines
Filipino domestic helpers constitute Singapore's most concentrated migrant worker segment, with remittances directed to Metro Manila, Cebu, and Davao urban centers. Bangko Sentral ng Pilipinas oversees the National Retail Payment System enabling InstaPay and PESONet interoperability with Singapore-originated transfers. Provincial Luzon and Visayas regions retain cash pickup dependency despite accelerating mobile wallet adoption.
Malaysia
Cross-border workers and business travelers sustain high-velocity SGD-MYR corridors linking Singapore to Johor Bahru, Kuala Lumpur, and Penang. Bank Negara Malaysia's DuitNow real-time payment system links directly with Singapore's PayNow infrastructure. Iskandar Malaysia special economic zone generates corridor-specific volume from daily commuter flows and SME trade settlements.
Singapore Remittance Market Competitive Landscape
Top-tier vendors anchor institutional trust through banking licenses, while API-first fintech challengers capture volume through embedded finance partnerships and corridor-specific pricing transparency. The market structure exhibits tiered consolidation: three full-service banks with Payment Services Act major payment institution licenses coexist with eight to twelve specialized digital remittance operators. Two dominant strategic archetypes have emerged—bank-affiliated platforms leveraging existing compliance infrastructure, and pure-play fintechs monetizing white-label API infrastructure. Competitive moves concentrate on stablecoin settlement pilots and real-time payment system integrations rather than traditional branch expansion.
Among Singapore-headquartered operators, Instarem and Nium occupy positions within the API infrastructure archetype, exemplifying the shift toward embedded cross-border payment capabilities. DBS Bank anchors the licensed banking tier, representing institutional trust frameworks that persist among high-value senders and SME segments. Wise sits within the consumer-grade transparency archetype, demonstrating how corridor-specific pricing clarity captures repeat-frequency migrant worker volume.
| Leading Market Players |
|---|
| Instarem |
| DBS Bank |
| Nium |
| SingX |
| 2C2P |
| Wise |
| Airwallex |
| Thunes |
| Xendit |
| Others |
Pricing and Supply Chain Analysis
SGD liquidity buffers maintained at Monetary Authority of Singapore thresholds cascade through correspondent banking networks into three-tier pricing structures across premium, standard, and economy service levels. Operators calibrate FX margins against real-time payment system integration costs, with settlement rail selection determining final price tiers for migrant worker and expat segments.
Pricing Analysis
Short lead-time premiums for real-time mobile wallet crediting compress operator margins by 15-30 basis points against standard bank transfer economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by settlement speed and recipient convenience features. Pricing pressure stems from narrowing spreads on INR, BDT, and PHP corridors as fintech challengers force repricing. Migrant workers exhibit highest price sensitivity, while SME businesses tolerate premium tiers for regulatory certainty.
Supply Chain Analysis
Reverse-logistics flows for failed remittance returns and wallet reconciliation create operational friction in correspondent banking networks. Supply concentration rests in Singapore, Malaysia, and Indonesia for last-mile digital payment infrastructure. Dependencies include SWIFT messaging licenses, e-money issuer partnerships, and real-time payment API integrations. Single-source vulnerability in USD-SGD correspondent banking creates settlement latency risks during liquidity stress. Distribution runs through licensed payment institutions and API-embedded white-label platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
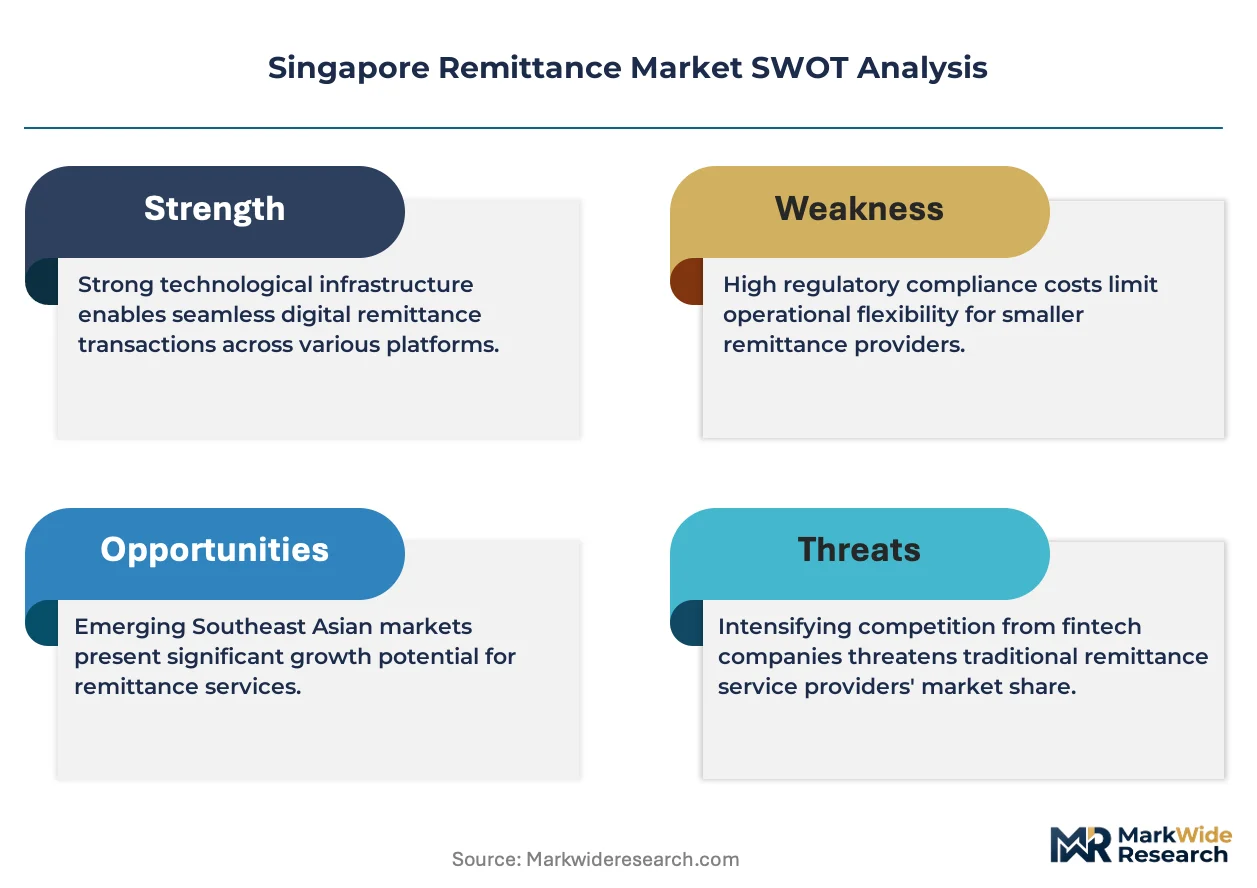
Consolidation pressure from Payment Services Act capital requirements is forcing smaller licensees toward acquisition or exit. Regulatory compliance infrastructure costs favor scaled operators with existing banking relationships.
For Market Incumbents: Deploy API infrastructure monetization to capture embedded finance revenue from non-financial platforms seeking cross-border payment capabilities. Secure exclusive partnerships with Indonesian and Malaysian mobile wallet operators to lock in corridor density. Threaten fintech challengers by integrating stablecoin settlement pilots ahead of regulatory clarity.
For New Entrants and Emerging Players: SME importers in Vietnamese and Thai manufacturing corridors represent the most penetrable white-space target, with underdigitized B2B payment flows and higher per-transaction values. White-label remittance-as-a-service platforms enable market entry without direct licensing burden. Go-to-market through accounting software and trade finance platforms already embedded in target buyer workflows.
For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first fintech operators with existing Payment Services Act licenses and proven corridor economics in Bangladesh-India-Philippines flows. Long-term viability hinges on stablecoin regulatory clarity and real-time payment system interoperability across Southeast Asia. Monitor Monetary Authority of Singapore digital payment token framework calibrations as inflection indicator for institutional capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Stablecoin Settlement Rail Integration | Compresses cross-border settlement from T+2 to near-real-time through licensed e-money issuer networks. |
| Real-Time Payment System Partnership | Links Singapore's PayNow with Indonesia's BI-FAST and Malaysia's DuitNow for sub-60-second crediting. |
| API Infrastructure Monetization | Enables non-financial platforms to embed remittance capabilities without direct licensing overhead. |
| Corridor-Specific Mobile Wallet Integration | Deepens last-mile access for unbanked recipients in rural Indonesian and Philippine provinces. |
| Compliance Infrastructure Scaling | Addresses talent scarcity in Payment Services Act engineering and machine-learning transaction monitoring. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with remittance operations executives, compliance officers at licensed payment institutions, migrant worker advocacy representatives, and fintech product managers combined with Monetary Authority of Singapore licensing disclosures, Association of Banks in Singapore industry standards, and central bank payment system reports. Bottom-up transaction volume modeling and top-down macroeconomic remittance flow estimates provided triangulation validation.
Data-stream reconciliation across multiple sources informed the analytical framework over the projection horizon. Segmentation dimensions modeled include service type, customer type, transfer method, and currency type alongside corridor-specific regulatory framework clusters. CAGRs were derived through trend extrapolation of digital payment adoption curves and real-time payment system penetration rates. Forecast inputs incorporated migrant worker population projections and mobile wallet interoperability expansion timelines.
Revisions become necessary when regulatory framework shifts, stablecoin approval delays, or correspondent banking liquidity stress events materialize. Forecasts reflect assumptions about Payment Services Act enforcement consistency and bilateral payment system agreements. Practitioners should monitor Monetary Authority of Singapore digital payment token calibrations and Bangladesh Bank mobile financial services liberalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
France Mobile Payment Market
Payments
South Korea Digital Payments Market
Payments
Canada POS Terminal Market
Payments
Electronic Cash Register Market
Payments
China Virtual Cards Market
Payments
Forex Cards Market
Payments
Japan Mobile Payments Market
Payments
South Korea Real Time Payments Market
Payments
North America Mobile Payments Market
Payments
Digital Money Transfer Market
Payments
Mobile Point of Sale (POS) Market
Payments
Asia Pacific POS Terminal Market
Payments
Saudi Arabia Gift Card and Incentive Card Market
Payments
Italy Payments Market
Payments
Digital Debit Market
Payments
Global Accounts Payable (AP) Automation Software Market