
 Financial Forecasting Software Market | 2026-2036
Financial Forecasting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Forecasting Software Market Insights
The capital-intensity divergence between legacy on-premises incumbents and cloud-native challengers is unwinding as infrastructure costs equalize and subscription economics dominate. Workday Adaptive Planning leverages its enterprise HCM installed base to cross-sell integrated planning suites. Anaplan specializes in hyperscale scenario modeling for multinational corporations with complex entity structures. Datarails anchors its position among mid-market accounting firms through native Excel integration that reduces change-management friction.
Financial forecasting software comprises algorithmic platforms that synthesize historical ledger data, macroeconomic indicators, and operational metrics to project future cash positions, revenue trajectories, and capital requirements. These systems employ time-series analysis, Monte Carlo simulation, and machine learning pattern recognition to transform static spreadsheets into dynamic, multi-scenario planning environments. Cloud-Based deployment leads current uptake as finance teams prioritize remote accessibility and automatic version control over on-premises data sovereignty. Scenario Modeling within the Use Case dimension represents the fastest-expanding functional area, driven by board-level demand for stress-testing against supply chain disruptions and interest rate volatility. The Solution Offering segment shows margin pools concentrating in Risk Management modules, where regulatory pressure elevates willingness-to-pay for predictive analytics.
The SEC's disclosure rules on climate-related financial risks are compelling US corporations to adopt forecasting tools with embedded ESG scenario capabilities. The EU's CSRD and Digital Operational Resilience Act impose granular audit-trail requirements that favor platforms with native compliance documentation. ISO 27001 certification has become a non-negotiable procurement filter for banks and investment firms evaluating vendor shortlists. Stakeholders must monitor how generative AI integration reshapes competitive differentiation between established platforms and emerging entrants.
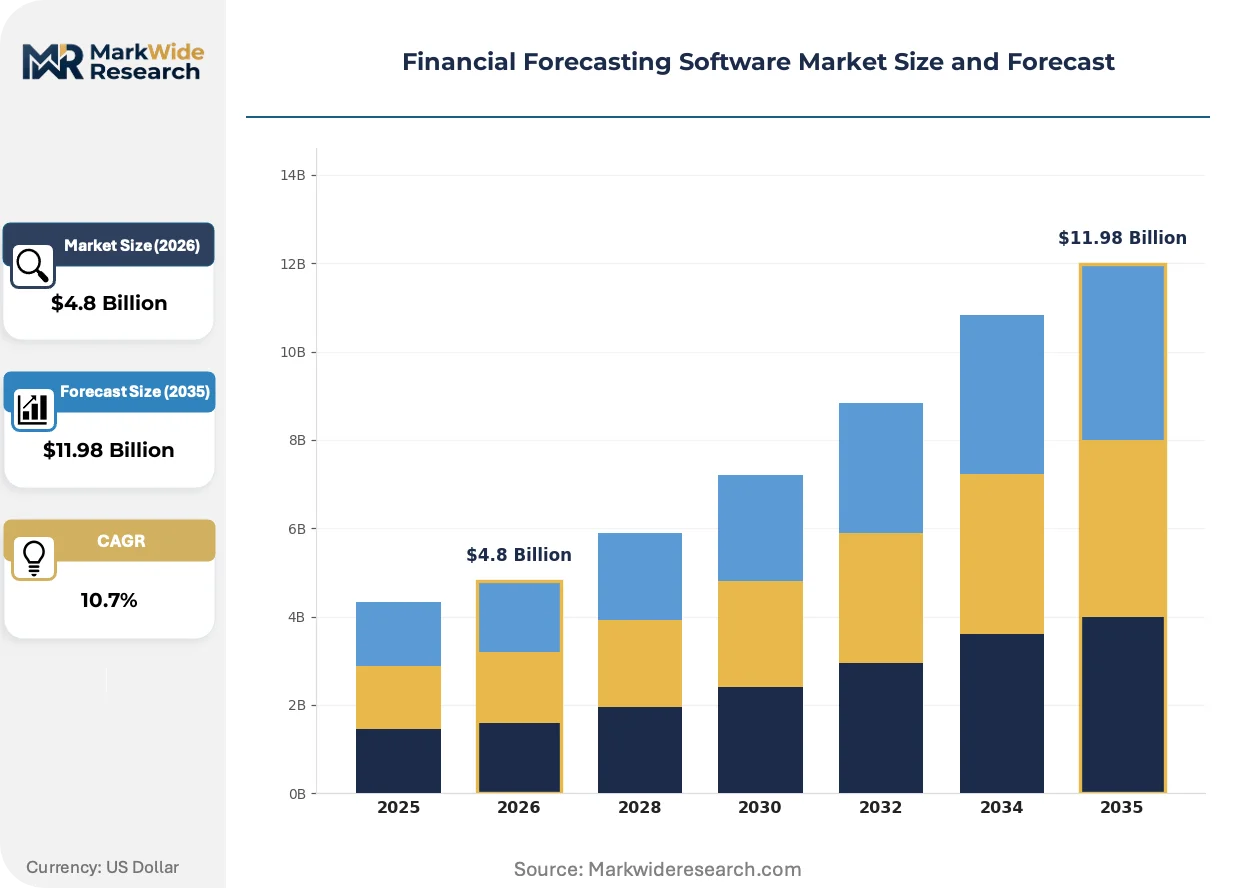
Market Dynamics
The convergence of generative AI architectures with legacy financial planning systems is compressing implementation cycles and reconfiguring vendor competitive moats around data integration depth rather than interface design.
Growth Catalysts
- SEC Climate Disclosure Mandates:US corporations must embed scenario modeling for physical and transition climate risks into forward-looking financial statements, forcing procurement of ESG-capable forecasting platforms.
- Cloud-Native Infrastructure Maturation:Mid-market accounting firms now deploy browser-based planning environments without dedicated IT support, collapsing barriers that previously favored on-premises incumbents.
- EU Digital Operational Resilience Act:Financial entities under EU jurisdiction must maintain auditable forecasting workflows with granular change-tracking, accelerating replacement of spreadsheet-dependent processes.
Market Restraints
- Data Sovereignty Fragmentation:Divergent cross-border data localization requirements between the US CLOUD Act and EU GDPR create architectural complexity for multinational deployment.
- Specialized Talent Scarcity:Shortage of professionals combining actuarial science with machine learning engineering constrains enterprise adoption of advanced predictive modules.
- Legacy System Entrenchment:Deep integration between existing ERP installations and customized spreadsheet workflows generates switching costs that delay platform migration.
Strategic Opportunities
- Embedded Finance Convergence:Integration of forecasting APIs directly into banking and payment platforms enables real-time cash flow projection for small businesses without standalone software procurement.
- India's Digital Public Infrastructure:Account Aggregator framework and GST invoice data streams create foundation for automated financial modeling targeted at MSME lending markets.
- ISO 27001 Certification Arbitrage:Vendors achieving information security certification ahead of competitors capture procurement shortlists from regulated financial institutions where compliance documentation is mandatory.
Industry Challenges
- Model Explainability Requirements:Black-box machine learning predictions face rejection by audit committees and regulators demanding transparent algorithmic decision pathways.
- Multi-Entity Consolidation Complexity:Currency translation, intercompany elimination, and local GAAP reconciliation across dozens of operating units strain platform architecture and implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Forecasting Software Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.98 Billion |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, Web-Based Solution Offering: Budgeting & Forecasting, Financial Planning, Risk Management, Investment Analysis, Revenue Projection Use Case: Cash Flow Prediction, Expense Tracking, Scenario Modeling, Profit & Loss Analysis, Capital Allocation End User: Corporations, Investment Firms, Banks, Financial Advisors, Accounting Firms |
| Companies Covered | Planful, Workday Adaptive Planning, Anaplan, Cube, Prophix, Abacum, Mammoth Analytics, Vena, Datarails, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Forecasting Software Market Trends and Innovations
Generative AI is collapsing the traditional boundary between data preparation and insight generation, enabling finance teams to query forecast models through natural language rather than predefined dashboard configurations.
Agentic AI orchestration is miniaturizing the forecasting workflow by automating data ingestion from fragmented source systems, exception flagging, and variance commentary generation. Mid-market CFOs at SaaS-enabled professional services firms are deploying these capabilities without dedicated analytics teams. The technology is compressing the time between period-close and board-ready forecast refresh from weeks to hours.
CSRD implementation timelines across EU member states are mandating double materiality assessment integration within financial planning systems, requiring vendors to embed sustainability metric libraries and scenario stress-testing modules. Industrial manufacturers with complex supply chain exposures face the steepest compliance burden. German automotive suppliers are prioritizing platforms with pre-built Scope 3 emission forecasting templates to meet auditor documentation standards.
Subscription pricing for forecasting modules is displacing perpetual license structures as the dominant commercial model, with buyers demanding consumption-based tiers tied to entity count or scenario volume rather than user seats. Value-added resellers and accounting firm partnerships are capturing an expanding share of initial deployment and ongoing support revenue. This shift is most pronounced in the United States, where private equity-backed SaaS accounting firms bundle forecasting tools into client advisory retainers.
Financial Forecasting Software Market Segmentation
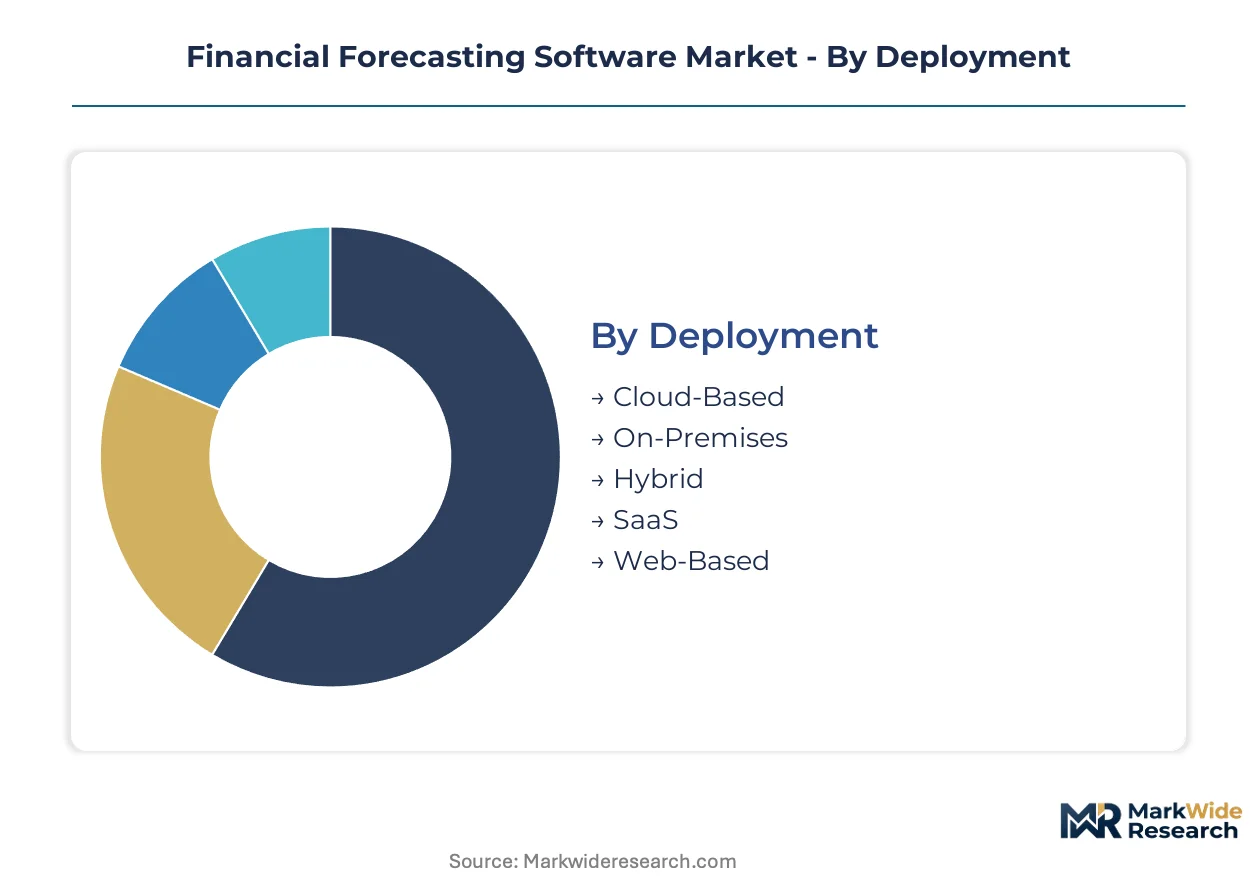
Segmentation in financial forecasting software reveals how procurement criteria diverge between regulated institutions and agile mid-market adopters. Deployment architecture and compliance documentation requirements reshape vendor selection more than feature breadth alone.
Deployment:
EU Digital Operational Resilience Act audit-trail mandates and US SEC climate disclosure rules are bifurcating procurement between compliant cloud-native platforms and legacy on-premises holdouts.
- Cloud-Based:Browser-native architectures enable automatic version control and remote accessibility for distributed finance teams. Mid-market accounting firms in the United States prioritize these platforms to serve cross-border clients without dedicated IT infrastructure.
- On-Premises:Installed software maintains data sovereignty within corporate firewalls, appealing to banks and investment firms with stringent internal security protocols. German automotive suppliers favor this model for Scope 3 emission forecasting templates requiring localized data residency.
- Hybrid:Split architectures balance sensitive ledger data on-premises with collaborative scenario modeling in cloud environments.
- SaaS:Subscription delivery collapses implementation cycles and shifts capital expenditure to operational budgets.
- Web-Based:Lightweight browser access reduces change-management friction for Excel-dependent finance teams.
Established volume favors On-Premises; emerging adoption favors Cloud-Based.
Solution Offering:
Margin concentration tracks regulatory pressure intensity, with Risk Management modules commanding premium pricing due to ISO 27001 certification requirements.
- Risk Management:Predictive analytics modules embed Monte Carlo simulation and stress-testing against interest rate volatility. EU financial entities under the Digital Operational Resilience Act procure these capabilities for auditable workflow documentation.
- Budgeting & Forecasting:Core planning environments synthesize historical ledger data with operational metrics for multi-scenario projections. US corporations facing SEC climate disclosure mandates prioritize ESG-capable variants.
- Financial Planning:Integrated suites connect workforce planning with capital requirements forecasting.
- Investment Analysis:Cash flow projection tools target private equity and venture capital due diligence workflows.
- Revenue Projection:Time-series analysis and machine learning pattern recognition transform CRM pipeline data into forward-looking statements.
Procurement concentration tilts toward Risk Management in regulated sectors; Budgeting & Forecasting dominates mid-market volume.
Use Case:
Functional priority reflects board-level demand for supply chain disruption preparedness and interest rate hedge positioning.
- Scenario Modeling:Hyperscale multi-entity simulation enables stress-testing against macroeconomic shocks and supply chain interruptions. Multinational corporations with complex entity structures in Germany and the United States deploy these capabilities for auditor documentation.
- Cash Flow Prediction:Algorithmic projection of future liquidity positions integrates accounts payable, receivable, and capital expenditure timelines. SaaS-enabled professional services firms compress period-close to board-ready refresh cycles using automated variance commentary.
- Expense Tracking:Real-time monitoring of operational spend against budgeted categories.
- Profit & Loss Analysis:Driver-based modeling links revenue and cost centers to consolidated performance statements.
- Capital Allocation:Project prioritization frameworks rank investment alternatives by risk-adjusted return thresholds.
Scenario Modeling is climbing the fastest as compliance mandates expand; Cash Flow Prediction retains the largest installed base.
End User:
Customer type determines implementation complexity tolerance and willingness-to-pay for embedded AI capabilities.
- Corporations:Enterprise finance teams at mid-market manufacturers deploy integrated planning suites connecting ERP ledger data with operational metrics. CSRD implementation timelines across EU member states are accelerating replacement of spreadsheet-dependent processes.
- Accounting Firms:SaaS-enabled practices bundle forecasting tools into client advisory retainers for small business cash flow projection. Native Excel integration reduces change-management friction and accelerates platform adoption.
- Banks:Regulated institutions demand ISO 27001 certification and granular audit trails for forecasting workflow documentation.
- Investment Firms:Portfolio companies require scenario modeling for due diligence and value creation planning.
- Financial Advisors:Wealth management practices leverage revenue projection for client retirement and estate planning.
Corporations drive platform R&D amortization; Accounting Firms represent the steepest expansion trajectory through embedded finance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-market accounting firms in the United States display the lowest price elasticity, absorbing premium subscription tiers for ESG-capable platforms, while Indian MSMEs remain highly sensitive to per-seat licensing costs despite rapid digital adoption.
United States
SaaS-enabled accounting firms serving cross-border clients drive concentrated procurement of cloud-native forecasting suites. SEC climate disclosure mandates compel corporations to embed scenario modeling for physical and transition risks into forward-looking statements. New York Metro and San Francisco Bay Area clusters host the densest concentrations of fintech-integrated advisory practices bundling forecasting tools into client retainers.
Germany
Automotive suppliers prioritize platforms with pre-built Scope 3 emission forecasting templates to meet auditor documentation standards. EU Digital Operational Resilience Act requirements accelerate replacement of spreadsheet-dependent processes with auditable workflow solutions. Bavaria's industrial manufacturing corridor exhibits the steepest compliance-driven procurement intensity for risk management modules.
United Kingdom
Private equity-backed professional services firms deploy agentic AI orchestration to compress period-close cycles without dedicated analytics teams. GDPR data localization requirements create architectural complexity for multinational deployment of cloud-based platforms. London's financial services cluster anchors demand for ISO 27001-certified forecasting tools among investment firms and wealth management practices.
India
MSME lending markets attract automated financial modeling platforms leveraging Account Aggregator framework and GST invoice data streams. The central bank's digital payment infrastructure expansion enables real-time cash flow projection for small businesses without standalone software procurement. Karnataka's Bangalore cluster and Maharashtra's Mumbai-Pune corridor concentrate fintech platform development and accounting firm digitization initiatives.
Japan
Enterprise manufacturers with complex entity structures deploy hyperscale scenario modeling for multi-currency consolidation and local GAAP reconciliation. METI industrial digitization programs subsidize cloud migration for mid-market CFOs hesitant to abandon legacy spreadsheet workflows. Tokyo-Osaka corridor headquarters of multinational corporations drive integrated planning suite adoption connecting workforce planning with capital requirements forecasting.
Financial Forecasting Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the financial forecasting software market. Enterprise incumbents with established HCM installed bases leverage cross-sell integration for integrated planning suites, while cloud-native challengers compete on implementation speed and Excel compatibility. Three archetypes dominate: hyperscale scenario modeling specialists, mid-market Excel-integrated platforms, and compliance-focused risk management module providers. Strategic moves concentrate on generative AI feature integration and accounting firm partnership networks to capture advisory retainer bundling opportunities.
Within the cloud-native tier, Datarails anchors mid-market positioning through native Excel integration that reduces change-management friction. Workday Adaptive Planning exemplifies the enterprise cross-sell archetype, leveraging installed base relationships to displace standalone forecasting vendors. Anaplan occupies the hyperscale specialization position, serving multinational corporations with complex entity structures requiring multi-scenario stress-testing capabilities.
| Leading Market Players |
|---|
| Planful |
| Workday Adaptive Planning |
| Anaplan |
| Cube |
| Prophix |
| Abacum |
| Mammoth Analytics |
| Vena |
| Datarails |
| Others |
Pricing and Supply Chain Analysis
Subscription pricing displacing perpetual license structures simultaneously shifts supply geography toward cloud infrastructure hubs and compresses margin capture for on-premises incumbents. This substitution dynamic redistributes value toward recurring revenue platforms while eroding upfront license economics.
Pricing Analysis
After-sales revenue through value-added reseller partnerships and accounting firm advisory retainers drives lifetime value concentration. The dominant pricing structure is subscription SaaS with consumption-based tiers tied to entity count or scenario volume rather than user seats. Price differentiation rests on ISO 27001 certification grade and native Excel integration depth. Cost compression in mid-market tiers is intensifying because cloud-native challengers collapse implementation cycles. SaaS-enabled accounting firms in the United States display the lowest price sensitivity, while Indian MSMEs remain most elastic.
Supply Chain Analysis
Just-in-time deployment through browser-native architectures dominates over strategic stockpiling of on-premises infrastructure. Supply concentrates in the United States for cloud-native platform development, Germany for automotive compliance module specialization, and India for fintech-integrated MSME solutions. Raw material dependencies include hyperscaler compute capacity, API integration frameworks, and machine learning training infrastructure. Single-source vulnerability stems from concentrated hyperscaler reliance for cloud infrastructure. Distribution runs through value-added resellers and accounting firm partnership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The financial forecasting software market sits at a cyclical recovery phase driven by compliance mandate waves from SEC climate disclosure and EU Digital Operational Resilience Act deadlines.
For Market Incumbents: Secure cross-sell integration depth within enterprise HCM installed bases before cloud-native challengers displace standalone forecasting vendors. Invest in generative AI feature development to defend against interface-centric entrants. Prioritize ISO 27001 certification maintenance to retain regulated financial institution procurement shortlists. For New Entrants and Emerging Players: Differentiate on agentic AI orchestration capabilities that compress period-close cycles for mid-market CFOs without dedicated analytics teams. Target India's MSME lending markets through Account Aggregator framework integration. Pursue embedded finance convergence via API-first forecasting modules bundled into banking platforms. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with native compliance documentation and accounting firm partnership density. Long-term viability hinges on generative AI integration depth and multi-entity consolidation architecture. The signal to watch is CSRD implementation acceleration across EU member states driving replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Generative AI Feature Integration | Natural language query capabilities collapse dashboard configuration friction for Excel-dependent finance teams. |
| Accounting Firm Partnership Expansion | Value-added reseller networks capture advisory retainer bundling opportunities in the United States. |
| ISO 27001 Certification Investment | Information security compliance unlocks regulated bank and investment firm procurement shortlists. |
| Embedded Finance API Development | Real-time cash flow projection integration into banking platforms bypasses standalone software procurement. |
| CSRD Compliance Module Launch | Pre-built Scope 3 emission forecasting templates address German automotive supplier auditor documentation requirements. |
Research Methodology
A spread of perspectives from CFOs at mid-market manufacturers, IT procurement officers at SaaS-enabled accounting firms, platform engineers at cloud-native vendors, and regulatory compliance leads at EU financial entities converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through SEC filings, EU regulatory directive documentation, and hyperscaler capex disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing across cloud-native and on-premises segments.
Segmentation dimensions modeled include deployment architecture, solution offering type, use case functional priority, and end-user organization category across the analysis window. CAGRs were derived from growth rate reconciliation between historical adoption curves and forward procurement intention surveys. Forecast inputs incorporated CSRD implementation timelines and SEC climate disclosure compliance deadlines without specific year anchoring.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement intensity and cloud infrastructure cost trajectories would require recalibration. Forecasts reflect assumptions on compliance mandate adherence rates and mid-market digital adoption velocity. Revision becomes warranted when generative AI capability commoditization crosses thresholds that erode vendor differentiation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Financial Fraud Detection Software Market
FinTech
Cloud AI in Fintech Market
FinTech
Financial Management Software Market
FinTech
Global Saas Spend Management Software Market
FinTech
Finance Cloud Market
FinTech
Autonomous Finance Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Saudi Arabia Fintech Market
FinTech
Europe Embedded Finance Market
FinTech
China Fintech Market
FinTech
Singapore Fintech Market
FinTech
United Kingdom Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Europe Financial Analytics Market
FinTech
Smart Advisors Market
FinTech
North America AI in Fintech Market