
 Smart POS System Market | 2026-2036
Smart POS System Market Size, Share, and Industry Trends Forecast 2026-2036
Smart POS System Market Insights
PCI DSS compliance is hardening the cost-of-entry calculus for new hardware entrants, forcing investments in encrypted card readers and secure element chips. Ingenico leverages its European manufacturing footprint to sustain certification breadth across regional variants. Verifone anchors North American enterprise accounts through dedicated account teams and vertical-specific software bundles. PAX Global Technology competes on price-performance in emerging markets where terminal density remains low.
A smart POS system integrates payment processing hardware with software-driven inventory, customer relationship, and analytics functions, typically incorporating ARM-based processors, touchscreen interfaces, and dual-band Wi-Fi connectivity to enable real-time transaction authorization and cloud synchronization. The primary commercial purpose is to unify checkout operations with back-office intelligence for merchants seeking operational visibility. Cloud-based POS deployment is capturing the fastest expansion as small and mid-sized merchants abandon capital-intensive on-premise installations. Mobile POS terminals are carving out share in hospitality and entertainment venues where fixed-counter constraints limit service speed. Biometric authentication technology is creating premium margin pools as retailers deploy fingerprint and facial recognition for card-not-present fraud reduction.
The US Federal Trade Commission and the European Banking Authority shape terminal security standards and liability allocation between merchants and acquirers, while China's MIIT enforces domestic encryption protocols that favor local certification holders. These frameworks fragment product roadmaps and extend development cycles for vendors seeking multi-jurisdiction approval. Stakeholders must monitor evolving authentication mandates and cloud data residency requirements to align R&D allocation with regulatory trajectories.
Market Dynamics
Terminal replacement cycles in quick-service restaurants are compressing as PCI DSS compliance mandates and biometric authentication requirements force simultaneous hardware and software upgrades across merchant estates.
Growth Catalysts
- PCI DSS 4.0 Compliance Deadlines:Merchants in the United States face mandatory encryption upgrades for card readers and secure element chips, accelerating terminal refresh programs.
- Quick-Service Restaurant Omnichannel Integration:Kiosks and mobile ordering platforms require cloud-synchronized POS terminals capable of real-time inventory deduction across digital and physical channels.
- Contactless Payment Infrastructure Deployment:Germany's retail banking consortium is expanding NFC terminal density in small merchant segments previously served by cash-only systems.
Market Restraints
- Secure Element Chip Supply Concentration:Foundry capacity for certified payment processors concentrates in Taiwan and South Korea, creating input bottlenecks for terminal manufacturers.
- Regulatory Fragmentation Across Jurisdictions:China's MIIT domestic encryption protocols require separate certification tracks from EBA standards in Europe, extending product development cycles.
- Software-Defined Terminal Substitution:Tablet-based mPOS solutions with downloadable payment applications threaten dedicated hardware demand in micro-merchant segments.
Strategic Opportunities
- Biometric Authentication Convergence:Fingerprint and facial recognition modules integrated with EMV kernels create premium pricing tiers for fraud-sensitive retailers.
- India's Digital Payment Expansion:RBI's push for merchant discount rate reductions and UPI terminal subsidies opens volume opportunities in underpenetrated tier-2 and tier-3 cities.
- Cloud-Native SaaS Distribution:Subscription-based POS software delivered through payment processor app marketplaces displaces traditional reseller channels.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Vendors seeking simultaneous approval from the FTC, EBA, and MIIT face sequential testing queues that delay product launches by 8-14 months.
- Embedded Systems Engineering Talent Scarcity:ARM-based secure processor development requires specialized firmware expertise concentrated among semiconductor veterans in Austin, Bangalore, and Cambridge.
- Legacy ERP Integration Complexity:Mid-market retailers operating on-premise inventory systems demand custom API development for cloud POS synchronization, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart POS System Market |
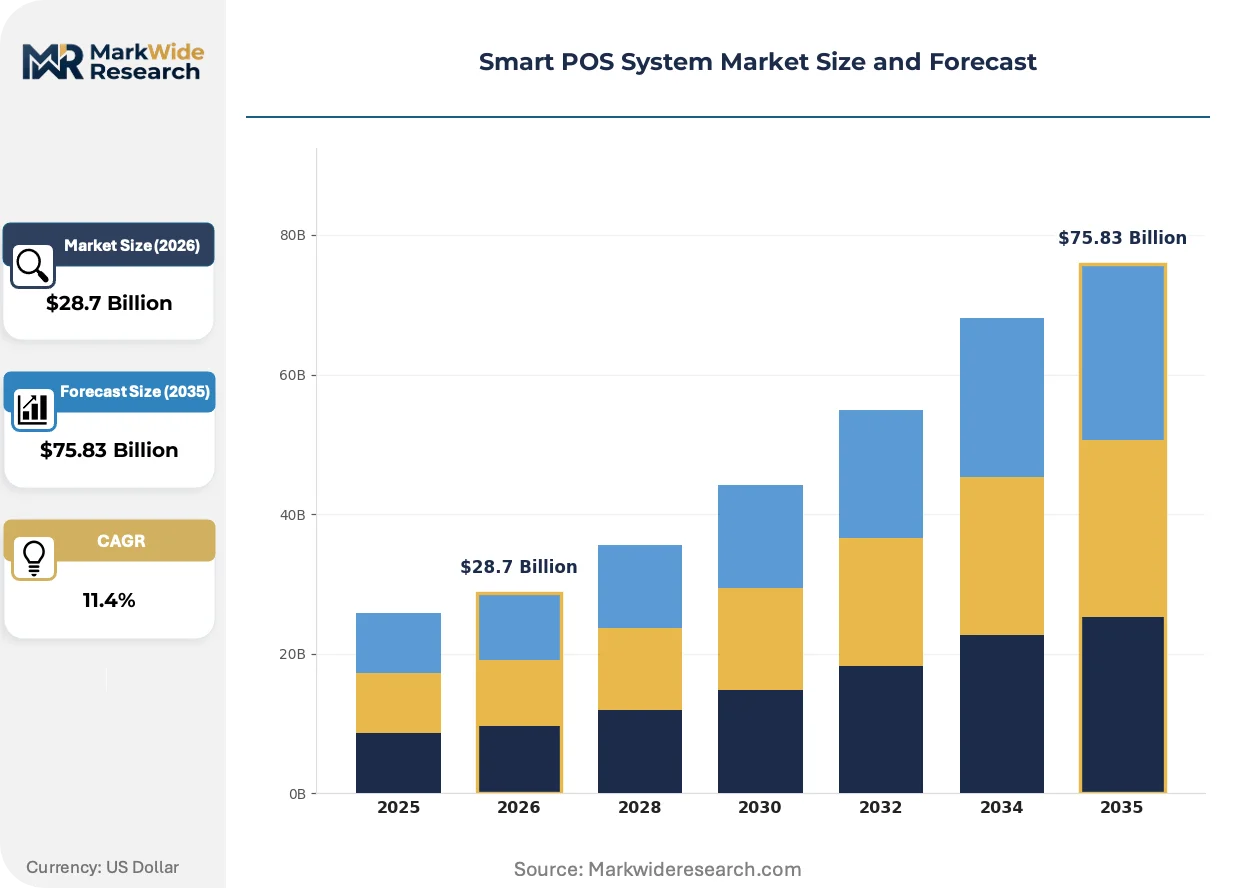
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed POS, Mobile POS, Cloud-Based POS, Hybrid POS End User: Retail Stores, Restaurants, Hospitality, Entertainment Venues Technology: Contactless Payment, NFC, Barcode Scanning, Biometric Authentication Deployment: On-Premise, Cloud, Hybrid, Others |
| Companies Covered | Ingenico, Verifone, NCR Corporation, PAX Global Technology, Diebold Nixdorf, Castles Technology, Block, Shopify, Lightspeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart POS System Market Trends and Innovations
Cloud-native architecture is overtaking on-premise installations as the default deployment model, compressing merchant capital requirements while expanding real-time analytics capabilities across distributed store networks.
Android-based open-platform terminals are overtaking proprietary operating systems in new merchant deployments. Small and mid-sized retailers in hospitality and specialty retail favor these devices for their application marketplace flexibility and lower total cost of ownership. The shift is overtaking traditional closed-system vendors' maintenance revenue streams and forcing SDK-based partner ecosystems.
The European Banking Authority's Strong Customer Authentication requirements under PSD2 are mandating biometric or two-factor verification for card-not-present transactions above threshold amounts. Terminal manufacturers must integrate fingerprint sensors or facial recognition cameras into countertop devices. German and French acquirers are demanding certified modules by Q3 2026, compressing hardware roadmaps.
Merchant acquisition patterns are fragmenting as ISOs and payment facilitators unbundle hardware from processing contracts. Small restaurants and salons now source terminals through e-commerce marketplaces and configure payment routing independently. This behavior concentrates in the United States and United Kingdom where processor switching costs have declined following regulatory intervention on interchange fee transparency.
Smart POS System Market Segmentation
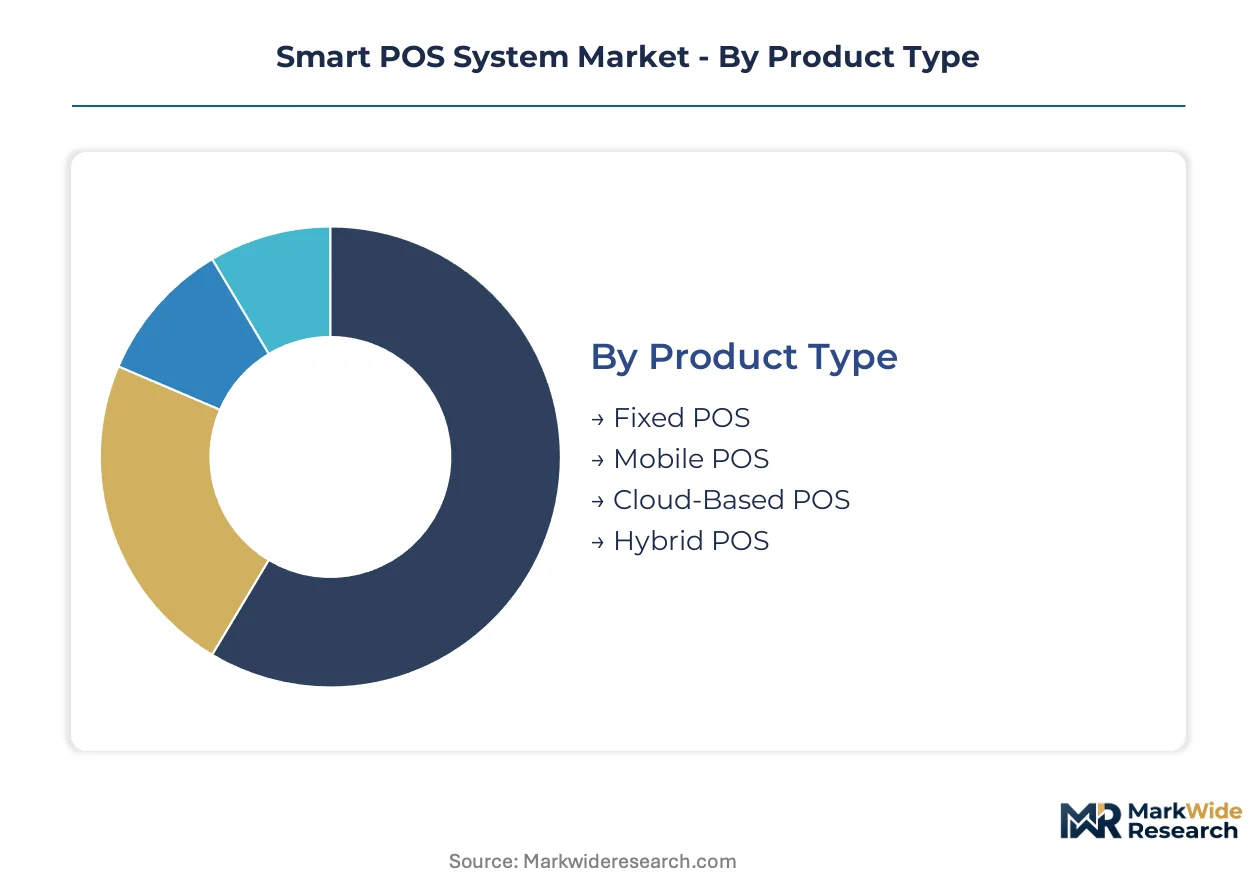
Smart POS system segmentation reveals how hardware specifications, software architecture, and authentication methods diverge across merchant scale and transaction environments. Understanding these splits clarifies why terminal procurement patterns vary dramatically between quick-service restaurants and specialty retail chains.
Product Type:
Supply concentration for payment processors and secure element chips shapes which terminal formats achieve manufacturing scale and certification breadth fastest.
- Fixed POS:Countertop terminals with integrated receipt printers, cash drawers, and customer-facing displays dominate high-volume retail environments. These systems absorb the majority of PCI DSS 4.0 compliance-driven replacement cycles in the United States as merchants upgrade encryption modules.
- Mobile POS:Handheld terminals with Bluetooth-connected card readers and tablet-based interfaces are displacing fixed infrastructure in hospitality and entertainment venues where tableside payment accelerates turnover. Germany's small merchant segment is expanding NFC-enabled mPOS density fastest among previously cash-only operators.
- Cloud-Based POS:Browser-accessible platforms with minimal local hardware requirements reduce capital barriers for micro-merchants.
- Hybrid POS:Systems combining local transaction processing with cloud synchronization address connectivity-unstable environments.
Fixed POS absorbs the bulk of installed capacity; Mobile POS is expanding most quickly.
End User:
Customer transaction velocity and payment method diversity determine which merchant verticals prioritize biometric authentication and omnichannel integration.
- Retail Stores:Department stores and grocery chains deploy self-checkout kiosks with integrated scanners and contactless pads. Inventory synchronization demands are forcing cloud POS adoption across multi-location apparel chains in China.
- Restaurants:Quick-service and full-service establishments require kitchen display system integration and split-check functionality. Table management software compatibility is narrowing vendor selection for independent operators in tier-2 Indian cities.
- Hospitality:Hotels and resorts need property management system connectivity and multi-currency support.
- Entertainment Venues:Stadiums, theaters, and amusement parks prioritize speed over receipt detail for concession transactions.
Retail Stores command the largest hardware procurement volumes; Restaurants are climbing the fastest as PCI deadlines compress replacement timelines.
Technology:
Authentication method selection reflects fraud exposure severity and customer demographic preferences across transaction environments.
- Contactless Payment:Tap-to-pay card and mobile wallet acceptance requires NFC antenna integration and EMV kernel certification. Small merchant segments in Germany previously resistant to electronic payments are converting fastest under banking consortium terminal subsidy programs.
- Biometric Authentication:Fingerprint sensors and facial recognition cameras embedded in countertop devices address card-not-present fraud. PSD2 Strong Customer Authentication mandates are forcing module integration for French and German acquirers.
- NFC:Near-field communication enables peer-to-peer transfer and wearable payment acceptance.
- Barcode Scanning:1D and 2D imagers support loyalty program enrollment and product lookup.
Contactless Payment dominates new terminal shipments; Biometric Authentication is gaining share fastest as fraud-sensitive retailers accept premium pricing.
Deployment:
Capital availability and IT staffing levels determine whether merchants absorb upfront hardware costs or shift to subscription-based operational expenditure models.
- Cloud:SaaS-delivered POS with browser-based interfaces eliminates server maintenance burdens. India's tier-2 and tier-3 cities are expanding cloud POS fastest under RBI-subsidized UPI terminal programs.
- On-Premise:Locally installed software with dedicated servers persists among mid-market retailers with legacy ERP integration requirements.
- Hybrid:Local transaction processing with cloud backup addresses intermittent connectivity in semi-urban locations.
- Others:Edge-deployed and containerized architectures serve specialized latency-sensitive applications.
Cloud deployment captures the majority of new merchant additions; Hybrid configurations are expanding most quickly among connectivity-constrained operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Bangalore concentrate terminal manufacturing and software development capacity, attracting payment processor certification labs and ARM-based chipset design houses.
United States
Quick-service restaurant chains compress replacement cycles to meet PCI DSS 4.0 encryption mandates. The FTC enforces terminal security standards that allocate liability between merchants and acquirers. Atlanta hosts major payment processor headquarters where cloud-native POS platforms undergo certification testing.
Germany
Small merchant segments convert from cash-only systems under banking consortium NFC terminal subsidy programs. The European Banking Authority's PSD2 Strong Customer Authentication rules mandate biometric module integration. Frankfurt's financial technology cluster drives acquirer demand for certified countertop devices.
China
Multi-location apparel chains force cloud POS adoption across distributed store networks. MIIT enforces domestic encryption protocols requiring separate certification tracks from European standards. Shenzhen's hardware manufacturing corridor supplies Android-based open-platform terminals to emerging markets.
India
Tier-2 and tier-3 cities expand terminal density under RBI-subsidized UPI programs with reduced merchant discount rates. The central bank's payment system directives shape subsidy allocation and certification requirements. Bangalore's software development ecosystem produces cloud-native SaaS distribution platforms.
United Kingdom
Independent restaurants and salons source terminals through e-commerce marketplaces following regulatory intervention on interchange fee transparency. The Financial Conduct Authority oversees payment system conduct rules. London's fintech cluster incubates ISO and payment facilitator business models that unbundle hardware from processing contracts.
Smart POS System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across certification-intensive segments. The vendor base stratifies into three tiers: multinational hardware manufacturers with broad geographic certification, regional specialists concentrating on price-performance in emerging markets, and software-native platforms expanding into embedded payment acceptance. Dominant competitive moves include strategic partnerships between terminal manufacturers and payment processors, plus portfolio diversification into biometric authentication modules.
Among diversified payment technology conglomerates, Ingenico and Verifone occupy positions spanning enterprise certification breadth and dedicated account team coverage. PAX Global Technology exemplifies the price-performance specialist archetype competing in terminal-density-constrained emerging markets. These three entities represent distinct strategic postures: European manufacturing footprint leverage, North American enterprise anchoring, and emerging market volume scaling.
| Leading Market Players |
|---|
| Ingenico |
| Verifone |
| NCR Corporation |
| PAX Global Technology |
| Diebold Nixdorf |
| Castles Technology |
| Block |
| Shopify |
| Lightspeed |
| Others |
Pricing and Supply Chain Analysis
Embedded systems engineering talent concentrated in Austin, Bangalore, and Cambridge feeds labor-cost differentials that widen pricing-tier spreads between premium biometric-enabled terminals and economy Android-based devices. The scarcity of ARM-based secure processor firmware expertise concentrates R&D overhead in certified product lines, compressing margins for vendors lacking scale.
Pricing Analysis
Short lead-time premiums apply to PCI DSS 4.0-certified terminals with integrated secure element chips, while spot inventory of prior-generation hardware trades at discounts. The dominant structure stratifies across premium biometric-authentication tiers, standard EMV-contactless configurations, and economy tablet-based mPOS alternatives. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because software-defined terminal substitution accelerates. Micro-merchants exhibit highest price sensitivity; enterprise quick-service chains absorb premium pricing for compliance-certain delivery.
Supply Chain Analysis
Reverse-logistics flows for terminal refurbishment and remanufacturing concentrate in Shenzhen and Taipei, extending hardware lifecycle value for certified payment processors. Foundry capacity for secure element chips centers on Taiwan and South Korea, with assembly operations drawing from China's component manufacturing base. Raw material dependencies span ARM-based chipsets, NFC antenna substrates, and biometric sensor modules. Single-source vulnerability in certified payment processor supply creates structural risk. Distribution runs through payment processor app marketplaces and traditional ISO reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where PCI DSS 4.0 mandates erect barrier-to-entry moats favoring incumbents with pre-certified hardware portfolios and dedicated certification teams.
For Market Incumbents: Acquire biometric authentication module suppliers to capture premium pricing tiers and defend against software-defined terminal substitution. Expand certification lab capacity in Frankfurt and Atlanta to compress multi-jurisdiction approval timelines. Vertical integration into secure element chip sourcing mitigates Taiwan foundry bottleneck exposure. For New Entrants and Emerging Players: Cloud-native SaaS platforms with browser-based interfaces offer a technology-first wedge into India's tier-2 and tier-3 merchant segments under RBI-subsidized UPI terminal programs. White-space targets include hospitality venues with connectivity-unstable environments requiring hybrid deployment architectures. Go-to-market through payment facilitator app marketplaces bypasses traditional ISO channel control. For Investors and Strategic Acquirers: Re-rating potential sits with Android-based open-platform terminal specialists given PSD2 Strong Customer Authentication mandate acceleration across German and French acquirers. Long-term viability favors vendors with simultaneous FTC, EBA, and MIIT certification breadth. Monitor biometric module certification queue lengths as inflection indicator for hardware roadmap competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Module Integration | PSD2 mandates force fingerprint and facial recognition adoption in German and French countertop devices. |
| Cloud-Native SaaS Distribution | Subscription platforms displace traditional reseller channels in India's RBI-subsidized UPI terminal expansion. |
| Multi-Jurisdiction Certification Investment | Simultaneous FTC, EBA, and MIIT approval compresses product launch timelines by 8-14 months. |
| Secure Element Chip Supply Anchoring | Taiwan and South Korea foundry partnerships mitigate input bottlenecks for terminal manufacturers. |
| Android Open-Platform Ecosystem Development | SDK-based partner networks displace proprietary operating system maintenance revenue streams. |
Research Methodology
Multi-period observation of terminal replacement cycle compression, certification queue lengths, and cloud POS adoption rates anchored the trend analysis, supplemented by interviews with payment processor product managers, terminal manufacturer R&D directors, ISO channel partners, and merchant IT procurement officers. Secondary validation drew from SEC filings of listed payment technology vendors, PCI DSS certification registry data, European Banking Authority PSD2 implementation trackers, and RBI payment system directives. Bottom-up merchant segmentation data and top-down hardware shipment estimates were triangulated to cross-validate volume assumptions.
Input-output matrices mapped ARM-based processor supply, secure element chip foundry allocation, and certification lab capacity against terminal shipment forecasts across the analysis window. Segmentation dimensions modeled include product type, deployment architecture, end-user vertical, authentication technology, and regional regulatory cluster. CAGRs were derived from terminal refresh program announcements and omnichannel integration timelines. Industry-specific forecast inputs encompass PCI DSS 4.0 compliance deadline pacing and biometric module integration roadmaps.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan semiconductor supply, abrupt regulatory reprieve on authentication mandates, and merchant abandonment of dedicated hardware for pure-software payment acceptance. Forecasts reflect assumptions regarding certification timeline continuity and foundry capacity expansion. Practitioners should monitor secure element chip lead times and multi-jurisdiction approval queue lengths for early signals of supply constraint or competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Israel Credit Cards Market
Payments
Belgium Payments Market
Payments
US Virtual Cards Market
Payments
United States Real Time Payments Market
Payments
Global Real-Time Payments Market
Payments
Cloud Billing Market
Payments
GCC Mobile Payment Market
Payments
Europe Gift Card and Incentive Card Market
Payments
Proximity Payment Market
Payments
Digital Payment Market
Payments
Global Payment Monitoring Market
Payments
Middle East and Africa Prepaid Card Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Transit Cards Market
Payments
Malta POS Terminal Market