
 UK Prepaid Cards Market | 2026-2036
UK Prepaid Cards Market Size, Share, and Industry Trends Forecast 2026-2036
UK Prepaid Cards Market Outlook
UK fintech issuance capacity is hardening as neobanks scale their prepaid card infrastructure. Revolut Ltd leverages its multi-currency technology stack to anchor cross-border spending volumes. Starling Bank competes through its Banking-as-a-Service rails that embed prepaid functionality for third-party distributors. Wise Plc differentiates on transparent foreign-exchange execution, sustaining transaction frequency among expatriate and freelancer segments.
Prepaid cards are stored-value payment instruments loaded with funds prior to transaction execution, typically operating on Visa or Mastercard networks without extending credit to the cardholder. These products serve commercial purposes spanning payroll disbursement, consumer budgeting discipline, and travel expenditure containment. Open loop products dominate transaction volume due to universal merchant acceptance, while reloadable formats capture the fastest growth as recurring-use behavior displaces single-load gifting applications. The business user segment concentrates margin pools, since corporate payroll and expense management programs generate higher interchange yields and lower churn than consumer budgeting tools.
The Financial Conduct Authority enforces conduct standards under Consumer Duty and the Electronic Money Regulations, requiring issuers to demonstrate fair value and adequate customer support. The Payment Services Regulator shapes interchange economics and access rules that determine issuer profitability and merchant acceptance breadth. The Information Commissioner's Office enforces data protection standards on transaction analytics and customer profiling activities. Stakeholders must monitor how the FCA's ongoing review of buy-now-pay-later regulation might extend to prepaid credit features, and whether the Bank of England's digital pound consultations alter the competitive positioning of private-sector prepaid infrastructure.
Market Dynamics
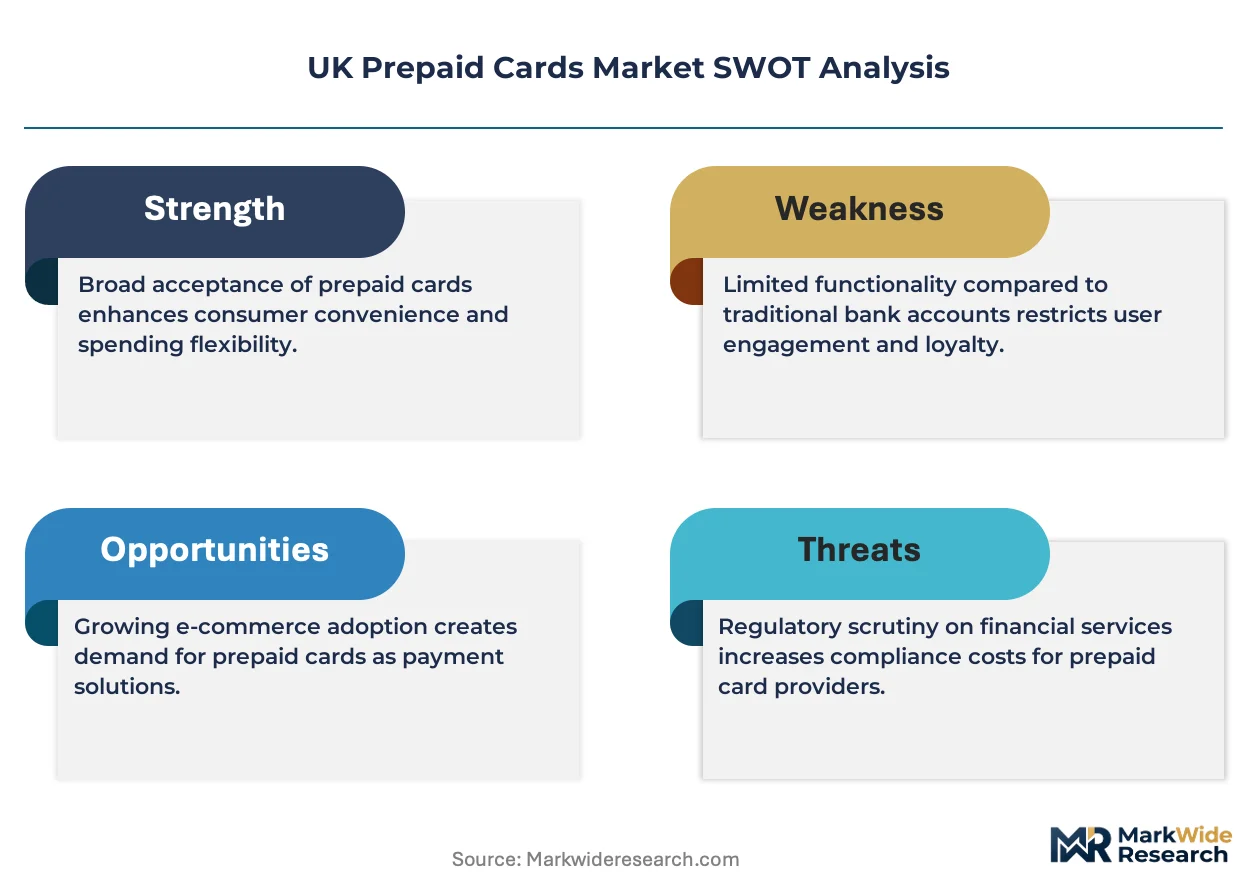
The Financial Conduct Authority's Consumer Duty framework is compressing issuer margins while forcing product governance upgrades across the UK prepaid card infrastructure. Compliance costs are redistributing competitive advantage toward scaled operators with dedicated regulatory technology stacks.
Growth Catalysts
- Electronic Money Regulations:The FCA's licensing regime creates barriers that protect incumbent issuers from unregulated competition, concentrating volume among authorized e-money institutions.
- Payroll disbursement:UK employers are migrating wage payments to prepaid rails to reduce banking costs and accelerate settlement timelines for gig-economy workers.
- London-South East corridor:Digital-first banking penetration among under-30 consumers concentrates transaction velocity in this geography, anchoring reloadable card adoption.
Market Restraints
- Interchange economics:The Payment Services Regulator's fee caps compress issuer profitability on low-value consumer transactions, favoring high-volume B2B programs.
- Single-currency legacy infrastructure:Core banking systems at traditional issuers lack real-time multi-currency processing, limiting cross-border product development.
- Gift card substitution:Digital wallet pass-through and voucher platforms displace single-load prepaid applications in corporate incentive budgets.
Strategic Opportunities
- Banking-as-a-Service embedding:Starling Bank's API infrastructure enables non-financial brands to launch co-branded prepaid products without direct FCA authorization.
- Scotland-North England corridor:Underpenetrated regions outside London present whitespace for neobanks to capture unbanked populations with basic account alternatives.
- Open Banking convergence:PSD2-mandated data sharing is automating prepaid funding from primary bank accounts, reducing friction in reload behavior.
Industry Challenges
- Regulatory technology talent:FCA Consumer Duty reporting requirements demand specialized compliance engineering skills that compete with broader fintech hiring pools.
- Legacy core migration:Established issuers face multi-year system transitions to real-time processing architectures required for competitive feature parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Prepaid Cards Market |
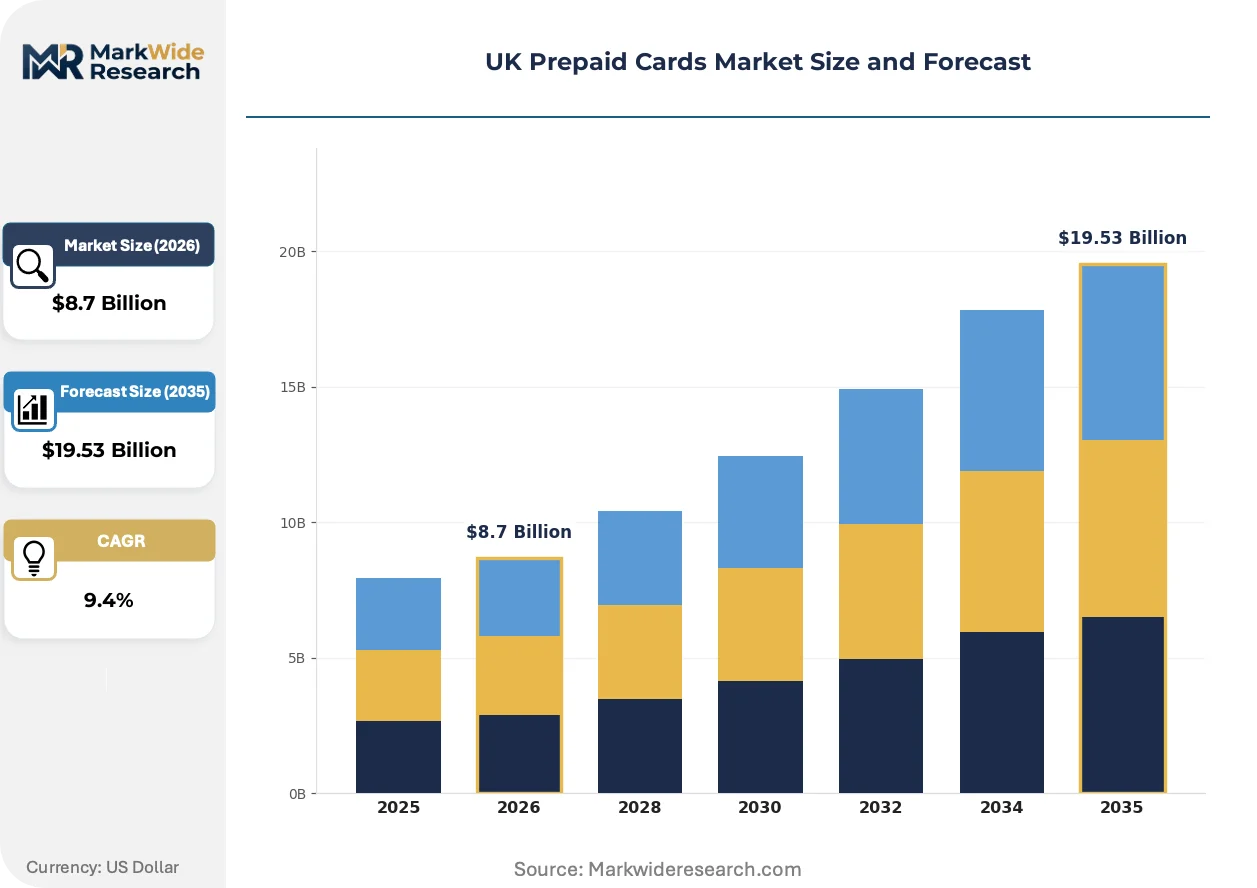
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Loop, Closed Loop, Reloadable, Non-reloadable User Type: Consumers, Businesses, Government, Non-profit Distribution Channel: Retail Stores, Online Platforms, Banks, Financial Institutions Purpose: Travel, Budgeting, Gifting, Payroll |
| Companies Covered | Edenred UK, Starling Bank, Revolut Ltd, Pockit, Tide Platform, PrePay Technologies, Wise Plc, allpay, Barclaycard, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Prepaid Cards Market Strategic Shifts
Real-time payment infrastructure and embedded finance architectures are converging to transform prepaid card functionality from stored-value instruments into integrated financial operating systems for consumers and businesses.
API-native card management platforms are automating KYC verification, transaction monitoring, and fund settlement workflows that previously required manual intervention. Mid-market fintechs and retail brands adopting these stacks compress launch timelines from months to weeks. The structural consequence is automating compliance cost distribution away from tier-one banks toward specialized infrastructure providers.
The FCA's Consumer Duty rules mandate fair value assessments and enhanced customer support standards across all retail financial products. Issuers must now document price transparency and vulnerability detection protocols or face enforcement action. The consumer segment bears the heaviest adaptation burden, with smaller e-money institutions accelerating partnership strategies to access shared compliance infrastructure.
Freelancer and expatriate segments are consolidating spending onto multi-currency cards that eliminate foreign exchange markups. Traditional banks with static forex pricing lose transaction frequency to transparent alternatives. This behavioral pivot concentrates volume among London-based digital natives and cross-border service professionals who prioritize cost visibility over brand familiarity.
UK Prepaid Cards Market Segmentation
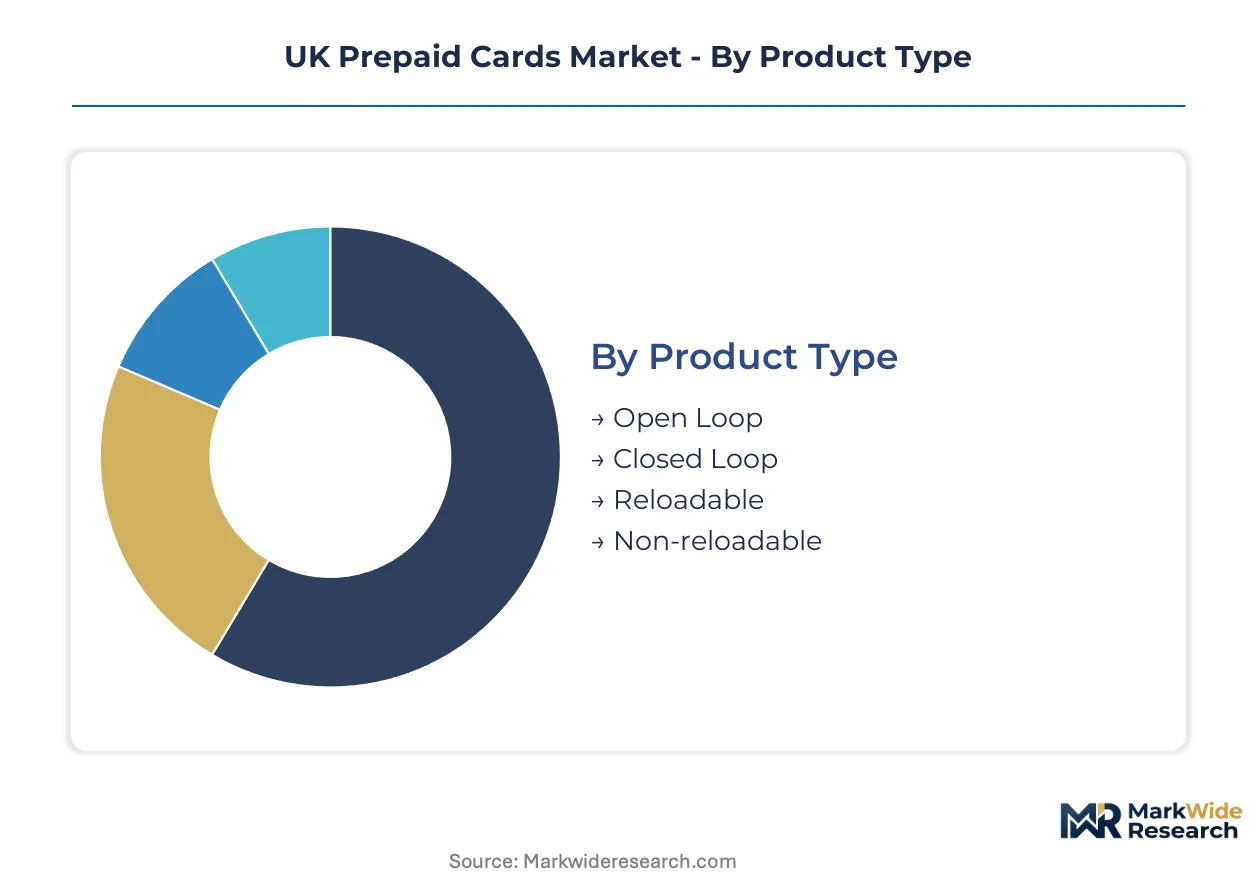
Prepaid card segmentation in the UK reveals how product architecture, user economics, and distribution mechanics interact to determine issuer profitability. Understanding these category boundaries enables precise targeting of high-margin applications versus commodity segments.
Product Type:
Customization intensity varies sharply across this spectrum, from standardized network-branded instruments to proprietary closed-loop systems requiring bespoke merchant integration.
- Open Loop:These products carry Visa or Mastercard branding and settle through standard interchange rails. Corporate expense management programs in London's financial services sector drive volume concentration, though Payment Services Regulator fee caps compress margins on low-value consumer loads.
- Reloadable:Cards permitting repeated fund deposits via bank transfer, cash networks, or Open Banking APIs. Under-30 consumers in the South East corridor favor these for budgeting discipline, with neobanks capturing recurring-use behavior through real-time notification features.
- Closed Loop:Single-merchant or limited-network instruments restricted to specific retail ecosystems. Major UK supermarket chains deploy these for loyalty-linked stored value.
- Non-reloadable:Single-load products typically issued for gifting or one-time disbursements. Digital voucher platforms are displacing these in corporate incentive budgets.
Most installed capacity flows through Open Loop products. Expansion is steepest in Reloadable formats as recurring-use behavior displaces single-load applications.
User Type:
Margin architecture diverges across this category, with commercial programs generating superior interchange economics and lower churn than consumer applications.
- Businesses:Corporate payroll and expense management programs command premium pricing through dedicated account management and API integration. The Financial Conduct Authority's Consumer Duty rules impose governance costs that favor scaled operators serving this segment.
- Consumers:Individual users seeking alternatives to traditional current accounts, concentrated among unbanked and underbanked populations. Fintech challengers capture this demand through digital-first onboarding and multi-currency functionality.
- Government:Public sector benefit disbursement and social payment programs. The Department for Work and Pensions has explored prepaid rails for universal credit distribution.
- Non-profit:Charitable organizations utilizing prepaid instruments for aid distribution and restricted-purpose grants. Compliance with FCA vulnerability detection protocols adds operational complexity.
Business segment concentration anchors issuer profitability. Consumer applications are gaining share fastest as neobank marketing reduces switching costs.
Distribution Channel:
Channel selection determines customer acquisition economics and regulatory burden intensity, with direct digital distribution compressing cost structures relative to intermediary-dependent models.
- Online Platforms:Neobank apps and fintech websites enabling instant issuance with in-app KYC verification. Revolut and Starling Bank dominate this channel through frictionless onboarding workflows.
- Banks:Traditional deposit-taking institutions offering prepaid products as gateway accounts. Legacy core systems limit real-time feature parity with digital-native competitors.
- Retail Stores:Physical point-of-sale distribution through supermarkets and convenience networks. Cash-loading infrastructure supports unbanked customer segments.
- Financial Institutions:Building societies and credit unions leveraging prepaid products for member expansion. Smaller scale necessitates partnership with Banking-as-a-Service providers for compliance infrastructure.
Online Platforms capture the majority of new account openings. Retail Stores retain relevance for cash-dependent user segments.
Purpose:
Application-specific use cases determine reload frequency, average transaction size, and vulnerability to substitute payment methods.
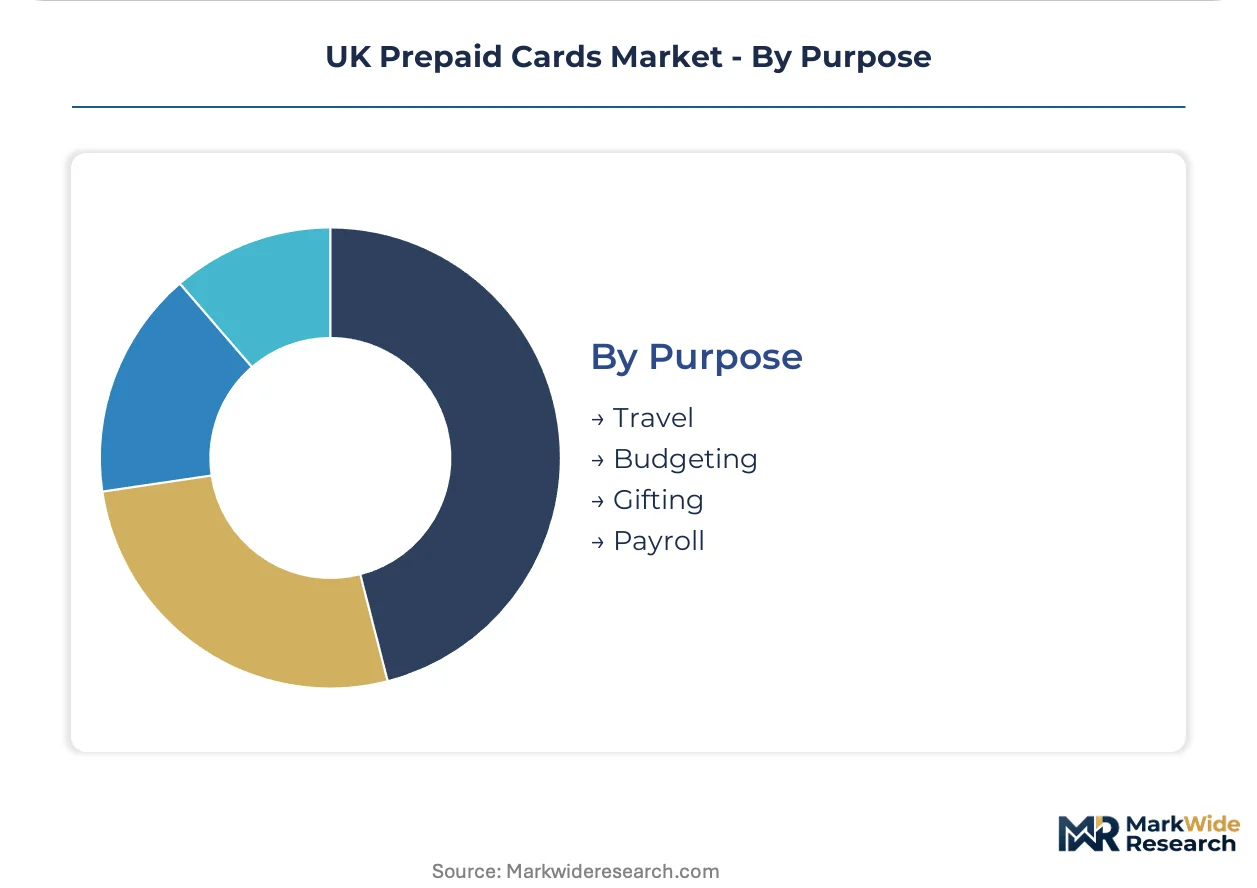
- Payroll:Employer-directed wage disbursement for gig-economy and temporary workers. UK employers migrate to prepaid rails to reduce banking costs and accelerate settlement timelines.
- Travel:Multi-currency spending with transparent foreign exchange execution. Expatriate and freelancer segments in London consolidate volume onto neobank-issued products.
- Budgeting:Self-imposed spending controls through segregated stored-value pools. Younger demographics favor reloadable formats with real-time balance notifications.
- Gifting:Single-load products for personal and corporate incentive use. Digital wallet pass-through and voucher platforms erode this application's growth trajectory.
Payroll applications anchor B2B issuer revenue. Travel purpose cards are climbing the fastest as cross-border remote work expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Financial Conduct Authority's Consumer Duty framework creates compliance cost disparities across UK sub-regions, concentrating scaled prepaid issuance in London's regulatory technology cluster while smaller operators migrate toward partnership models in lower-cost corridors.
London and South East
Digital-first banking penetration among under-30 consumers drives reloadable card adoption velocity. The FCA's Electronic Money Regulations license applications concentrate in this corridor, creating regulatory talent density. Fintech challengers cluster in Shoreditch and Canary Wharf, anchoring multi-currency product development for expatriate segments.
Midlands
Corporate payroll disbursement programs for logistics and manufacturing workforces generate B2B prepaid volume. The Payment Services Regulator's interchange fee caps compress margins on consumer transactions, favoring high-value employer-directed applications. Birmingham's fintech incubator supports Banking-as-a-Service middleware development for regional issuers.
North England
Underbanked populations in post-industrial urban centers create demand for basic account alternatives. The Department for Work and Pensions has piloted prepaid rails for benefit distribution in Greater Manchester. Leeds and Sheffield host emerging neobank operations targeting whitespace outside London's saturated core.
Scotland
Edinburgh's financial services heritage supports compliance infrastructure for e-money institutions serving UK-wide programs. The Scottish Government's financial inclusion initiatives explore prepaid instruments for rural unbanked communities. Glasgow's technology sector attracts fintech engineering talent from London's cost-pressured market.
Wales and Northern Ireland
Cash-dependent economies sustain retail store distribution networks for single-load products. The FCA's vulnerability detection protocols impose operational complexity on smaller issuers serving these markets. Belfast's regulatory technology providers offer shared compliance infrastructure to offset authorization burdens.
UK Prepaid Cards Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue embedded finance partnerships and Banking-as-a-Service distribution. The market structure concentrates among three archetypes: scaled neobanks with proprietary technology stacks, legacy payment processors modernizing through API layers, and specialized e-money institutions targeting niche disbursement verticals. Dominant competitive moves include strategic partnerships with non-financial brands for co-branded issuance and geographic expansion into underpenetrated UK corridors.
Within the scaled neobank tier, Revolut Ltd and Starling Bank exemplify divergent technology strategies. Revolut anchors cross-border spending volumes through multi-currency infrastructure. Starling occupies a position in Banking-as-a-Service, embedding prepaid functionality for third-party distributors without direct FCA authorization burdens. Wise Plc sits within the transparent forex execution archetype, sustaining transaction frequency among freelancer and expatriate segments through cost visibility rather than brand heritage.
| Leading Market Players |
|---|
| Edenred UK |
| Starling Bank |
| Revolut Ltd |
| Pockit |
| Tide Platform |
| PrePay Technologies |
| Wise Plc |
| allpay |
| Barclaycard |
| Others |
Value Chain & Pricing Dynamics
Multi-tier authorization divergence between full Electronic Money Regulations licenses and Banking-as-a-Service partnerships manifests in both pricing architecture and supply chain configurations across UK prepaid issuance. Premium-tier FCA-authorized issuers command higher interchange retention through direct network relationships, while middleware-dependent operators absorb compliance cost fragmentation through API-layer distribution.
Pricing Analysis
Direct-to-consumer digital channels compress acquisition costs relative to retail intermediary markups. Three-tier pricing structure across premium multi-currency, standard reloadable, and basic single-load levels stratifies by feature depth and foreign exchange transparency. Pricing pressure stems from Payment Services Regulator interchange caps on low-value consumer transactions. Corporate payroll segments exhibit lowest price sensitivity due to settlement efficiency gains; unbanked cash-loading users face highest sensitivity to load fees.
Supply Chain Analysis
FCA authorization gating concentrates compliant processing capacity among UK-licensed e-money institutions with dedicated regulatory technology stacks. Core card production draws from Netherlands, Germany, and Belgium manufacturing clusters. Payment network rails rest on Visa and Mastercard European settlement infrastructure. Single-source vulnerability concentrates in BIN sponsorship arrangements with limited FCA-authorized sponsors. Distribution runs through API-native platforms, traditional bank branches, and retail cash-loading networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK prepaid cards market compounds value through regulatory deepening, with the Financial Conduct Authority's Consumer Duty implementation accelerating compliance infrastructure demand across issuance tiers.
For Market Incumbents: Cement market position through captive BIN sponsorship capacity and proprietary core banking modernization. Vertical integration into real-time multi-currency processing defends against neobank feature parity. Regulatory technology talent acquisition anchors Consumer Duty reporting automation before smaller competitors access shared infrastructure. For New Entrants and Emerging Players: Enter via Scotland-North England corridor whitespace where digital-first penetration lags London saturation. Underbanked populations in Leeds and Manchester present lowest customer acquisition cost relative to regulatory density. Banking-as-a-Service embedding through Starling Bank APIs accelerates launch without direct FCA authorization timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where compliance cost scaling outpaces revenue growth for sub-scale e-money institutions. Mid-tier issuers with regional payroll contracts and aging core systems represent prime acquisition targets. Watch Payment Services Regulator interchange review announcements as margin structure inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Investment | FCA Consumer Duty automation separates scalable operators from partnership-dependent competitors. |
| Banking-as-a-Service Partnership | API embedding through authorized sponsors compresses launch timelines for non-financial brands. |
| Multi-Currency Infrastructure Buildout | Real-time forex processing captures expatriate and freelancer transaction frequency from legacy banks. |
| Corporate Payroll Program Expansion | Employer-directed disbursement generates superior interchange yields and lower churn than consumer applications. |
| Geographic Expansion to Underpenetrated Regions | Scotland and North England corridors offer whitespace with lower competitive intensity than London. |
Study Parameters
Multiple input streams — prepaid card issuer executives, regulatory compliance officers, Banking-as-a-Service platform engineers, and corporate treasury managers — were reconciled against secondary validation from FCA authorization registers, Payment Services Regulator interchange filings, and Open Banking implementation data. Bottom-up transaction volume modeling and top-down market sizing triangulation anchored value estimates across product and user type segmentations.
Historical issuance volume trajectories were cross-referenced against panel input from neobank product leads and legacy processor strategy heads. Segmentation dimensions modeled include product architecture, user economics, distribution channel, and geographic adoption pattern. CAGRs were derived through trend extrapolation adjusted for regulatory milestone impacts and competitive entry dynamics. Forecast inputs incorporated Electronic Money Regulations licensing velocity and Open Banking API penetration rates.
Inputs from FCA authorization databases and issuer financial disclosures were available through the study window; gaps in real-time transaction-level data introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding regulatory stability and competitive entry timing. A model refresh is warranted upon material change in Payment Services Regulator interchange policy or Bank of England digital pound implementation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
In-Vehicle Payment System Market
Payments
Portugal POS Terminals Market
Payments
Vehicle Toll Collection and Access System Market
Payments
Crypto Payment Gateway Market
Payments
Netherlands Mobile Payments Market
Payments
Europe Prepaid Card Market
Payments
Romania POS Terminals Market
Payments
Contactless Payment Terminals Market
Payments
Saudi Arabia Payment Gateway Market
Payments
Global Real-Time Payments Market
Payments
Forex Prepaid Cards Market
Payments
Middle East and Africa Payment Gateway Market
Payments
Global Wearable Payment Device Market
Payments
UK Virtual Cards Market
Payments
India RTP Market
Payments
Electronic Payment System for Transportation Market