
 Mobile Money Market | 2026-2036
Mobile Money Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Money Market Intelligence
The expanding role of mobile money in the small enterprises segment is repositioning the market beyond its traditional focus on individual consumer transfers. Safaricom leverages its pioneering M-PESA platform to sustain dominance in East Africa's financial ecosystem. MTN Group competes across multiple African nations through its extensive mobile network infrastructure and agent networks. In Bangladesh, bKash dominates its domestic market with a bank-led model focused on high-volume, low-value transactions.
Mobile money refers to electronic wallet services accessible via mobile phones, enabling financial transactions often without a formal bank account. These platforms operate using technologies ranging from basic USSD and SMS protocols to more advanced app-based interfaces with QR code functionality. While app-based and QR code technologies are becoming the standard for urban users, USSD remains critical for reaching rural populations with limited data access. Peer-to-peer transfers constitute the largest volume, but merchant payments and microfinance services represent the fastest-growing segments.
Regulatory frameworks established by central banks, such as the Reserve Bank of India (RBI) and the Central Bank of Kenya (CBK), directly influence market structure and interoperability rules. Data protection regulations like Europe's GDPR also impose strict compliance requirements on operators handling sensitive user financial information. Future platform success depends on the ability to customize service offerings while navigating these fragmented and evolving national regulatory environments.
Market Dynamics
The market's central structural force is the transition from a consumer-to-consumer transfer model to a broader digital commerce ecosystem. This evolution is driven by central bank mandates for payment system interoperability and the growing demand from small enterprises for accessible digital payment solutions.
Growth Catalysts
- National Financial Inclusion Initiatives:Government-led programs in countries like India and Nigeria are actively promoting mobile money as a tool to bring unbanked and underbanked populations into the formal financial system, creating a large, state-supported user base.
- QR Code Standardization:The widespread adoption of standardized QR code technology in retail and transport sectors simplifies merchant payments, lowering the barrier to entry for small businesses to accept digital transactions without expensive point-of-sale hardware.
- Small Enterprise Adoption:Small and medium-sized enterprises are increasingly leveraging mobile money platforms not just for payments but for payroll, supplier transactions, and basic cash flow management, expanding the market beyond individual use cases.
Market Restraints
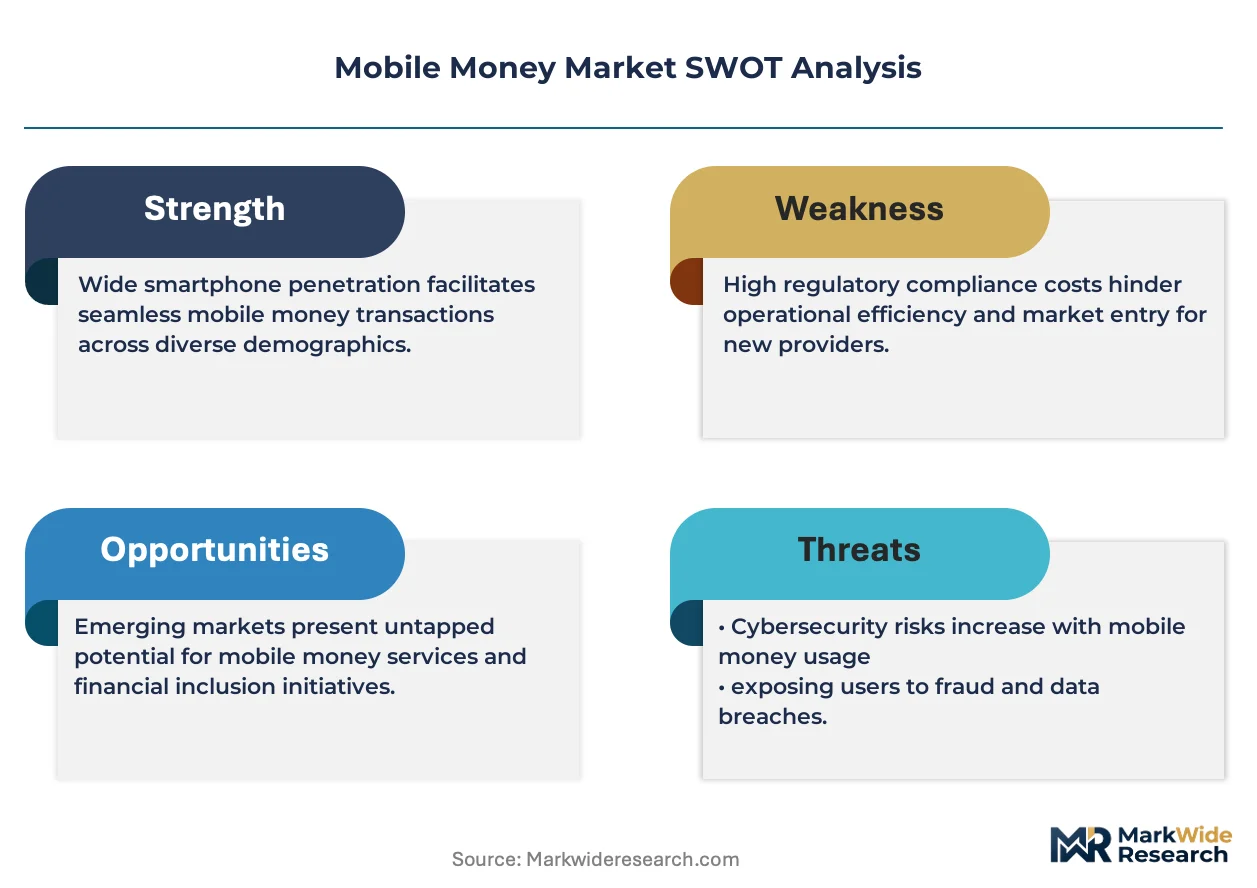
- Regulatory Fragmentation:Divergent national regulations, particularly concerning Know Your Customer (KYC) requirements and data localization rules, create significant compliance overhead and hinder the seamless cross-border operation of mobile money services.
- Legacy Technology Dependence:Continued reliance on USSD protocols to serve rural populations with feature phones limits the scope of available services and creates a functionality gap compared to richer, app-based experiences on smartphones.
- Competition from Bank-Led Systems:In markets with improving banking infrastructure, bank-led instant payment networks and neobank applications present a direct substitution threat, offering similar convenience with deeper integration into the formal banking system.
Strategic Opportunities
- Value-Added Financial Services:Integrating micro-credit, insurance, and investment products directly into mobile money wallets offers a significant revenue diversification opportunity, transforming platforms into comprehensive financial service hubs.
- Cross-Border Remittances:Targeting the high-cost international remittance corridor provides a major growth avenue, leveraging mobile money's low-cost infrastructure to disrupt traditional money transfer operators.
- IoT and M2M Payments:The convergence of mobile money with the Internet of Things (IoT) opens new use cases for automated machine-to-machine payments in sectors like logistics, smart utilities, and connected vehicle services.
Industry Challenges
- Platform Interoperability:Achieving seamless technical and commercial interoperability between competing MNO-led, bank-led, and independent fintech platforms remains a significant operational hurdle, often slowed by competitive friction and technical integration complexity.
- Data Security and Privacy Compliance:Operators face the ongoing challenge of securing sensitive financial data against sophisticated cyber threats while navigating complex and evolving data protection regulations like GDPR, requiring continuous investment in security infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Money Market |
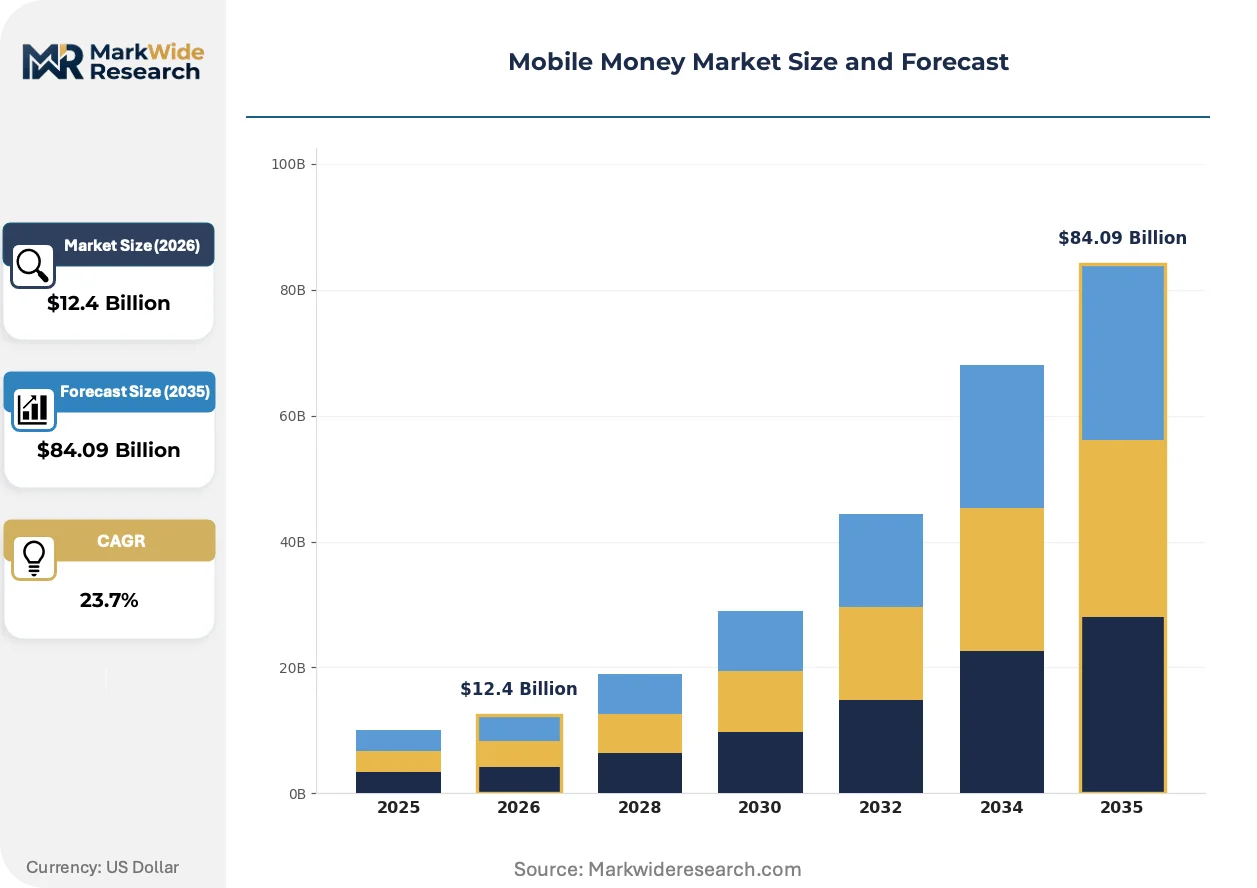
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $84.09 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Peer-to-Peer Transfer, Bill Payment, Merchant Payment, Microfinance, International Remittance, Salary Disbursement Technology: USSD, SMS, NFC, QR Code, Mobile Web, App-Based End User: Individual Consumers, Small Enterprises, Freelancers, NGOs, Educational Institutions, Religious Organizations Distribution Channel: Retail Agents, Mobile Network Operators, Online Platforms, Banking Correspondents, E-Wallets, Kiosks |
| Companies Covered | Safaricom, MTN Group, Orange, Vodafone Group, Airtel, bKash, GCash, True Corporation, Globe Telecom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Money Market Strategic Shifts & Innovations
The market's primary evolution is from a simple transactional tool to an integrated financial lifestyle platform. This shift is characterized by the fusion of advanced security, regulatory pressures for openness, and a fundamental change in how consumers and merchants interact with digital currency in daily life.
App-based interfaces incorporating biometric authentication provide a core layer of enhanced transaction security. Urban consumers and small business owners are rapidly adopting these features for their convenience and peace of mind. This secure payment technology is converging with national digital identity frameworks, enabling more complex financial services like instant credit scoring and loan disbursement directly within the mobile money application.
Regulatory mandates from central banks, such as those issued by the Reserve Bank of India, are a primary force for change. These rules compel platform operators to ensure full interoperability, enabling seamless fund transfers between competing wallets and traditional bank accounts. The segments most affected are historically closed-loop, MNO-led systems, which must now open their APIs and integrate with national payment switches.
A definitive behavioral shift from peer-to-peer transfers toward retail merchant payments is underway. This trend is displacing the use of physical cash for everyday purchases, especially within the informal economy where QR code adoption is high. This pattern is most pronounced in the bustling urban and semi-urban commercial centers of developing economies across Africa and South Asia.
Mobile Money Market Segmentation
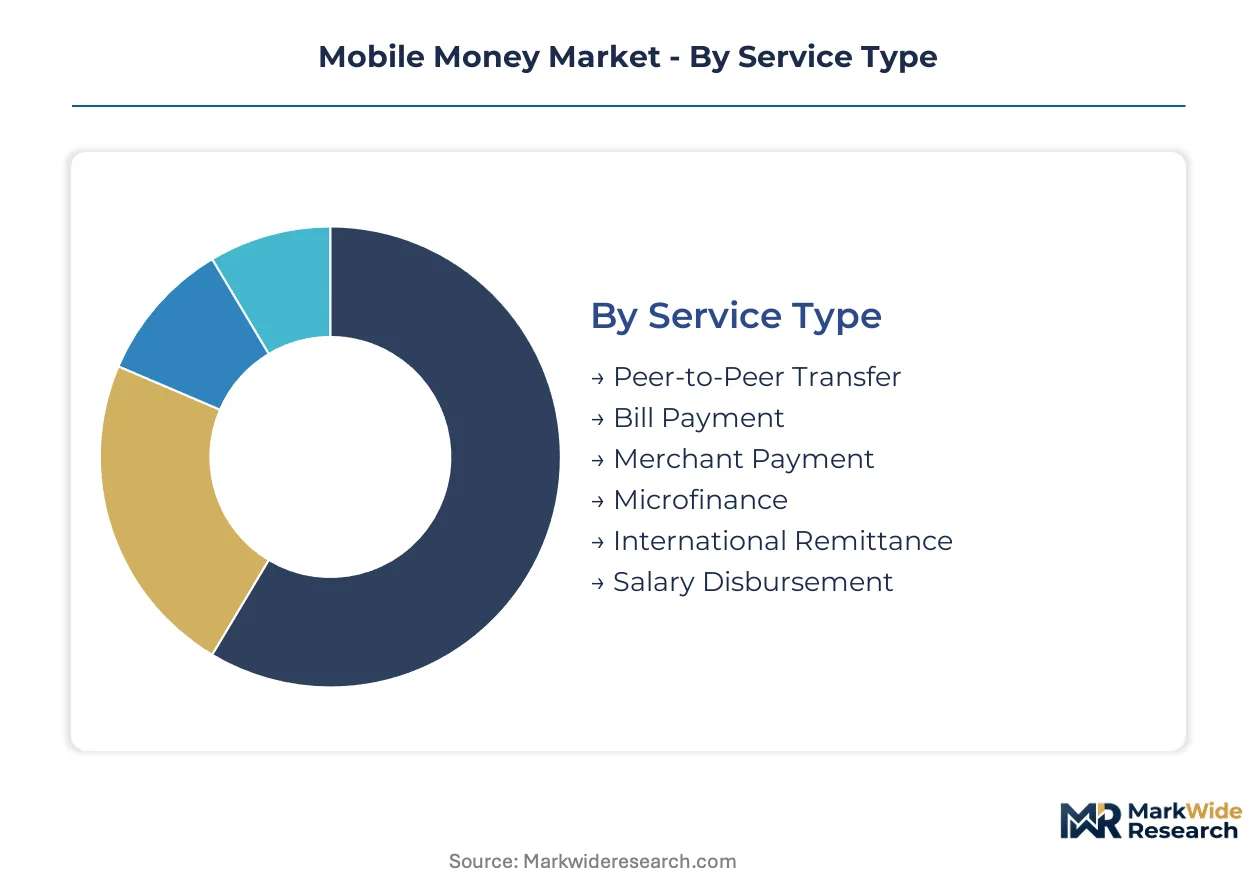
The mobile money market exhibits diverse segmentation, reflecting its expanding applications and user base beyond basic transactions. Understanding these distinct segments is crucial for operators and regulators to tailor services and navigate the complex compliance landscape effectively.
Service Type:
Mobile money service types often face distinct regulatory scrutiny, with varying compliance burdens for anti-money laundering (AML) and Know Your Customer (KYC) protocols depending on transaction value and cross-border nature.
- Peer-to-Peer Transfer:This service facilitates direct fund transfers between two individual mobile money accounts. It constitutes the largest volume of transactions, particularly in markets like Kenya and Nigeria, driven by everyday personal financial exchanges.
- Merchant Payment:This segment enables digital transactions between consumers and businesses for goods and services. It represents a rapidly expanding segment, especially within India and Bangladesh, as small enterprises increasingly adopt digital payment solutions.
- Bill Payment:Users settle utility bills and other recurring expenses directly through their mobile wallets.
- Microfinance:This service provides small loans, savings, and insurance products to underserved populations, often through mobile platforms.
- International Remittance:This service supports cross-border money transfers, offering a lower-cost alternative to traditional channels.
- Salary Disbursement:Employers pay wages directly into employee mobile money accounts, streamlining payroll processes.
Leading the category by volume: Peer-to-Peer Transfer. Growing fastest: Merchant Payment.
Technology:
The choice of mobile money technology directly influences user accessibility and the range of services that can be effectively delivered, spanning from basic feature phone support to advanced smartphone capabilities.
- USSD:Unstructured Supplementary Service Data (USSD) uses short codes for text-based menu interactions on any mobile phone. This technology remains critical for reaching rural populations in countries like Nigeria with limited smartphone penetration and unreliable internet access.
- App-Based:Dedicated mobile applications offer rich graphical user interfaces and advanced features, often with biometric authentication. Urban consumers and tech-savvy users in markets such as India increasingly prefer these platforms for their convenience and enhanced security.
- SMS:Transaction notifications and simple commands are executed via Short Message Service (SMS) protocols.
- NFC:Near Field Communication (NFC) enables contactless payments by tapping a mobile device on a compatible terminal.
- QR Code:Quick Response (QR) codes facilitate rapid merchant payments and peer-to-peer transfers through scanning.
- Mobile Web:Browser-based platforms provide access to mobile money services without requiring a dedicated application download.
The market currently favors USSD for reach, while app-based solutions are expanding most quickly.
End User:
Different end-user segments contribute distinct transaction volumes and value propositions to the mobile money ecosystem, influencing product development and service customization.
- Individual Consumers:This segment comprises the general public utilizing mobile phones for personal financial transactions, including transfers and bill payments. Individual consumers constitute the foundational user base, particularly in African markets, driving high volumes of peer-to-peer transfers and daily cash displacement.
- Small Enterprises:Businesses with limited staff and revenue use mobile money for merchant payments, payroll, and supplier transactions. This segment is central to market expansion, especially in India and Bangladesh, as digital payment acceptance becomes standard practice.
- Freelancers:Independent workers leverage mobile money for receiving payments and managing project-based income.
- NGOs:Non-Governmental Organizations use mobile money for disbursing aid, managing field expenses, and collecting donations.
- Educational Institutions:Schools and universities adopt mobile money for tuition fee collection and staff salary disbursements.
- Religious Organizations:Faith-based groups utilize mobile money for collecting offerings and managing charitable contributions.
Individual consumers form the largest user base, while small enterprises are gaining share fastest.
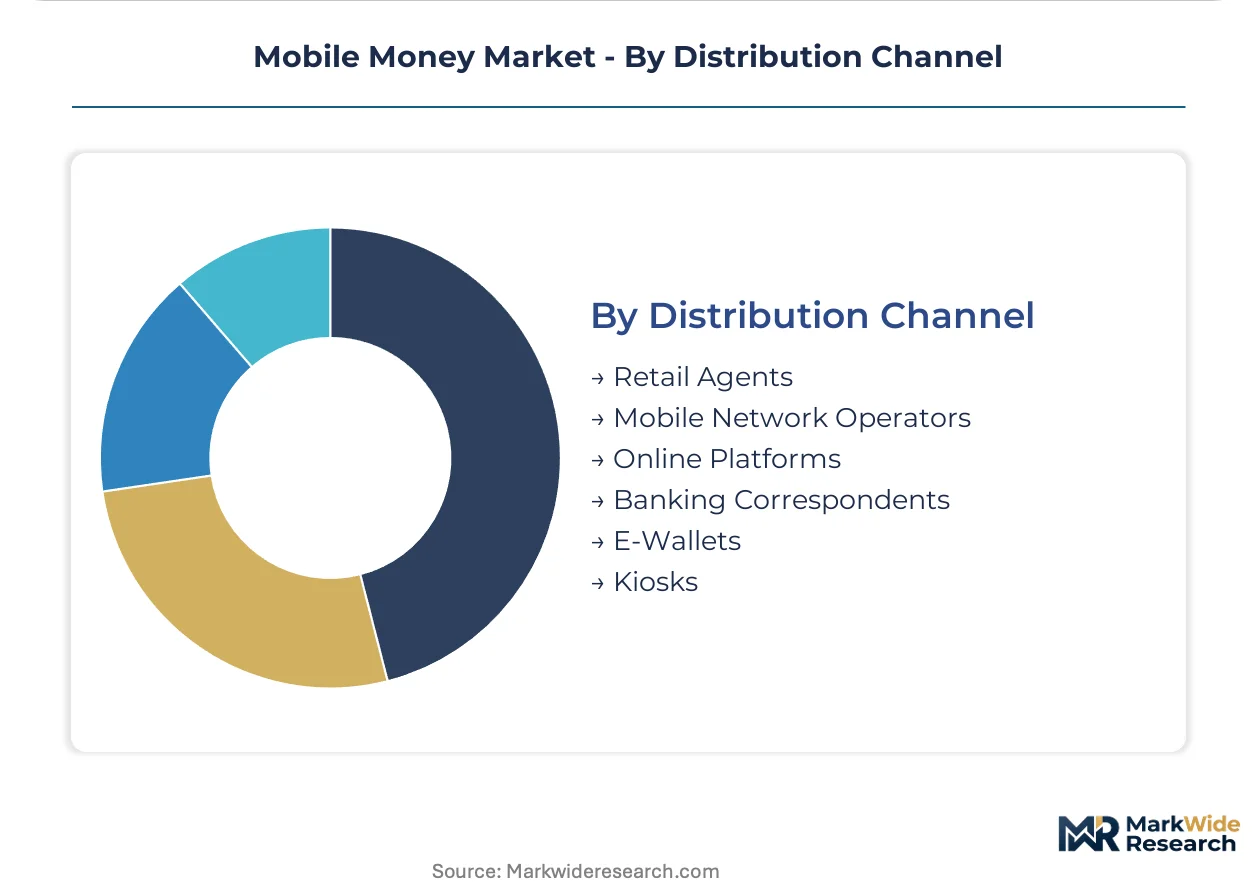
Distribution Channel:
The effectiveness of mobile money distribution channels directly impacts user acquisition and service accessibility, particularly in reaching unbanked populations across diverse geographies.
- Retail Agents:This network of physical outlets, often small shops, allows users to deposit, withdraw, and register for mobile money services. These agents are pivotal in extending mobile money's reach into rural and underserved areas, particularly across East Africa and West Africa.
- Mobile Network Operators:These telecommunications companies own and operate the underlying network infrastructure and often the mobile money platform itself. MNOs like Safaricom and MTN Group drive extensive platform integration and agent network expansion across multiple African nations.
- Online Platforms:Web-based or app-based interfaces allow users to manage mobile money accounts and conduct transactions digitally.
- Banking Correspondents:These intermediaries provide basic banking services on behalf of regulated banks, often leveraging mobile money infrastructure.
- E-Wallets:Digital wallets store funds and facilitate payments, sometimes independent of a specific mobile network.
- Kiosks:Automated or semi-automated terminals offer self-service options for mobile money transactions, including cash-in and cash-out.
Retail agents remain central to physical access, while mobile network operators anchor platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National financial inclusion initiatives, operating as concentrated policy zones, are driving significant mobile money market demand in key developing economies. These programs aim to integrate unbanked populations into formal financial systems through accessible digital payment platforms. This strategic focus underpins much of the market's expansion, particularly in regions with high smartphone penetration and robust government support for digitalization.
India
India's national financial inclusion initiatives drive substantial mobile money demand, particularly among small enterprises. The Reserve Bank of India (RBI) actively promotes payment system interoperability across various platforms. Widespread QR code adoption in bustling urban centers like Mumbai and Delhi facilitates everyday merchant payments. This strategic emphasis on digital transactions supports broad market penetration.
Nigeria
Nigeria benefits from strong national financial inclusion initiatives, aiming to integrate its large unbanked population. The Central Bank of Nigeria (CBN) oversees the regulatory framework for mobile money operations. Continued reliance on USSD protocols in rural areas ensures broad accessibility, complementing app-based growth in urban hubs like Lagos. This dual approach addresses diverse user needs.
Kenya
Kenya's mobile money market is significantly shaped by the pioneering M-PESA platform, sustaining dominance in East Africa. The Central Bank of Kenya (CBK) sets the regulatory environment, influencing market structure and interoperability. Nairobi serves as a hub for innovation, driving both individual consumer transfers and expanding merchant payment services. This mature ecosystem continues to evolve.
Bangladesh
Bangladesh exhibits strong mobile money growth, largely driven by bKash's domestic market dominance. Bangladesh Bank, the country's central bank, oversees the regulatory landscape for digital financial services. Its bank-led model focuses on high-volume, low-value transactions, especially in bustling commercial centers like Dhaka. Small enterprises are increasingly adopting these payment solutions.
Mobile Money Market Key Industry Players
Branded service providers and underlying infrastructure operators split market share differently across mobile money segments, reflecting diverse business models and regional strengths. The market structure exhibits a blend of MNO-led systems, bank-led platforms, and independent fintech archetypes. Companies pursue strategic partnerships to expand agent networks and geographic reach, particularly in underserved rural areas. Portfolio diversification into value-added financial services also represents a common competitive strategy, aiming to transform platforms into comprehensive financial hubs.
Within the MNO-led archetype, Safaricom, a Kenyan-based telecommunications company, and the South African-headquartered MTN Group exemplify extensive mobile network infrastructure leverage. Safaricom anchors East Africa's financial ecosystem with its pioneering M-PESA platform. MTN Group competes across multiple African nations, utilizing its broad agent networks. Separately, bKash, a Bangladeshi-based company, occupies a leading position within the bank-led model. This company focuses on high-volume, low-value transactions in its domestic market. These entities collectively demonstrate the varied approaches to mobile money market dominance.
| Leading Market Players |
|---|
| Safaricom |
| MTN Group |
| Orange |
| Vodafone Group | Airtel |
| bKash |
| GCash |
| True Corporation |
| Globe Telecom |
Cost & Logistics Intelligence
Regulatory mandates from central banks, such as those issued by the Reserve Bank of India, gate both qualified supply of interoperable platforms and premium-tier access for advanced financial services. This regulatory landscape significantly influences the cost structures and market entry barriers for mobile money operators.
Pricing Analysis
Premium pricing for short lead times on platform integration services reflects the urgent market demand for rapid deployment. The dominant pricing structure is a per-transactional fee model, often supplemented by subscription-tiered access for value-added services like micro-credit. Price differentiation stems from the breadth of agent network coverage and the level of regulatory compliance, particularly for GDPR adherence. Pricing pressure intensifies from bank-led instant payment networks, which often offer lower transaction fees. Individual consumers remain the most price-sensitive segment for basic peer-to-peer transfers, while small enterprises demonstrate lower sensitivity for comprehensive payroll and merchant payment solutions.
Supply Chain Analysis
Reverse-logistics flows for mobile money involve managing agent network liquidity and ensuring secure cash-in/cash-out points across vast geographies. Geographic supply concentration for platform development and operational support centers in India, Nigeria, and Kenya, driven by established MNOs. Raw material dependencies include mobile network infrastructure, secure data centers, and a robust physical agent network presence. Regulatory fragmentation represents a significant structural risk, hindering seamless cross-border operations and increasing compliance costs. The dominant downstream distribution model relies heavily on agent-led networks, which provide essential physical access points for users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile money market is in a vertical-integration race, driven by players pursuing deeper control over financial service product development directly within their platforms. This strategic imperative aims to capture more value across the transaction lifecycle.
For Market Incumbents:Hedge against increasing competitive pressure from bank-led systems by diversifying service portfolios beyond basic payments. Acquire specialized fintechs to integrate micro-insurance or investment products, enhancing platform stickiness. This strategy addresses the threat of neobank applications offering integrated financial solutions. Investment in robust data security infrastructure and regulatory compliance capabilities represents a critical lever for sustained trust and market share.
For New Entrants and Emerging Players:National financial inclusion initiatives in Nigeria open a window for fintechs to introduce specialized microfinance solutions. Target underserved rural populations with USSD-based micro-savings products, which require minimal smartphone penetration. Niche agricultural value chains represent a penetrable application segment. A key go-to-market angle involves forming partnerships with local community leaders and leveraging existing agent networks for rapid user acquisition.
For Investors and Strategic Acquirers:The widespread adoption of standardized QR code technology is the leading indicator that merchant payment ecosystems are maturing. Long-term viability remains strong for platforms evolving into comprehensive financial hubs, offering a full suite of services. Target agile fintechs with strong API integration capabilities or specialized value-added services, particularly in micro-lending or digital insurance. Monitor sustained growth in non-peer-to-peer transaction volumes as a key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhance Platform Interoperability | Enables seamless transfers between diverse mobile money providers, expanding user reach in India. |
| Develop Micro-Credit Products | Diversifies revenue streams and addresses the financial needs of small enterprises in Bangladesh. |
| Expand Agent Network Density | Improves cash-in/cash-out accessibility for rural populations across African nations. |
| Integrate Biometric Security | Boosts user trust and secures transactions on app-based platforms for urban consumers. |
| Target Cross-Border Remittances | Captures a high-value corridor by offering lower-cost transfer options for global users. |
Research Approach
Document review covered central bank reports, financial inclusion mandates, and mobile network operator disclosures, complemented by interviews with mobile money platform executives, fintech founders, and regulatory advisors. This approach combined primary insights with secondary validation, employing both bottom-up market sizing and top-down industry trend analysis.
Historical market data was cross-referenced with expert panel input to establish baseline figures and project future trajectories across the analysis window. Segmentation dimensions modeled included service type, technology, end-user, distribution channel, and regional regulatory maturity. Compound Annual Growth Rates were derived from a synthesis of historical performance and projected adoption rates. Key forecast inputs included smartphone penetration rates and national financial inclusion targets.
The model assumes a particular technology adoption path; alternative pathways for distributed ledger technology integration would alter the outlook. Forecasts reflect underlying assumptions regarding regulatory evolution and competitive dynamics. Practitioners should monitor shifts in central bank interoperability mandates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Korea Real Time Payments Market
Payments
Latin America Payment Gateway Market
Payments
India Forex Cards Market
Payments
Philippines Remittance Market
Payments
Singapore Remittance Market
Payments
South Korea Digital Payments Market
Payments
North America Payment Analytics Software Market
Payments
Direct Carrier Billing Market
Payments
North America Payments Market
Payments
Europe Payment Gateways Market
Payments
Mobile Wallet Market
Payments
Ghana Mobile Money Market
Payments
Japan Payments Market
Payments
Cyprus POS Terminals Market
Payments
Asia-Pacific Accounts Payable Automation Market
Payments
Latin America Mobile Payment Market