
 Latin America Retail Cash Management Market | 2026-2036
Latin America Retail Cash Management Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Retail Cash Management Market Analytics
Branch-based cash distribution across Latin America is tilting toward automated endpoint networks. BBVA sustains extensive recycler deployments across Mexican retail corridors. Bradesco anchors Brazil's cash-in-transit integration with banking infrastructure. Mercado Pago competes through digital-physical hybrid collection points that bridge informal commerce.
Retail cash management encompasses hardware, software, and services that automate currency handling, verification, storage, and transport for commercial endpoints, typically processing notes at speeds exceeding 1,000 bills per minute with counterfeit detection thresholds below 50 parts per million. Cash recyclers dominate capital expenditure budgets due to their dual deposit-dispense functionality that reduces armored car visit frequency. Smart safes attract independent retailers seeking provisional credit without daily bank runs. Cloud solutions are gaining fastest among chains requiring real-time visibility across multi-country operations.
Brazil's Central Bank governs cash handling standards through Resolution 4,893 while Mexico's CNBV supervises vault and transportation licensing for retail service providers. Argentina's BCRA imposes strict liquidity reporting that shapes safe deployment density. Stakeholders must weigh PIX and SPEI real-time rails against persistent cash dependency in informal trade corridors.
Market Dynamics
Brazil's Central Bank PIX infrastructure has compressed cash velocity patterns across metropolitan retail corridors, forcing cash management providers to reconfigure endpoint networks around real-time settlement rails while maintaining physical currency infrastructure for informal trade segments.
Growth Catalysts
- PIX Instant-Payment Infrastructure:Brazil's Central Bank real-time settlement rails are accelerating provisional credit offerings through smart safe networks, reducing retailer working capital requirements.
- Convenience Store Expansion:Brazil and Mexico's independent retail chains are deploying automated cash handling to reduce armored car visit frequency and labor costs.
- Resolution 4,893 Compliance:Brazil's cash handling standards mandate counterfeit detection thresholds that drive recycler upgrades across banking and retail endpoints.
Market Restraints
- Armored Car Cost Structure:Fuel and security labor inflation across São Paulo and Mexico City corridors compresses margins for cash-in-transit integration services.
- Import Dependency:Hardware recyclers and smart safes rely on Asian component supply chains vulnerable to currency volatility and logistics friction.
- PIX Substitution Effect:Brazil's zero-fee instant payments reduce cash transaction volumes in formal retail, constraining endpoint deployment ROI in urban centers.
Strategic Opportunities
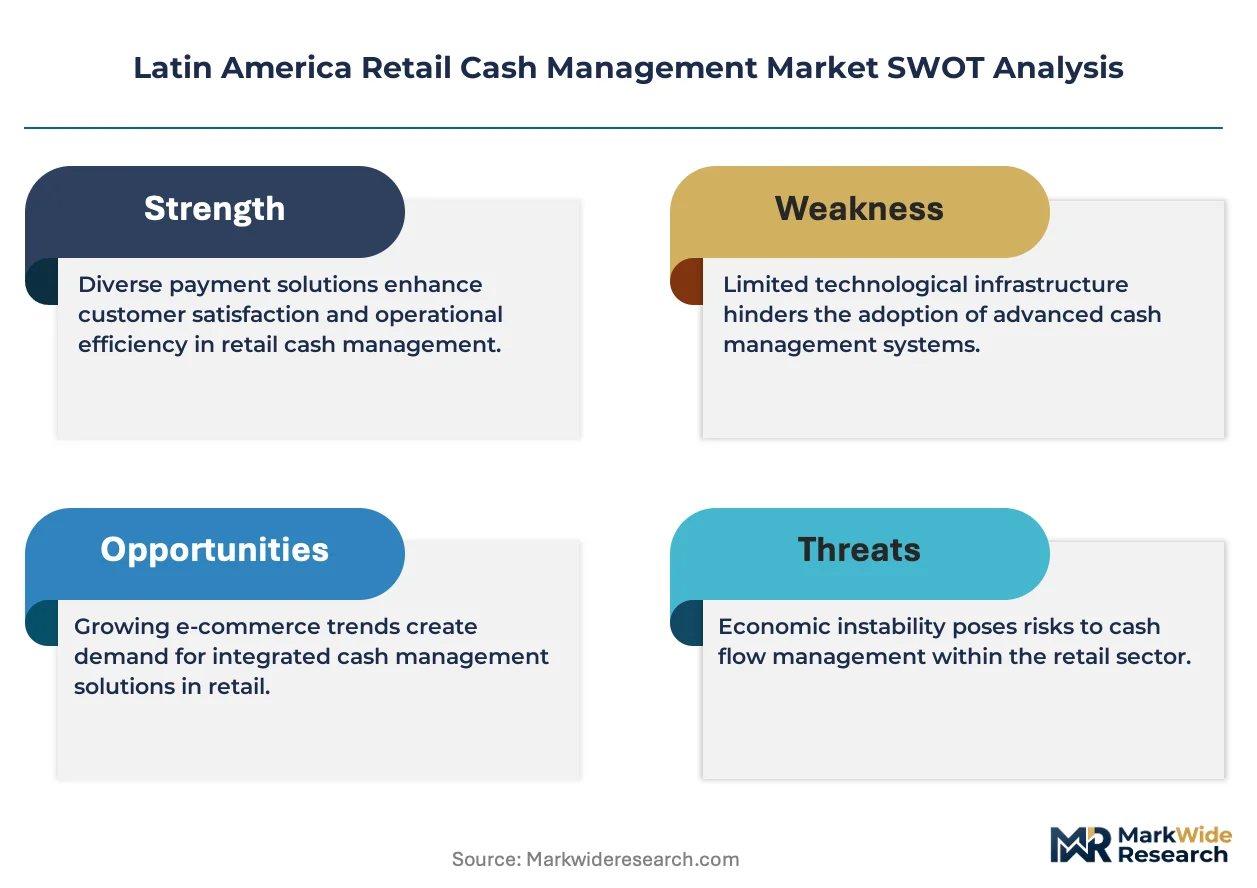
- Argentina's Liquidity Reporting Gap:BCRA's strict vault density requirements create demand for cloud-connected safe networks that automate compliance documentation.
- Colombia's Informal Commerce Corridors:Unbanked merchant segments in Bogotá and Medellín offer white space for digital-physical hybrid collection infrastructure.
- Multi-Country Cloud Visibility:Regional retail chains require real-time cash position monitoring across Brazil, Mexico, and Chile operations, favoring SaaS platform providers.
Industry Challenges
- Recycling Mechanism Maintenance:Note recognition sensors in high-dust environments require specialized technician networks that concentrate in São Paulo and Mexico City.
- Legacy Core Banking Integration:Provisional credit APIs must interface with Bradesco and BBVA's heterogeneous legacy systems, extending deployment timelines.
- CNBV Licensing Timelines:Mexico's vault and transportation licensing creates regulatory friction for cross-border service standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Retail Cash Management Market |
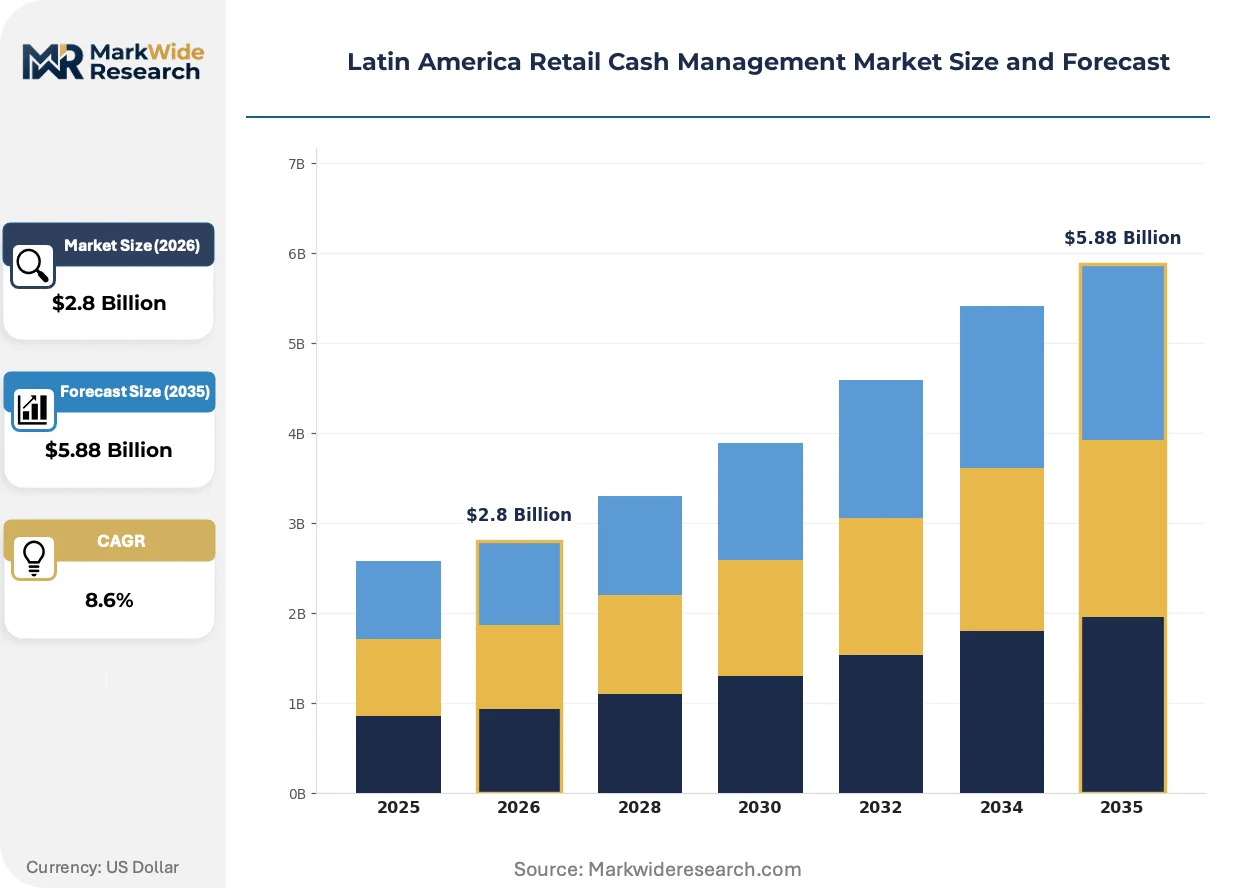
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cash Recyclers, Smart Safes, Cash Counters, Coin Sorters Customer Type: Retail Chains, Independent Retailers, Online Retailers, Convenience Stores Service Type: Transportation Services, Maintenance Services, Software Solutions, Security Services Technology: Biometric Systems, RFID Technology, Cloud Solutions, AI Analytics |
| Companies Covered | BBVA, Mercado Pago, Mastercard, J.P. Morgan, Bradesco, BTG Pactual, Citi, Morgan Stanley, BBVA Bancomer, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Retail Cash Management Market Evolving Landscape
Cloud-native cash management platforms are compressing the advantage of hardware-centric incumbents, while real-time payment rails force providers to reposition physical infrastructure as compliance and credit-enabling assets rather than transaction-processing endpoints.
AI-powered counterfeit detection is digitizing note verification workflows across Brazilian retail corridors. Supermarket and hypermarket chains in São Paulo's metropolitan zone are adopting multi-spectral imaging systems that process mixed denominations without manual sorting. The technology is digitizing labor allocation patterns, compressing cashier training requirements and reducing checkout friction.
Brazil's Resolution 4,893 and Mexico's CNBV transportation licensing frameworks are tightening endpoint security mandates. Retail service providers must now document chain-of-custody protocols for provisional credit eligibility. Small-format convenience stores face the steepest compliance burden, driving consolidation toward integrated hardware-software-service bundles.
Merchant procurement of cash management is rotating from capital purchase toward subscription-based service contracts. Independent retailers in Brazil's Northeast and Mexico's Central Belt prefer per-transaction pricing that bundles hardware, maintenance, and provisional credit. Chile's formal retail sector exhibits the fastest adoption of outcome-based arrangements where fees scale with cash velocity rather than device count.
Latin America Retail Cash Management Market Segmentation
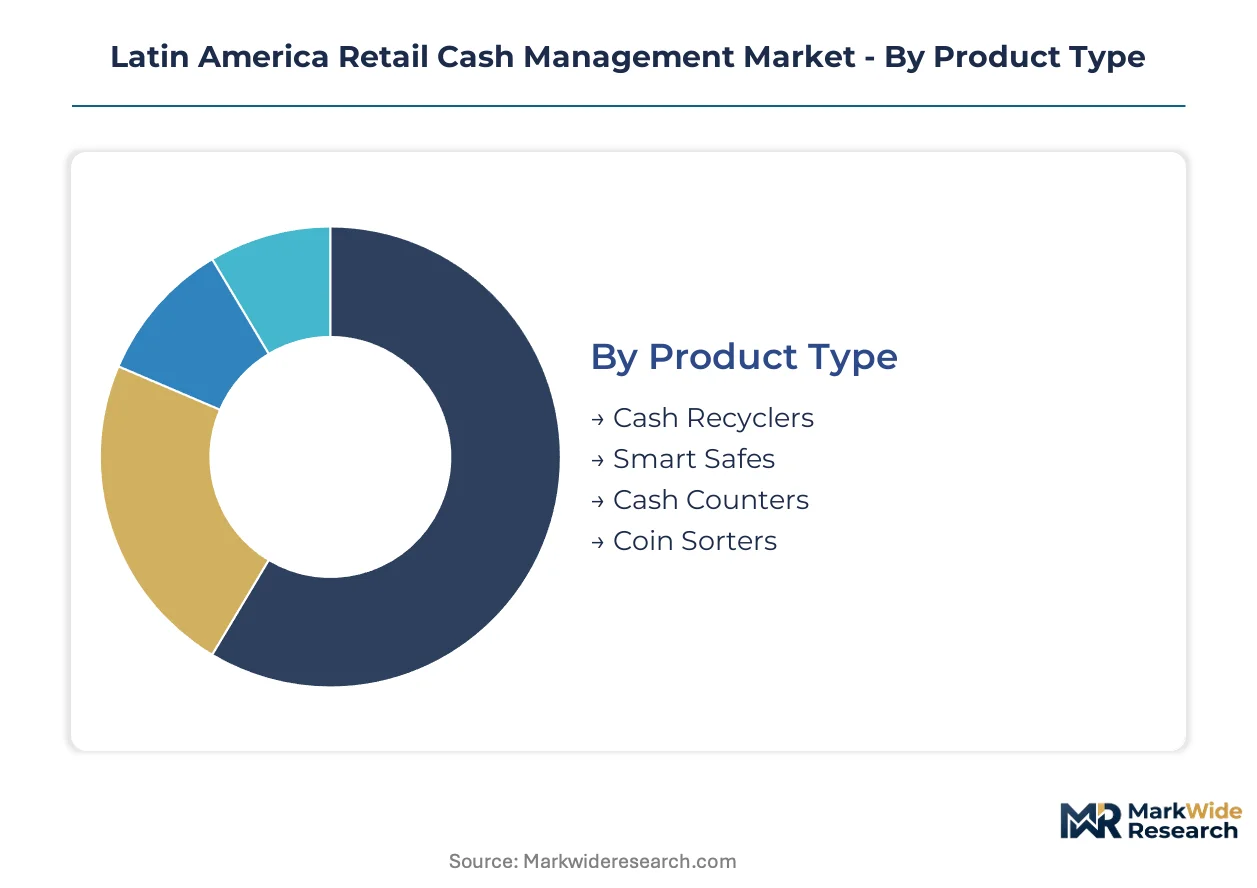
Cash management providers configure product portfolios around distinct operational intensity profiles across Latin American retail corridors. Each segment category reflects divergent capital constraints, regulatory exposure, and integration complexity that shape procurement patterns.
Product Type:
Hardware selection tracks cash velocity thresholds and provisional credit requirements across Brazilian and Mexican retail networks.
- Cash Recyclers:Dual-function deposit-dispense units process mixed denominations at speeds exceeding 1,000 bills per minute with counterfeit detection below 50 parts per million. São Paulo's metropolitan retail corridor concentrates demand as supermarket chains compress armored car visit frequency through automated recycling endpoints.
- Smart Safes:Network-connected vaults enable provisional credit without daily bank runs through real-time deposit verification. Independent retailers across Brazil's Northeast and Mexico's Central Belt favor these units to reduce working capital requirements and security labor costs.
- Cash Counters:Back-office verification devices with batch processing capabilities serve mid-size retail chains in Chile's formal sector.
- Coin Sorters:Specialized denomination-segregation hardware addresses high-coin-velocity segments including public transit and quick-service food in Buenos Aires and Bogotá.
The dominant share belongs to Cash Recyclers, while Smart Safes is closing the gap fastest.
Customer Type:
Procurement scale and integration sophistication vary sharply across organizational formats and geographic concentration.
- Retail Chains:Multi-location operators demand cloud-native visibility platforms with centralized cash position monitoring across Brazil, Mexico, and Chile operations. These buyers negotiate outcome-based contracts where fees scale with cash velocity rather than device count.
- Convenience Stores:Small-format independent networks across Brazil and Mexico deploy smart safe networks to meet Resolution 4,893 compliance while minimizing capital expenditure. PIX instant-payment infrastructure has accelerated provisional credit adoption among these liquidity-constrained operators.
- Independent Retailers:Single-location merchants in Colombia's informal commerce corridors favor per-transaction pricing bundles covering hardware, maintenance, and credit access.
- Online Retailers:Omnichannel fulfillment operations require hybrid cash-digital collection points bridging physical returns and cash-on-delivery reconciliation.
Retail Chains command procurement volume leadership, though Convenience Stores are expanding device deployment most aggressively.
Service Type:
Revenue mix is tilting toward recurring service contracts as hardware commoditization compresses upfront margins.
- Transportation Services:Armored car and vault logistics integrate with banking infrastructure under CNBV licensing frameworks in Mexico and Central Bank supervision in Brazil. Fuel and security labor inflation across São Paulo and Mexico City corridors pressures margin structures.
- Software Solutions:Cloud platforms enabling real-time visibility across multi-country operations attract fastest growth among regional retail chains requiring consolidated treasury management.
- Maintenance Services:Specialized technician networks for note recognition sensor calibration concentrate in São Paulo and Mexico City due to high-dust environment degradation rates.
- Security Services:Chain-of-custody documentation and compliance protocol management support provisional credit eligibility under tightening endpoint security mandates.
Transportation Services retains the largest revenue share, while Software Solutions is climbing the fastest as subscription models displace capital purchase arrangements.
Technology:
Capability investment prioritizes authentication accuracy and connectivity resilience over processing speed alone.
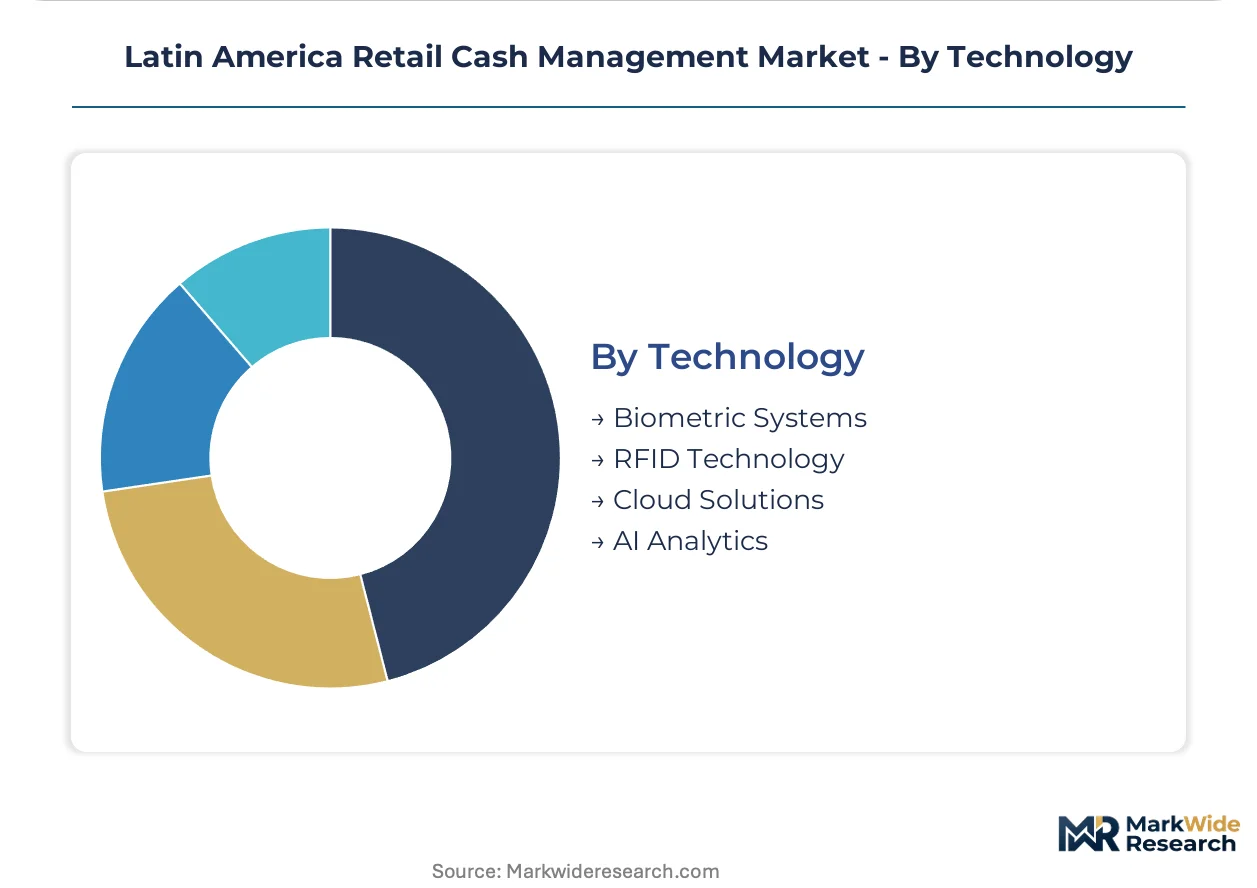
- Cloud Solutions:SaaS architectures deliver real-time cash position monitoring and automated compliance documentation for multi-country retail operations. Argentina's BCRA liquidity reporting requirements drive safe network connectivity demand.
- AI Analytics:Machine learning-powered counterfeit detection digitizes note verification workflows across Brazilian supermarket chains, compressing cashier training requirements and reducing checkout friction through multi-spectral imaging.
- Biometric Systems:Fingerprint and facial authentication secure endpoint access for provisional credit eligibility in high-fraud corridors.
- RFID Technology:Tag-based cash bag tracking supports chain-of-custody documentation for CNBV transportation licensing compliance in Mexico.
Cloud Solutions holds installed base leadership, while AI Analytics is gaining share fastest through supermarket and hypermarket upgrade cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's PIX instant-payment infrastructure anchors Latin America's retail cash management transformation, compressing cash velocity across metropolitan corridors while sustaining demand for physical endpoints in informal trade segments.
Brazil
Supermarket chains in São Paulo's metropolitan corridor deploy cash recyclers to reduce armored car visit frequency. Brazil's Central Bank Resolution 4,893 mandates counterfeit detection thresholds below 50 parts per million, driving hardware upgrade cycles. Bradesco anchors cash-in-transit integration with banking infrastructure across the Southeast region.
Mexico
Convenience store networks across Mexico's Central Belt favor smart safe networks with provisional credit functionality. Mexico's CNBV supervises vault and transportation licensing, creating regulatory friction for cross-border service standardization. BBVA sustains extensive recycler deployments across retail corridors in Mexico City.
Argentina
Cloud-connected safe networks automate compliance documentation for retailers facing strict liquidity reporting requirements. Argentina's BCRA imposes vault density requirements that shape safe deployment patterns. Buenos Aires concentrates demand for coin sorters in public transit and quick-service food segments.
Chile
Formal retail chains in Santiago adopt outcome-based service contracts where fees scale with cash velocity rather than device count. Chile's central bank standards support provisional credit eligibility through documented chain-of-custody protocols. The capital's corporate treasury functions drive fastest adoption of multi-country cloud visibility platforms.
Colombia
Unbanked merchant segments in Bogotá and Medellín create white space for digital-physical hybrid collection infrastructure. Colombia's financial regulator shapes endpoint security mandates for provisional credit eligibility. Informal commerce corridors in the Andean region sustain demand for per-transaction pricing bundles.
Latin America Retail Cash Management Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying authentication modules and connectivity hardware. The vendor base stratifies across banking incumbents with captive cash management arms, fintech platforms bridging digital-physical collection, and independent hardware-service bundlers. Two strategic archetypes dominate: banking-anchored providers leveraging core infrastructure relationships, and cloud-native challengers compressing hardware-centric incumbents through SaaS visibility platforms. Competitive moves concentrate on API integration with legacy core banking systems and subscription-based contract structures displacing capital purchase arrangements.
Among banking-anchored providers, BBVA and Bradesco occupy positions exemplifying the integrated hardware-software-service archetype, while Mercado Pago represents the fintech platform model bridging informal commerce through digital-physical hybrid collection points. These three entities anchor the competitive structure across Brazil and Mexico's primary retail corridors.
| Leading Market Players |
|---|
| BBVA |
| Mercado Pago |
| Mastercard |
| J.P. Morgan |
| Bradesco |
| BTG Pactual |
| Citi |
| Morgan Stanley |
| BBVA Bancomer |
| Others |
Value Network & Pricing Analysis
Asian component supply chain vulnerability determines both tiered hardware pricing spreads and procurement risk profiles across Latin American retail cash management markets. Currency volatility and logistics friction compress margins for recyclers and smart safes while forcing distributors toward bundled service contracts.
Pricing Analysis
Volume-discount tiering structures separate multinational retail chains from independent convenience store operators across Brazilian and Mexican procurement corridors. Pricing stratifies across premium, standard, and economy tiers based on counterfeit detection certification thresholds and cloud connectivity integration depth. Cost compression in the independent retailer segment intensifies because per-transaction pricing bundles mask hardware amortization within service fees. Convenience store networks exhibit highest price sensitivity due to liquidity constraints, while regional retail chains demonstrate lowest sensitivity through outcome-based contracts scaling with cash velocity.
Supply Chain Analysis
Upstream feedstock for note recognition sensors and recycling mechanisms draws from precision manufacturing clusters in China, South Korea, and Taiwan. Currency handling hardware rests on semiconductor components, optical imaging modules, and specialized metal alloys for cash transport mechanisms. Single-source vulnerability concentrates in high-dust-environment sensor calibration parts requiring specialized technician networks. Distribution runs through São Paulo and Mexico City logistics hubs serving banking-anchored providers and independent hardware-service bundlers across the Latin American corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American retail cash management functions as a defensive-moat market where regulatory entrenchment through Central Bank licensing and CNBV vault supervision creates durable barriers against unqualified competitors.
For Market Incumbents: Insulate core banking relationships through API integration depth with Bradesco and BBVA legacy systems, extending switching costs for retail chain clients. Deepen backward integration into cloud-native visibility platforms to offset hardware commoditization pressure from Asian component suppliers. Resolution 4,893 compliance mandates and CNBV transportation licensing create regulatory chokepoints that captive infrastructure providers can exploit. For New Entrants and Emerging Players: Colombia's informal commerce corridors in Bogotá and Medellín offer white-space expansion targets where unbanked merchant segments lack digital-physical hybrid collection infrastructure. Per-transaction pricing bundles covering hardware, maintenance, and provisional credit access represent the most penetrable go-to-market angle for liquidity-constrained independent retailers. Mercado Pago's fintech platform model demonstrates viable entry architecture bridging cash and digital rails. For Investors and Strategic Acquirers: Brazil's Central Bank PIX infrastructure expansion reshapes the acquisition landscape toward providers with real-time settlement integration capabilities. Long-term viability hinges on positioning physical infrastructure as compliance and credit-enabling assets rather than transaction-processing endpoints. Cloud-native challengers with multi-country SaaS visibility platforms represent priority acquisition archetypes. The signal to watch is provisional credit API penetration rates across supermarket and convenience store networks.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Real-time cash position monitoring across Brazil, Mexico, and Chile compresses hardware-centric incumbents. |
| Provisional Credit API Development | PIX instant-payment infrastructure integration reduces retailer working capital requirements in São Paulo corridors. |
| Multi-Spectral Imaging Deployment | AI-powered counterfeit detection digitizes note verification workflows across Brazilian supermarket chains. |
| Subscription-Based Service Contracts | Outcome-based arrangements scaling with cash velocity displace capital purchase arrangements in Chile. |
| Regulatory Compliance Automation | Argentina's BCRA liquidity reporting requirements drive cloud-connected safe network demand. |
Research Methodology
Cross-validation between primary fieldwork with cash management providers and secondary regulatory filings anchors the qualitative findings in documented Central Bank and CNBV standards. Conversations with hardware procurement directors at retail chains, armored car logistics managers, provisional credit product officers at banking incumbents, and cloud platform engineers informed operational intensity profiles. Secondary validation drew from Brazil's Central Bank Resolution 4,893 documentation, CNBV vault licensing registries, customs records for cash handling equipment imports, and SEC filings from banking-anchored providers. Bottom-up device deployment counts triangulate against top-down banking infrastructure expenditure patterns.
Calibration against historical cash velocity shifts following PIX infrastructure rollout informs projection elasticity across metropolitan retail corridors. Segmentation dimensions modeled include hardware type, customer format, service revenue mix, and technology integration depth alongside regional regulatory cluster differentiation. CAGRs derive from installed base expansion rates, replacement cycle compression, and service contract conversion velocity. Forecast inputs incorporate armored car visit frequency reduction targets and provisional credit adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investment by fintech challengers would shift outcomes beyond modeled ranges. Cross-checking against Central Bank payment system statistics and retail banking infrastructure expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Germany POS Terminal Market
Payments
North America Mobile Payments Market
Payments
Cyprus POS Terminals Market
Payments
Cloud Billing Market
Payments
In-Vehicle Payment Services Market
Payments
Qatar Payments Market
Payments
Japan Prepaid Cards Market
Payments
US Gift Card and Incentive Card Market
Payments
POS Terminals Market
Payments
US Virtual Cards Market
Payments
Romania POS Terminals Market
Payments
Global Telecom Billing Market
Payments
Transit Cards Market
Payments
Europe Prepaid Card Market
Payments
Global Bitcoin Payments Ecosystem Market
Payments
Saudi Arabia Cash Management Services Market