
 Singapore Gift Card and Incentive Card Market | 2026-2036
Singapore Gift Card and Incentive Card Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Gift Card and Incentive Card Market Outlook
Bundled corporate reward packages is shifting buyer choice away from standalone retail gift cards. NTUC FairPrice Co-operative Pte Ltd leverages its supermarket network to anchor physical card distribution across Singapore. Blackhawk Network competes through technology leadership in digital card infrastructure. Lazada Singapore extends its e-commerce platform to dominate online gift card redemption.
Gift cards and incentive cards are stored-value instruments preloaded with monetary value, typically encoded via magnetic stripe, chip, or tokenized digital credential, designed to facilitate purchases at designated merchants or merchant networks. These instruments serve commercial purposes spanning consumer gifting, employee recognition, customer loyalty programs, and promotional campaigns. Digital cards and e-gift cards represent the fastest-expanding product type as mobile wallet penetration deepens. Corporate clients constitute the highest-margin end user segment due to bulk contractual volumes and recurring incentive program renewals. Supermarkets and convenience stores remain the most mature distribution channel for physical card fulfillment.
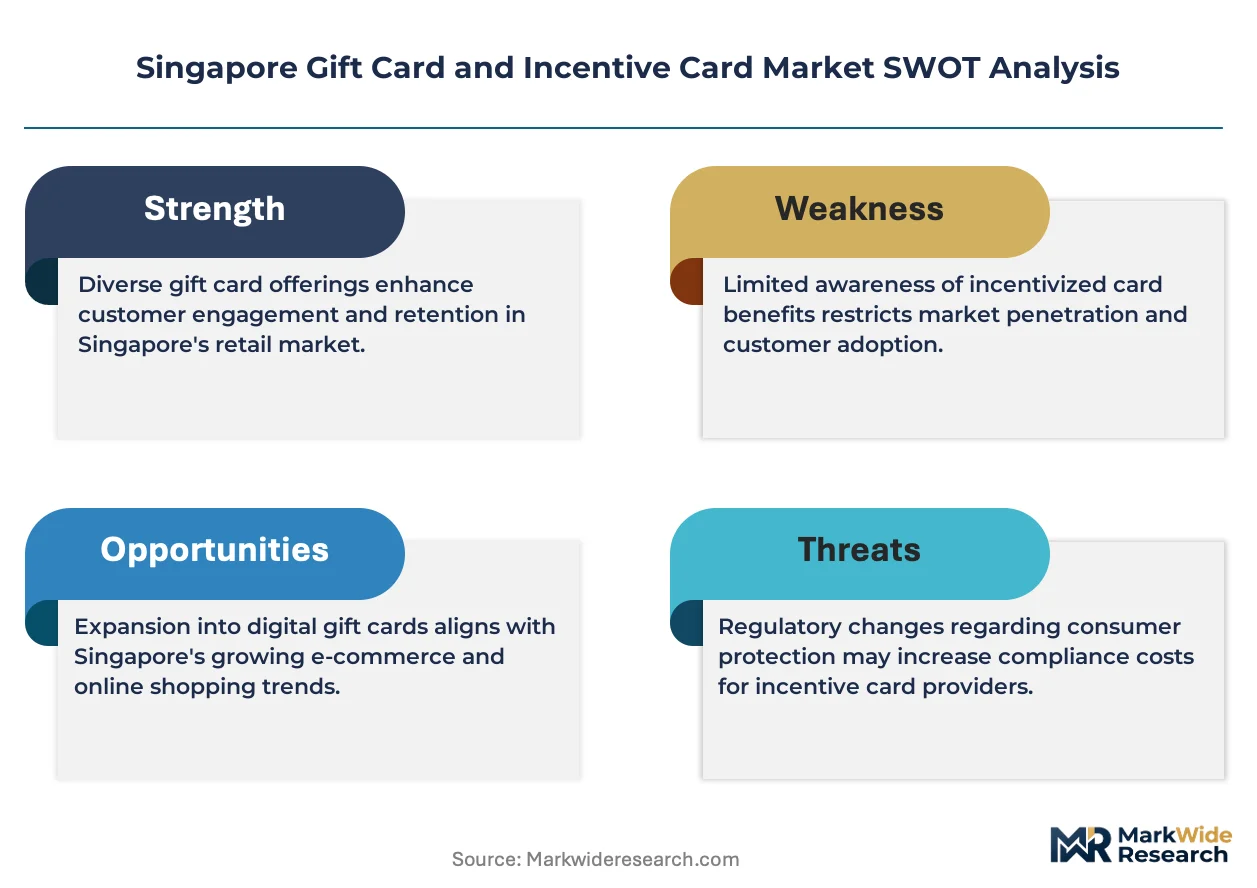
The Monetary Authority of Singapore regulates stored value facility issuers under the Payment Services Act, requiring capital adequacy and safeguarding arrangements that elevate barriers for new market entrants. Enterprise Singapore administers standards for consumer protection in promotional gift card offerings, shaping product disclosure and expiry term requirements. Stakeholders must monitor evolving digital payment token regulations and assess whether to pursue stored value facility licensing or partner with licensed issuers for program deployment.
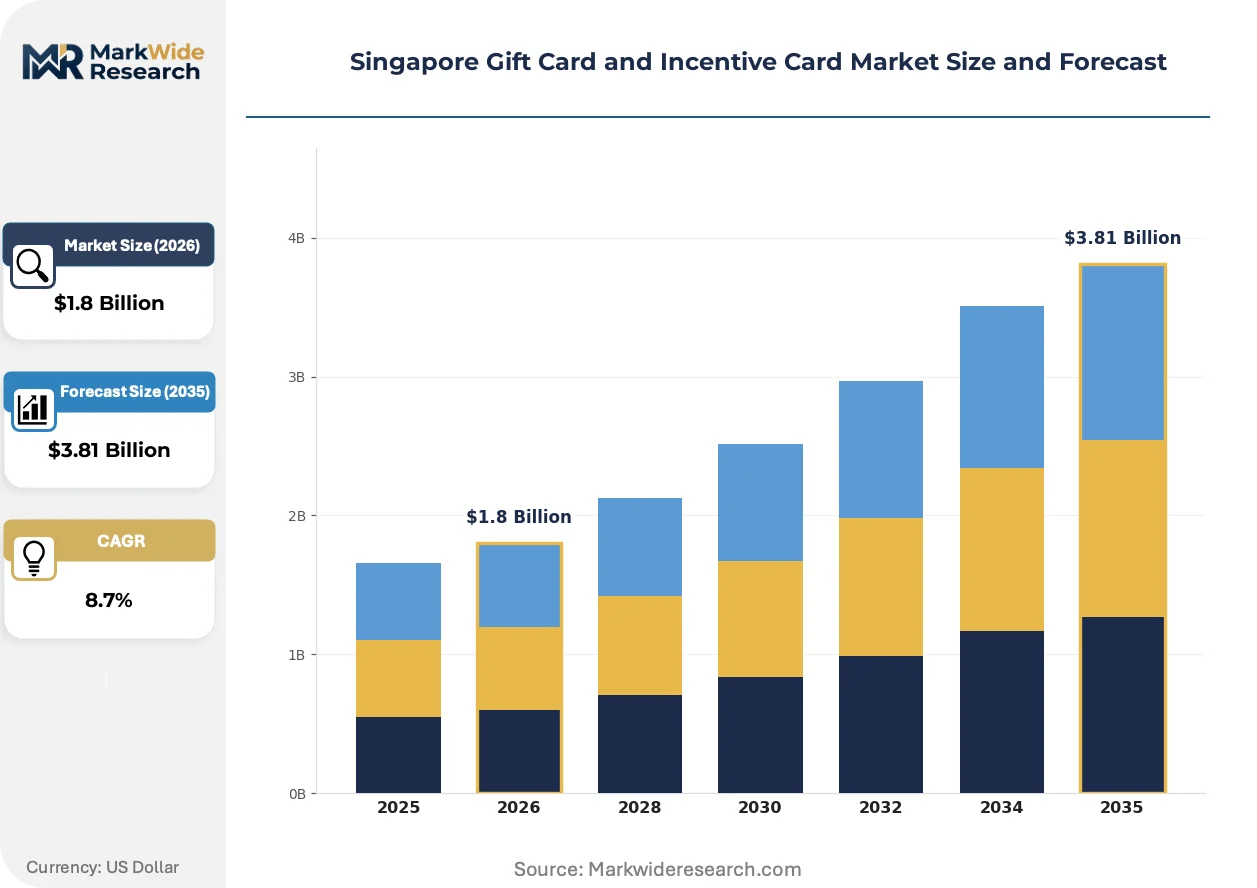
Market Dynamics
The Monetary Authority of Singapore's stored value facility framework is compressing issuer economics while digital wallet penetration accelerates platform consolidation among corporate buyers.
Growth Catalysts
- Payment Services Act compliance:The Monetary Authority of Singapore's capital adequacy requirements filter out undercapitalized competitors, strengthening licensed incumbents' pricing power.
- Corporate HR digitization:Enterprise incentive program managers are consolidating vendor relationships around API-enabled card platforms that integrate with payroll systems.
- Mobile wallet infrastructure:Tokenized digital credentials embedded in Apple Pay and Google Wallet are displacing physical card redemption at Singapore retail points of sale.
Market Restraints
- Safeguarding arrangement costs:The Monetary Authority of Singapore mandates segregated trust structures that elevate working capital requirements for stored value facility issuers.
- Supermarket channel concentration:NTUC FairPrice's dominance in physical card distribution limits shelf access for competing gift card programs.
- Platform substitution:Direct bank transfer incentives and payroll-integrated cashback programs are capturing share from standalone incentive card products.
Strategic Opportunities
- Jurong Lake District expansion:Singapore's second central business district development will concentrate new financial services and technology employers requiring employee reward infrastructure.
- Cross-border ASEAN redemption:Regional e-commerce platforms present white space for Singapore-issued digital cards valid across Malaysia, Indonesia, and Thailand merchant networks.
- Enterprise Singapore sustainability incentives:Government grants for green procurement are steering corporate buyers toward digital-first reward programs with carbon footprint disclosures.
Industry Challenges
- API integration complexity:Corporate IT departments face extended deployment timelines connecting legacy HRIS platforms to modern card management systems.
- Compliance talent scarcity:Shortage of professionals versed in both Payment Services Act requirements and enterprise software architecture limits program rollout velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Gift Card and Incentive Card Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Physical Card, Digital Card, e-Gift Card, Prepaid Card End User: Retail Customers, Corporate Clients, Small Businesses, Large Enterprises Distribution Channel: Online Retailers, Supermarkets, Convenience Stores, Direct Sales Usage Occasion: Holidays, Birthdays, Corporate Incentives, Promotions |
| Companies Covered | Takashimaya Co Ltd, Blackhawk Network, NTUC FairPrice Co-operative Pte Ltd, Giftbit, InComm, Dairy Farm International Holdings Ltd, Mustafa Holdings Pte Ltd, Lazada Singapore, Shen Siong Supermarket Pte Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Gift Card and Incentive Card Market Strategic Shifts
Tokenization and API-first architecture are compressing issuance costs while regulatory tightening around stored value facilities is elevating compliance automation investment across Singapore's gift card ecosystem.
Blockchain-based settlement rails are integrating with traditional stored value infrastructure to enable real-time cross-merchant reconciliation. Large employers in Singapore's Central Business District are piloting these systems for multi-brand corporate reward programs. The technology is integrating previously siloed issuer ledgers into unified clearing networks that reduce settlement latency from days to minutes.
The Monetary Authority of Singapore's 2024 guidance on digital payment token custody has triggered infrastructure upgrades among stored value facility licensees. Issuers must now demonstrate cold-wallet segregation and multi-signature controls for cryptocurrency-linked card products. Fintech card platforms serving speculative digital asset segments are absorbing the steepest compliance costs while pivoting toward stablecoin-denominated corporate incentive offerings.
Corporate procurement teams are consolidating vendor relationships around bundled reward platforms that combine gift cards, experiential benefits, and wellness allowances. HR departments previously managing separate point solutions are displacing standalone retail card contracts with integrated employee experience platforms. This concentration is most visible among Singapore's financial services and technology employers with workforces exceeding five hundred employees.
Singapore Gift Card and Incentive Card Market Segmentation
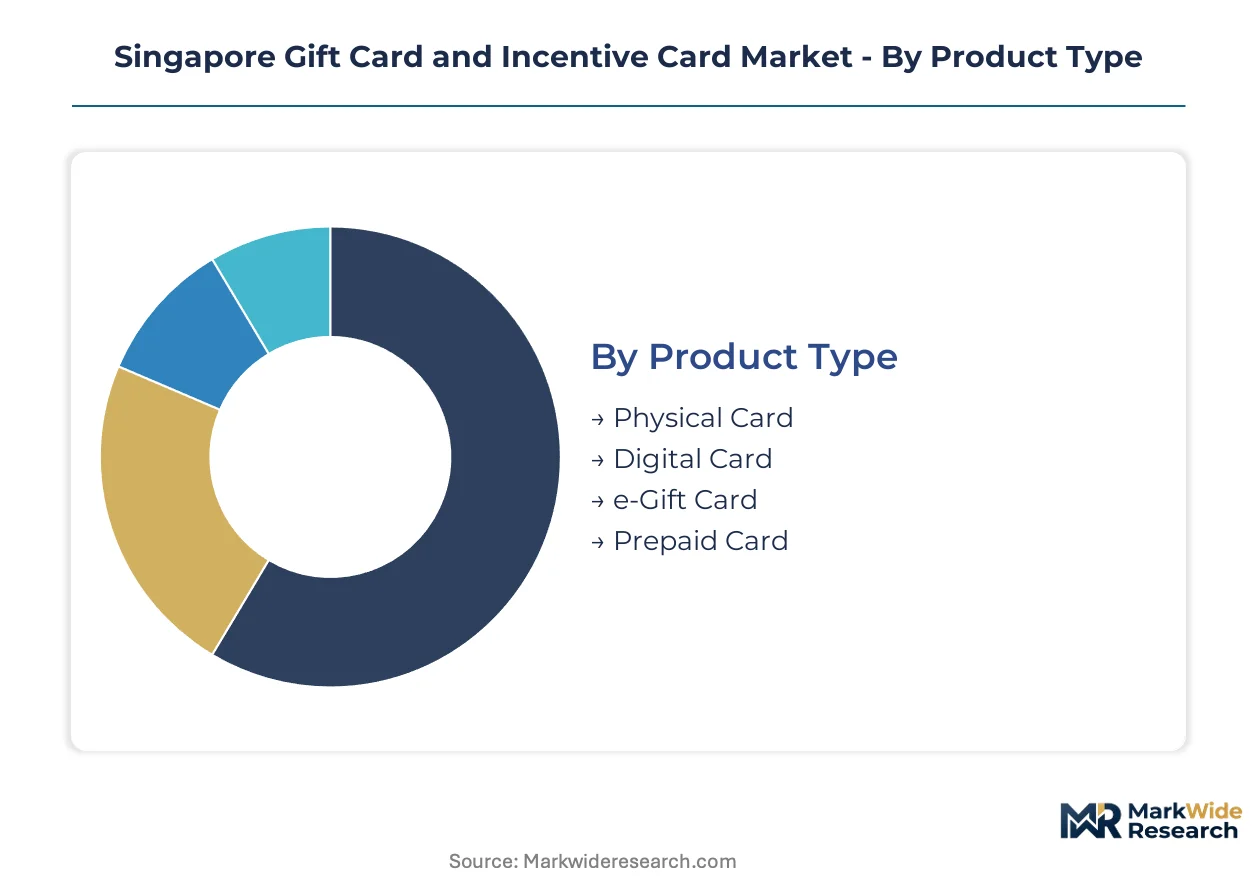
Segmentation in Singapore's gift card market reveals divergent capital requirements and margin profiles across issuance formats. Issuers must calibrate infrastructure investment against customer acquisition economics in each vertical.
Product Type:
Capital intensity varies sharply across issuance formats, with physical card production demanding manufacturing partnerships and inventory carrying costs while digital platforms require upfront API development and tokenization infrastructure.
- Physical Card:Magnetic stripe or chip-encoded plastic instruments produced through contracted card manufacturers. Demand concentrates among NTUC FairPrice's supermarket network shoppers seeking tangible gifting options; shelf space scarcity limits new entrant penetration.
- Digital Card:Tokenized credentials delivered via email or SMS with API-enabled redemption. Singapore's Central Business District financial employers are consolidating procurement around these platforms for employee reward integration with payroll systems.
- e-Gift Card:Platform-native instruments tied to specific merchant ecosystems like Lazada Singapore. Compact format suits last-minute gifting occasions with instant delivery.
- Prepaid Card:Reloadable stored value instruments regulated under Payment Services Act safeguarding requirements. Higher compliance burden elevates working capital needs for program operators.
Physical cards absorb the bulk of installed merchant acceptance infrastructure; digital cards are expanding most quickly as mobile wallet penetration deepens.
End User:
Customer lifetime value and contract renewal predictability separate segments, with institutional buyers offering multi-year commitments versus transactional retail purchasing.
- Retail Customers:Individual purchasers acquiring single cards for personal gifting. Occasional purchase frequency and price sensitivity compress margins for dedicated retail-focused programs.
- Corporate Clients:HR departments procuring bulk volumes for employee recognition and incentive programs. Recurring program renewals and API integration requirements create switching costs that entrench vendor relationships.
- Small Businesses:Owner-operated firms purchasing modest quantities for customer loyalty initiatives. Limited procurement sophistication favors off-the-shelf card solutions over customized platforms.
- Large Enterprises:Technology and financial services employers with workforces exceeding five hundred employees. These buyers demand bundled reward platforms combining cards with experiential benefits and wellness allowances.
Corporate clients generate the highest per-account revenue; large enterprises are climbing the fastest as HR digitization accelerates vendor consolidation.
Distribution Channel:
Channel economics reflect real estate costs and customer touchpoint density, with physical retail commanding premium placement fees while digital routes compete on acquisition spend efficiency.
- Online Retailers:E-commerce platforms and dedicated gift card marketplaces enabling instant purchase and delivery. Lazada Singapore dominates this channel through integrated checkout flows and redemption within its merchant ecosystem.
- Supermarkets:NTUC FairPrice's island-wide network anchors physical card distribution with high-frequency foot traffic. Limited shelf space and category management fees create barriers for competing programs.
- Convenience Stores:7-Eleven and Cheers outlets offering impulse purchase accessibility. Compact format suits low-denomination cards for immediate gifting needs.
- Direct Sales:B2B field teams and inside sales functions targeting corporate procurement departments. Relationship-driven channel with extended sales cycles but higher contract values.
Supermarkets retain the largest transaction volume base; online retailers are gaining share fastest as digital gifting occasions multiply.
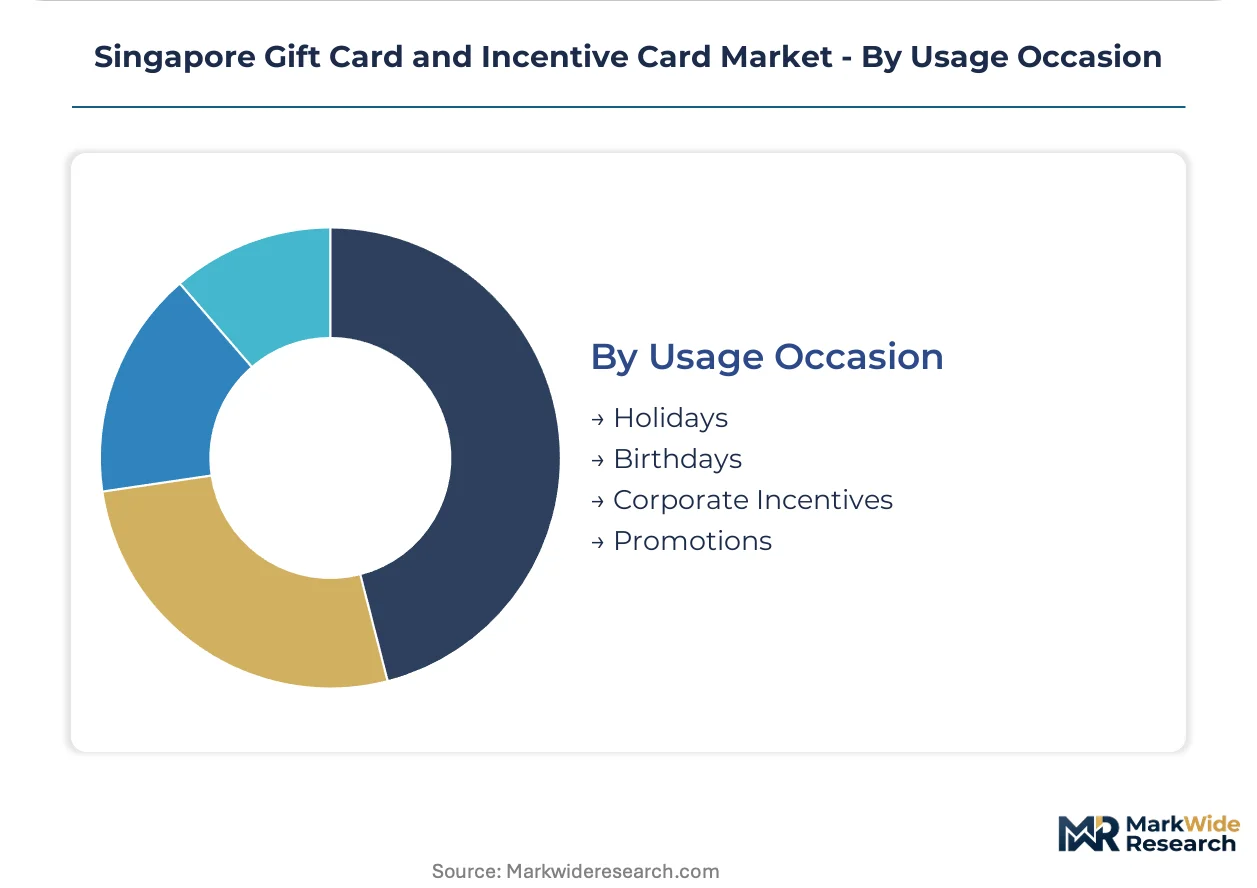
Usage Occasion:
Seasonal concentration and program cadence determine inventory planning and marketing calendar intensity across occasion types.
- Holidays:Lunar New Year, Christmas, and Hari Raya Puasa driving peak purchasing windows. Concentrated demand spikes strain fulfillment infrastructure and create temporary capacity constraints.
- Birthdays:Year-round personal gifting with lower individual transaction values but steadier demand flow. Digital delivery formats capture share through last-minute purchase convenience.
- Corporate Incentives:Scheduled quarterly and annual recognition programs with predictable procurement timelines. Enterprise buyers favor multi-brand card portfolios offering recipient choice.
- Promotions:Marketing campaign tie-ins and customer acquisition incentives with variable program durations. Short-term contracts and performance-based pricing compress issuer margins.
Holidays absorb the bulk of annual transaction volume; corporate incentives are expanding most quickly as employer reward program digitization advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jurong Lake District special economic zone concentrates Singapore's emerging financial services and technology employers, anchoring demand for enterprise-grade employee reward infrastructure across the island city-state.
Central Business District
Financial services and technology employers with workforces exceeding five hundred employees drive bulk procurement of digital incentive cards. The Monetary Authority of Singapore's Payment Services Act governs stored value facility issuers operating from this cluster. Marina Bay and Raffles Place house the headquarters of multinational banks piloting blockchain-based settlement rails for multi-brand corporate reward programs.
Jurong Lake District
Singapore's second central business district development is concentrating new financial services and technology employers requiring employee reward infrastructure. Enterprise Singapore administers standards for consumer protection in promotional gift card offerings across this zone. The district's mixed-use development is attracting regional headquarters of ASEAN e-commerce platforms exploring cross-border digital card redemption networks.
Orchard Road Retail Corridor
Department stores and luxury retailers anchor physical gift card distribution for tourist and affluent local segments. Takashimaya Co Ltd leverages its flagship presence to capture premium gifting occasions in this precinct. Ion Orchard and Ngee Ann City maintain high-frequency foot traffic supporting impulse card purchases.
Heartland Town Centres
NTUC FairPrice's island-wide supermarket network penetrates residential estates for mass-market physical card fulfillment. The co-operative's category management fees and limited shelf space create barriers for competing gift card programs. Tampines, Jurong East, and Woodlands regional centres concentrate family-oriented gifting demand.
Tuas Industrial Zone
Advanced manufacturing and logistics employers are emerging as new corporate incentive card buyers as the zone expands. The Monetary Authority of Singapore's safeguarding arrangement requirements elevate working capital needs for issuers serving this segment. Jurong Port and the upcoming Tuas Mega Port are concentrating maritime and supply chain employers with distributed workforces requiring digital-first reward delivery.
Singapore Gift Card and Incentive Card Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Singapore's gift card and incentive card market. The competitive structure tilts toward platform consolidation as mobile wallet penetration deepens and corporate HR departments consolidate vendor relationships. Three archetypes dominate: supermarket-anchored physical distributors, technology-led digital infrastructure providers, and e-commerce platform-integrated issuers. M&A activity concentrates on API-enabled card platforms, while strategic partnerships with licensed stored value facility holders accelerate program deployment.
Among Singapore-based retail-anchored distributors, NTUC FairPrice Co-operative Pte Ltd and Shen Siong Supermarket Pte Ltd exemplify the supermarket-channel archetype. Blackhawk Network occupies a position representing technology-led digital infrastructure specialization. Lazada Singapore anchors the e-commerce platform-integrated tier, extending its merchant ecosystem to dominate online gift card redemption.
| Leading Market Players |
|---|
| Takashimaya Co Ltd |
| Blackhawk Network |
| NTUC FairPrice Co-operative Pte Ltd |
| Giftbit |
| InComm |
| Dairy Farm International Holdings Ltd |
| Mustafa Holdings Pte Ltd |
| Lazada Singapore |
| Shen Siong Supermarket Pte Ltd |
| Others |
Value Chain & Pricing Dynamics
Corporate HR digitization toward API-enabled reward platforms is compressing margins for standalone card issuers while elevating premiums for integrated infrastructure providers. The Monetary Authority of Singapore's safeguarding requirements force working capital restructuring that filters through to program pricing tiers.
Pricing Analysis
Short lead-time premiums dominate enterprise procurement, with same-day digital credential deployment commanding 15-25% markups over standard fulfillment windows. Three-tier pricing structure across premium API-integrated, standard digital delivery, and economy physical card levels segments buyer willingness to pay. Cost compression in the physical card tier is intensifying because NTUC FairPrice's shelf-space scarcity limits new entrant distribution. Small businesses exhibit highest price sensitivity, while large enterprises prioritize integration reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from corporate procurement teams require issuers to maintain relationships with at least two licensed stored value facility operators. Card manufacturing draws from China, South Korea, and domestic Singapore converters for magnetic stripe and chip encoding substrates. Single-source vulnerability concentrates in tokenization infrastructure providers serving mobile wallet integration. Distribution runs through NTUC FairPrice's supermarket network for physical fulfillment, with direct sales teams capturing enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as platform providers pursue captive control over stored value facility licensing to bypass third-party compliance costs and capture margin stack.
For Market Incumbents: Extend API-first architecture investments to deepen payroll system integration and entrench corporate client relationships. Secure Payment Services Act license maintenance through compliance automation that emerging fintechs cannot replicate. Threat substitution from direct bank transfer incentives demands preemptive bundling with experiential benefits to preserve switching costs. For New Entrants and Emerging Players: Launch via white-label partnerships with licensed stored value facility holders to bypass capital adequacy barriers. The Jurong Lake District expansion presents the most penetrable geography, with new financial services employers lacking entrenched vendor relationships. Target small business loyalty programs with off-the-shelf digital card solutions before scaling to enterprise API integration. For Investors and Strategic Acquirers: The window for entry favors API-enabled card platforms with existing corporate client rosters and demonstrated Payment Services Act compliance. Long-term viability hinges on consolidation into bundled employee experience platforms rather than standalone card products. Watch for Monetary Authority of Singapore guidance on stablecoin-linked incentives as the signal for next-generation infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Deepens HRIS integration with payroll systems at Singapore's Central Business District employers. |
| Stored Value Facility Licensing | Captures compliance margin stack and eliminates third-party issuer dependency. |
| Cross-Border ASEAN Partnership | Enables redemption across Malaysia, Indonesia, and Thailand merchant networks. |
| Blockchain Settlement Integration | Reduces multi-brand corporate reward reconciliation latency through unified clearing rails. |
| Sustainability Disclosure Program | Aligns with Enterprise Singapore green procurement grants steering corporate buyer preference. |
Study Parameters
Multi-period observation of stored value facility licensing trends, mobile wallet penetration rates, and corporate procurement consolidation anchored the trend analysis, supplemented by interviews with payment services compliance officers, HR technology procurement managers, supermarket category buyers, digital card platform engineers, and incentive program administrators. Secondary validation drew from Monetary Authority of Singapore regulatory circulars, Enterprise Singapore consumer protection standards, Payment Services Act filings, and e-commerce platform transaction disclosures. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates.
Input-output matrices mapped credential issuance volumes against merchant acceptance infrastructure expansion, corporate headcount growth in financial services, and mobile wallet adoption curves across the projection horizon. Segmentation dimensions included product format, end-user organization size, distribution channel density, and usage occasion seasonality. CAGRs derived from regression analysis of historical issuance growth against explanatory variables including employment growth in target sectors and digital payment penetration rates.
Regulatory enforcement intensity shifts, corporate incentive program budget reallocations, and mobile wallet platform strategy pivots are the dominant revision risks to the outlook. Deviation in Monetary Authority of Singapore stablecoin custody guidance timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
South Korea Payments Market
Payments
Global Smart Payment Systems Market
Payments
Spain Real Time Payments Market
Payments
China Forex Cards Market
Payments
Canada Prepaid Cards Market
Payments
Asia Pacific Buy Now Pay Later Service Market
Payments
Saudi Arabia Payments Market
Payments
Asia-Pacific Payment Gateway Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Greece POS Terminals Market
Payments
Dual Interface Payment Card Market
Payments
Belgium Payments Market
Payments
Vietnam Payments Market
Payments
Global Mobile Payment Technology Market
Payments
Spain Payment Gateway Market
Payments
Mobile Wallet Market