
 Norway POS Terminals Market | 2026-2036
Norway POS Terminals Market Size, Share, and Industry Trends Forecast 2026-2036
Norway POS Terminals Market Analytics
Reseller networks in Norway is tilting toward direct-to-merchant software bundling as terminal vendors bypass traditional distribution tiers. Verifone Systems leverages its Nordic service footprint to sustain long-term leasing contracts with national grocery operators. PAX Technology competes on hardware modularity, allowing Norwegian merchants to swap connectivity modules without full device replacement.
Norway POS terminals comprise electronic payment acceptance devices equipped with secure element chips, NFC antennas, and EMV-certified pin entry pads, engineered to authenticate card-present transactions through encrypted data exchanges with acquiring banks. Mobile terminals lead hardware shipments among Norwegian small merchants seeking countertop flexibility without fixed infrastructure commitments. Cloud-based deployment models are capturing disproportionate growth in hospitality chains requiring centralized terminal management across distributed Oslo, Bergen, and Trondheim locations.
Finanstilsynet, Norway's financial supervisory authority, enforces PSD2-compliant strong customer authentication standards that mandate biometric-ready terminal specifications for transactions exceeding defined thresholds. Norges Bank's oversight of the national payment system shapes hardware certification timelines, creating compliance windows that synchronize merchant upgrade cycles. Stakeholders must monitor whether upcoming central bank digital currency pilots will require firmware-level terminal modifications that alter current replacement schedules.
Market Dynamics
Norges Bank's contactless infrastructure mandates have compressed hardware replacement cycles across Norwegian retail, forcing merchants to accelerate terminal refresh programs ahead of regulatory deadlines.
Growth Catalysts
- PSD2 Strong Authentication:Finanstilsynet's biometric-ready terminal specifications for high-value transactions mandate hardware upgrades across hospitality and grocery sectors.
- Cloud Terminal Management:Hospitality chains in Oslo, Bergen, and Trondheim are adopting centralized device management platforms to reduce distributed infrastructure overhead.
- Mobile Form Factor Preference:Norwegian small merchants favor countertop-flexible terminals that eliminate fixed infrastructure commitments in urban retail corridors.
Market Restraints
- Certification Timeline Compression:Norges Bank's synchronized compliance windows create concentrated upgrade demands that strain manufacturing capacity and logistics networks.
- Hardware Modularity Trade-offs:Connectivity module swapping capabilities introduce firmware complexity that extends testing protocols and delays market entry.
- Leasing Contract Lock-in:Long-term terminal leasing agreements with national grocery operators reduce competitive switching and suppress hardware refresh velocity.
Strategic Opportunities
- Central Bank Digital Currency Pilots:Potential Norges Bank CBDC initiatives may require firmware-level terminal modifications, creating preemptive upgrade demand.
- Direct-to-Merchant Software Bundling:Terminal vendors bypassing traditional reseller tiers can capture margin expansion through integrated payment application stacks.
- NFC Antenna Performance Differentiation:Enhanced contactless range and reliability specifications offer hardware vendors technical segmentation against modular competitors.
Industry Challenges
- EMV Certification Backlogs:Pin entry pad and secure element chip testing queues at accredited laboratories extend product launch timelines for new terminal introductions.
- Legacy System Integration:Merchants operating mixed terminal fleets face operational complexity reconciling cloud-managed devices with on-premise estate management tools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway POS Terminals Market |
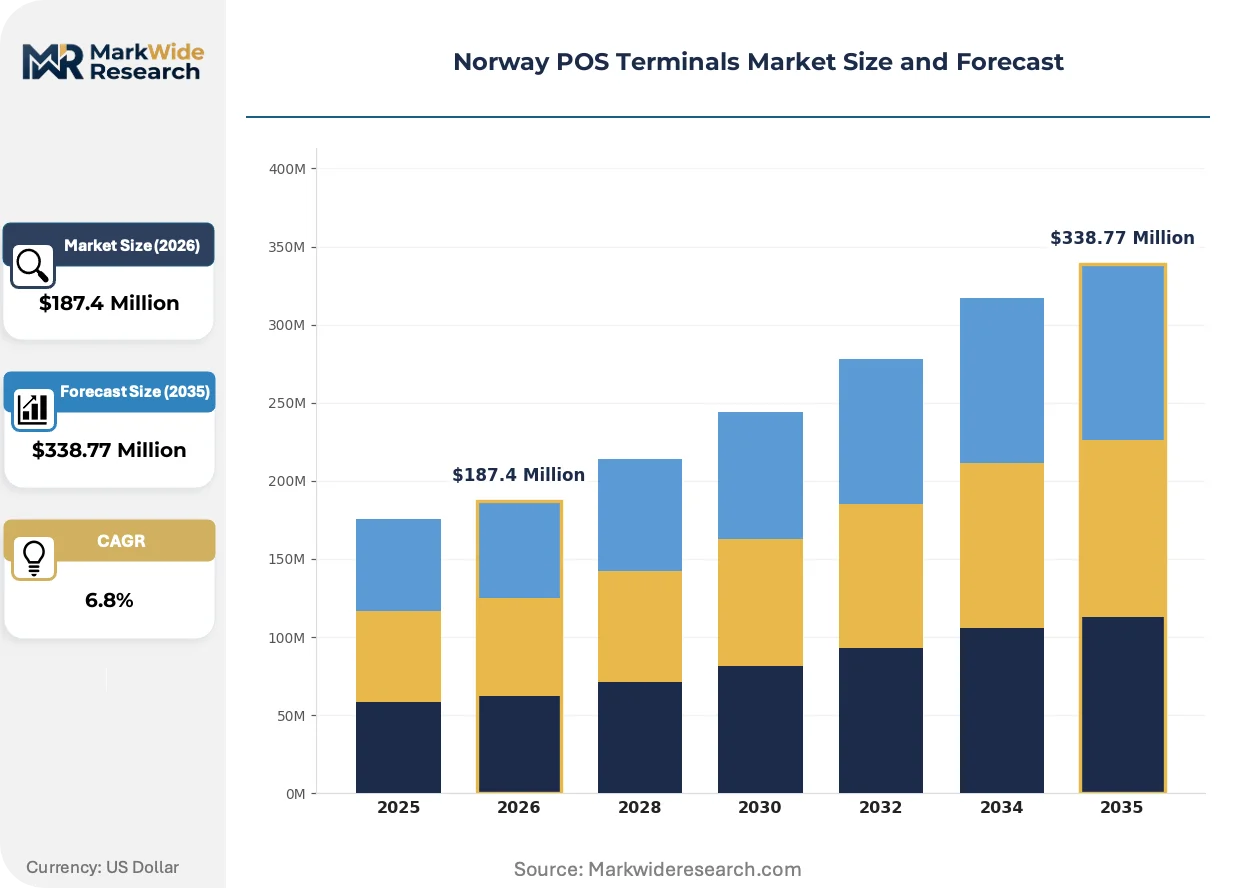
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
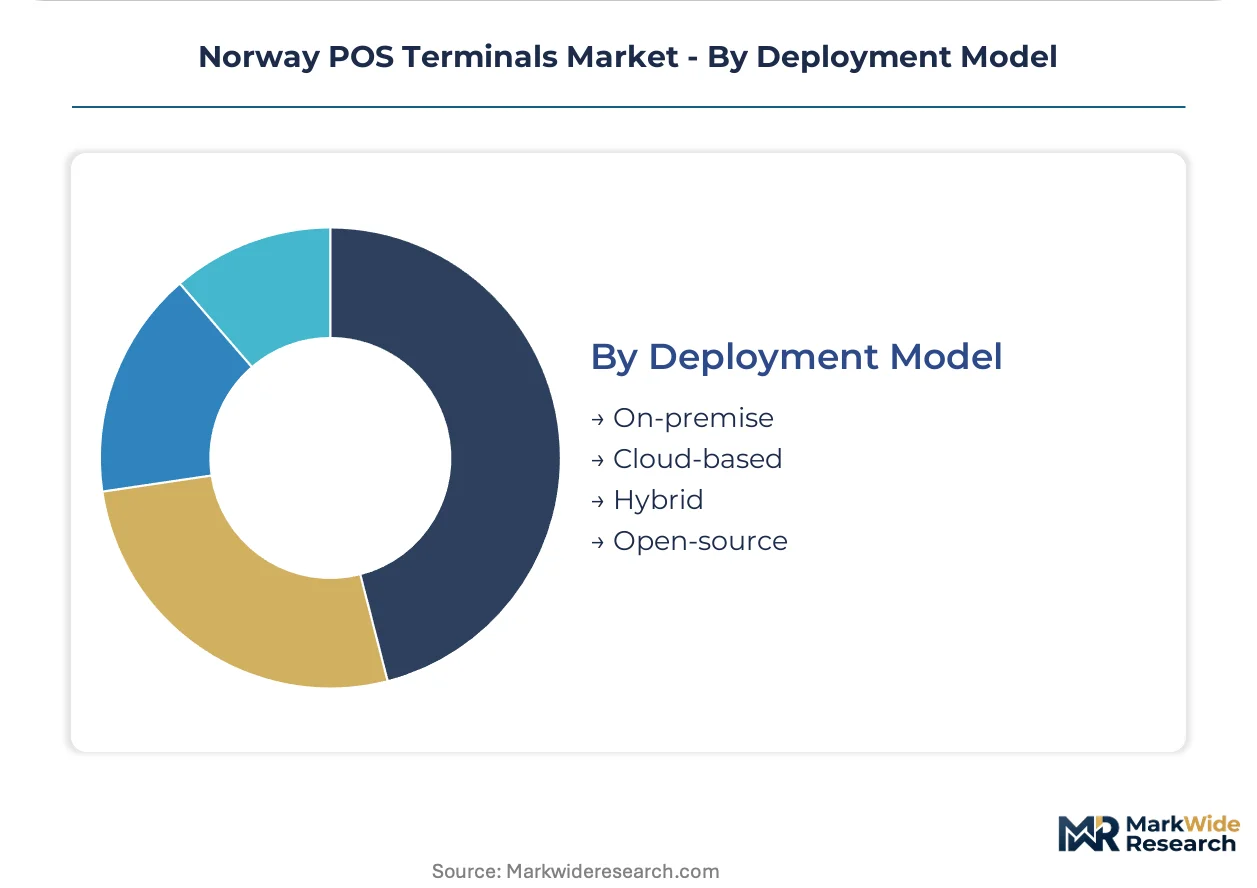
| Segmentation | Product Type: Mobile Terminals, Countertop Terminals, Integrated Terminals, Multi-functional Terminals Technology: Contactless, Chip and Pin, Magnetic Stripe, Bluetooth End User: Retail, Hospitality, Healthcare, Transportation Deployment Model: On-premise, Cloud-based, Hybrid, Open-source |
| Companies Covered | NETS Pte Ltd, PAX Technology, Verifone Systems, Front Systems, Nayax, Ingenico Group, Zettle, Spire Payments, NCR Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway POS Terminals Market Evolving Landscape
Terminal virtualization and software-defined payment acceptance are restructuring how Norwegian merchants deploy and manage point-of-sale infrastructure across distributed locations.
SoftPOS technology is virtualizing payment acceptance onto standard smartphones and tablets without dedicated hardware. Norwegian micro-merchants and pop-up retailers are adopting this capability fastest, eliminating countertop device costs. The technology is virtualizing the traditional terminal market by collapsing the distinction between merchant-owned devices and consumer payment instruments.
Finanstilsynet's enforcement of biometric authentication thresholds is mandating terminal hardware refreshes ahead of previous depreciation schedules. Norwegian hospitality operators face the steepest compliance burden as transaction values routinely exceed authentication triggers. Hardware vendors are pre-certifying fingerprint and facial recognition modules to capture this mandated replacement demand.
Merchant acquisition patterns are consolidating around integrated software-hardware bundles that embed payment acceptance into vertical-specific applications. Norwegian grocery and fuel retail chains are displacing standalone terminal procurement with platform contracts bundling device, software, and transaction processing. This bundling concentrates vendor relationships and reduces price transparency for merchant buyers.
Norway POS Terminals Market Segmentation

Hardware form factors and connectivity specifications shape procurement patterns across Norwegian retail corridors. Terminal segmentation reveals how Norges Bank's infrastructure mandates synchronize upgrade cycles across merchant tiers with divergent technical requirements.
Product Type:
Cost tier differentiation separates fixed infrastructure investments from flexible countertop solutions across Oslo's urban retail corridor.
- Mobile Terminals:Battery-powered units with integrated receipt printers and cellular connectivity modules enable transaction acceptance without fixed line dependencies. Norwegian small merchants in Bergen and Trondheim favor these for pop-up retail and seasonal market operations where infrastructure permanence is uneconomical. Demand concentrates among hospitality operators requiring tableside payment flexibility.
- Countertop Terminals:Stationary devices with ethernet and WiFi connectivity anchor fixed-location checkout infrastructure. Oslo grocery chains and fuel retailers deploy these for high-throughput environments where transaction speed determines queue length. Norges Bank's contactless mandates are accelerating refresh programs for legacy countertop estates.
- Integrated Terminals:Units combining payment acceptance with barcode scanning and customer-facing displays streamline single-device checkout workflows.
- Multi-functional Terminals:Hardware supporting payment, loyalty program management, and digital receipt delivery reduces countertop device proliferation.
Countertop terminals hold installed capacity. Mobile terminals are rotating up the share rankings.
Technology:
Authentication protocols determine hardware certification requirements under Finanstilsynet's PSD2 enforcement framework.
- Contactless:NFC antenna configurations enabling tap-to-pay transactions dominate new terminal shipments following Norges Bank's infrastructure mandates. Norwegian hospitality chains prioritize enhanced read range specifications to reduce transaction friction during peak service periods. Oslo retailers face compressed upgrade timelines as legacy magnetic stripe capabilities sunset.
- Chip and Pin:EMV-certified secure element chips with pin entry pads remain mandatory for transactions exceeding biometric authentication thresholds. Healthcare providers and high-value retail segments require these specifications for compliance with Finanstilsynet's strong customer authentication standards.
- Magnetic Stripe:Legacy swipe compatibility persists in merchant fleets serving international tourists with non-EMV cards.
- Bluetooth:Short-range wireless pairing enables tablet-based SoftPOS configurations for micro-merchants.
Chip and pin holds installed capacity. Contactless is climbing the fastest.
End User:
Application-specific transaction patterns drive divergent terminal specifications across Norwegian commercial sectors.
- Retail:Grocery and specialty merchants require high-throughput terminals with durable pin pads and rapid contactless read cycles. Oslo's urban retail corridor concentrates demand for cloud-managed device fleets enabling centralized estate oversight across distributed locations.
- Hospitality:Restaurants and hotels prioritize mobile form factors and tableside payment capabilities to reduce checkout friction. Bergen hospitality operators face steepest compliance burdens as average transaction values routinely trigger Finanstilsynet's biometric authentication thresholds.
- Healthcare:Clinics and pharmacies require terminals with integrated health insurance card readers and privacy-enhanced pin entry.
- Transportation:Transit operators demand ruggedized terminals with rapid transaction processing for high-volume fare collection.
Retail holds installed capacity. Hospitality is gaining share fastest.
Deployment Model:
Customer type and operational scale determine infrastructure control preferences across Norwegian merchant tiers.
- Cloud-based:Centralized terminal management platforms enable remote configuration, software updates, and transaction monitoring across distributed locations. Trondheim hospitality chains and multi-site retailers adopt these to reduce on-premise infrastructure overhead and accelerate compliance rollout.
- On-premise:Local server dependencies persist among merchants with legacy estate management tools and data residency requirements. National grocery operators with established IT infrastructure favor hybrid approaches preserving on-premise control for core systems.
- Hybrid:Mixed architectures balance local transaction processing with cloud-based reporting and device management.
- Open-source:Customizable firmware stacks attract technically sophisticated merchants seeking payment application differentiation.
On-premise holds installed capacity. Cloud-based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norges Bank's contactless infrastructure mandates synchronize terminal replacement cycles across Norwegian sub-regions, compressing upgrade timelines for merchants in urban corridors and peripheral municipalities alike.
Oslo and Akershus
Finanstilsynet's PSD2 enforcement concentrates compliance burdens on high-transaction-value hospitality operators along Karl Johans gate and Aker Brygge. Cloud-based terminal management platforms capture disproportionate share among multi-site retailers headquartered in Oslo's financial district. National grocery chains anchor hardware refresh programs in this corridor.
Bergen and Vestland
Maritime tourism and fjord cruise operations drive seasonal demand spikes for mobile payment terminals at Bergen harbor retail clusters. Seafood export merchants require terminals with integrated foreign currency handling and robust cellular connectivity for remote processing. The city's hospitality sector faces steepest biometric authentication thresholds under Finanstilsynet rules.
Trondheim and Trøndelag
University-city retail patterns favor countertop-flexible terminals serving student populations and academic conference traffic. Technology transfer from NTNU research clusters supports local pilot programs for SoftPOS deployment among micro-merchants. Regional hospital networks mandate chip-and-pin specifications for health insurance card integration.
Stavanger and Rogaland
Energy sector service companies drive corporate procurement of ruggedized terminals for offshore supply base operations. Oil industry expense account transactions routinely trigger high-value authentication requirements. Stavanger's airport retail corridor concentrates contactless infrastructure investment ahead of Norges Bank deadlines.
Tromsø and Northern Norway
Sparse population density and seasonal tourism create infrastructure challenges that favor modular terminal hardware with field-swappable connectivity modules. Sami cultural tourism operators adopt mobile form factors for reindeer herding experience payments. Arctic logistics constraints extend delivery timelines for certification-compliant hardware.
Norway POS Terminals Market Competitive Landscape
On the supply side, the industry is consolidating around integrated software-hardware bundles that displace standalone terminal procurement. Vendor relationships concentrate among Nordic service specialists and global hardware platforms with regional certification capabilities. Two strategic archetypes dominate: leasing-heavy incumbents with long-term grocery contracts, and modular hardware specialists enabling connectivity field upgrades. Competitive moves center on direct-to-merchant software bundling and bypassing traditional reseller distribution tiers.
Among Nordic-rooted payment infrastructure providers, NETS Pte Ltd and Front Systems occupy positions within the integrated solutions tier, while Verifone Systems anchors the leasing-contract incumbent archetype. These companies exemplify divergent approaches to merchant acquisition—platform bundling versus hardware-centric long-term agreements.
| Leading Market Players |
|---|
| NETS Pte Ltd |
| PAX Technology |
| Verifone Systems |
| Front Systems |
| Nayax |
| Ingenico Group |
| Zettle |
| Spire Payments |
| NCR Corporation |
| Others |
Value Network & Pricing Analysis
Secure element chip fabrication concentrates in Taiwan and South Korea, concentrating margin capture upstream while Norwegian terminal vendors compete on software bundling and service attach rates downstream. This upstream concentration forces downstream players to differentiate through integrated payment application stacks rather than hardware cost leadership.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts for national grocery operators, with three-tier pricing stratification across premium biometric-ready terminals, standard contactless units, and economy-grade legacy replacements. Price differentiation rests on EMV certification grade and after-sales service bundling, with Finanstilsynet's authentication mandates compressing margins on standard-tier hardware. Cost compression in the economy tier is intensifying as Chinese modular suppliers expand Nordic distribution. Small hospitality merchants in Bergen and Trondheim exhibit highest price sensitivity, while Oslo-based grocery chains prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Export-control regimes on advanced semiconductor manufacturing equipment limit secure element chip flows from Taiwan to non-allied jurisdictions, constraining terminal vendors' sourcing flexibility. Supply chains draw from China for PCB assembly, Taiwan for secure element chips, and Vietnam for peripheral component manufacturing. Single-source vulnerability concentrates in NFC antenna substrate suppliers serving European certification requirements. Distribution runs through direct-to-merchant software bundling channels that bypass traditional Nordic reseller networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's POS terminal market is approaching a platform-economics inflection as SoftPOS virtualization collapses the boundary between merchant devices and consumer instruments, with interoperability mandates from Norges Bank accelerating ecosystem consolidation.
For Market Incumbents: Build switching-cost moats through long-term cloud management platform contracts that embed estate management tools into merchant operational workflows. Verifone-style leasing structures with national grocery operators should expand to include predictive maintenance analytics, while biometric module pre-certification investments capture Finanstilsynet-mandated replacement cycles ahead of modular competitors. For New Entrants and Emerging Players: Micro-merchants in Trondheim's university district and seasonal tourism operators in Tromsø represent the most penetrable entry points, with SoftPOS-enabled tablet configurations bypassing hardware certification backlogs entirely. Direct-to-merchant software bundling through vertical-specific hospitality applications offers the cleanest go-to-market angle against incumbent leasing networks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Nordic payment infrastructure platforms holding integrated software-hardware contracts but lacking cloud-native terminal management capabilities. Long-term viability hinges on firmware-level adaptability for potential Norges Bank CBDC pilots, with the signal to watch being central bank digital currency pilot announcements that would trigger preemptive merchant upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Terminal Management Platform | Centralized estate oversight reduces distributed infrastructure overhead for Oslo hospitality chains. |
| Biometric Module Pre-Certification | Finanstilsynet's authentication mandates create captive demand for fingerprint-ready hardware specifications. |
| Direct-to-Merchant Software Bundling | Bypassing Nordic reseller tiers captures margin expansion through integrated payment application stacks. |
| SoftPOS Technology Deployment | Virtualized acceptance eliminates countertop hardware costs for Bergen micro-merchants and pop-up retailers. |
| Modular Connectivity Field Upgrades | PAX-style hardware modularity extends device lifecycles without full replacement in Arctic logistics-constrained regions. |
Research Methodology
Cross-validation between terminal vendor shipment disclosures and Norges Bank payment system statistics anchors the qualitative findings on replacement cycle compression. Primary interviews with merchant acquisition executives at Nordic payment platforms, compliance officers at Finanstilsynet-regulated entities, and procurement leads at national grocery chains combined with secondary validation from EMVCo certification databases, customs import records, and central bank payment system reports. Bottom-up terminal deployment estimates triangulate against top-down acquiring bank transaction volume data.
Calibration against historical replacement cycles and regulatory compliance windows shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include hardware form factor, authentication technology, end-use sector, and deployment architecture, with cloud-adoption curves and biometric authentication thresholds as industry-specific forecast inputs. CAGRs derive from regression analysis of terminal refresh patterns against regulatory deadline clustering.
Practitioners should monitor Norges Bank CBDC pilot announcements, Finanstilsynet authentication threshold adjustments, and EMV certification laboratory capacity constraints for early signals that would revise deployment assumptions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
UAE POS Terminal Market
Payments
United States Payment Gateways Market
Payments
Global Financial Cards and Payments Market
Payments
Japan Credit Cards Market
Payments
Mobile Card Reader Market
Payments
Digital Remittance Service Market
Payments
Digital Money Transfer Market
Payments
Digital Debit Market
Payments
Singapore Payments Market
Payments
Philippines Remittance Market
Payments
MENA Digital Payments Market
Payments
Direct Carrier Billing Platform Market
Payments
Global Virtual Cards Market
Payments
Spain Payments Market
Payments
Global Accounts Payable Automation Market
Payments
Payment Security Software Market