
 Germany Payments Market | 2026-2036
Germany Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Payments Market Foresight
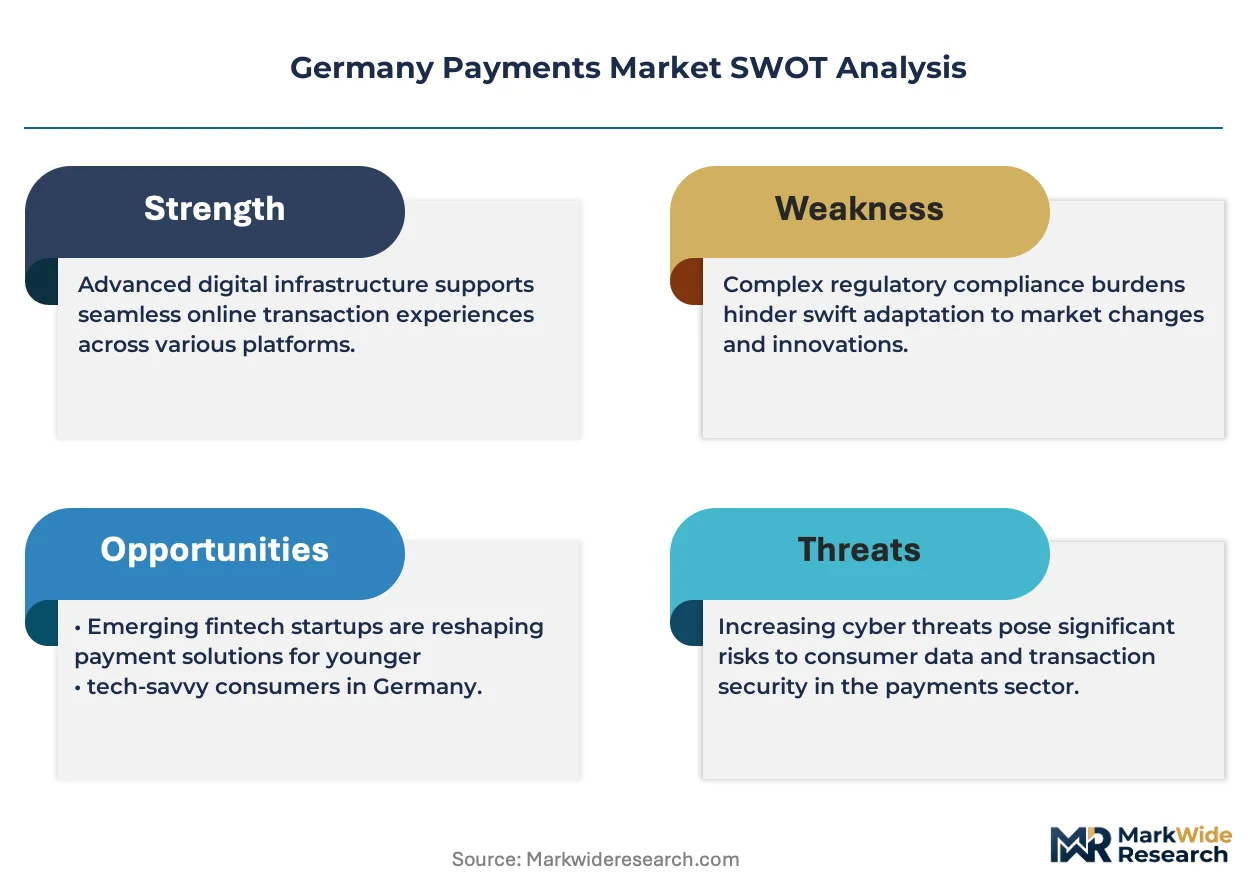
PSD2 Strong Customer Authentication is shifting the cost-of-entry calculus for new payment service providers entering Germany. Visa Inc sustains dominant network infrastructure across German acquiring banks. Mastercard Inc competes through tokenization partnerships with domestic issuers. Paydirekt GmbH anchors merchant loyalty via its bank-backed consortium model.
Germany Payments encompasses electronic fund transfer systems, card networks, and digital settlement rails that process consumer and commercial transactions through encrypted authorization protocols. NFC-enabled point-of-sale terminals and EMV chip authentication form the technical backbone, enabling sub-second transaction verification for retail and transit applications. Mobile Wallets and Bank Transfers lead transaction volume, with Mobile Wallets capturing disproportionate growth in transit and quick-service retail. NFC and Tokenization technologies concentrate margin pools, as biometric-integrated authentication commands premium interchange rates from high-risk merchants.
BaFin supervises payment institutions under the German Payment Services Supervision Act, while the ECB coordinates euro-denominated settlement policy across German TARGET2 participants. The EU AI Act introduces algorithmic audit requirements for fraud-scoring engines deployed by German issuers. Stakeholders must decide whether to build in-house biometric stacks or license modular authentication from specialized vendors before regulatory deadlines harden compliance costs.
Market Dynamics
PSD2 Strong Customer Authentication mandates from the European Banking Authority are forcing German issuers to rebuild authentication stacks before hard compliance deadlines. This regulatory compression is redistributing margin pools toward biometric-integrated verification vendors and away from legacy password-based systems.
Growth Catalysts
- Contactless Infrastructure Mandates:Berlin's transit authority and Hamburg's port logistics operators are deploying NFC-enabled terminals across municipal transport networks. This creates captive demand for tap-to-pay credential provisioning.
- PSD2 Regulatory Compliance:The European Banking Authority's authentication requirements are compelling German banks to upgrade authorization protocols. Issuers must deploy SCA-compliant flows for all remote electronic payments.
- Merchant Acquiring Consolidation:Hamburg's merchant acquiring hub is attracting processor investments focused on quick-service retail and fuel station verticals. Sub-second settlement rails are becoming table stakes for merchant retention.
Market Restraints
- Interchange Rate Compression:Domestic debit scheme pricing pressure from Paydirekt GmbH is compressing acquirer margins. Merchant lobbying for reduced card acceptance costs is forcing network fee renegotiations.
- Biometric Stack Capital Intensity:In-house development of fingerprint and facial recognition authentication requires substantial R&D expenditure. Mid-tier issuers face build-versus-license dilemmas with constrained IT budgets.
- Legacy Core Banking Integration:Decades-old host systems at regional German banks resist API-native payment architectures. Middleware complexity extends deployment timelines for real-time payment rails.
Strategic Opportunities
- EU AI Act Algorithmic Audits:Fraud-scoring engine vendors can capture compliance services revenue from German issuers facing mandatory algorithmic transparency requirements. Audit tooling represents an adjacent services expansion.
- Berlin Fintech Corridor Talent Density:The capital's concentrated developer pool enables rapid prototyping of embedded finance products. Neobank partnerships offer white-label payment infrastructure to non-financial brands.
- Tokenization-Transit Convergence:Deutsche Bahn and municipal transport operators are piloting credentialized mobile ticketing. Transit authorities seek to reduce cash handling costs through closed-loop digital wallets.
Industry Challenges
- SCA Friction-Abandonment Tradeoffs:German e-commerce merchants report elevated cart abandonment during stepped-up authentication flows. Balancing fraud reduction against checkout completion rates requires continuous A/B testing of challenge pathways.
- Real-Time Payment Scheme Interoperability:TARGET2 instant settlement integration with domestic retail payment systems demands complex message format mapping. Technical standardization lags between ECB infrastructure and private scheme operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Payments Market |
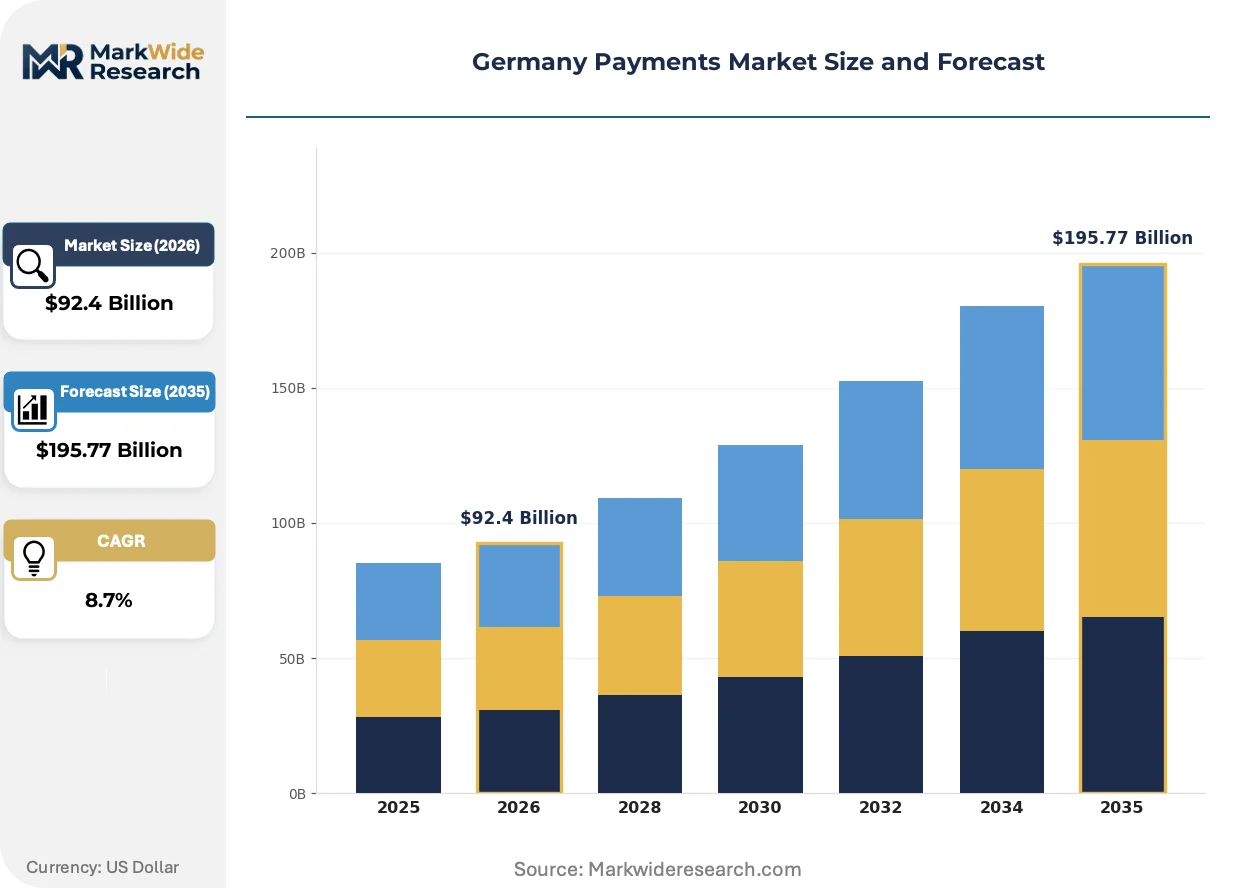
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Cards, Debit Cards, Mobile Wallets, Bank Transfers, Digital Banking, Direct Debit End User Industry: E-commerce, Transportation, Hospitality, Telecommunications, Education, Utilities Technology: EMV Chips, NFC, QR Code, Tokenization, Blockchain, Biometric Authentication Distribution Channel: Online Platforms, Point of Sale Terminals, Mobile Applications, ATMs, Contact Centers |
| Companies Covered | PayPal Holdings Inc, Visa Inc, Mastercard Inc, Klarna Bank AB, Adyen NV, Stripe Inc, Worldline Sa, Paydirekt GmbH, Girocard (Deutsche Kreditwirtschaft), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Payments Market Shifts & Advancements
Authentication modalities are bifurcating between frictionless biometric flows and stepped-up cryptographic challenges. German issuers are racing to deploy compliant stacks before regulatory enforcement hardens.
Biometric payment authentication is converging with transit credential systems to enable seamless multimodal mobility. Fingerprint and facial recognition sensors embedded in smartphones are replacing physical transit cards across Berlin U-Bahn and Hamburg S-Bahn networks. Transit authorities are capturing fare revenue through tokenized device credentials rather than proprietary closed-loop media. This convergence is compressing the addressable market for dedicated transit card issuers while expanding biometric sensor deployment at fare gates.
The EU AI Act introduces mandatory algorithmic audit requirements for fraud-scoring engines deployed by German payment institutions. Issuers must document training data provenance and decision explainability for machine learning models used in transaction authorization. High-risk merchant categories including gambling and cryptocurrency exchanges face enhanced scrutiny of automated decline algorithms. German banks are responding by licensing modular compliance tooling from specialized regtech vendors rather than building audit capabilities in-house.
Merchant procurement of payment acceptance infrastructure is fragmenting across specialized vertical providers. Quick-service restaurant chains and fuel station operators are bypassing traditional acquiring banks to contract directly with software-integrated payment facilitators. These embedded finance arrangements bundle POS hardware, payment processing, and working capital advances into unified service contracts. The shift is most visible in Bavaria's autonomous retail corridor where unattended payment terminals dominate forecourt and vending deployments.
Germany Payments Market Segmentation
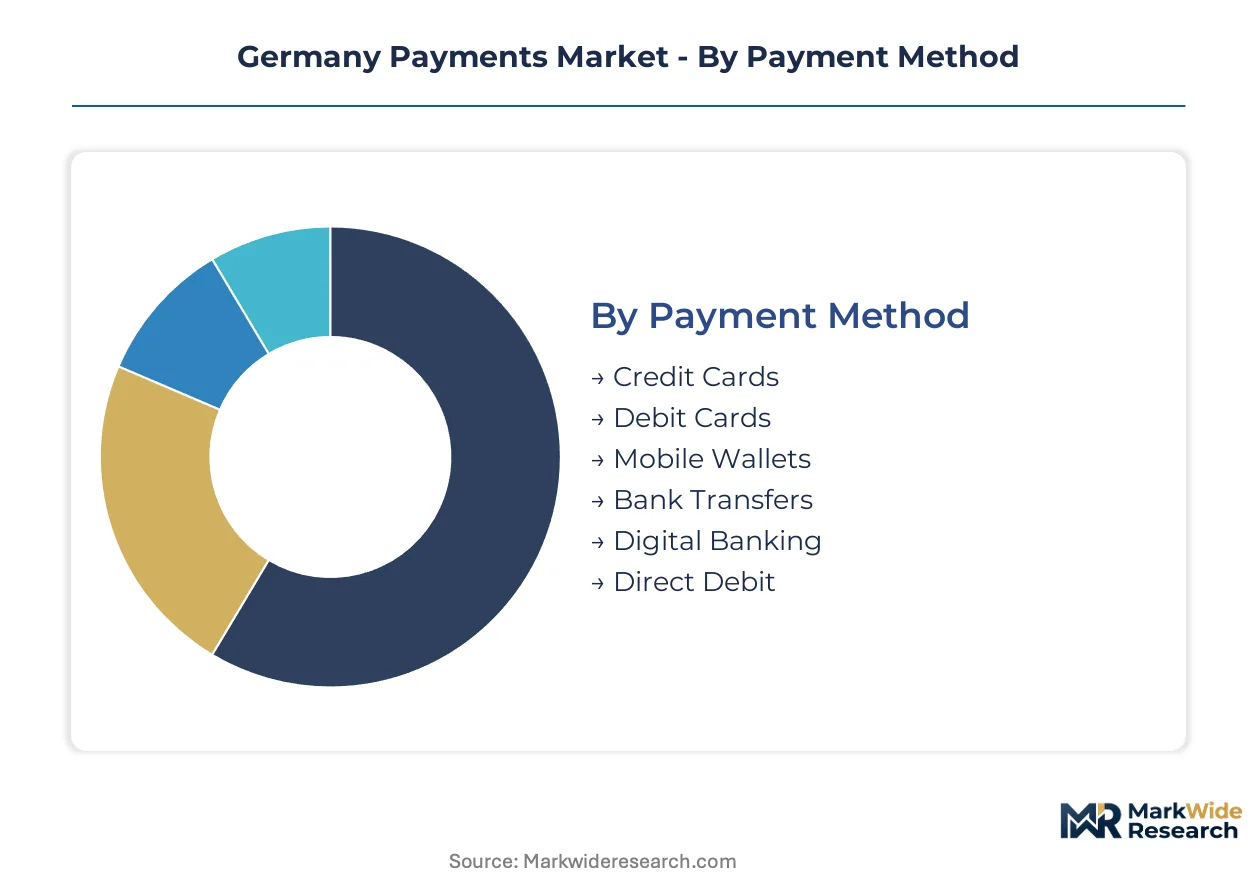
German payment infrastructure fragments across distinct technical and commercial dimensions. Each segmentation axis reveals divergent margin structures, regulatory exposure, and capital deployment requirements for market participants.
Payment Method:
Standardization dominates high-volume retail rails while customization concentrates in closed-loop loyalty schemes and bank consortium products.
- Credit Cards:Revolving credit instruments carrying interchange fees averaging 1.5-2.5% per transaction. Demand clusters in Hamburg's luxury retail corridor and Munich's business travel vertical, where corporate card programs command premium acceptance rates.
- Debit Cards:Direct-account-linked payment vehicles processing through Girocard domestic scheme and Visa/Maestro international rails. Berlin's grocery chains and fuel station networks drive volume through instant PIN-verified debits.
- Mobile Wallets:Smartphone-credentialized storage enabling tap-to-pay and in-app checkout. Apple Pay and Google Pay dominate Berlin transit integration.
- Bank Transfers:Account-to-account settlement via SEPA Credit Transfer and Instant Credit Transfer rails. E-commerce merchants in Hamburg favor this for high-ticket purchases.
- Digital Banking:Neobank-issued virtual cards and integrated payment interfaces. N26 and Tomorrow Bank anchor this segment.
- Direct Debit:Pre-authorized pull transactions for recurring utility and subscription billing. German insurers and telecom operators rely on SEPA Direct Debit mandates.
Leading the category by volume: Debit Cards. Growing fastest: Mobile Wallets.
End User Industry:
Volume concentration tilts toward transaction-frequency verticals while value concentration favors high-ticket discretionary spending.
- E-commerce:Online merchant checkout encompassing marketplace platforms, direct-to-consumer brands, and digital service subscriptions. Berlin's fashion-tech startups and Munich's automotive parts marketplaces generate disproportionate payment processing demand amid PSD2 SCA compliance investments.
- Transportation:Transit fare collection, ride-hailing settlement, and logistics payment corridors. Deutsche Bahn's nationwide mobile ticketing migration and Hamburg's port logistics operators are eliminating cash acceptance.
- Hospitality:Hotel reservations, restaurant settlements, and tourism service payments. Bavaria's alpine resort municipalities drive seasonal volume spikes.
- Telecommunications:Mobile plan billing, device financing, and digital content purchases. Deutsche Telekom and Vodafone Germany anchor recurring payment volumes.
- Education:Tuition processing, campus commerce, and student fee collection. Technical University of Munich and Humboldt University Berlin deploy contactless campus cards.
- Utilities:Electricity, gas, water, and waste management billing. Municipal Stadtwerke across North Rhine-Westphalia favor direct debit mandates.
Transaction frequency peaks in E-commerce. Value per transaction peaks in Transportation.
Technology:
Hardware-dependent authentication methods carry higher deployment friction than software-native verification layers.
- EMV Chips:Embedded microprocessor cards storing cryptographic keys for offline PIN verification and online authorization. German card issuers completed migration years ago; replacement cycles now drive refresh demand.
- NFC:Near-field communication enabling contactless tap-to-pay at point-of-sale terminals. Berlin's BVG transit authority and Hamburg's HVV mandate NFC-only fare gates.
- QR Code:Optical machine-readable matrix codes for merchant-presented and consumer-presented payment initiation. PayPal and Klarna deploy these for merchant-free onboarding.
- Tokenization:Primary account number substitution with device-bound credentials. Mastercard's MDES and Visa's VTS services provision German issuers.
- Blockchain:Distributed ledger settlement for cryptocurrency conversions and experimental central bank digital currency pilots. Deutsche Bundesbank's Project Helvetia tests wholesale applications.
- Biometric Authentication:Fingerprint, facial recognition, and behavioral pattern verification for SCA-compliant step-up authentication. FIDO Alliance standards guide German bank implementations.
Deployment maturity peaks with EMV Chips. Regulatory momentum favors Biometric Authentication.
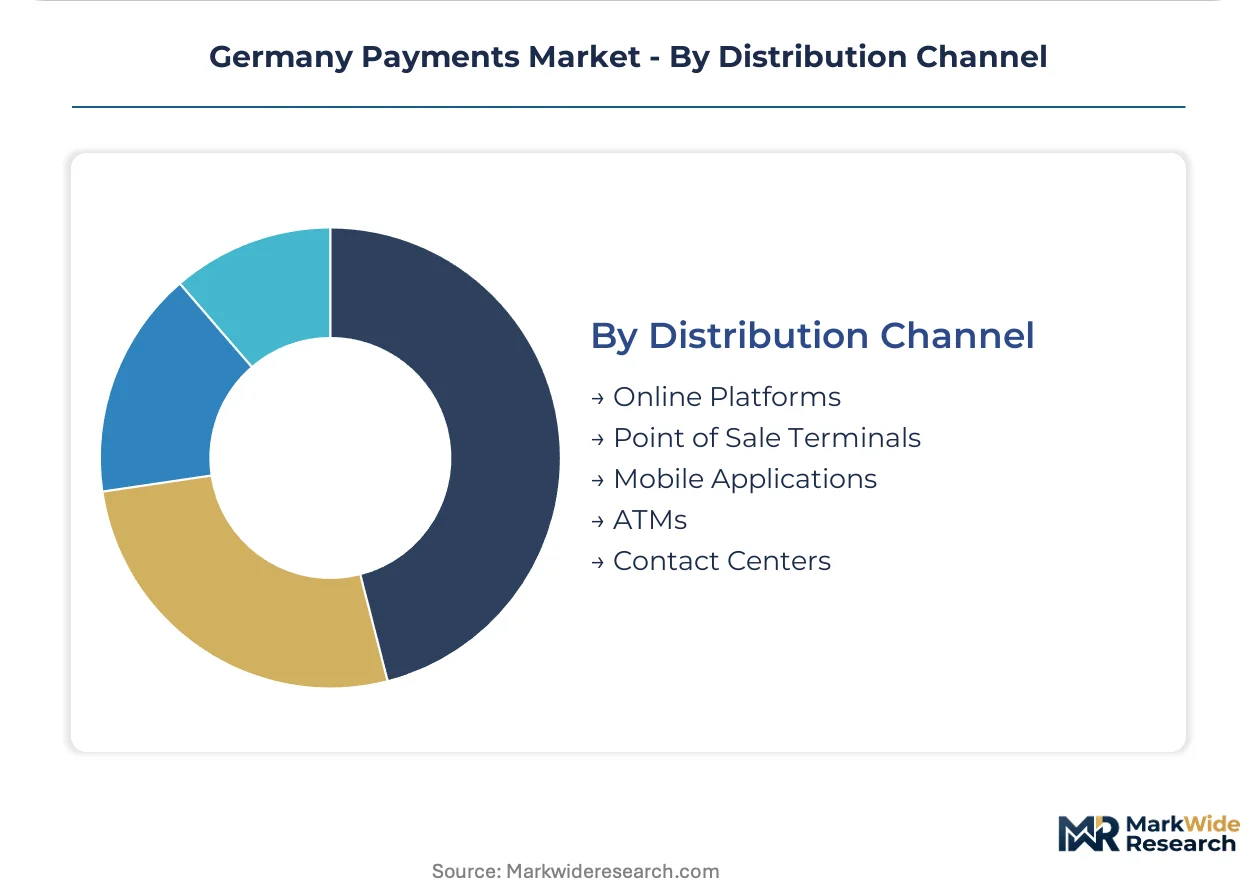
Distribution Channel:
Physical infrastructure carries fixed cost burdens while digital channels scale with marginal cost approaching zero.
- Online Platforms:Browser-based checkout flows and merchant-integrated payment gateways. Shopify and WooCommerce plugin ecosystems dominate German SME enablement.
- Point of Sale Terminals:Physical card acceptance devices at retail locations. Ingenico and Verifone hardware saturates Hamburg's merchant acquiring hub.
- Mobile Applications:Smartphone-native payment initiation and credential management. Banking apps from Deutsche Bank and Commerzbank aggregate multiple payment methods.
- ATMs:Cash dispensing and deposit infrastructure with declining transaction relevance. Sparkassen and Volksbanken maintain dense rural networks.
- Contact Centers:Agent-assisted payment processing for complex or high-value transactions. Insurance and utilities deploy these for payment plan negotiations.
Transaction volume concentrates in Online Platforms. Infrastructure investment concentrates in Point of Sale Terminals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Berlin's fintech corridor anchors German payment innovation through concentrated venture deployment and regulatory sandbox access. The city's dense developer pool accelerates embedded finance prototyping for neobank partnerships.
North Rhine-Westphalia
Industrial payment corridors dominate transaction volume through manufacturing supply chain settlements. BaFin supervision under the German Payment Services Supervision Act governs Cologne-based payment institutions. Düsseldorf's corporate banking cluster processes high-value B2B settlements through TARGET2 instant rails.
Bavaria
Autonomous retail infrastructure drives unattended terminal deployment across fuel stations and vending networks. The EU AI Act mandates algorithmic audits for Munich-based fraud-scoring engine vendors. Bavaria's alpine resort municipalities generate seasonal hospitality payment spikes.
Hamburg
Merchant acquiring consolidation concentrates processor investments in quick-service retail verticals. PSD2 Strong Customer Authentication requirements reshape authorization protocol upgrades at Hamburg's port logistics operators. The city's merchant acquiring hub demands sub-second settlement rails for retention.
Baden-Württemberg
Automotive parts marketplaces generate disproportionate payment processing demand. Stuttgart's manufacturing ecosystem favors SEPA Direct Debit mandates for recurring supplier billing. The region's Mittelstand fabricators adopt contactless B2B procurement terminals.
Hesse
Frankfurt's TARGET2 settlement infrastructure anchors euro-denominated wholesale payment flows. The ECB coordinates instant settlement policy across regional banking participants. Hesse's dense financial services concentration supports specialized payment infrastructure vendors.
Germany Payments Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across German payment infrastructure. Consolidation pressure intensifies as merchant acquiring margins compress under domestic debit scheme pricing. Three archetypes dominate: global network operators, bank-backed consortium players, and software-integrated payment facilitators. M&A activity concentrates in merchant acquiring assets, while technology licensing agreements proliferate for biometric authentication stacks.
Among US-based network operators, Visa Inc and Mastercard Inc anchor the infrastructure tier through tokenization services and domestic issuer partnerships. Paydirekt GmbH exemplifies the bank-backed consortium model, leveraging Sparkassen and cooperative banking density for merchant loyalty. Klarna Bank AB and Adyen NV represent the software-integrated facilitator archetype, embedding payment acceptance into vertical-specific merchant workflows.
| Leading Market Players |
|---|
| PayPal Holdings Inc |
| Visa Inc |
| Mastercard Inc |
| Klarna Bank AB |
| Adyen NV |
| Stripe Inc |
| Worldline Sa |
| Paydirekt GmbH |
| Girocard (Deutsche Kreditwirtschaft) |
| Others |
Supply & Pricing Matrix
The EU AI Act's algorithmic audit mandate gates qualified supply for biometric authentication stacks, restricting premium-tier pricing access to vendors with documented training-data provenance and FIDO Alliance certification. Compliance tooling bundling now separates audit-ready authentication providers from commodity middleware suppliers, concentrating margin capture among regtech specialists serving Hamburg's merchant acquiring hub and Berlin's fintech corridor.
Pricing Analysis
Lead-time-driven pricing angles dominate authentication stack procurement, with PSD2 SCA-compliant biometric modules commanding premiums for sub-90-day deployment against discounted spot licensing for legacy password-based systems. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales integration support. Cost compression in standard-tier middleware is intensifying because Paydirekt GmbH's domestic debit scheme pricing pressures acquirer margins. Mid-tier regional Sparkassen exhibit highest price sensitivity, while TARGET2-connected Frankfurt wholesale banks prioritize compliance speed over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from BaFin-supervised payment institutions mandate multi-supplier qualification for biometric sensor hardware and tokenization service modules, reducing single-source concentration risk. Hardware supply concentrates in Taiwan, South Korea, and Germany for NFC-enabled terminal chipsets and fingerprint sensor arrays. Component dependencies include EMV-certified secure elements, FIDO2-compliant authentication processors, and API-native core banking middleware. Tariff exposure on Taiwanese semiconductor imports represents the dominant structural vulnerability. Distribution runs through Hamburg's merchant acquiring hub for terminal hardware and Berlin's fintech corridor for software-native authentication licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Payments Market sits in a technology-transition phase where biometric-integrated authentication is displacing legacy password-based verification stacks ahead of hard regulatory enforcement deadlines.
For Market Incumbents: Anchor defensive positioning through in-house biometric stack development or exclusive licensing partnerships with FIDO Alliance-certified vendors, protecting interchange rate premiums from merchant attrition to software-integrated payment facilitators. Deepen backward integration into tokenization infrastructure to preserve margin pools against Mastercard's and Visa's network service bundling. For New Entrants and Emerging Players: Enter via white-label authentication-as-a-service offerings targeting mid-tier Sparkassen and Volksbanken constrained by IT budget limitations and legacy core banking integration complexity. The most penetrable segment sits in Bavaria's autonomous retail corridor, where unattended fuel station and vending terminal operators seek bundled POS-hardware-payment-processing contracts without traditional acquiring bank intermediation. For Investors and Strategic Acquirers: BaFin's first algorithmic audit enforcement actions against fraud-scoring engine vendors are the leading indicator that compliance-service revenue multiples will expand for regtech specialists with pre-built EU AI Act tooling. Long-term viability over the next decade favors acquisition targets combining biometric authentication IP with established BaFin payment institution licensing, particularly those serving the transit-tokenization convergence segment.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Stack Licensing | Captures premium interchange rates from high-risk merchants facing PSD2 SCA deadlines. |
| Transit Credential Tokenization Partnership | Deutsche Bahn's mobile ticketing migration eliminates cash handling costs through closed-loop digital wallets. |
| EU AI Act Compliance Tooling Development | BaFin enforcement creates adjacent services revenue from mandatory algorithmic transparency requirements. |
| Merchant Acquiring Consolidation | Hamburg's processor investments concentrate quick-service retail and fuel station vertical retention. |
| Neobank Embedded Finance Integration | Berlin's developer density enables rapid prototyping of white-label payment infrastructure for non-financial brands. |
Research Methodology
Multi-period observation of contactless terminal deployment rates, biometric authentication adoption curves, and merchant acquiring margin compression anchored the trend analysis, supplemented by interviews with payment network executives, BaFin supervisory officers, merchant acquiring operations leads, and neobank product directors. Secondary validation drew from ECB settlement policy disclosures, BaFin payment institution licensing registers, TARGET2 participant data, and SEPA scheme operator reports. Bottom-up transaction volume modeling and top-down regulatory impact assessment were triangulated against processor investment announcements.
Input-output matrix framing structured the analytical framework, with segmentation dimensions spanning payment method, end-user industry, authentication technology, and distribution channel across the analysis window. CAGRs were derived from regression analysis of historical adoption curves and regulatory deadline acceleration effects. Industry-specific forecast inputs included PSD2 SCA compliance cost pass-through rates and transit authority digital wallet procurement timelines.
Revisions become necessary when regulatory enforcement timelines accelerate, biometric sensor supply disruptions materialize, or domestic debit scheme pricing collapses below network cost recovery thresholds. Forecasts reflect assumptions about merchant authentication abandonment tolerance and issuer IT budget allocation priorities. A model refresh is warranted upon material change in ECB instant settlement policy or EU AI Act audit enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Convergent Billing Market
Payments
Saudi Arabia Buy Now Pay Later Services Market
Payments
Uganda Mobile Money Market
Payments
India Forex Cards Market
Payments
Recurring Payments Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Cross-Border Payment Platform Market
Payments
United Kingdom Mobile Payments Market
Payments
Proximity Mobile Payment Market
Payments
India Gift Card and Incentive Card Market
Payments
United States Electronic Toll Collection Market
Payments
Vietnam Payments Market
Payments
Forex Cards Market
Payments
Italy POS Terminals Market
Payments
Global Wearable Payment Device Market
Payments
Social Media Payment Solution Market