
 Global Gift Card Market | 2026-2036
Global Gift Card Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gift Card Market Analysis
PCI DSS Level 1 certification is rotating as the decisive qualification gating which gift card issuers and processors can serve tier-one merchants and financial institutions. Amazon.com Inc leverages its closed-loop ecosystem to sustain dominance in digital gift card origination. Blackhawk Network anchors the B2B wholesale channel through its retail network density across North America.
Gift cards function as prepaid stored-value instruments, typically encoded with magnetic stripe, EMV chip, or tokenized digital credentials redeemable at designated merchants or open-loop payment networks. Their primary commercial purpose centers on transferring purchasing power without cash handling, enabling recipient choice while locking spend within issuer-controlled acceptance environments. Virtual gift cards and electronic gift cards command the fastest expansion as mobile wallet integration and instant delivery displace physical plastic production and fulfillment costs. Plastic gift cards retain margin concentration through seasonal retail merchandising and in-aisle impulse placement at supermarkets and convenience stores.
The US Federal Reserve supervises open-loop gift card compliance under Regulation E, while the EU Payment Services Directive governs electronic money issuance across European Economic Area jurisdictions. India's RBI mandates prepaid payment instrument licensing for domestic gift card circulation, creating localized barriers to foreign platform entry. Stakeholders must monitor central bank digital currency pilots and evolving e-money frameworks to assess whether sovereign-issued digital wallets displace proprietary stored-value architectures.
Market Dynamics
The migration from physical plastic to tokenized digital credentials is compressing issuance costs and collapsing fulfillment timelines across enterprise procurement programs. This technical shift redistributes margin from manufacturing and logistics toward platform software and API integration layers.
Growth Catalysts
- Corporate Incentive Programs:Human resources departments at Fortune 500 firms deploy bulk digital gift card distributions for employee recognition and wellness incentives. This channel bypasses traditional retail merchandising constraints.
- EU Payment Services Directive:The PSD2 framework harmonizes electronic money licensing across European Economic Area jurisdictions. Cross-border issuance friction drops for qualified non-bank payment institutions.
- Mobile Wallet Integration:Apple Wallet and Google Pay native gift card storage APIs enable instant redemption without merchant app downloads. Consumer adoption accelerates in urban China and South Korean metropolitan clusters.
Market Restraints
- Breakage Accounting Complexity:Unredeemed balance recognition under US GAAP and IFRS standards creates financial reporting uncertainty for large issuers. Audit scrutiny intensifies on revenue timing assumptions.
- Plastic Supply Concentration:Specialty PVC substrate and magnetic stripe production concentrates in East Asian manufacturing zones. Geopolitical friction threatens card body cost stability.
- Central Bank Digital Currency Substitution:Pilot programs by the People's Bank of China and European Central Bank test direct-to-consumer digital wallets. Sovereign-issued instruments may displace proprietary stored-value architectures.
Strategic Opportunities
- India Prepaid Payment Instrument Licensing:RBI-mandated PPI frameworks create localized entry barriers that favor early movers with domestic banking partnerships. Foreign platforms face 18-24 month authorization timelines.
- API-First B2B Distribution:Enterprise resource planning system integrations enable programmatic gift card issuance tied to customer lifetime value triggers. Salesforce and Workday connector ecosystems expand addressable procurement workflows.
- ISO 20022 Messaging Convergence:The global payments messaging standard harmonizes settlement data fields across open-loop networks. Issuers gain interoperability with real-time gross settlement systems in 70+ country corridors.
Industry Challenges
- PCI DSS Level 1 Certification Timelines:The 6-12 month audit cycle for tier-one merchant service status gates enterprise contract eligibility. Qualified security assessor capacity constraints extend project schedules.
- Legacy Core Banking Integration:Mainframe-based general ledger systems at regional banks require custom middleware development for real-time gift card balance synchronization. API abstraction layers demand ongoing maintenance investment.
- Fraud Vector Proliferation:Card-not-present transaction monitoring must distinguish legitimate bulk purchases from account takeover schemes. Machine learning model training requires labeled datasets that competing issuers rarely share.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gift Card Market |
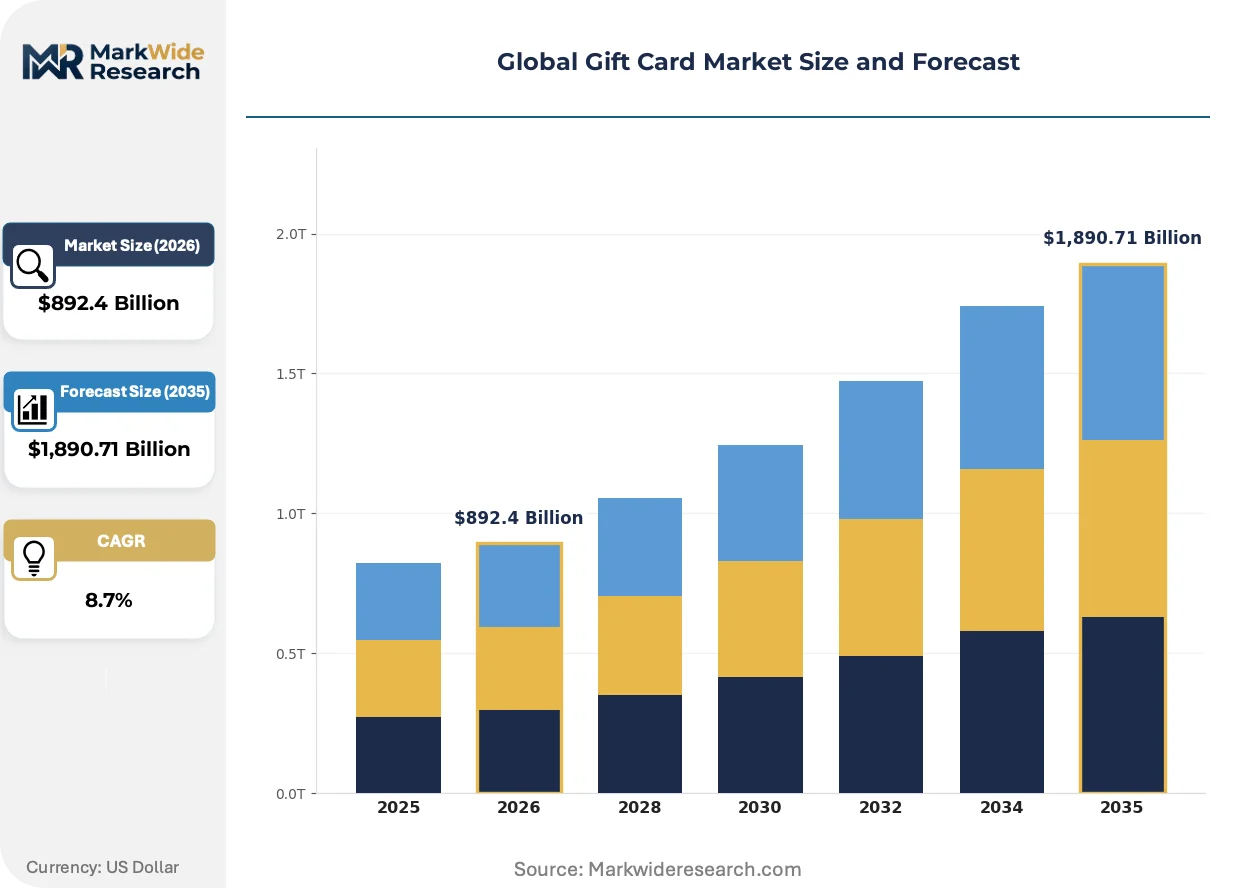
| Market Size in 2026 | $892.4 Billion |
| Market Size in 2035 | $1,890.71 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Gift Cards, Plastic Gift Cards, Electronic Gift Cards, Mobile Gift Cards Distribution Channel: Retail Stores, Online Platforms, Supermarkets, Convenience Stores Customer Type: Individuals, Corporations, Retailers, E-commerce Platforms End Use: B2C, B2B, Promotional, Loyalty Programs |
| Companies Covered | American Express Company, Starbucks Coffee Company, Amazon.com Inc, InComm Payments, PayPal Holdings Inc, Apple Inc, Best Buy Co Inc, Blackhawk Network, Target Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gift Card Market Emerging Trajectories
Digital credential architectures are collapsing the distinction between gift cards and general-purpose prepaid instruments. Platform providers now compete on redemption network breadth rather than proprietary merchant exclusivity.
Tokenized virtual card provisioning is supplanting physical plastic production for enterprise incentive and consumer gifting use cases. Large employers in technology and financial services verticals now default to API-delivered digital credentials for 80% of new program launches. This shift compresses issuance costs toward near-zero marginal economics while expanding last-minute purchase windows.
The EU AI Act imposes algorithmic transparency requirements on fraud detection systems used in electronic money issuance. Gift card platforms must document automated decision logic for transaction blocking and velocity limit enforcement. German and French regulators are first-movers in demanding explainable AI documentation from licensed payment institutions.
Employer-funded lifestyle benefit wallets are displacing single-merchant gift cards in North American corporate procurement. Human resources departments consolidate vendor relationships through flexible spending platforms that aggregate hundreds of redemption options. This concentration is most visible in US metropolitan technology hubs where talent competition drives benefit differentiation.
Global Gift Card Market Segmentation
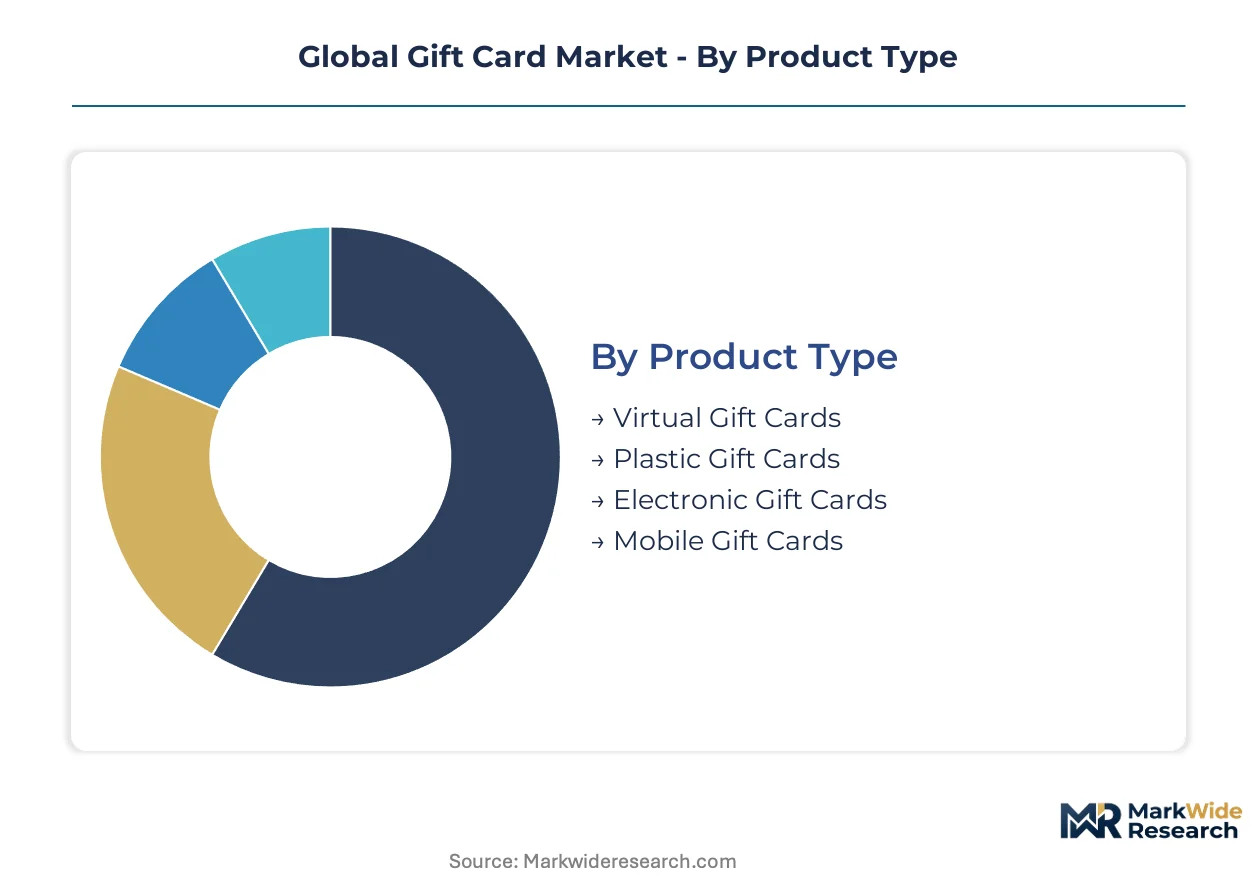
Gift card market segmentation reveals how technical form factors, procurement channels, and buyer economics create distinct margin pools. Each dimension carries unique regulatory exposure and capital intensity requirements that shape competitive positioning.
Product Type:
Regulatory frameworks differentiate stored-value instruments by credential format, with tokenized digital products facing lighter custody requirements than EMV-chip plastic under PCI DSS and e-money licensing regimes.
- Virtual Gift Cards:API-delivered credentials stored in Apple Wallet or Google Pay enable instant issuance with zero marginal production cost. Enterprise HR departments in US technology corridors and South Korean metropolitan clusters default to this format for employee recognition programs seeking last-minute delivery flexibility.
- Plastic Gift Cards:PVC substrate cards with magnetic stripe or EMV chip encoding retain margin concentration through seasonal retail merchandising and in-aisle impulse placement. German supermarket chains and US convenience store networks sustain volume through physical gift card rack density and breakage revenue recognition.
- Electronic Gift Cards:Email-delivered redemption codes bridge physical and fully tokenized formats, capturing mid-tier procurement budgets that require branding customization without plastic production timelines.
- Mobile Gift Cards:Native app-integrated credentials leverage NFC tap-to-pay infrastructure at point-of-sale terminals across Chinese urban retail ecosystems.
Established volume favors plastic gift cards; emerging adoption favors virtual gift cards.
Distribution Channel:
Channel economics concentrate margin capture at different supply chain depths, with direct-to-consumer platforms retaining full interchange while retail intermediaries extract rack placement fees.
- Online Platforms:Issuer-direct websites and mobile apps eliminate intermediary margin splits while capturing first-party purchase data for loyalty program integration. Amazon's closed-loop origination demonstrates maximum margin retention through proprietary distribution.
- Retail Stores:Third-party gift card racks at mass merchandisers generate placement fee revenue and incremental foot traffic. Blackhawk Network's North American retail density anchors this channel's wholesale economics.
- Supermarkets:Seasonal promotional displays and checkout lane placement drive impulse purchasing velocity during holiday windows in US and German grocery chains.
- Convenience Stores:24-hour accessibility and immediate physical fulfillment serve last-minute gifting demand in Japanese urban corridors and US interstate highway networks.
Volume concentrates in retail stores; steepest expansion trajectory belongs to online platforms.
Customer Type:
Procurement scale and contract structure differentiate buyer segments, with enterprise purchasing departments negotiating API-based programmatic issuance against individual transactional purchases.
- Corporations:Bulk digital distributions for employee incentives and customer acquisition campaigns command volume discounts while requiring PCI DSS Level 1 certification and SOC 2 audit documentation from issuers.
- Individuals:Single-unit purchasing for personal gifting occasions drives highest per-unit margin through convenience premiums and expedited delivery fees.
- Retailers:Co-branded issuance programs leverage merchant acceptance networks to lock spend within proprietary ecosystems.
- E-commerce Platforms:Marketplace-integrated gift card origination extends platform stickiness through stored-value retention and redemption velocity tracking.
Margin accretion favors individuals; contract stability favors corporations.
End Use:
Commercial purpose determines redemption velocity and breakage probability, with incentive-based issuance showing faster utilization than discretionary gifting.
- B2B:Enterprise procurement of bulk credentials for channel partner incentives and sales performance rewards. Salesforce and Workday ERP integrations enable programmatic trigger-based issuance tied to customer lifetime value milestones.
- Loyalty Programs:Points-to-gift-card conversion and tiered reward redemption drive repeat engagement in airline, hospitality, and retail coalition programs across US and Chinese markets.
- B2C:Direct consumer purchasing for personal gifting occasions carries highest seasonal concentration and promotional sensitivity.
- Promotional:Issuer-funded or merchant-subsidized campaigns acquire new customers through trial-inducing small-denomination distribution.
Redemption speed favors loyalty programs; margin depth favors B2B procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement departments in the United States, China, and Germany dominate issuance volume. Corporate incentive programs and mobile wallet integration drive adoption across these primary corridors.
United States
Fortune 500 human resources departments deploy bulk digital distributions for employee recognition and wellness incentives. The Federal Reserve supervises open-loop compliance under Regulation E. San Francisco Bay Area technology firms default to API-delivered credentials for programmatic issuance tied to customer lifetime value triggers.
China
Urban retail ecosystems leverage NFC tap-to-pay infrastructure for mobile gift card redemption at point-of-sale terminals. The People's Bank of China pilots central bank digital currency programs that test direct-to-consumer digital wallets. Shanghai and Beijing metropolitan clusters show fastest consumer adoption of native app-integrated credentials.
Germany
Supermarket chains sustain physical gift card volume through seasonal merchandising and in-aisle impulse placement. The EU Payment Services Directive harmonizes electronic money licensing across European Economic Area jurisdictions. Berlin and Munich regulators demand explainable AI documentation from licensed payment institutions under the EU AI Act.
India
RBI-mandated prepaid payment instrument licensing creates localized entry barriers favoring early movers with domestic banking partnerships. The central bank requires PPI authorization for domestic gift card circulation. Mumbai and Bangalore technology corridors face 18-24 month authorization timelines for foreign platform entry.
South Korea
Metropolitan clusters accelerate consumer adoption of Apple Wallet and Google Pay native storage APIs. The country's financial regulator oversees electronic money issuance frameworks. Seoul-based employers consolidate vendor relationships through flexible spending platforms that aggregate hundreds of redemption options.
Global Gift Card Market Vendor Landscape
Player mix skews toward diversified payment networks and closed-loop retail ecosystems. Concentration is moderate at the top tier with long-tail fragmentation among regional processors. Three archetypes dominate: closed-loop retail originators, open-loop payment networks, and B2B wholesale distributors. Strategic moves center on API-first platform development and mobile wallet integration partnerships.
Within the closed-loop retail tier, Amazon.com Inc and Starbucks Coffee Company exemplify proprietary ecosystem control. Blackhawk Network anchors B2B wholesale distribution through retail network density. These three occupy positions that represent the spectrum from merchant-locked stored value to network-agnostic programmatic issuance.
| Leading Market Players |
|---|
| American Express Company |
| Starbucks Coffee Company |
| Amazon.com Inc |
| InComm Payments |
| PayPal Holdings Inc |
| Apple Inc |
| Best Buy Co Inc |
| Blackhawk Network |
| Target Corporation |
| Others |
Supply Flow & Price Mechanics
PCI DSS Level 1 certification gates both supplier qualification and price differentiation simultaneously, with tier-one merchants demanding certified processors while paying premium rates for API-first platform access. This regulatory threshold concentrates pricing power among qualified issuers while compressing margins for uncertified regional players locked out of enterprise procurement channels.
Pricing Analysis
Cost-plus contracts with PVC substrate indexation dominate physical gift card manufacturing, while digital credential issuance shifts toward per-transaction SaaS tiers. Price differentiation hinges on certification grade—PCI DSS Level 1 versus Level 2—and volume scale for bulk enterprise distributions. Pricing pressure stems from near-zero marginal costs of virtual card provisioning eroding traditional breakage-reliant models. Individual purchasers show highest price sensitivity to delivery fees; corporate procurement departments prioritize API reliability over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate digital credential provisioning, while physical card production maintains strategic stockpiles of EMV chip modules and specialty PVC substrate. Manufacturing concentrates in China, South Korea, and Taiwan for chip encoding and card body fabrication. Raw material dependencies include PVC substrate, magnetic stripe ferric oxide tape, and EMV chip modules from semiconductor foundries. Single-source vulnerability threatens EMV chip supply from concentrated semiconductor packaging facilities. Distribution runs through wholesale B2B platforms and retail rack placement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Fortune 500 procurement departments consolidate vendor relationships through flexible spending platform aggregators, fragmenting demand across hundreds of redemption options rather than single-merchant lock-in.
For Market Incumbents: Fortify API-first platform architecture against emerging fintech challengers by deepening direct banking partnerships for real-time settlement. Invest in ISO 20022 messaging compliance to maintain interoperability with real-time gross settlement systems. Prioritize explainable AI documentation for EU AI Act compliance in German and French regulatory jurisdictions. For New Entrants and Emerging Players: Mid-market employer lifestyle benefit wallets represent an underserved service layer where incumbents under-serve customization demands. Target Indian metropolitan technology corridors where RBI-mandated PPI licensing creates 18-24 month barriers for foreign platforms. Deploy Salesforce and Workday ERP connector ecosystems as primary go-to-market infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across virtual credential provisioning as cloud-native platforms displace legacy mainframe integrations. Long-term viability favors issuers with diversified redemption network breadth over closed-loop merchant exclusivity. Monitor central bank digital currency pilot programs as inflection indicators for sovereign-issued wallet displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Development | Enables Salesforce and Workday ERP integrations for programmatic enterprise issuance tied to customer lifetime value triggers. |
| Mobile Wallet Integration Partnership | Apple Wallet and Google Pay native storage APIs accelerate redemption velocity in South Korean and Chinese urban clusters. |
| ISO 20022 Messaging Compliance | Harmonizes settlement data fields across open-loop networks for interoperability with 70+ country real-time gross settlement corridors. |
| Domestic Banking Partnership Deepening | Secures real-time balance synchronization for legacy core banking integration at regional financial institutions. |
| Explainable AI Documentation Investment | Satisfies German and French regulator demands under EU AI Act for algorithmic transparency in fraud detection systems. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gift card platform CTOs, enterprise HR procurement directors, payment network compliance officers, and retail distribution channel managers. Secondary validation drew from SEC 10-K filings of listed payment networks, RBI circulars on prepaid payment instruments, EU Payment Services Directive regulatory texts, and customs records for PVC substrate trade flows. Bottom-up issuance volume estimates triangulated against top-down payment network transaction disclosures.
Across the analysis window, forecasts model product type segmentation by credential format, distribution channel by procurement workflow, and customer type by contract structure. CAGRs derive from regression analysis of historical issuance growth against mobile wallet penetration curves and corporate incentive program adoption rates. Industry-specific inputs include central bank digital currency pilot timelines and PCI DSS certification queue capacity constraints.
Forecasts assume regulatory continuity in US Regulation E supervision, EU PSD2 electronic money frameworks, and RBI prepaid payment instrument licensing; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as sovereign digital wallet pilots and geopolitical friction in semiconductor supply chains evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Point-To-Point Encryption (P2PE) Payment Market
Payments
Qatar Payments Market
Payments
NFC Payments Market
Payments
Global Payments Market
Payments
UAE Buy Now Pay Later Services Market
Payments
Digital Remittance Service Market
Payments
Sweden POS Terminals Market
Payments
China Prepaid Cards Market
Payments
Germany Real Time Payments Market
Payments
India Mobile Payments Market
Payments
France Buy Now Pay Later Services Market
Payments
Europe Payment Gateways Market
Payments
United States Electronic Toll Collection Market
Payments
Singapore Gift Card and Incentive Card Market
Payments
South Korea Payments Market
Payments
North America POS Terminal Market