
 UAE Buy Now Pay Later Services Market | 2026-2036
UAE Buy Now Pay Later Services Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Buy Now Pay Later Services Market Analytics
Market Context
The UAE is reshaping digital credit infrastructure through sovereign fintech investment and open-banking mandates. Tabby leverages its merchant network density to sustain checkout-integration leadership across Gulf Cooperation Council retail chains. Tamara anchors its position through proprietary risk-scoring algorithms tailored to thin-file borrowers in the Emirates. Postpay competes aggressively on zero-interest positioning, extending its footprint into Saudi Arabia and Kuwait from its Dubai headquarters.
Technical Definition and Segment Structure
Buy Now Pay Later services constitute short-term, point-of-sale credit instruments that split consumer purchases into equal instalments, typically processed through API-embedded checkout interfaces with real-time underwriting decisions. These instruments serve primarily to reduce cart abandonment in digital commerce while capturing interchange-equivalent revenue from merchant fees rather than borrower interest. Pay Later and Interest-Free Financing categories dominate transaction volume, though Flexible Payments commands superior unit economics due to longer tenors and higher merchant discount rates. Mobile Applications lead platform adoption, while Luxury Purchases within the Transaction Size dimension concentrate margin pools despite representing lower absolute frequency.
Regulatory Framework and Outlook
The Central Bank of the UAE governs non-bank lending through its Consumer Protection Regulation and digital financial services licensing regime, while SAMA in neighbouring Saudi Arabia imposes parallel caps on late fees and disclosure requirements that ripple across Gulf-based BNPL operators. MOHAP and the UAE's economic departments coordinate on e-commerce consumer safeguards that directly affect refund workflows and dispute resolution timelines for instalment products. Stakeholders must monitor whether the Central Bank extends prudential capital requirements currently applied to banks onto large-scale BNPL balance sheets.
Market Dynamics
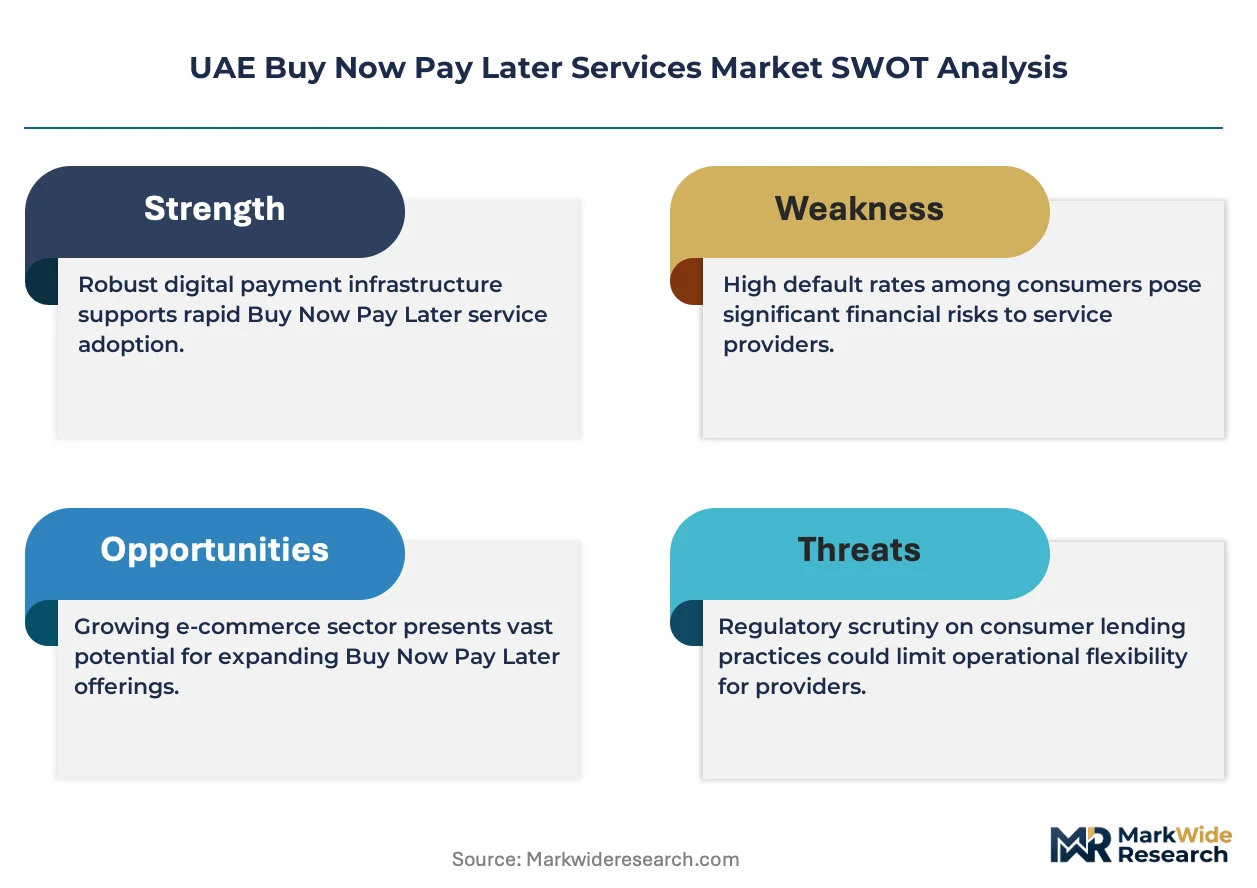
The Central Bank of the UAE's tightening oversight of non-bank digital lenders is compressing operational runway for unlicensed BNPL providers while accelerating consolidation toward regulated balance-sheet operators. This regulatory pressure is redrawing competitive boundaries across the Emirates' point-of-sale credit landscape.
Growth Catalysts
- Open Banking Mandates:The UAE's open-banking framework is forcing incumbent banks to share customer transaction data via standardized APIs. This data liquidity enables real-time alternative credit scoring for thin-file borrowers previously excluded from formal credit.
- E-commerce Checkout Integration:Merchant-side API embedment at digital point-of-sale is reducing cart abandonment rates in Dubai's retail corridor. Retailers are prioritizing BNPL partnerships that preserve conversion funnel velocity.
- Smartphone Penetration:Near-universal mobile device ownership across the Emirates is collapsing customer acquisition costs for app-native instalment providers. Mobile-first underwriting interfaces are displacing traditional branch-based credit applications.
Market Restraints
- Regulatory Capital Uncertainty:The Central Bank of the UAE has not yet clarified whether prudential capital requirements applied to banks will extend to large-scale BNPL balance sheets. This ambiguity is freezing long-term funding strategies for scaling operators.
- Merchant Discount Rate Compression:Competitive pressure from zero-interest positioning is squeezing the primary revenue stream for instalment providers. Merchant fees are trending toward interchange-equivalent levels that challenge unit economics.
- Thin-File Default Risk:Proprietary risk-scoring algorithms lack sufficient historical performance data across Gulf Cooperation Council credit cycles. Underwriting models face validation gaps during macroeconomic stress scenarios.
Strategic Opportunities
- SME Working Capital Extension:B2B trade credit represents an adjacent white space with superior ticket sizes and lower customer acquisition costs. Merchant networks built in retail can pivot toward invoice financing for Dubai's trading businesses.
- Cross-Border GCC Licensing:SAMA's regulatory framework in Saudi Arabia permits reciprocal recognition for UAE-licensed digital lenders. Operators can leverage Dubai headquarters to access the Kingdom's larger consumer base.
- Embedded Insurance Attach:Product protection and purchase insurance bundled at checkout is generating incremental revenue per transaction. Regulatory coordination between the Central Bank and MOHAP is clarifying composite product distribution rules.
Industry Challenges
- Sharia Compliance Complexity:Structuring instalment products as murabaha or ijara contracts requires specialized Islamic finance legal expertise. Talent scarcity in fintech-sharia hybrid skill sets is constraining product velocity.
- Legacy Core Banking Integration:Merchant acquirers in the Emirates operate on fragmented payment switch architectures. API standardization gaps are forcing costly custom integration work for each major retail chain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Buy Now Pay Later Services Market |
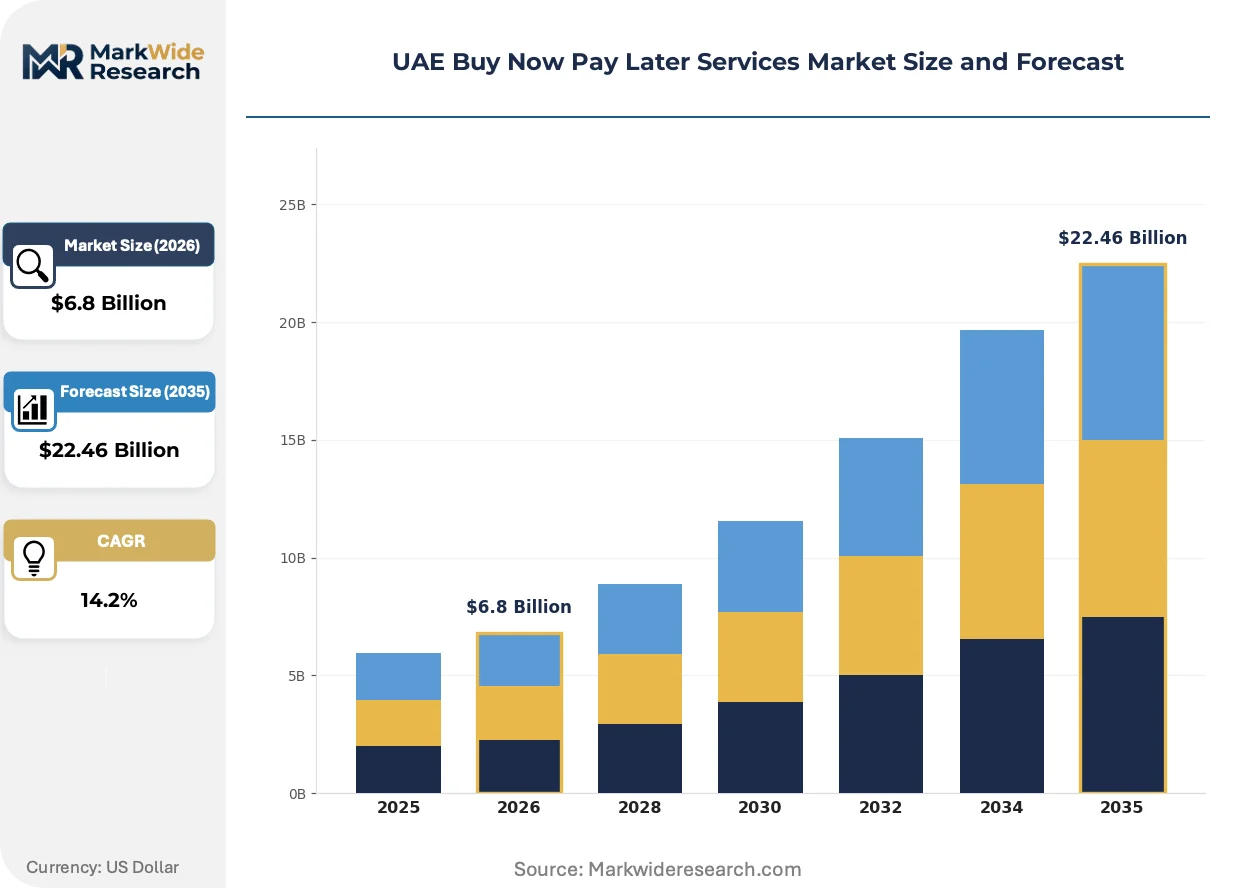
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pay Later, Partial Payment, Interest-Free Financing, Flexible Payments Customer Type: Retail Customers, E-commerce Shoppers, Millennials, Working Professionals Platform: Mobile Applications, Online Portals, Retail APIs, In-store Solutions Transaction Size: Low Value, Medium Value, High Value, Luxury Purchases |
| Companies Covered | Postpay, Payby, Tabby, Rise, Zoodpay, Tamara, Spotii, Aramex Smart, Cashew Payments, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Buy Now Pay Later Services Market Evolving Landscape
Real-time decisioning infrastructure is displacing batch-processed credit applications across the Emirates' digital commerce stack. Three convergent developments are compressing underwriting latency while expanding addressable borrower pools.
Alternative data fusion is migrating from experimental pilot programs to production-grade risk engines. BNPL providers are ingesting telco payment histories, utility bill records, and e-commerce return patterns to score thin-file applicants. Dubai-based fintechs are deploying machine learning models trained on these non-traditional signals to approve borrowers rejected by conventional bureau-dependent scoring.
The Central Bank of the UAE's Consumer Protection Regulation is mandating standardized late-fee disclosures and cooling-off periods for digital credit products. Compliance investments are diverting engineering resources from feature development toward regulatory reporting infrastructure. Operators are responding by restructuring product terms to cap maximum liability exposure while preserving merchant-facing value propositions.
Checkout financing preferences are fragmenting by purchase category across the Emirates. Luxury goods buyers are gravitating toward longer-tenor flexible payment structures with embedded upgrade options, while grocery and convenience purchases concentrate in two-instalment split-pay formats. Dubai's mall operators are segmenting BNPL partnerships by tenant category to match these divergent behavioral patterns.
UAE Buy Now Pay Later Services Market Segmentation
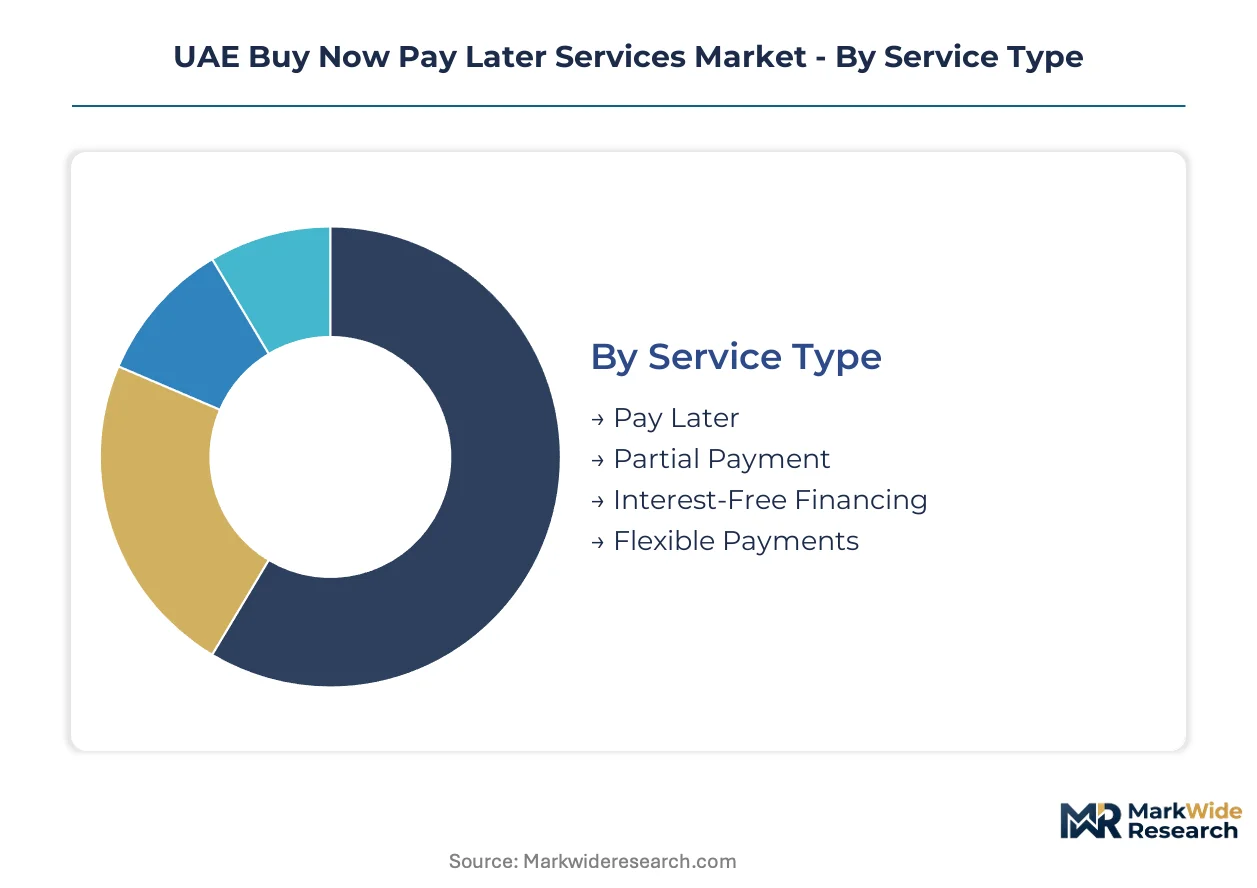
Segmentation in UAE BNPL services reveals divergent monetization paths across payment structures and customer acquisition channels. Platform choice and transaction sizing determine unit economics more decisively than in conventional consumer credit markets.
Service Type:
Mature instalment structures dominate transaction volume while emerging hybrid formats capture margin expansion opportunities.
- Pay Later:Single-invoice deferral products with 14-30 day settlement windows. Dubai's retail corridor concentrates demand where merchants prioritize checkout conversion velocity over financing revenue.
- Flexible Payments:Extended-tenor instalment structures with variable schedules and embedded upgrade options. Luxury retail tenants in Emirates malls are driving adoption for higher-ticket discretionary purchases.
- Interest-Free Financing:Sharia-compliant murabaha structures with merchant-funded promotional periods. Central Bank disclosure mandates are standardizing fee transparency across licensed providers.
- Partial Payment:Split-deposit models requiring upfront fractional commitment. Travel and hospitality verticals in Abu Dhabi are piloting these structures for package bookings.
Pay Later handles the majority of throughput; Flexible Payments is the fastest mover on share.
Customer Type:
Acquisition cost tiers separate digitally native cohorts from salary-linked traditional borrowers.
- E-commerce Shoppers:Cart-level financing users acquired through embedded checkout APIs. Smartphone penetration near 100% across the Emirates collapses onboarding friction for this segment.
- Working Professionals:Salary-backed instalment users with employer-verified income streams. KYC automation through HR platform integrations is accelerating approval rates in Dubai's corporate zones.
- Retail Customers:Branch-originated borrowers from traditional consumer finance backgrounds. Legacy documentation requirements constrain growth velocity relative to digital-native alternatives.
- Millennials:Age-cohort segment with thin-file credit histories and high digital engagement. Alternative data scoring using telco and utility records is expanding approval pools for this demographic.
E-commerce Shoppers generate the lowest acquisition costs; Working Professionals deliver the strongest repayment performance.
Platform:
Integration depth determines merchant switching costs and revenue retention.
- Mobile Applications:Native iOS and Android interfaces with biometric authentication and push-notification repayment reminders. Near-universal device ownership across the Emirates makes this the default engagement layer.
- Retail APIs:Embedded checkout modules integrating directly into merchant e-commerce stacks. Dubai's mall operators are mandating API standardization to reduce technical integration timelines.
- Online Portals:Browser-based account management and application interfaces. Legacy users and B2B procurement workflows maintain residual demand for this channel.
- In-store Solutions:QR-code and terminal-based origination at physical point-of-sale. High-value jewellery and electronics retailers in Abu Dhabi malls favor this verification-heavy format.
Mobile Applications anchor customer engagement; Retail APIs are climbing the fastest on merchant adoption.
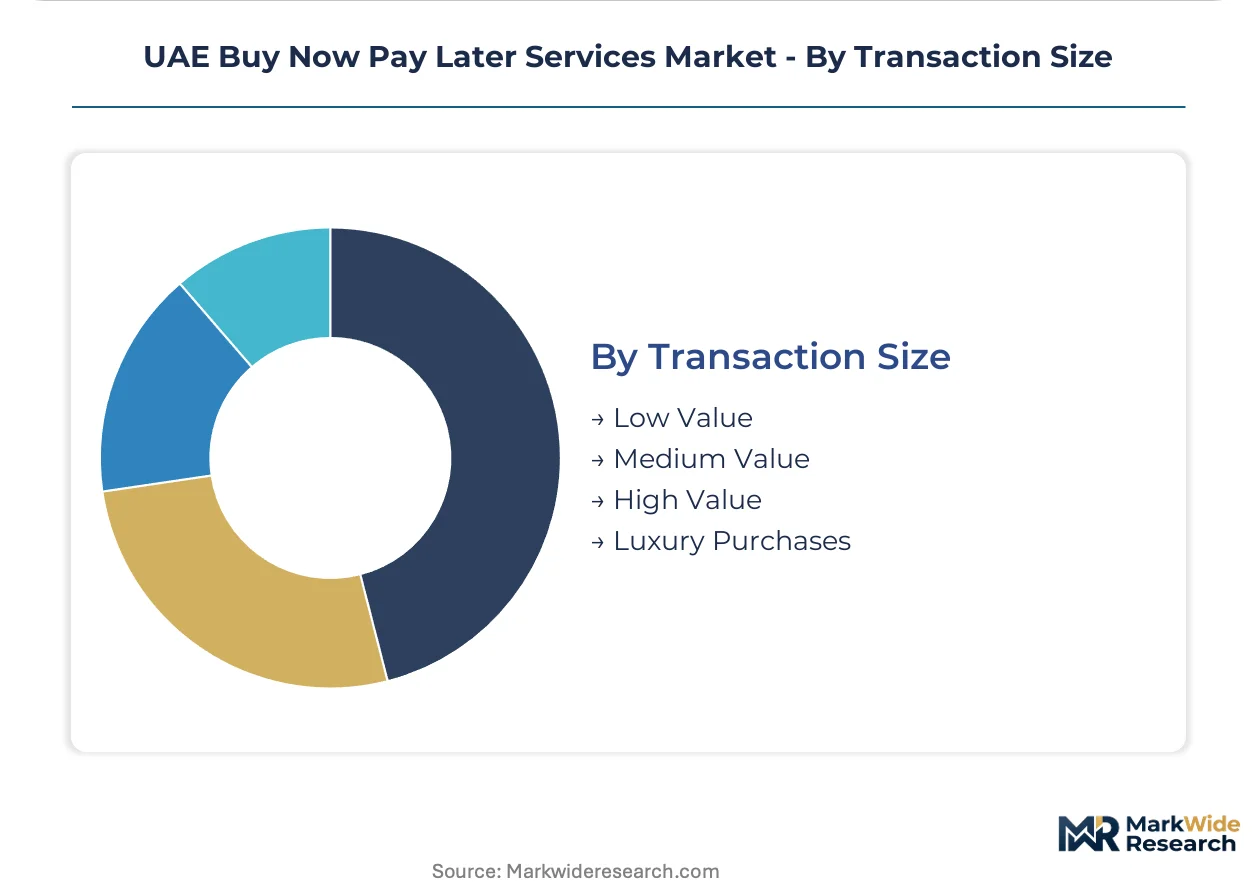
Transaction Size:
Ticket stratification aligns with merchant discount rate tolerance and default risk calibration.
- Luxury Purchases:High-ticket discretionary financing for fashion, jewellery, and premium electronics. Emirates mall tenants in Dubai concentrate demand where extended tenors justify elevated merchant fees.
- High Value:Mid-luxury segment spanning AED 5,000-20,000 ticket sizes. Home furnishing and appliance retailers are expanding BNPL availability to reduce cart abandonment.
- Medium Value:Core retail segment covering fashion, beauty, and consumer electronics. Grocery and convenience verticals are piloting split-pay formats in this range.
- Low Value:Micro-instalment products for sub-AED 500 purchases. Quick-service restaurants and pharmacy chains are testing two-instalment structures to drive frequency.
Medium Value transactions process the highest absolute volume; Luxury Purchases deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali Port and the UAE's fiber-optic backbone to Saudi Arabia and Kuwait underpin the Emirates' position as the Gulf's digital credit corridor.
Dubai
E-commerce checkout integration drives merchant adoption across Dubai's retail corridor. The Central Bank of the UAE's Consumer Protection Regulation mandates standardized late-fee disclosures for all digital lenders operating in the emirate. Dubai Internet City clusters fintech engineering talent where BNPL providers deploy real-time underwriting infrastructure.
Abu Dhabi
Luxury retail and hospitality verticals concentrate demand for extended-tenor instalment products. ADGM's digital banking framework permits sandbox licensing for experimental credit products. Yas Island's entertainment and retail complexes host pilot programs for high-ticket BNPL partnerships.
Sharjah
Mid-income retail segments generate volume for split-pay grocery and convenience formats. The emirate's economic department coordinates with MOHAP on e-commerce consumer safeguards affecting refund workflows. Sharjah's industrial zones supply merchant networks for B2B trade credit expansion.
Northern Emirates
Thin-file borrower pools in Ajman, Ras Al Khaimah, Fujairah, and Umm Al Quwain attract alternative data scoring pilots. The Central Bank's licensing regime extends compliance requirements to all non-bank lenders regardless of headquarters location. Mall operators in these emirates are replicating Dubai's segmented BNPL partnership models.
UAE Buy Now Pay Later Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in risk-scoring and merchant-acquirer modules. The UAE BNPL market exhibits tiered concentration with three to four balance-sheet operators controlling merchant network density while smaller app-native challengers compete on customer acquisition cost. Strategic archetypes include merchant-embedded checkout platforms, standalone consumer apps, and bank-affiliated instalment products. Dominant competitive moves involve regulatory licensing sprint strategies and cross-border GCC expansion through reciprocal Saudi SAMA recognition.
Within the merchant-embedded tier, Tabby and Tamara exemplify platform-scale operators leveraging Dubai headquarters to anchor Gulf-wide networks. Postpay occupies a position among the zero-interest positioning specialists extending from UAE bases into Kuwait and Saudi Arabia. These three entities represent the archetype of regulated balance-sheet operators consolidating market share as Central Bank compliance requirements compress runway for unlicensed competitors.
| Leading Market Players |
|---|
| Postpay |
| Payby |
| Tabby |
| Rise |
| Zoodpay |
| Tamara |
| Spotii |
| Aramex Smart |
| Cashew Payments |
| Others |
Value Network & Pricing Analysis
Jebel Ali Port's container throughput costs cascade through merchant discount rate negotiations, concentrating pricing power with Dubai-headquartered balance-sheet operators while fragmenting margins for API-dependent challengers. The corridor's logistics economics tether supply concentration to downstream price differentiation across the Emirates' instalment landscape.
Pricing Analysis
Volume-discount tiering structures separate enterprise retail chains with AED 50 million-plus annual throughput from mid-market merchants and single-location independents. Merchant fees stratify across premium, standard, and economy tiers based on transaction velocity guarantees and exclusivity commitments. Pricing pressure stems from zero-interest positioning compressing the primary revenue stream, with grocery and convenience verticals exhibiting acute price sensitivity while luxury mall tenants tolerate elevated rates for extended-tenor products.
Supply Chain Analysis
Supplier-financing facilities from UAE-headquartered merchant acquirers extend 60-90 day payment terms to retail chain partners, embedding working capital into distribution relationships. Technology infrastructure draws from India, Singapore, and Estonia for cloud-native underwriting platforms. Single-source vulnerability concentrates in payment switch architectures, with distribution running through Dubai Internet City data centers to Northern Emirates mall operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity runs through checkout-embedded instalment products as e-commerce shoppers fragment by purchase category, creating specialized niches for vertical-specific providers.
For Market Incumbents: Pre-empt regulatory compression by securing Central Bank of the UAE digital lending licenses before capital requirements harden. Consolidate merchant API integration talent pools to defend against bank-affiliated challengers entering through open-banking mandates. Vertical integration into proprietary risk-scoring engines preserves margin position as third-party algorithm costs escalate. For New Entrants and Emerging Players: Northern Emirates thin-file borrower pools offer the most penetrable geographic white space, with Ajman and Ras Al Khaimen mall operators replicating Dubai's segmented partnership models. B2B trade credit for Sharjah industrial zone trading businesses delivers superior unit economics through employer-verified income streams. A mobile-first KYC automation play through HR platform integrations unlocks working professional segments. For Investors and Strategic Acquirers: Balance-sheet operators with GCC-wide SAMA reciprocal licensing represent the priority acquisition archetype for regional consolidation plays. Long-term viability hinges on regulatory licensing moats deepening over a five-to-ten year window. Monitor Central Bank prudential capital requirement clarity as the decisive inflection signal for funding strategy shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Central Bank Licensing Sprint | Regulatory authorization from the Central Bank of the UAE compresses unlicensed competitor runway. |
| Cross-Border SAMA Expansion | Reciprocal recognition unlocks Saudi Arabia's larger consumer base from Dubai headquarters. |
| Merchant API Standardization | Dubai mall operator mandates reduce technical integration timelines for checkout embedment. |
| Alternative Data Engine Development | Telco and utility record ingestion expands thin-file approval pools beyond bureau-dependent scoring. |
| SME Working Capital Pivot | Invoice financing for trading businesses leverages existing retail merchant networks. |
Research Methodology
Operator-level perspectives from BNPL product managers, merchant acquisition heads, risk-scoring engineers, and Central Bank regulatory liaisons anchored the qualitative base. Secondary validation drew from UAE Central Bank Consumer Protection Regulation filings, SAMA digital lending circulars, e-commerce platform integration documentation, and Gulf Cooperation Council payment switch operator disclosures. Bottom-up transaction volume modeling triangulated against top-down merchant network density estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon without year-specific anchoring. Segmentation dimensions modeled include service type, customer acquisition channel, platform integration depth, and transaction size tier. CAGRs derived from merchant fee trajectory assumptions and smartphone penetration saturation curves, with open-banking API adoption velocity and regulatory capital requirement timing as key industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by bank-affiliated instalment products or zero-interest positioning specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
United States Mobile Payment Market
Payments
Saudi Arabia Cash Management Services Market
Payments
Asia Pacific Mobile Wallet Market
Payments
Global Mobile Point of Sale (Mpos) Terminals Market
Payments
Payment Service Provider Market
Payments
P2P Payment Market
Payments
Global Virtual Payment (POS) Terminals Market
Payments
India POS Terminals Market
Payments
Middle East & North Africa Digital Payments Market
Payments
Europe POS Terminal Market
Payments
Bill Splitting Apps Market
Payments
Indonesia Payments Infrastructure Market
Payments
Forex Cards Market
Payments
North America Real Time Payment Market
Payments
GCC Payment Gateway Market
Payments
Europe Fuel Cards Market