
 Cash Management System Market | 2026-2036
Cash Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Cash Management System Market Intelligence
ISO 20022 certification is unwinding competitive barriers across the cash management system landscape, forcing vendors to rebuild messaging architectures around the standard. Kyriba leverages its cloud-native treasury platform to sustain dominance in multi-entity liquidity planning. HighRadius anchors its position through AI-driven receivables automation that competes with traditional ERP modules. TIS differentiates via bank connectivity aggregation that controls payment rail access across fragmented geographic banking networks.
A cash management system constitutes an integrated software platform that automates treasury operations including cash positioning, forecasting, payment execution, and bank reconciliation through real-time data aggregation from multiple financial institutions and ERP systems. Its primary commercial purpose is to minimize idle cash balances, reduce borrowing costs, and mitigate operational risk across corporate finance functions. Liquidity management modules command the deepest margin pools as multinational corporations demand predictive analytics for multi-currency cash pools across dispersed banking relationships. Cloud-based deployment is displacing on-premises installations as treasurers prioritize API-driven bank connectivity and elastic compute for stress-testing scenarios. Fraud detection capabilities are maturing fastest among product types as real-time payment rails expand attack surfaces requiring behavioral analytics and anomaly detection.
The European Banking Authority's PSD3 framework and the SEC's investment adviser custody rule shape product roadmaps by mandating audit trails and segregation of duties in treasury workflows. Singapore's Monetary Authority requires cyber resilience standards for cloud-hosted financial infrastructure that filters vendor eligibility across Asia-Pacific deployments. Stakeholders must weigh bank-agnostic connectivity against embedded ERP treasury modules as open banking APIs proliferate and treasury teams consolidate vendor relationships.
Market Dynamics
ISO 20022 migration is compressing vendor differentiation across the cash management system landscape, forcing treasury technology providers to rebuild core messaging engines around unified data standards while corporate treasurers demand seamless bank-agnostic connectivity.
Growth Catalysts
- PSD3 Framework:The European Banking Authority's enhanced audit trail mandates are compelling treasury departments across Germany, France, and the Netherlands to replace legacy reconciliation tools with automated platforms that embed segregation of duties.
- Real-Time Payment Rails:FedNow and SEPA Instant adoption is accelerating fraud detection module procurement as corporate finance teams confront expanded attack surfaces requiring behavioral analytics integration.
- Singapore Hub Concentration:The Monetary Authority of Singapore's cyber resilience certification for cloud-hosted financial infrastructure is filtering vendor eligibility and concentrating Asia-Pacific deployment decisions through Singapore-based treasury operations.
Market Restraints
- Implementation Cost Structure:Multi-entity ERP integration projects for cash forecasting platforms require substantial professional services expenditure that mid-market treasury departments cannot absorb without dedicated IT support.
- Bank Connectivity Concentration:SWIFT network dependency creates single-point-of-failure risk for payment execution modules, with regional bank API fragmentation in emerging markets forcing redundant connectivity investments.
- Data Standardization Friction:Incomplete ISO 20022 adoption across correspondent banking networks generates message format translation overhead that delays real-time cash positioning capabilities.
Strategic Opportunities
- India Treasury Modernization:RBI's push for corporate account aggregation through the Account Aggregator framework creates white space for cloud-native cash visibility platforms targeting manufacturing conglomerates in Mumbai and Bangalore.
- AI-Driven Predictive Analytics:Convergence of machine learning models with open banking APIs enables dynamic cash flow forecasting that traditional spreadsheet-based treasury processes cannot replicate.
- Embedded Finance Distribution:Banking-as-a-Service channels allow treasury technology vendors to embed liquidity management modules directly into vertical ERP suites serving healthcare and retail supply chains.
Industry Challenges
- Treasury Technology Talent Scarcity:Shortage of professionals combining corporate finance expertise with API architecture knowledge constrains implementation velocity for automated cash forecasting deployments.
- Legacy System Integration Complexity:SAP and Oracle ERP environments running decades-old general ledger architectures resist real-time data extraction without expensive middleware layers that erode cloud-native cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cash Management System Market |
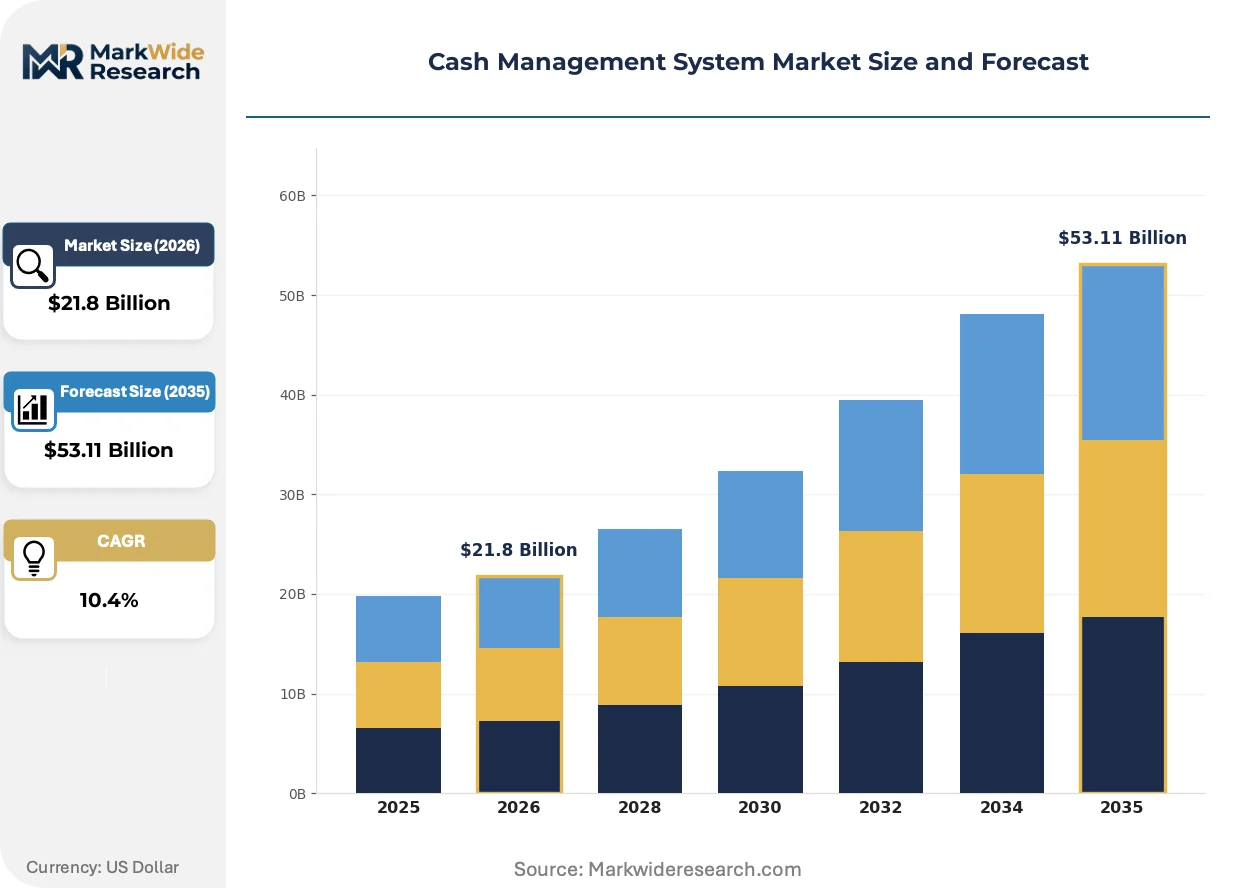
| Market Size in 2026 | $21.8 Billion |
| Market Size in 2035 | $53.11 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transaction Management, Liquidity Management, Reporting Solutions, Fraud Detection Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Corporations, Financial Institutions, Government Agencies, Non-Profit Organizations Solution: Integrated Systems, Standalone Applications, Consulting Services, Technical Support |
| Companies Covered | Nomentia, TIS, Kyriba, Trovata, Netgain, HighRadius, Agicap, CashAnalytics, SAP Cash Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cash Management System Market Strategic Shifts & Innovations
Cloud-native treasury architectures are dismantling the on-premises software model as API-driven bank connectivity becomes the non-negotiable procurement criterion for multinational liquidity management.
Embedded payment orchestration layers are displacing standalone treasury workstations by consolidating payment rail access, FX execution, and fraud screening into unified cloud platforms. Fortune 500 treasury departments in the United States and Germany are migrating core cash positioning functions to these integrated stacks within 18-to-24-month implementation windows. This consolidation is compressing margins for point-solution vendors while rewarding platforms that control end-to-end payment workflow automation.
The SEC's investment adviser custody rule is mandating granular audit trails and segregation of duties across treasury workflows, forcing asset managers to replace manual approval chains with permissioned blockchain or immutable database architectures. Compliance teams must now demonstrate real-time transaction logging that legacy spreadsheet-based processes cannot satisfy. North American buy-side institutions are responding by prioritizing vendors with pre-certified regulatory reporting modules over functionality-rich alternatives lacking audit-grade infrastructure.
Subscription-based pricing models are unbundling perpetual license structures as treasury software procurement teams favor consumption-aligned cost structures over upfront capital expenditure. Mid-market corporate buyers in the United Kingdom and Australia are driving this shift, demanding monthly billing tied to payment volume or entity count rather than user seats. This reconfiguration pressures incumbent vendors to rebuild revenue recognition systems while creating entry points for challengers offering transparent, scalable pricing tiers.
Cash Management System Market Segmentation
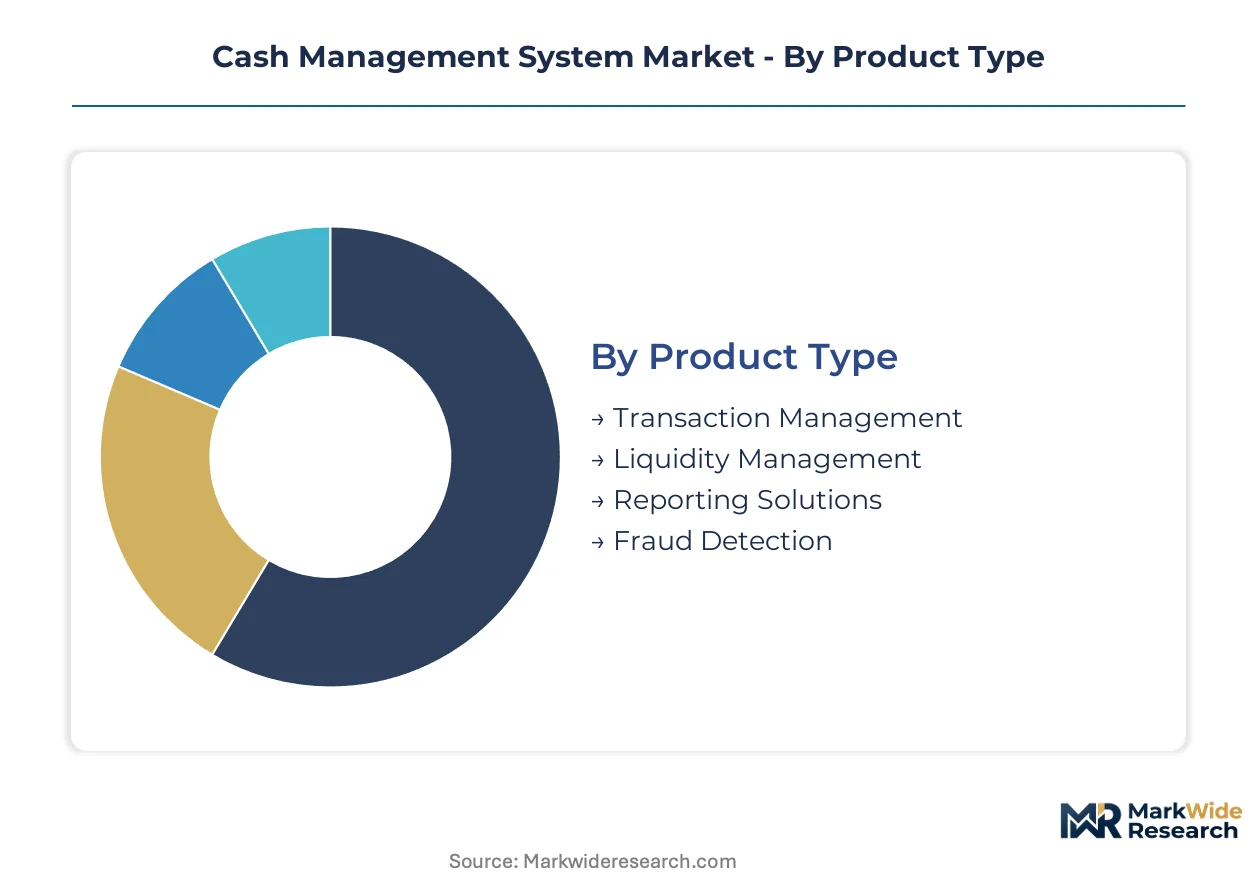
Treasury technology procurement splits across four dimensions that determine integration complexity and recurring revenue potential. Product type and deployment mode shape margin capture, while end-user scale and solution architecture dictate implementation timelines and professional services attachment rates.
Product Type:
Liquidity management modules command the deepest margin pools as multinational corporations demand predictive analytics for multi-currency cash pools across dispersed banking relationships.
- Liquidity Management:Predictive cash pooling engines aggregate real-time balances across correspondent banking networks to optimize working capital deployment. Demand concentrates among Fortune 500 treasury departments in the United States and Germany as interest rate volatility intensifies focus on idle cash minimization.
- Fraud Detection:Behavioral analytics platforms screen payment instructions against anomaly patterns before execution on real-time rails. Financial institutions in Singapore and the United States are expanding procurement as FedNow and SEPA Instant adoption widens attack surfaces requiring machine-learning-based surveillance.
- Transaction Management:Payment execution workflows automate multi-bank instruction formatting and confirmation matching.
- Reporting Solutions:Regulatory disclosure engines compile audit trails for SEC custody rule and PSD3 compliance.
Liquidity management holds installed capacity. Fraud detection is rotating up the share rankings.
Deployment:
Cloud-based architectures concentrate volume growth as API-driven bank connectivity becomes non-negotiable for treasury teams consolidating vendor relationships.
- Cloud-Based:Elastic compute environments host treasury platforms with direct bank API integration, eliminating middleware maintenance overhead. Mid-market corporations in the United Kingdom and Australia favor subscription pricing aligned to payment volume rather than perpetual licenses.
- Hybrid:Split architectures retain sensitive forecasting models on-premises while routing payment execution through cloud-hosted connectivity layers. German automotive conglomerates prefer this configuration to satisfy Bundesbank operational resilience guidelines while capturing open banking API benefits.
- On-Premises:Legacy installations persist where data sovereignty requirements block external hosting.
- Mobile:Smartphone-accessible approval workflows extend treasury oversight to distributed finance teams.
On-premises retains legacy footprint. Cloud-based deployment is climbing the fastest.
End User:
Corporations generate the steepest expansion trajectory as decentralized treasury structures in manufacturing and healthcare drive entity-count-based licensing.
- Corporations:Multi-entity enterprises deploy integrated cash forecasting across ERP environments spanning SAP and Oracle general ledger systems. Manufacturing conglomerates in Mumbai and Bangalore are modernizing treasury infrastructure under RBI Account Aggregator framework incentives.
- Financial Institutions:Banks and asset managers require custody rule compliance modules with immutable audit trails for SEC examination readiness. North American buy-side institutions prioritize pre-certified regulatory reporting over functionality breadth.
- Government Agencies:Public sector treasuries mandate segregation of duties workflows for appropriation control.
- Non-Profit Organizations:Grant-dependent entities seek donor fund visibility with restricted cash tracking.
Corporations anchor current spending. Financial institutions are gaining share fastest.
Solution:
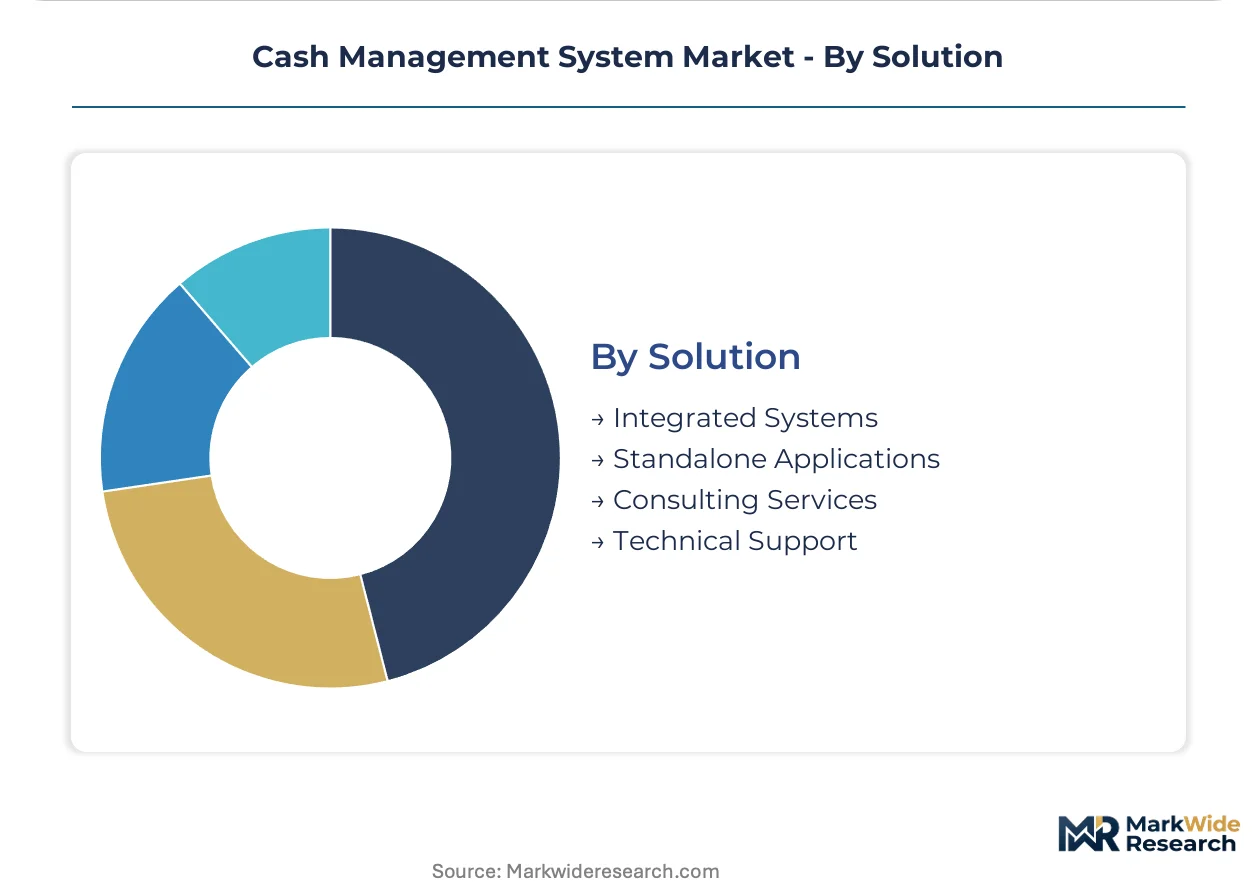
Integrated systems capture premium pricing through end-to-end workflow consolidation that displaces point-solution vendor relationships.
- Integrated Systems:Unified platforms combine cash positioning, payment execution, and bank reconciliation within single vendor contracts. Fortune 500 treasury departments in Germany and the United States are completing migrations to these consolidated stacks within 18-to-24-month implementation windows.
- Consulting Services:Professional services teams configure ERP integration layers and design treasury center operating models. Demand surges where legacy SAP and Oracle environments resist real-time data extraction without expensive middleware investment.
- Standalone Applications:Point solutions address specific functions like FX hedging or bank fee analysis.
- Technical Support:Ongoing maintenance contracts ensure ISO 20022 message format compatibility as correspondent networks migrate.
Integrated systems hold platform dominance. Consulting services are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Banking Authority's PSD3 audit trail mandates and the Monetary Authority of Singapore's cyber resilience certification are redirecting procurement budgets toward compliant treasury infrastructure. Corporate finance teams in financial hubs prioritize platforms that satisfy multi-jurisdictional regulatory requirements.
United States
Fortune 500 treasury departments in New York and Chicago are consolidating vendor relationships around cloud-native platforms with FedNow connectivity. The SEC's investment adviser custody rule mandates immutable audit trails that manual processes cannot satisfy. Buy-side institutions in Boston and San Francisco prioritize pre-certified regulatory reporting modules.
Germany
Automotive conglomerates in Stuttgart and Munich demand hybrid deployment architectures that satisfy Bundesbank operational resilience guidelines. The European Banking Authority's PSD3 framework compels replacement of legacy reconciliation tools with automated segregation-of-duties workflows. Industrial manufacturers in North Rhine-Westphalia are modernizing multi-entity cash forecasting infrastructure.
Singapore
Multinational corporations operating Asia-Pacific treasury centers from Singapore require cyber resilience certification for cloud-hosted financial infrastructure. The Monetary Authority of Singapore's standards filter vendor eligibility across regional deployment decisions. Financial institutions in the Marina Bay district are expanding fraud detection procurement as real-time payment rails widen attack surfaces.
India
Manufacturing conglomerates in Mumbai and Bangalore are modernizing treasury infrastructure under the Reserve Bank of India's Account Aggregator framework incentives. The central bank's push for corporate account aggregation creates white space for cloud-native cash visibility platforms. IT services exporters in Hyderabad are adopting automated forecasting to manage multi-currency receivables.
United Kingdom
Mid-market corporations in London and Manchester are driving subscription-based pricing adoption, favoring consumption-aligned cost structures over perpetual licenses. The Financial Conduct Authority's operational resilience requirements shape vendor selection criteria for cloud deployments. Fintech clusters in Edinburgh and Bristol are piloting AI-driven predictive analytics for dynamic cash flow forecasting.
Cash Management System Market Key Industry Players
Player mix skews toward cloud-native treasury specialists and ERP-embedded modules. The vendor base concentrates around two distinct capability clusters: bank connectivity aggregators and AI-driven analytics platforms. Strategic archetypes include multi-entity liquidity planners, receivables automation specialists, and payment rail orchestrators. Competitive dynamics center on ISO 20022 messaging certification and open banking API integration velocity.
Within the cloud-native specialist tier, Kyriba and HighRadius exemplify contrasting positioning strategies. Kyriba anchors the multi-entity liquidity planning archetype through treasury platforms designed for dispersed banking relationships. HighRadius occupies a position within AI-driven receivables automation, competing directly with traditional ERP treasury modules. TIS represents the bank connectivity aggregation archetype, controlling payment rail access across fragmented geographic banking networks. SAP Cash Management sits within the ERP-embedded category, leveraging existing enterprise software relationships to defend installed base positions.
| Leading Market Players |
|---|
| Nomentia |
| TIS |
| Kyriba |
| Trovata |
| Netgain |
| HighRadius |
| Agicap |
| CashAnalytics |
| SAP Cash Management |
| Others |
Cost & Logistics Intelligence
Cloud-native infrastructure scale economies concentrate vendor margins in multi-tenant SaaS architectures, compressing unit economics for on-premises deployments while elevating price floors for ISO 20022-certified platforms serving multinational treasury operations.
Pricing Analysis
Certification level creates the primary spread between vendor tiers, with ISO 20022-compliant platforms commanding premium positioning against legacy message-format alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by entity count, payment volume, and bank connectivity depth. Pricing pressure stems from mid-market subscription fatigue as CFOs scrutinize SaaS spend consolidation. Corporate treasury departments in the United Kingdom and Australia exhibit highest price sensitivity, while Fortune 500 liquidity managers in Germany and the United States prioritize functionality breadth over cost minimization.
Supply Chain Analysis
The United States and Germany anchor cloud infrastructure provisioning for treasury platforms, with Singapore emerging as Asia-Pacific hosting hub under Monetary Authority cyber resilience certification. Software development draws from India-based engineering centers, U.S.-based AI/ML research clusters, and European regulatory compliance specialists. Single-source vulnerability concentrates in SWIFT network connectivity modules, where regional bank API fragmentation forces redundant integration investments. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships for ERP deployment complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud migration tailwinds position this market in early-cycle expansion, with ISO 20022 standardization and open banking API proliferation creating sustained replacement demand for legacy treasury infrastructure.
For Market Incumbents: Consolidate around bank connectivity aggregation capabilities as open banking APIs proliferate and treasury teams reduce vendor counts. Defensive priority centers on embedding fraud detection modules into core platforms to counter AI-native challengers. Capacity addition in Singapore and Mumbai captures Asia-Pacific deployment momentum under local cyber resilience mandates. For New Entrants and Emerging Players: Anchor in India's Account Aggregator framework white space, where RBI incentives for corporate cash visibility modernization outpace incumbent presence. Manufacturing conglomerates in Mumbai and Bangalore represent the most penetrable segment. Go-to-market leverage through vertical ERP partnerships serving healthcare supply chains bypasses direct enterprise sales friction. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native treasury specialists with pre-certified regulatory reporting modules. Long-term viability over the analysis window favors platforms controlling end-to-end payment workflow automation rather than point-solution vendors facing margin compression. Acquisition target archetype: bank connectivity aggregators with fragmented geographic network coverage. Signal to watch: FedNow adoption velocity as proxy for fraud detection module procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20022 Certification Investment | Unlocks bank-agnostic connectivity for multinational treasury operations across correspondent networks. |
| Open Banking API Integration | Accelerates real-time cash positioning capabilities through direct financial institution data feeds. |
| AI-Driven Predictive Analytics Development | Enables dynamic cash flow forecasting that displaces spreadsheet-based treasury processes. |
| Embedded Finance Partnership | Distributes liquidity management modules through vertical ERP suites serving healthcare and retail. |
| Regional Cloud Infrastructure Expansion | Satisfies Monetary Authority of Singapore cyber resilience certification for Asia-Pacific eligibility. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC investment adviser custody rule filings, European Banking Authority PSD3 implementation guidance, and Monetary Authority of Singapore cyber resilience standards. Primary interviews engaged corporate treasury directors, bank connectivity specialists, ERP integration consultants, and regulatory compliance officers across the United States, Germany, Singapore, and India. Secondary validation drew from central bank policy documents, vendor certification registries, and enterprise software procurement databases. Bottom-up deployment estimates triangulated against top-down market sizing by product type and end-user segment.
Segmentation dimensions modeled include deployment architecture, solution integration level, end-user scale tier, and regional regulatory cluster across the projection horizon. CAGRs derived from trend extrapolation of ISO 20022 migration timelines, open banking API adoption curves, and real-time payment rail expansion patterns. Industry-specific forecast inputs incorporated ERP modernization cycle timing and treasury technology talent availability constraints.
Material uncertainties — central bank policy shifts on account aggregation, correspondent bank ISO 20022 adoption delays, and cybersecurity incident impacts on cloud hosting preferences — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory compliance timelines and enterprise software replacement cycles. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Credit Card Payments Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Netherland Payments Market
Payments
Ghana Mobile Money Market
Payments
Global Accounts Payable (AP) Automation Software Market
Payments
Middle East and Africa Payment Gateway Market
Payments
United Kingdom Payment Market
Payments
Fingerprint Payment Market
Payments
Online Payment Gateway Market
Payments
Japan POS Terminals Market
Payments
France Virtual Cards Market
Payments
Japan Mobile Payments Market
Payments
China Payment Gateway Market
Payments
Tanzania Mobile Money Market
Payments
Indonesia Payments Infrastructure Market
Payments
South Korea Digital Payments Market