
 Artificial Intelligence in Insurtech Market | 2026-2036
Artificial Intelligence in Insurtech Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in Insurtech Market Insights
The United Kingdom is rewriting insurance automation standards through its regulatory sandbox programs. IBM Corporation leverages extensive patent portfolios in machine learning for actuarial modeling. Microsoft Corporation anchors cloud infrastructure serving carrier-grade deployments across North America and Europe. Lemonade, Inc. differentiates through fully automated policy issuance and claims settlement workflows.
Artificial intelligence in insurtech encompasses algorithmic systems that ingest structured and unstructured data to automate insurance functions, typically processing claims images, policy documents, and telematics streams through neural networks with sub-second inference latency. Its primary commercial purpose is reducing loss-adjustment expense while improving risk-selection accuracy. Machine learning dominates current carrier spending as mature libraries enable rapid model deployment for pricing optimization. Natural language processing is expanding fastest as brokers and carriers automate policy review and customer correspondence. Cloud-based deployment captures the largest margin pool by eliminating capital-intensive data center builds and enabling elastic compute for catastrophe modeling.
The National Association of Insurance Commissioners in the United States drafts model governance standards for algorithmic decision-making, while the EU AI Act imposes risk-tiered conformity requirements on automated underwriting systems. HIPAA constrains how health insurers deploy predictive analytics on protected member data. Stakeholders must monitor evolving state-level algorithmic accountability bills that could fragment compliance requirements and reshape vendor qualification criteria.
Market Dynamics
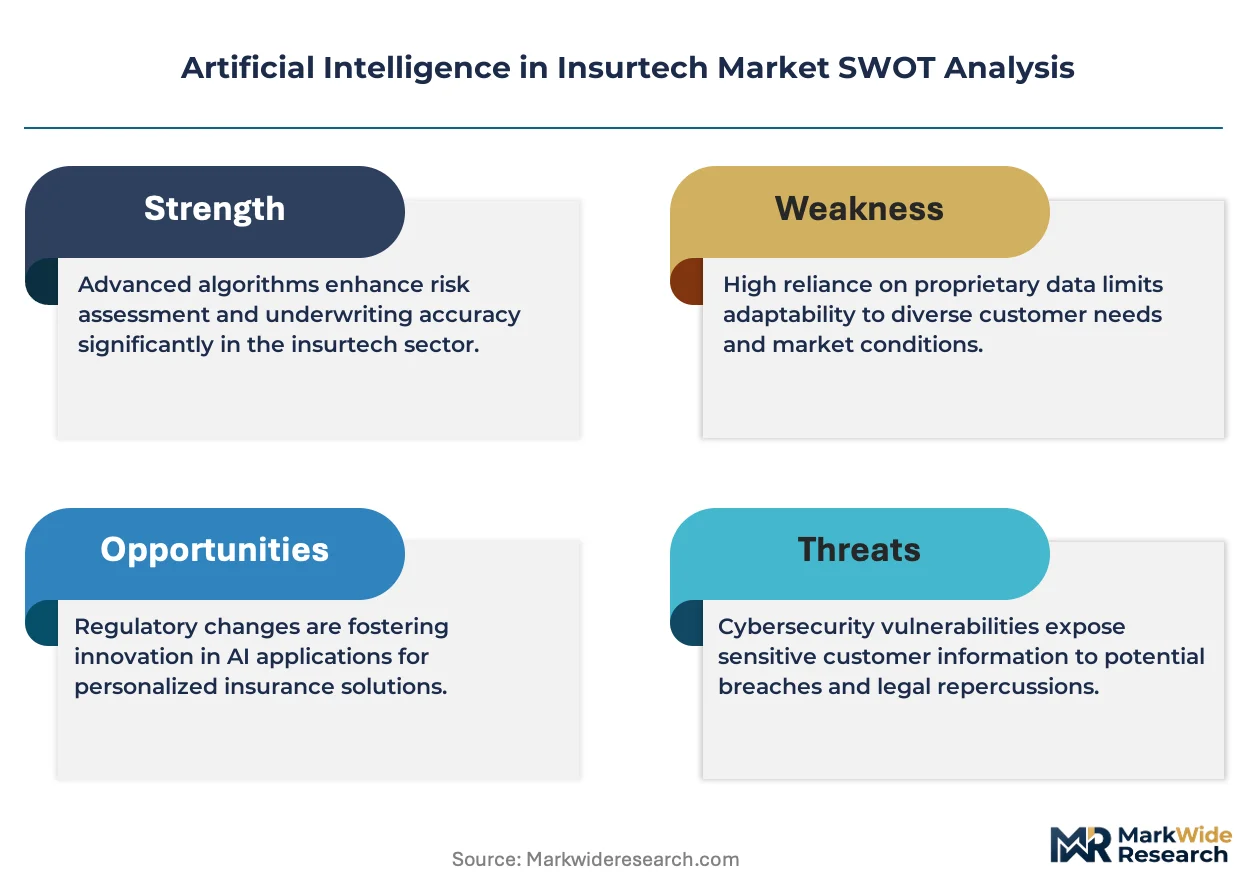
Property and casualty insurers are accelerating algorithmic underwriting adoption as the EU AI Act imposes risk-tiered conformity requirements, forcing carriers to restructure governance frameworks and vendor qualification criteria.
Growth Catalysts
- Automated Claims Processing:Neural networks analyzing telematics streams and damage imagery compress loss-adjustment expense cycles. Property insurers deploy computer vision for real-time damage assessment.
- EU AI Act Compliance Mandates:Risk-tiered conformity requirements for automated underwriting systems drive carrier investment in explainable machine learning. Member state regulators enforce algorithmic accountability standards.
- Cloud Infrastructure Elasticity:Catastrophe modeling demands burst compute capacity. North American carriers eliminate capital-intensive data center builds through carrier-grade cloud deployments.
Market Restraints
- Algorithmic Bias Liability:Fair lending scrutiny extends to insurance pricing. Regulators in multiple jurisdictions challenge proxy discrimination in predictive models.
- Data Silo Fragmentation:Legacy policy administration systems resist API integration. Carriers face seven-figure modernization costs to unify structured and unstructured data lakes.
- Talent Scarcity in Actuarial Data Science:Hybrid skill sets combining statistical modeling with neural network architecture command premium compensation. Recruitment pipelines lag carrier demand.
Strategic Opportunities
- Natural Language Processing for Policy Review:Brokers automate correspondence and document extraction. Commercial lines carriers reduce manual underwriting touchpoints.
- Embedded Insurance Distribution:Point-of-sale integration with e-commerce platforms and IoT devices. Automotive and real estate verticals present attachment opportunities.
- Regulatory Sandbox Participation:United Kingdom programs permit controlled testing of automated issuance workflows. Insurtech startups validate models under supervisory observation.
Industry Challenges
- Model Explainability Requirements:Regulators demand interpretable decision pathways for declined coverage. Black-box neural networks face scrutiny during market conduct examinations.
- Legacy System Integration Complexity:Decades-old policy administration cores resist real-time data ingestion. Middleware layers introduce latency and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in Insurtech Market |
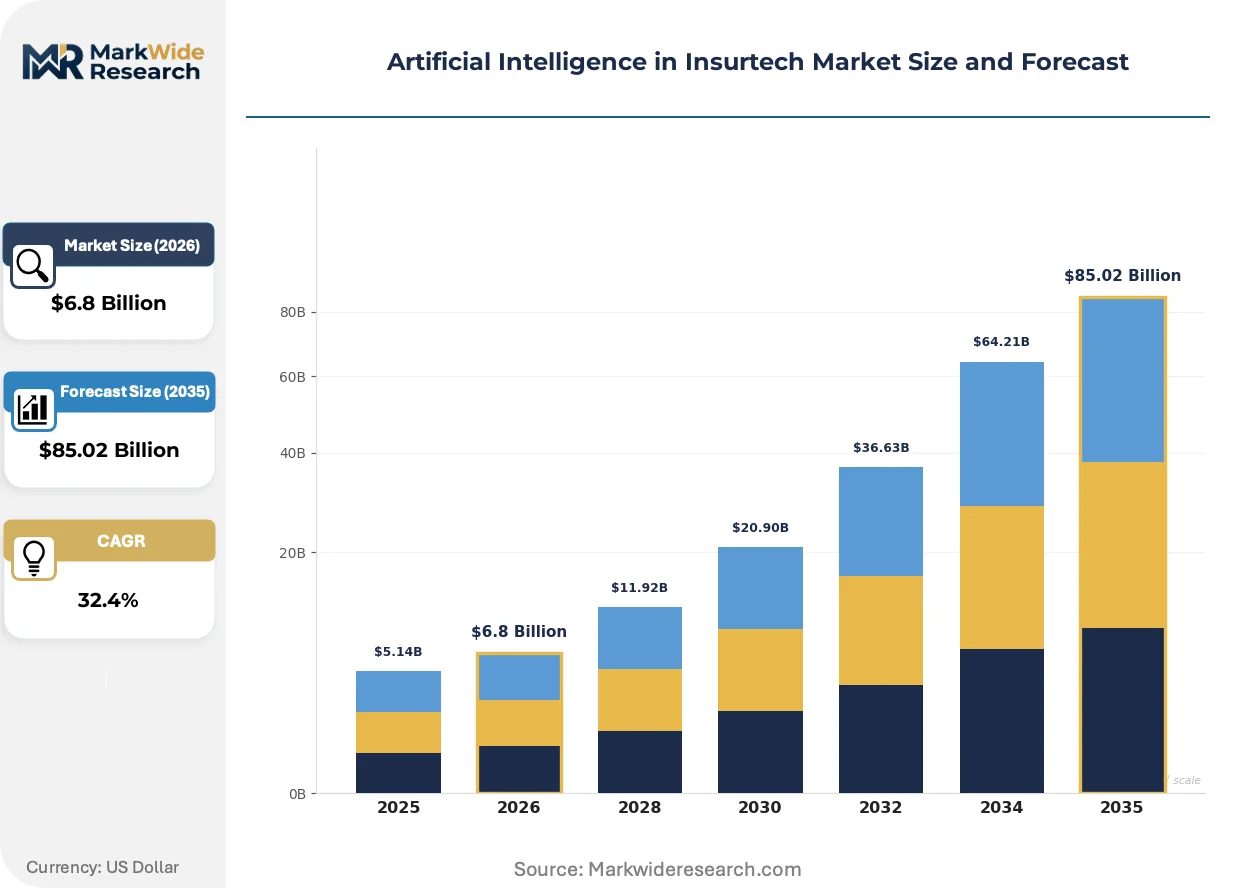
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $85.02 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fraud Detection, Claims Management, Underwriting Automation, Customer Engagement, Risk Assessment, Pricing Optimization Technology: Machine Learning, Natural Language Processing, Computer Vision, Predictive Analytics, Deep Learning, Robotic Process Automation End User: Insurance Carriers, Brokerages, Reinsurers, Actuarial Firms, Claims Adjustors, Policy Administrators Deployment: Cloud-Based, On-Premises, Hybrid, SaaS Platforms, Edge Computing, API Integrations |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Guidewire Software, Inc., Lemonade, Inc., Munich Re, Solera, Tractable, ZestyAI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in Insurtech Market Trends and Innovations
Machine learning architectures are migrating from batch processing toward real-time inference at the point of customer interaction, compressing quote-to-bind cycles and enabling dynamic pricing adjustments.
Transformer-based natural language processing is migrating from document classification to full policy generation. Commercial lines underwriters at midsize carriers adopt large language models for submission triage and exposure extraction. The technology is migrating from pilot programs to production deployments, displacing rules-based extraction engines and reducing manual review queues by half.
The EU AI Act establishes mandatory conformity assessments for high-risk automated underwriting systems. Carriers must document training data provenance and model performance metrics. European property insurers are responding by segregating algorithmic decision pathways into explainable rule sets and black-box score components.
Usage-based insurance procurement is reshaping personal auto coverage. Telematics-enabled pricing replaces annual renewals with continuous risk adjustment. Young driver segments in North American and European markets demonstrate willingness to trade privacy for premium reductions, accelerating sensor deployment across vehicle fleets.
Artificial Intelligence in Insurtech Market Segmentation
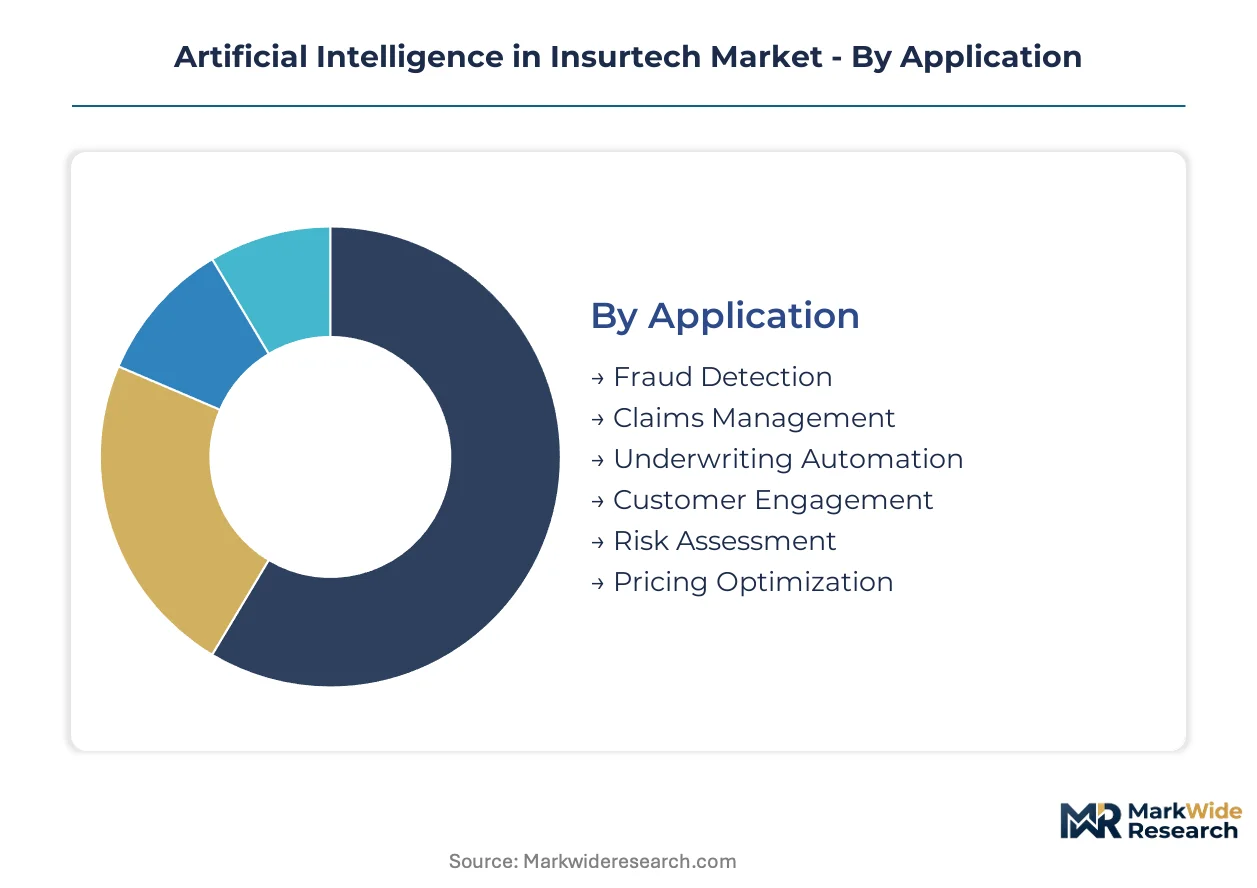
Insurtech AI segmentation reveals how technology maturity and deployment economics reshape vendor strategies. Carriers prioritize segments offering measurable loss-ratio improvement within compressed implementation timelines.
Application:
Mature automation functions coexist with emerging cognitive capabilities across the application spectrum.
- Claims Management:Neural networks process telematics streams and damage imagery to compress loss-adjustment expense cycles. Property insurers in the United States deploy computer vision for real-time damage assessment, reducing adjuster dispatch requirements.
- Underwriting Automation:Algorithmic risk selection ingests structured and unstructured data to accelerate quote-to-bind workflows. The EU AI Act forces European carriers to document training data provenance and model performance metrics, reshaping governance frameworks.
- Fraud Detection:Anomaly detection flags suspicious claim patterns before payout authorization.
- Customer Engagement:Chatbots and recommendation engines automate policy inquiries and cross-selling.
- Risk Assessment:Predictive models quantify exposure across property, casualty, and specialty lines.
- Pricing Optimization:Dynamic rating algorithms adjust premiums based on real-time behavioral data.
Claims Management retains volume leadership; Underwriting Automation holds the steepest expansion curve.
Technology:
Cost tier differentiation separates established libraries from compute-intensive architectures demanding specialized infrastructure.
- Machine Learning:Mature statistical libraries enable rapid model deployment for pricing optimization and risk segmentation. North American carriers favor gradient-boosted frameworks for their interpretability during regulatory examinations.
- Natural Language Processing:Transformer architectures automate policy review and customer correspondence. Commercial lines underwriters at midsize carriers adopt large language models for submission triage, displacing rules-based extraction engines.
- Computer Vision:Convolutional networks assess vehicle damage and property destruction from imagery.
- Predictive Analytics:Time-series forecasting supports reserving and catastrophe modeling.
- Deep Learning:Multi-layer neural networks handle complex pattern recognition in unstructured data.
- Robotic Process Automation:Software bots execute repetitive data entry and document routing tasks.
Machine Learning dominates current spending; Natural Language Processing is climbing the fastest as generative capabilities mature.
End User:
Customer type determines solution complexity, with direct carriers demanding integrated platforms while intermediaries prioritize modular tools.
- Insurance Carriers:Full-stack AI deployments spanning underwriting, claims, and distribution. Tier-one property and casualty insurers maintain captive data science teams building proprietary models.
- Brokerages:Workflow automation for submission triage and client correspondence. Independent agents in the United Kingdom leverage regulatory sandbox programs to test automated issuance workflows.
- Reinsurers:Catastrophe modeling and portfolio risk aggregation at scale.
- Actuarial Firms:Statistical consulting and reserve adequacy analysis.
- Claims Adjustors:Field assessment tools and settlement recommendation engines.
- Policy Administrators:Back-office automation for endorsements and renewals.
Insurance Carriers command the largest addressable spend; Brokerages are gaining share fastest as distribution digitizes.
Deployment:
Margin profile varies sharply by infrastructure model, with cloud eliminating capital intensity while on-premises retains control over sensitive data.
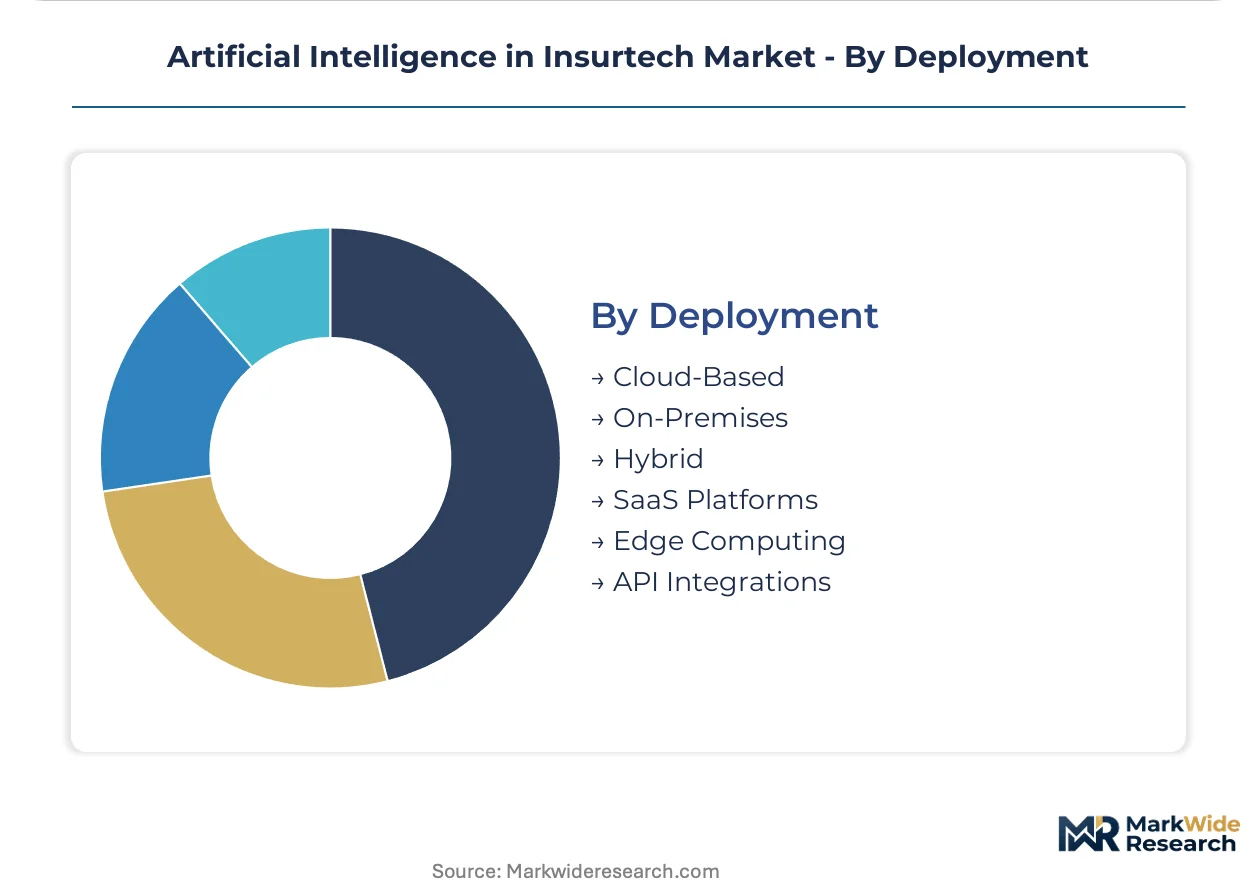
- Cloud-Based:Elastic compute for catastrophe modeling and burst processing demands. HIPAA constrains how health insurers deploy predictive analytics on protected member data, driving private cloud configurations.
- SaaS Platforms:Pre-configured AI modules with subscription pricing reduce implementation risk. Midmarket carriers eliminate seven-figure modernization costs through API-first architectures.
- On-Premises:Air-gapped systems for carriers with strict data residency requirements.
- Hybrid:Split workloads between cloud inference and on-premises training pipelines.
- Edge Computing:Real-time processing at telematics devices and mobile endpoints.
- API Integrations:Microservices connecting legacy policy administration to modern AI engines.
Cloud-Based deployment captures the largest margin pool; SaaS Platforms are expanding most quickly among capital-constrained carriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure providers cluster in the United States, while regulatory sandboxes in the United Kingdom and conformity assessments under the EU AI Act reshape vendor qualification criteria across Western Europe. Venture capital concentration in North American insurtech startups contrasts with carrier-led AI deployment in German and Japanese markets.
United States
Venture capital flows into predictive risk modeling startups across Silicon Valley and New York. The National Association of Insurance Commissioners drafts model governance standards for algorithmic decision-making. Property and casualty carriers in Texas and Florida deploy computer vision for hurricane damage assessment.
United Kingdom
Regulatory sandbox programs permit controlled testing of automated issuance workflows. The Financial Conduct Authority oversees algorithmic accountability in broker distribution channels. London-based insurtech startups validate machine learning models under supervisory observation.
Germany
Munich Re anchors reinsurance AI development for catastrophe modeling and portfolio risk aggregation. The Federal Financial Supervisory Authority enforces GDPR-aligned constraints on predictive analytics deployment. Industrial insurers in Baden-Württemberg integrate telematics for commercial auto fleets.
China
Internet giants deploy embedded insurance distribution through e-commerce platforms and mobile payment ecosystems. The Ministry of Industry and Information Technology issues algorithmic recommendation management provisions affecting automated underwriting. Shenzhen-based insurtech firms process claims imagery through convolutional networks.
Japan
Non-life insurers accelerate usage-based auto insurance adoption through original equipment manufacturer partnerships. The Financial Services Agency reviews governance frameworks for AI-driven claims settlement. Tokyo-based carriers deploy natural language processing for policy document extraction.
Artificial Intelligence in Insurtech Market Competitive Landscape
Technology conglomerates and specialized insurtech pure-plays split the market along infrastructure-versus-application lines. Cloud hyperscalers capture margin pools through carrier-grade elastic compute, while vertical software vendors embed machine learning into policy administration cores. Two strategic archetypes dominate: horizontal AI platforms licensing actuarial modeling tools, and full-stack carriers owning automated issuance workflows end-to-end. Competitive intensity centers on API-first architecture partnerships and regulatory sandbox participation rights.
Among technology conglomerates, IBM Corporation and Microsoft Corporation exemplify horizontal platform provision, supplying cloud infrastructure and machine learning libraries across North American and European carrier deployments. Lemonade, Inc. occupies a distinct position as a full-stack carrier archetype, integrating automated policy issuance with claims settlement workflows. These three entities represent the spectrum from infrastructure licensing to captive AI deployment, illustrating how vendor strategies diverge based on end-to-end control versus partnership-based distribution.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Guidewire Software, Inc. |
| Lemonade, Inc. |
| Munich Re |
| Solera |
| Tractable |
| ZestyAI |
| Others |
Pricing and Supply Chain Analysis
Transatlantic fiber-optic cable routes carry machine learning model training data and inference workloads between North American cloud hyperscalers and European carrier data centers, with bandwidth costs and latency constraints shaping how property insurers source algorithmic underwriting tools and how vendors tier their SaaS pricing across deployment regions.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for automated underwriting systems across member states, with explainable machine learning modules commanding premium positioning over black-box alternatives. Three-tier pricing structure across premium, standard, and economy levels separates carrier-grade deployments with full audit trails from midmarket SaaS configurations and basic API access tiers. Pricing pressure stems from venture-backed insurtech startups undercutting incumbent vendors with consumption-based models. Midmarket property carriers exhibit highest price sensitivity, while tier-one reinsurers prioritize compliance documentation over cost optimization.
Supply Chain Analysis
GPU clusters and specialized AI training hardware feed from Taiwan Semiconductor Manufacturing, NVIDIA's California design centers, and Samsung's South Korean foundries to power neural network development for claims processing and risk modeling. Cloud infrastructure providers draw from these concentrated semiconductor sources, creating single-source vulnerability for carriers dependent on elastic compute for catastrophe modeling. Distribution runs through hyperscaler marketplaces and direct enterprise licensing to insurance carriers, with API-first vendors bypassing traditional systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. The EU AI Act's conformity assessment requirements create switching costs that lock carriers into validated vendor relationships.
For Market Incumbents: Insulate core policy administration relationships by embedding machine learning modules directly into existing workflows, preventing displacement by API-first challengers. Acquire specialist computer vision firms to capture adjuster dispatch automation budgets before insurtech pure-plays consolidate this segment. Prioritize vertical integration into explainable AI tooling to meet emerging model interpretability mandates from the National Association of Insurance Commissioners.
For New Entrants and Emerging Players: Build out regulatory sandbox participation as a differentiated qualification pathway, leveraging United Kingdom Financial Conduct Authority programs to validate models under supervisory observation before broader European rollout. Target midsize commercial lines carriers in Germany and Japan, where legacy system fragmentation creates white-space for modular NLP-driven policy review tools. Pursue embedded insurance distribution partnerships with automotive OEMs and real estate platforms as the primary go-to-market channel.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified technology conglomerates seeking to divest non-core insurance software assets, particularly legacy policy administration platforms with captive carrier relationships but underinvested AI roadmaps. Long-term viability hinges on regulatory compliance automation capabilities rather than raw predictive accuracy. Monitor state-level algorithmic accountability legislation as the critical inflection signal for vendor consolidation timing. Quarterly review of carrier RFP language around explainability requirements is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | United Kingdom Financial Conduct Authority programs validate automated underwriting models under live supervisory observation. |
| Explainable AI Module Development | EU AI Act conformity assessments require documented training data provenance and interpretable decision pathways. |
| Cloud Infrastructure Partnership | Microsoft Azure and AWS carrier-grade deployments eliminate capital-intensive data center builds for property insurers. |
| Embedded Distribution Integration | Point-of-sale partnerships with automotive OEMs and real estate platforms reshape personal lines attachment economics. |
| Legacy System API Modernization | Middleware layers connecting decades-old policy administration cores to modern AI engines reduce seven-figure replacement costs. |
Research Methodology
The analysis maps claims management automation, underwriting algorithm deployment, fraud detection systems, and customer engagement platforms, each validated through chief data officers, actuarial science leads, regulatory compliance executives, and insurtech startup founders. Primary interviews with these stakeholders combined secondary sources including SEC 10-K filings, EU AI Act implementation guidance, National Association of Insurance Commissioners model governance drafts, and venture capital investment databases. Bottom-up deployment estimates triangulated against top-down carrier IT spending benchmarks.
Assumptions held fixed include current EU AI Act enforcement timelines and existing HIPAA constraints on health insurer predictive analytics, while cloud infrastructure pricing and state-level algorithmic accountability legislation were treated as variable inputs. Segmentation modeling incorporated application type, technology architecture, end-user category, and deployment mode across the projection horizon. CAGRs derived from carrier budget allocation surveys and vendor booking data, with catastrophe modeling compute demand and telematics sensor penetration serving as key forecast sensitivity inputs.
Practitioners should monitor regulatory enforcement variance across EU member states and state-level insurance commissioner election outcomes for early signals of compliance cost trajectory shifts. Forecasts reflect these assumptions without certainty. Quarterly review of carrier RFP requirements around model explainability and data provenance documentation is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance Technology
Singapore Insurtech Market
Insurance Technology
Latin America AI in Insurance Market
Insurance Technology
Europe Insurance Telematics Market
Insurance Technology
Germany AI in Insurance Market
Insurance Technology
China AI in Insurance Market
Insurance Technology
Japan AI in Insurance Market
Insurance Technology
Insurtech Market
Insurance Technology
Insurance Automation Market
Insurance Technology
North America Insurance Telematics Market
Insurance Technology
P and C Insurance Software Market
Insurance Technology
Middle East and Africa Insurtech Market
Insurance Technology
Middle East AI in Insurance Market
Insurance Technology
UK Insurtech Market
Insurance Technology
Asia-Pacific P&C Insurance Software Market
Insurance Technology
Global Digital Insurance Platform Market
Insurance Technology
Global Insurance Agency Software Market