
 Digital Payment Market | 2026-2036
Digital Payment Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Payment Market Intelligence
The shift from traditional retail to integrated eCommerce and social commerce is broadening the application scope for digital payment platforms. PayPal Holdings Inc. leverages its extensive user base to dominate consumer-to-consumer and small business transactions. Visa Inc. anchors its position through its vast card network infrastructure, enabling new contactless and mobile payment form factors. Meanwhile, Stripe Inc. specializes in providing API-driven payment processing for online businesses and software platforms, differentiating through developer-focused tools.
Digital payment refers to the transaction of funds or currency through an electronic medium, without the use of physical cash or checks. These systems rely on technologies like cryptographic encryption and tokenization to secure financial data during transmission between parties. Mobile wallets are gaining share over traditional credit card inputs, especially in high-growth markets. While the eCommerce vertical remains the largest segment, the transportation and education sectors represent high-potential areas for adoption due to their recurring payment models.
Regulatory frameworks such as the EU's General Data Protection Regulation (GDPR) and Payment Services Directive (PSD2) impose strict data security and consumer protection standards. In India, the Unified Payments Interface (UPI) framework, overseen by the Reserve Bank of India (RBI), has created a unique, state-backed infrastructure for instant payments. Navigating the divergent paths of national real-time payment systems and cross-border data privacy rules is the central strategic challenge for providers seeking to build unified platforms.
Market Dynamics
The central force shaping the digital payment market is the divergence between state-backed instant payment infrastructures and the push by global providers for unified, cross-border platforms. This dynamic creates friction between regulatory localization demands and the pursuit of platform scalability.
Growth Catalysts
- Real-Time Payment (RTP) Infrastructure:The proliferation of national RTP systems, such as India's UPI, enables instant bank-to-bank transfers. This accelerates the displacement of cash and traditional card rails for everyday transactions, particularly in emerging economies.
- eCommerce and Social Commerce Expansion:Growth in integrated eCommerce and social commerce platforms creates sustained demand for embedded, frictionless payment solutions. This is especially true within the small business and consumer-to-consumer segments.
- Open Banking Regulations:Mandates like the EU's Payment Services Directive (PSD2) compel financial institutions to share customer data via APIs. This fosters innovation from third-party payment providers and financial technology firms.
Market Restraints
- Data Localization Requirements:Strict data residency and privacy laws, including the EU's GDPR, create significant compliance overhead. These rules present technical barriers for providers attempting to operate a single, global technology stack.
- Fragmented Interoperability:A lack of interoperability between disparate national real-time payment systems complicates the execution of seamless cross-border transactions. This fragmentation inhibits the creation of a truly unified payment experience.
- Cybersecurity Threats:The persistent risk of sophisticated data breaches and phishing attacks erodes consumer trust. The high cost of implementing and maintaining advanced security measures acts as a barrier for smaller providers.
Strategic Opportunities
- Business-to-Business (B2B) Payments:Digitizing B2B payments, which remain heavily reliant on manual invoicing and paper checks, offers a vast area for growth. Solutions for automated accounts payable and receivable represent a significant opportunity.
- Underpenetrated Geographies:High smartphone penetration and large unbanked populations in Southeast Asia present a clear opportunity for mobile-first payment solutions. These services can bypass the need for traditional banking infrastructure.
- Value-Added Financial Services:Integrating services like micro-lending, insurance, or investment tools directly within payment apps can create new revenue streams. This transforms payment platforms into comprehensive financial hubs for users.
Industry Challenges
- Legacy System Integration:Connecting modern payment APIs to the core banking systems of incumbent financial institutions remains a complex and costly challenge. This technical hurdle slows the pace of innovation for established banks.
- Navigating Divergent Regulations:Managing compliance across a patchwork of national payment regulations and cross-border data transfer rules is a central operational challenge. This requires substantial legal and technical investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Payment Market |
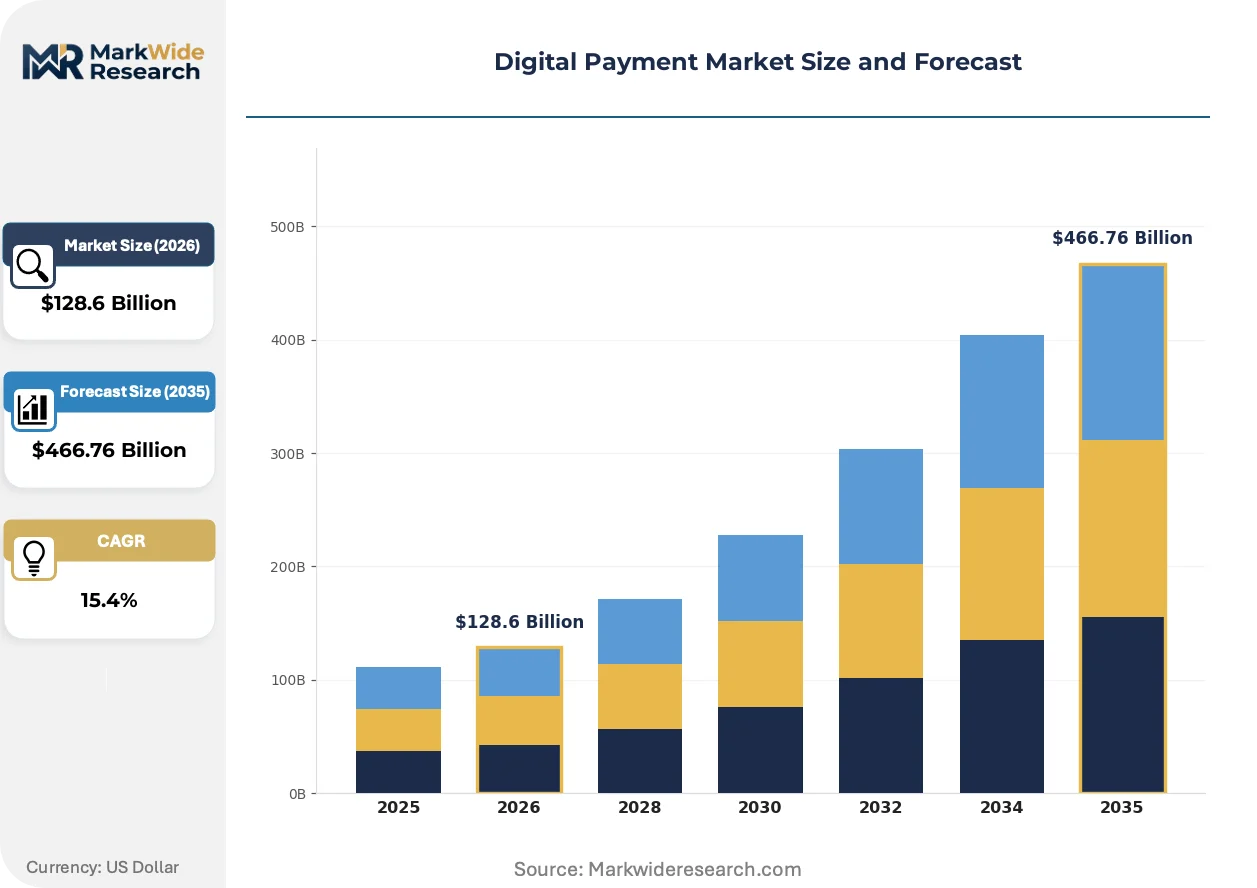
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $466.76 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
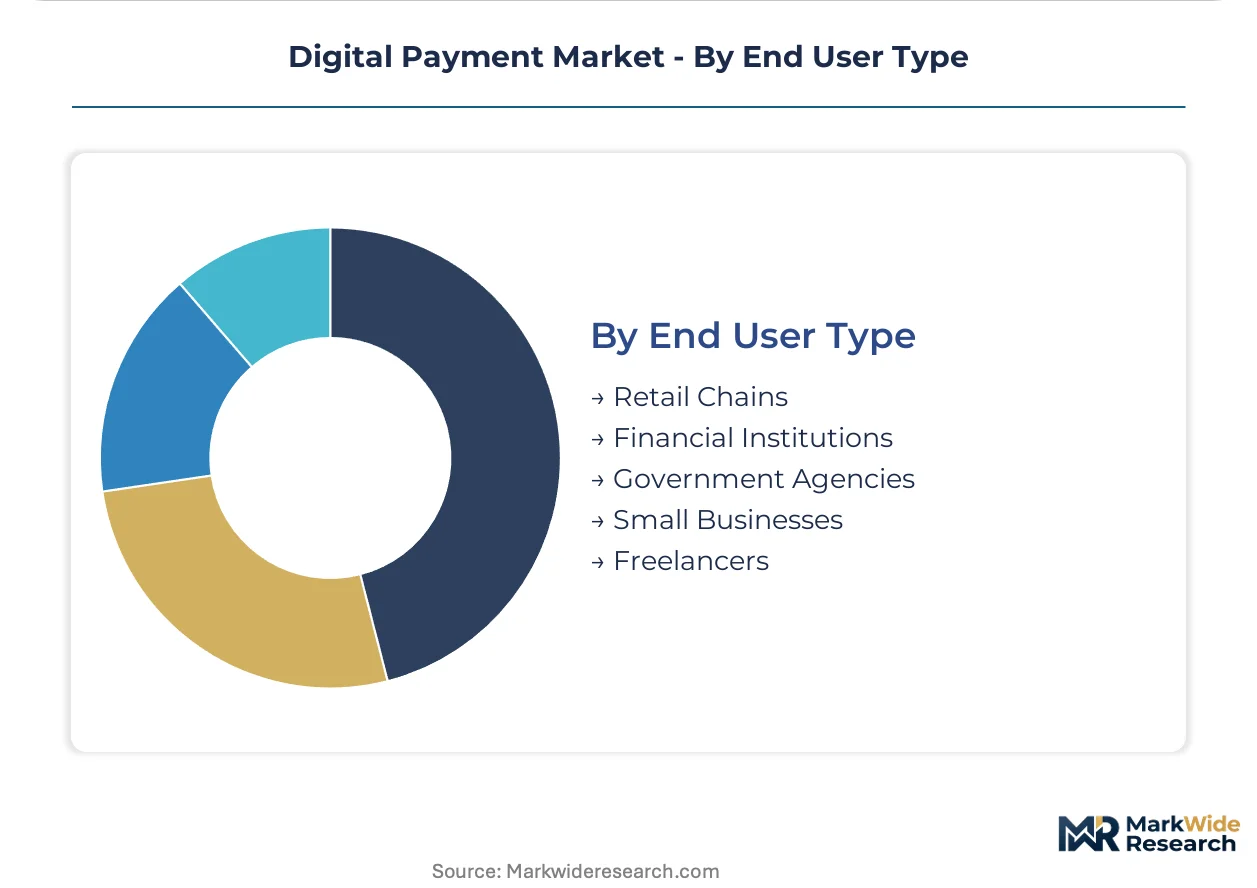
| Segmentation | Payment Method: Mobile Wallets, Credit Cards, Bank Transfers, Contactless Payments, E-Checks Industry Vertical: eCommerce, Hospitality, Telecommunication, Transportation, Education Deployment Mode: Cloud-Based, On-Premises, Hybrid, API Integration End User Type: Retail Chains, Financial Institutions, Government Agencies, Small Businesses, Freelancers |
| Companies Covered | PayPal Holdings Inc., Visa Inc., Mastercard Incorporated, Stripe Inc., Adyen N.V., Fiserv Inc., Block Inc., Amazon.com Inc., Ant Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Payment Market Strategic Shifts & Innovations
The market's evolution is defined by the embedding of payment functions directly into software and commerce experiences. This shift moves transaction capabilities from a standalone destination to an invisible, native feature within other applications, driven by API-first architectures.
Tokenization is a critical security technology that replaces sensitive card data with a unique, non-sensitive identifier. Online businesses and mobile wallet providers are rapidly adopting this method to secure stored credentials and enable one-click payments. This technology is consolidating consumer trust by minimizing the risk of data breaches, making digital transactions significantly safer than physical card usage.
Regulatory frameworks are actively shaping market structure, particularly in emerging economies. India's Unified Payments Interface (UPI), overseen by the RBI, has established a public utility for instant mobile payments, forcing providers to compete on user experience rather than proprietary networks. This model of state-backed infrastructure is being examined by other nations seeking to modernize their own payment systems.
A prominent behavioral shift is the consumer preference for mobile wallets over the manual entry of credit card details for online purchases. This trend is disrupting the traditional checkout form, favoring integrated wallet options that offer speed and enhanced security. The shift is most visible in high-frequency transaction environments such as urban transportation and quick-service restaurants across Asia and Europe.
Digital Payment Market Segmentation
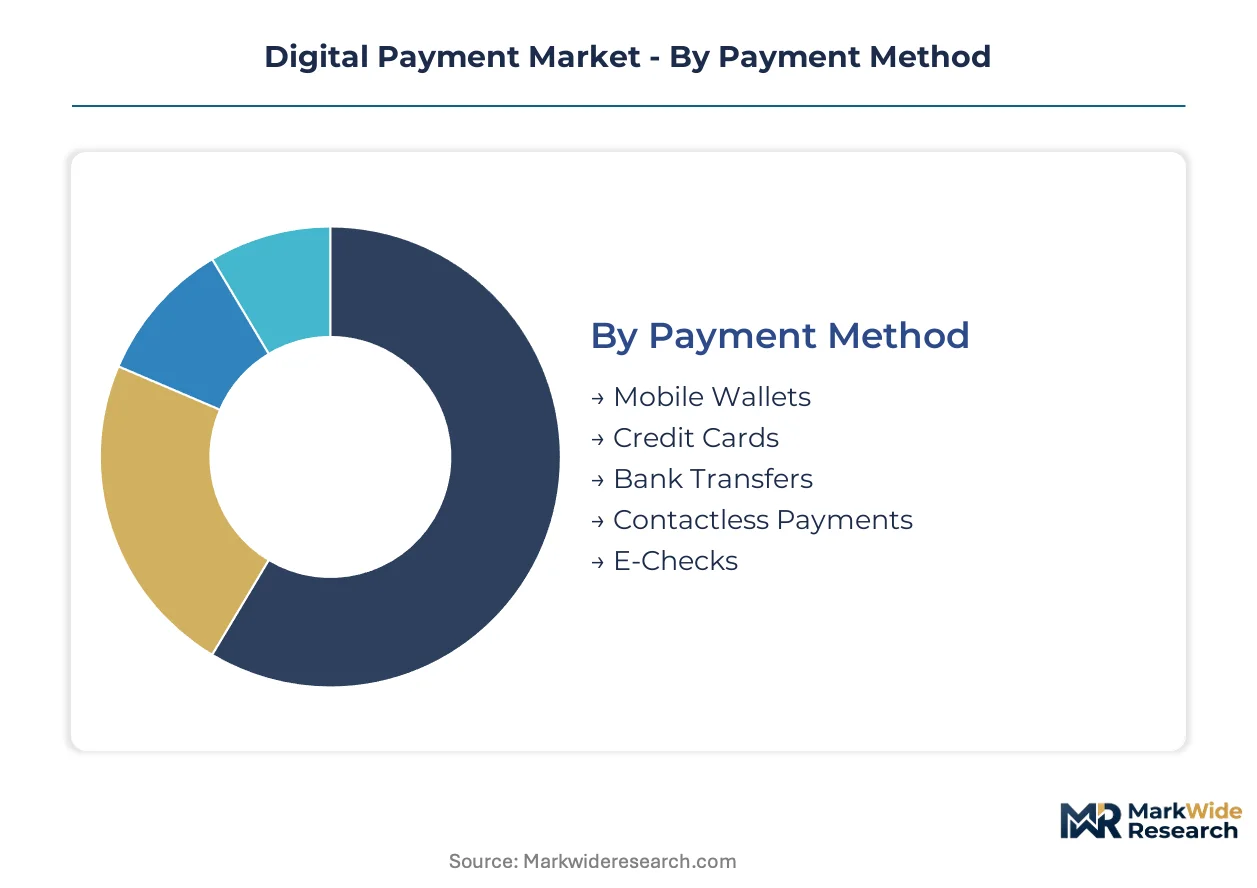
The digital payment market's segmentation reveals diverse adoption patterns, technology preferences, and regulatory compliance needs across its various facets. Understanding these distinctions is crucial for providers to tailor offerings, address specific market demands, and navigate the complex global landscape of financial technology.
Payment Method:
Different payment methods are subject to distinct regulatory oversight, from data privacy mandates like the EU's General Data Protection Regulation (GDPR) to central bank frameworks such as India's Reserve Bank of India-backed Unified Payments Interface (UPI).
- Mobile Wallets:These digital platforms store payment credentials, enabling transactions via smartphones or other devices, often secured by tokenization and biometric authentication. Demand for mobile wallets is concentrating in emerging economies like India and Southeast Asia, driven by high smartphone penetration and the push for financial inclusion.
- Credit Cards:Traditional plastic cards facilitate transactions through established global networks, offering credit lines and robust fraud prevention mechanisms. The widespread acceptance of credit cards globally anchors their position, particularly for high-value online purchases and international travel, despite competition from newer payment forms.
- Bank Transfers:Direct electronic movement of funds between bank accounts typically offers lower transaction fees and real-time processing capabilities in many national systems.
- Contactless Payments:Transactions completed by tapping a card or mobile device against a compatible terminal prioritize speed and convenience at physical points of sale.
- E-Checks:Electronic versions of paper checks provide a secure, trackable, and cost-effective method for business-to-business transactions, though processing times can be slower.
Leading the category by volume: Credit Cards. Growing fastest: Mobile Wallets.
Industry Vertical:
Digital payment solutions must adapt to the unique application requirements of various industry verticals, impacting implementation complexity and user experience.
- eCommerce:Online retail platforms require embedded, frictionless payment gateways that support diverse payment methods and cross-border transactions. This vertical continues to drive significant demand for secure, one-click payment solutions, particularly with the rise of social commerce platforms globally.
- Transportation:This sector demands high-frequency, mobile-first payment options for ticketing, ride-sharing, and public transit, often integrating with real-time payment systems. Urban centers across Europe and Asia are seeing rapid adoption of mobile wallet payments for public transport, enhancing commuter convenience.
- Hospitality:Hotels, restaurants, and travel services need integrated payment systems that handle reservations, point-of-sale transactions, and international guest payments.
- Telecommunication:Telcos utilize digital payments for subscription billing, top-ups, and value-added services, often leveraging mobile money platforms in developing markets.
- Education:Institutions adopt digital payment solutions for tuition fees, campus services, and online course payments, streamlining administrative processes for students and parents.
eCommerce drives the largest transaction volumes, while Transportation is expanding most quickly.
Deployment Mode:
The selection of a deployment mode carries significant implications for data security protocols and scalability requirements.
- Cloud-Based:Payment solutions hosted on remote servers offer scalability, reduced infrastructure costs, and continuous updates, often delivered as a Software-as-a-Service (SaaS) model. Cloud-based platforms enable rapid global expansion for payment providers, avoiding the need for extensive local hardware installations.
- API Integration:These developer-centric tools allow businesses to embed payment processing functionalities directly into their existing websites, applications, or software platforms. Stripe Inc. specializes in this mode, providing flexible tools for online businesses.
- On-Premises:Payment systems installed and maintained directly on a company's own servers provide maximum control over data and customization, suitable for highly regulated or large enterprises.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, balancing security, control, and scalability for complex enterprise environments.
Cloud-Based solutions lead in new deployments, with API Integration gaining share rapidly.
End User Type:
Specific end-user types necessitate customized digital payment functionalities, influencing transaction security and integration needs.
- Retail Chains:Large retail organizations require robust omnichannel payment solutions that integrate online, in-store, and mobile transactions seamlessly. These entities demand high-volume processing capabilities and advanced fraud detection systems to protect customer data.
- Financial Institutions:Banks and credit unions leverage digital payment technologies to modernize their core banking services, offer real-time transfers, and comply with evolving regulatory standards like PSD2. They often integrate new payment rails into their legacy systems to enhance customer experience.
- Government Agencies:Public sector entities adopt digital payments for tax collection, public service fees, and benefit disbursements, aiming for efficiency and transparency.
- Small Businesses:These enterprises seek affordable, easy-to-implement digital payment solutions for online sales, in-person transactions, and managing cash flow.
- Freelancers:Independent workers utilize digital payment platforms for receiving client payments, managing invoices, and facilitating cross-border transactions with speed and low fees.
Retail Chains represent substantial transaction volumes, and Small Businesses are increasingly adopting digital payment solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's designated fintech innovation zones drive digital payment market concentration across Southeast Asia. This strategic focus attracts investment and fosters the development of advanced payment solutions. The nation's regulatory environment supports cross-border digital financial services.
India
High smartphone penetration and the push for financial inclusion drive digital payment adoption in India. The Reserve Bank of India's Unified Payments Interface (UPI) framework has democratized instant mobile payments. Bengaluru's vibrant fintech ecosystem fosters continuous payment innovation.
United States
E-commerce expansion and the embrace of contactless payments fuel demand for digital solutions in the United States. Federal Reserve initiatives like FedNow aim to modernize real-time payments across the country. Silicon Valley, home to companies like Stripe, drives payment technology development and integration.
China
Mobile-first consumer behavior and the rapid growth of social commerce platforms define China's digital payment landscape. The People's Bank of China actively regulates payment service providers and promotes digital currency initiatives. Shanghai and Shenzhen lead in developing advanced mobile payment platforms and ecosystems.
Germany
Digitization of Business-to-Business (B2B) payments and open banking mandates accelerate digital payment adoption in Germany. The EU's Payment Services Directive (PSD2) compels financial institutions to open customer data via APIs. Frankfurt's financial hub integrates sophisticated digital payment solutions for European enterprises.
Singapore
Cross-border transaction volumes and smart city initiatives stimulate demand for advanced payment systems in Singapore. The Monetary Authority of Singapore (MAS) actively promotes fintech innovation through supportive regulatory sandboxes. The One-North innovation district supports payment gateway development and regional expansion.
Digital Payment Market Key Industry Players
Top-tier vendors anchor global digital payment processing, while specialized fintechs and regional players occupy niche segments. The market exhibits a tiered structure, with established card networks and digital wallets competing with API-driven payment processors. Strategic archetypes include infrastructure providers, platform specialists, and consumer-facing wallet operators. Dominant competitive moves involve strategic partnerships to expand reach and portfolio diversification into value-added financial services.
Within the consumer-facing wallet and peer-to-peer segment, PayPal Holdings Inc. exemplifies a broad user base model. Visa Inc. represents the global card network infrastructure providers, anchoring traditional and contactless payment forms. Stripe Inc. embodies the API-driven payment processing archetype, specializing in developer-focused tools for online businesses. These entities collectively highlight the market's segmentation into consumer platforms, network facilitators, and business-centric processing solutions, underscoring diverse strategies employed across the ecosystem.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Visa Inc. |
| Mastercard Incorporated |
| Stripe Inc. |
| Adyen N.V. |
| Fiserv Inc. |
| Block Inc. |
| Amazon.com Inc. |
| Ant Group |
| Others |
Cost & Logistics Intelligence
The shift to API-driven payment architectures is reshaping cost economics for providers, moving from fixed infrastructure investments to usage-based models, which decentralizes traditional supply concentration points.
Pricing Analysis
Demand for instant processing drives premium pricing for real-time payment solutions, while standard batch processing offers lower costs. Pricing models are primarily per-transactional, often tiered by volume. Price differentiation is driven by advanced security features and cross-border settlement capabilities. Pricing pressure stems from the commoditization of basic payment gateways, especially in high-volume domestic markets. Small businesses are highly price-sensitive, whereas financial institutions prioritize robust, compliant solutions.
Supply Chain Analysis
The mandate for multi-vendor integration drives platform providers to ensure diversified sourcing of core technology components. Geographic concentration for payment infrastructure development centers in the United States, India, and China. Key dependencies include cloud computing services and cryptographic hardware. A structural risk is the single-source vulnerability of specialized API providers. Distribution runs through direct integrations with merchants and partnerships with financial institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The digital payment market is currently in a technology-transition phase, with real-time payment systems rapidly displacing traditional batch processing infrastructure. This shift necessitates strategic adjustments across all stakeholder groups to remain competitive.
For Market Incumbents: Acquire specialized fintech capabilities to counter the threat of agile new entrants. Consolidate market share through strategic partnerships with emerging payment platforms, leveraging existing customer bases. Invest in advanced tokenization and fraud detection to maintain trust amidst rising cybersecurity risks. Deepen vertical integration into core processing infrastructure to control costs and enhance service reliability.
For New Entrants and Emerging Players: eCommerce platform providers represent a critical channel for embedding frictionless payment solutions. Target underpenetrated geographies like Southeast Asia with mobile-first payment applications, bypassing traditional banking infrastructure. Focus on providing API-driven tools for small businesses seeking integrated online sales and payment processing. A direct-to-developer go-to-market angle can accelerate adoption.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform specialists offering robust API-driven payment processing solutions. Long-term viability over a five-to-ten-year window favors companies with strong cross-border capabilities and compliance expertise. Target acquisition archetypes include firms with established real-time payment network integrations or innovative fraud prevention technologies. The signal to watch is the consistent growth in transaction volumes from embedded finance offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Real-Time Payment Network Integrations | This move enhances transaction speed and broadens market access for providers in emerging economies. |
| Develop Embedded Finance Solutions | Integrating micro-lending or insurance into payment apps creates new revenue streams for users. |
| Strengthen Cybersecurity and Tokenization | Robust security measures build consumer trust and protect sensitive financial data from breaches. |
| Pursue Cross-Border Regulatory Compliance | Navigating diverse data privacy laws like GDPR enables unified platform scalability across regions. |
| Target B2B Payment Digitization | Automating accounts payable offers significant efficiency gains for enterprises reliant on manual processes. |
Research Approach
Document review covered central bank reports, financial technology journals, and corporate financial filings, complemented by interviews with industry stakeholders. Primary research involved payment platform executives, fintech founders, financial institution compliance officers, and e-commerce payment managers. This approach combined bottom-up market sizing with top-down validation from industry experts. Secondary data sources included regulatory body publications and technology research databases.
The quantitative model produced detailed volume and value projections across the analysis window. Segmentation dimensions modeled included payment method, industry vertical, deployment mode, and end-user type, alongside regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers. Forecast inputs specifically considered smartphone penetration rates and regulatory shifts in emerging economies.
Caveats apply where significant geopolitical events or unforeseen regulatory changes could materially shift the outlook. Forecasts reflect assumptions regarding technological stability and sustained economic growth. Deviation in cybersecurity threat levels or open banking mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Global Virtual Cards Market
Payments
NFC Payments Market
Payments
Europe Payments Market
Payments
Slovakia POS Terminal Market
Payments
Contactless Payment Terminals Market
Payments
Nigeria Mobile Money Market
Payments
Mobile Card Reader Market
Payments
Global Payment Gateways Market
Payments
France Buy Now Pay Later Services Market
Payments
Wireless POS Terminals Market
Payments
Retail POS Terminals Market
Payments
Australia Buy Now Pay Later Services Market
Payments
United States Payments Market
Payments
M Commerce Payment Market
Payments
Digital Transfer Services Market
Payments
US Virtual Cards Market