
 UAE Weight Loss Market | 2026-2036
UAE Weight Loss Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Weight Loss Market Intelligence
The UAE weight loss landscape is recalibrating around a widening split between premium medical-grade interventions and mass-market commodity offerings. Abbott Laboratories leverages its clinical nutrition portfolio to anchor the premium hospital and clinic channel. Herbalife competes through direct-selling networks that dominate home-based consumer segments. Novo Nordisk specializes in prescription metabolic therapies that occupy the highest-margin tier of physician-supervised weight management.
Weight loss encompasses clinically supervised reduction of body mass through pharmaceutical intervention, nutritional modification, physical activity protocols, or surgical procedures, with measurable outcomes tracked via BMI reduction, waist circumference, and metabolic biomarker improvement. The dietary supplements segment sustains the highest volume base through over-the-counter accessibility, while meal replacement products capture concentrated margin pools in corporate wellness contracts. Fitness equipment trails in growth velocity as digital service alternatives displace capital-intensive home purchases.
MOHAP, the Dubai Health Authority, and ADQ's healthcare platforms collectively enforce product registration, advertising standards, and clinical efficacy claims that filter market entrants. The UAE's mandatory health insurance framework, overseen by the national insurance regulator, increasingly covers bariatric and metabolic interventions, redirecting patient flows toward approved provider networks. Stakeholders must monitor how MOHAP's evolving digital health licensing rules reshape telemedicine-based weight loss service delivery models.
Market Dynamics
MOHAP's tightened nutrition labeling standards are compressing formulation cycles for packaged weight loss products while redirecting R&D budgets toward clinical-grade evidence generation. This regulatory pressure is splitting the market between compliant premium offerings and reformulated mass-market lines.
Growth Catalysts
- Corporate Wellness Mandates:Abu Dhabi and Dubai government entities now require metabolic screening in employee health packages. This institutional demand pulls meal replacement and supervised program subscriptions into enterprise procurement pipelines.
- MOHAP Nutrition Labeling Standards:The 2024 enforcement of front-of-pack calorie disclosure rules forces transparency that advantages clinically validated products over legacy supplement brands.
- Medical Tourism Infrastructure:Dubai Healthcare City's bariatric surgery clusters attract GCC nationals seeking physician-supervised interventions unavailable in home markets.
Market Restraints
- Import Dependency for Active Pharmaceuticals:GLP-1 agonists and peptide-based metabolic therapies rely on European and North American API suppliers. Geopolitical friction or cold-chain disruption exposes inventory gaps.
- MOHAP Advertising Restrictions:The health authority's 2023 ban on before-and-after imagery in weight loss marketing compresses customer acquisition channels for direct-selling networks.
- Substitution by Lifestyle Apps:Free or low-cost digital fasting trackers and AI meal planners displace paid subscription services among price-sensitive Emirati consumers.
Strategic Opportunities
- Ras Al Khaimah Wellness Corridor:The emirate's lower operational costs and emerging hospitality infrastructure create white space for residential metabolic rehabilitation programs targeting GCC medical tourists.
- Telemedicine Licensing Evolution:MOHAP's draft framework for remote prescription of weight management pharmaceuticals opens channel innovation for clinic networks seeking geographic expansion without physical infrastructure.
- Employer Incentive Alignment:The national insurance regulator's pilot program tying premium reductions to documented employee BMI improvement creates a regulatory tailwind for corporate wellness providers.
Industry Challenges
- Specialized Bariatric Nursing Shortage:UAE medical schools produce insufficient trained personnel for post-surgical care coordination. Recruitment from Philippines and Indian subcontinent markets drives compensation inflation.
- Dual Certification Burden:Products claiming clinical efficacy require simultaneous MOHAP food supplement registration and Dubai Health Authority medical device classification. Timeline misalignment delays commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Weight Loss Market |
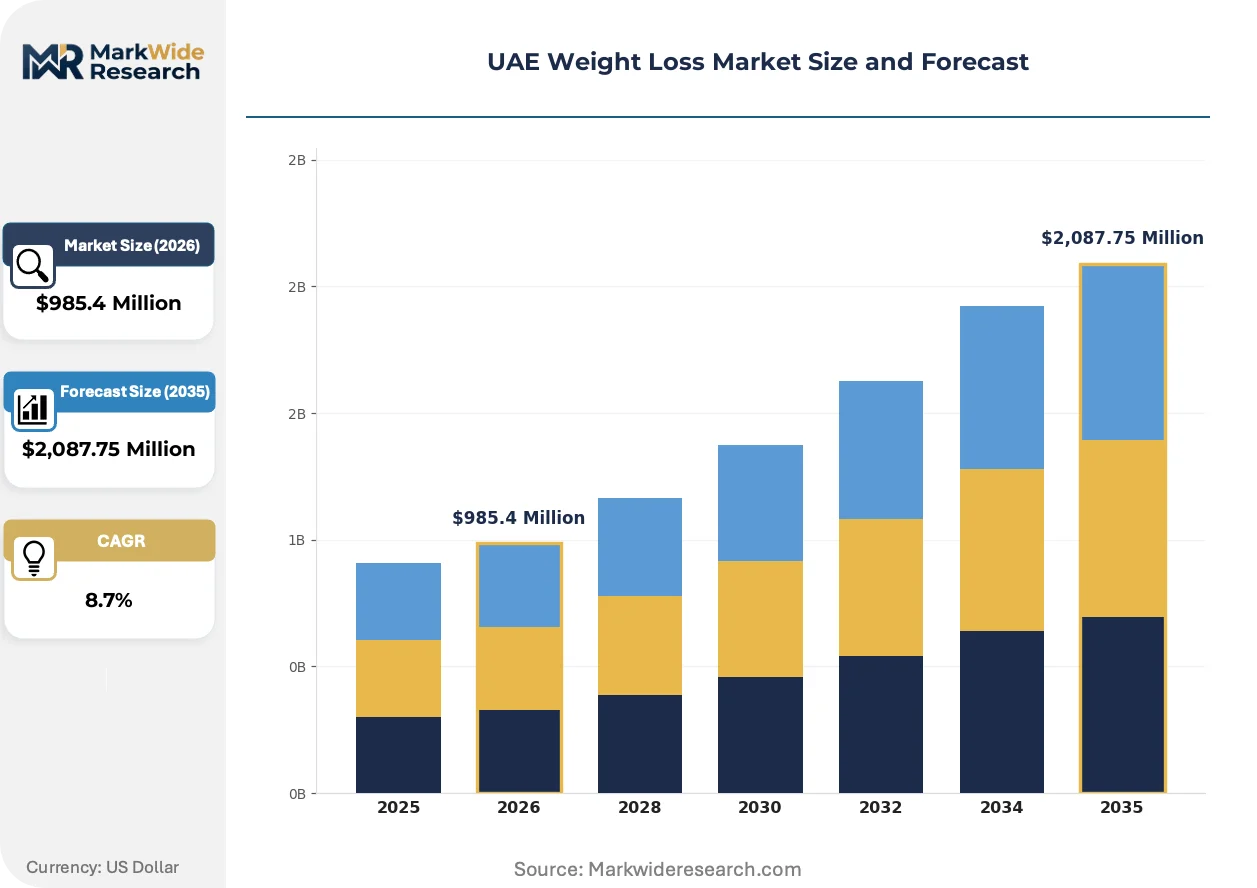
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacement, Weight Loss Programs, Fitness Equipment Consumer Type: Individuals, Corporate Clients, Health Clubs, Online Shoppers Distribution Channel: Pharmacies, Supermarkets, E-commerce, Health Stores Service Type: Personal Training, Nutrition Coaching, Online Consultation, Group Sessions |
| Companies Covered | Abbott Laboratories, Glanbia, Eli Lilly and Company, VIVUS LLC, Dardoc Health Technologies Limited, Novo Nordisk, Herbalife, Atkins Nutritionals, Nestlé Health Science, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Weight Loss Market Strategic Shifts & Innovations
Continuous glucose monitoring devices are migrating from diabetic management into preventive metabolic optimization. This hardware shift rewires how consumers perceive weight loss, reframing it as real-time biomarker control rather than episodic dieting.
CGM hardware paired with AI-driven meal recommendation engines is rewriting the competitive architecture of the home-based weight management segment. Affluent Emirati consumers now demand glucose curve visibility before committing to subscription nutrition services. Hardware-enabled coaching contracts are compressing margins for traditional supplement-only providers who lack biometric integration capabilities.
MOHAP's 2024 digital health licensing framework mandates clinical validation for algorithmic diet recommendations. This policy compresses the market for unvalidated wellness apps while privileging hospital-affiliated platforms with existing IRB infrastructure. Dubai-based telemedicine providers are restructuring compliance teams to secure the new category permits before competitors.
Employer procurement of weight management benefits is consolidating around outcome-verified contracts. Abu Dhabi sovereign wealth-linked entities now require documented waist circumference reduction before releasing milestone payments to wellness vendors. This behavioral shift is most visible in oil and gas sector contracts, where occupational health budgets face heightened scrutiny.
UAE Weight Loss Market Segmentation
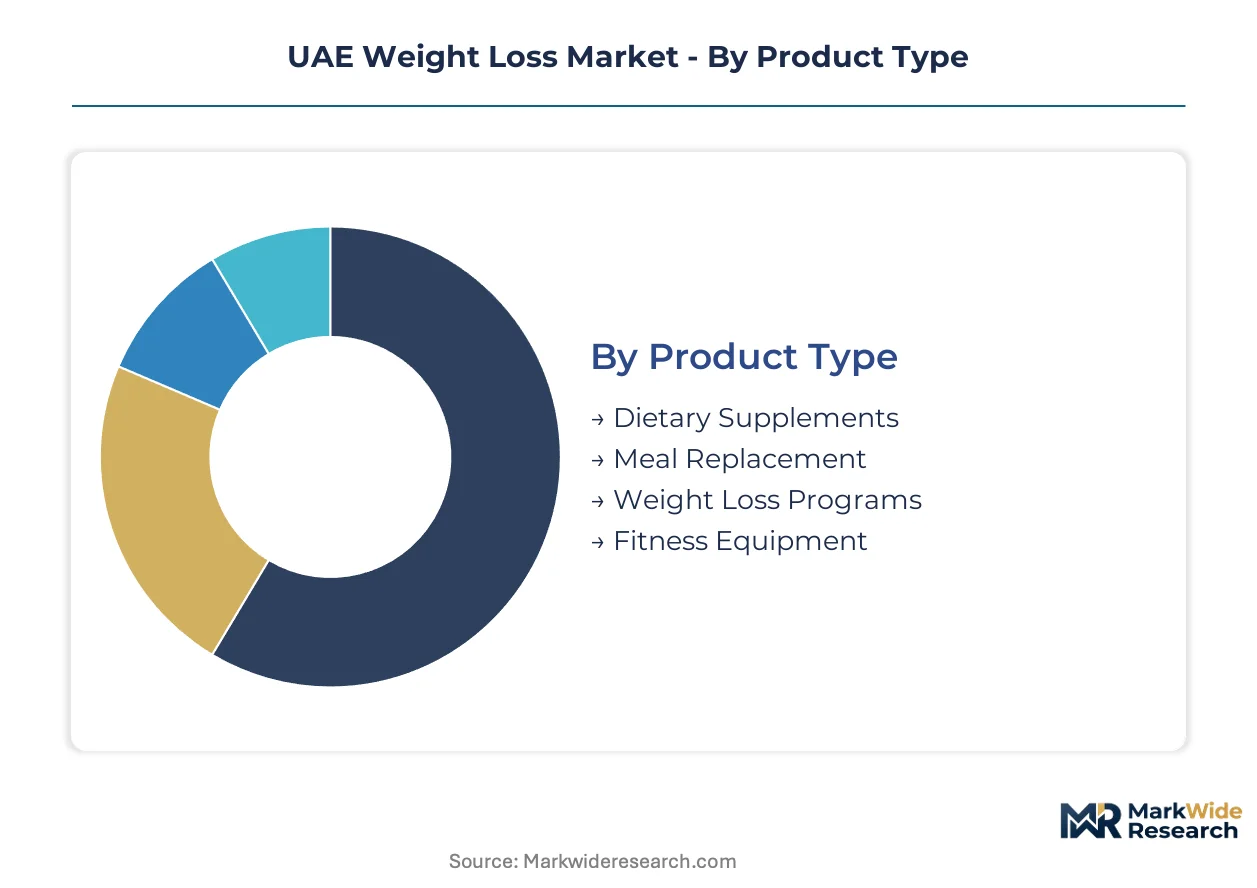
Segmentation in the UAE weight loss market reveals how regulatory pathways and procurement channels fragment commercial opportunity. Each dimension carries distinct compliance burdens and margin profiles that shape vendor positioning.
Product Type:
Dietary supplements require MOHAP food supplement registration, while meal replacement products claiming clinical efficacy face dual certification through Dubai Health Authority medical device classification. Weight loss programs and fitness equipment operate under lighter advertising standards but compete for institutional procurement slots.
- Dietary Supplements:Over-the-counter formulations including thermogenics, fiber complexes, and herbal extracts dominate pharmacy shelf space. Demand concentrates among individual consumers in Sharjah and Ajman emirates where price sensitivity exceeds Dubai levels, constrained by MOHAP's tightened nutrition labeling standards that force transparency on ingredient sourcing.
- Meal Replacement:Clinically formulated shakes and bars with documented macronutrient profiles. Corporate wellness contracts in Abu Dhabi government entities pull volume through enterprise procurement pipelines, with documented BMI outcomes now required for vendor retention under national insurance regulator pilot programs.
- Weight Loss Programs:Supervised protocols combining dietary intervention with behavioral coaching. Medical tourism clusters in Dubai Healthcare City anchor premium positioning.
- Fitness Equipment:Home-use devices and wearable biometric hardware. Digital service alternatives displace capital-intensive purchases among younger Emirati demographics.
Dietary supplements sit at the top of the volume ranking, with meal replacement climbing the fastest.
Consumer Type:
Cost tier stratification separates mass-market individual purchasers from enterprise-scale corporate contracts that command volume discounts and outcome verification clauses.
- Individuals:Direct-to-consumer purchasers seeking home-based solutions. E-commerce penetration in Dubai and Abu Dhabi enables subscription model adoption, though MOHAP advertising restrictions on before-and-after imagery compress customer acquisition efficiency for direct-selling networks.
- Corporate Clients:Government entities and sovereign wealth-linked enterprises procuring metabolic screening packages. Abu Dhabi and Dubai mandates now require employee health packages to include documented waist circumference reduction, with milestone payments tied to verified outcomes.
- Health Clubs:Facility-based operators reselling supervised programs and equipment access. Ras Al Khaimah's emerging hospitality infrastructure creates white space for residential metabolic rehabilitation targeting GCC medical tourists.
- Online Shoppers:Digital-native consumers comparing algorithmic diet recommendations across platforms. MOHAP's digital health licensing framework mandates clinical validation for AI-driven meal planners, compressing the market for unvalidated wellness apps.
Individuals anchor current volume, with corporate clients gaining share fastest as procurement consolidates around outcome-verified contracts.
Distribution Channel:
Channel selection determines which regulatory scrutiny applies — pharmacies face prescription verification requirements, while e-commerce platforms navigate MOHAP's evolving telemedicine licensing rules for remote pharmaceutical delivery.
- Pharmacies:Licensed retail outlets with trained personnel for supplement counseling. Dubai's premium clinic clusters concentrate high-margin metabolic therapy dispensing, though import dependency for GLP-1 agonists exposes inventory gaps during cold-chain disruptions.
- Supermarkets:Mass-market retail with front-of-pack calorie disclosure compliance. The 2024 enforcement of labeling rules advantages reformulated product lines with transparent formulation.
- E-commerce:Digital platforms enabling subscription nutrition services and hardware-enabled coaching contracts. Affluent Emirati consumers now demand glucose curve visibility before committing, compressing margins for traditional supplement-only providers lacking biometric integration.
- Health Stores:Specialized retail emphasizing natural and organic positioning. Limited penetration outside Dubai and Abu Dhabi urban cores.
Pharmacies retain the highest margin per transaction, with e-commerce expanding most quickly as telemedicine licensing evolution opens channel innovation.
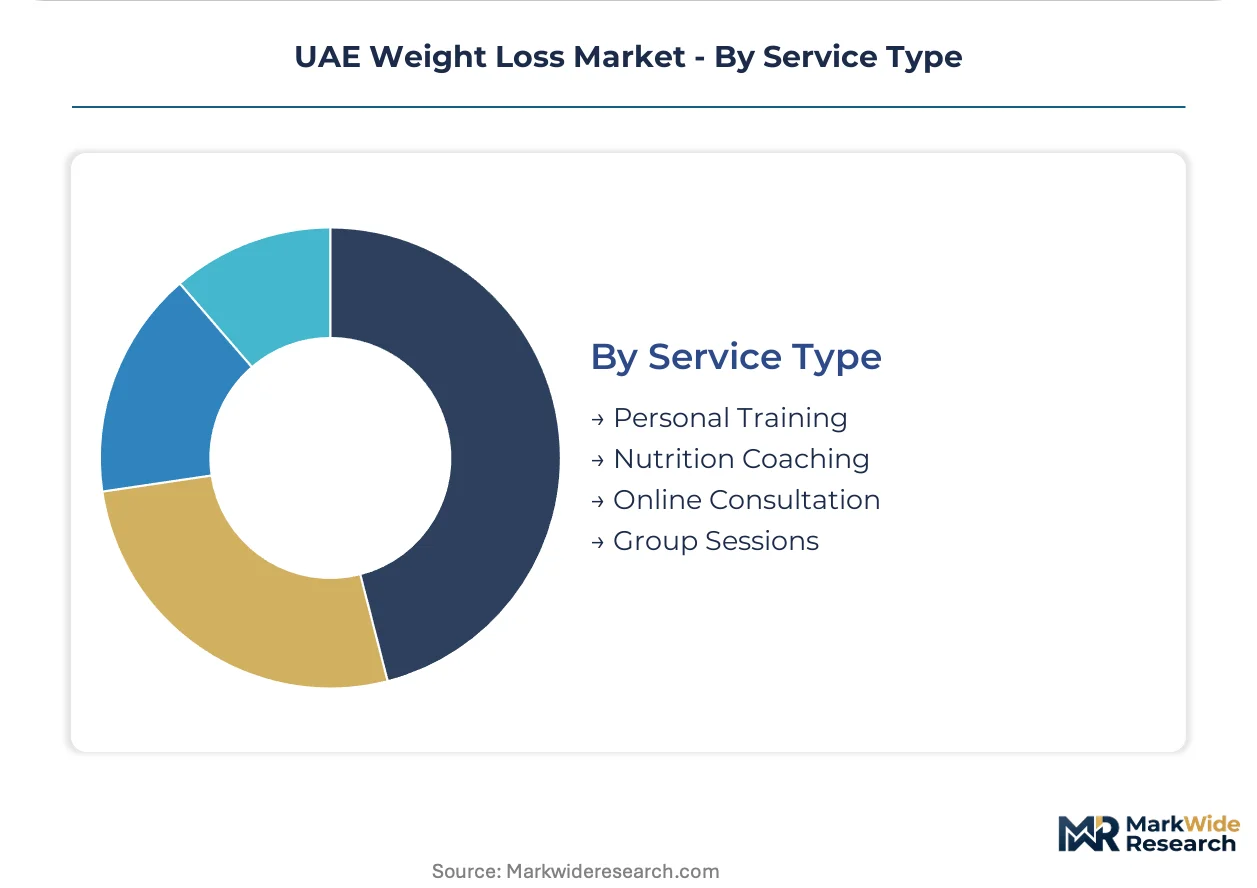
Service Type:
Maturity differentiation separates established in-person modalities from emerging digital formats still navigating regulatory classification.
- Personal Training:One-on-one physical activity supervision in gym or home settings. Oil and gas sector occupational health budgets in Abu Dhabi face heightened scrutiny, redirecting procurement toward outcome-measurable interventions.
- Nutrition Coaching:Registered dietitian-led dietary modification protocols. Specialized bariatric nursing shortage across UAE medical schools drives compensation inflation and care coordination gaps.
- Online Consultation:Remote delivery of weight management guidance via video or chat. MOHAP's draft framework for remote prescription of pharmaceuticals creates regulatory tailwinds for clinic networks seeking geographic expansion without physical infrastructure.
- Group Sessions:Cohort-based behavioral modification programs. Lower per-capita economics limit penetration outside corporate wellness contracts.
Personal training holds the largest installed base, with online consultation showing the steepest expansion trajectory as digital health licensing clarifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized bariatric nursing talent clusters in Dubai and Abu Dhabi anchor the UAE's metabolic intervention capacity, while Ras Al Khaimah's emerging hospitality infrastructure pulls residential rehabilitation investment northward.
Dubai
Medical tourism demand from GCC nationals concentrates in Dubai Healthcare City's bariatric surgery clusters, where physician-supervised interventions unavailable in home markets attract cross-border patients. MOHAP's 2024 digital health licensing framework mandates clinical validation for algorithmic diet recommendations, compressing unvalidated wellness apps while privileging hospital-affiliated platforms. Jumeirah and Downtown Dubai host premium clinic networks dispensing GLP-1 agonists, though cold-chain import dependency from European API suppliers exposes inventory vulnerability.
Abu Dhabi
Corporate wellness mandates in sovereign wealth-linked entities now require documented waist circumference reduction before milestone payment release to vendors. The national insurance regulator's pilot program ties premium reductions to verified employee BMI improvement, redirecting procurement toward outcome-measurable interventions. Yas Island and Saadiyat Island hospitality clusters are integrating metabolic screening into executive health packages for oil and gas sector occupational health budgets.
Sharjah
Price-sensitive individual consumers drive dietary supplement volume through pharmacy and supermarket channels, with demand exceeding Dubai levels for over-the-counter thermogenics and fiber complexes. MOHAP's tightened nutrition labeling standards force transparency on ingredient sourcing, advantaging reformulated product lines. The emirate's lower commercial rents enable supplement distributors to maintain margin buffers against compliance cost inflation.
Ras Al Khaimah
Lower operational costs and emerging hospitality infrastructure create white space for residential metabolic rehabilitation programs targeting GCC medical tourists. Al Marjan Island and Mina Al Arab developments are positioning wellness-branded residential offerings against Dubai's premium pricing. The emirate's nursing recruitment from Philippines and Indian subcontinent markets addresses UAE-wide bariatric care coordination gaps.
Northern Emirates
Ajman and Fujairah concentrate mass-market meal replacement distribution through supermarket channels, with front-of-pack calorie disclosure compliance advantages for transparent formulation. E-commerce penetration enables subscription model adoption among younger demographics, though MOHAP advertising restrictions on before-and-after imagery compress customer acquisition efficiency. The region's lower healthcare infrastructure density limits clinic-based program penetration.
UAE Weight Loss Market Key Industry Players
Top-tier vendors anchor hospital and clinic channels, while direct-selling networks and mass-market distributors occupy lower-margin tiers. Abbott Laboratories, Novo Nordisk, and Eli Lilly concentrate on prescription metabolic therapies and clinical nutrition portfolios requiring Dubai Health Authority medical device classification. Herbalife and Glanbia exemplify direct-selling and ingredient supply archetypes competing for home-based consumer segments. Strategic moves concentrate on telemedicine licensing acquisition and corporate wellness contract consolidation.
Within the clinical-grade tier, Abbott Laboratories and Novo Nordisk occupy positions exemplifying premium channel anchoring through hospital-affiliated dispensing networks. Eli Lilly and Company sits within the prescription metabolic therapy specialization. Among mass-market nutrition providers, Herbalife represents the direct-selling network archetype dominating home-based subscription models. Glanbia exemplifies the ingredient and formulation supply position serving branded product manufacturers. Atkins Nutritionals and Nestlé Health Science anchor positions in the meal replacement and macronutrient-controlled food segments. VIVUS LLC and Dardoc Health Technologies Limited occupy telemedicine-enabled service delivery positions awaiting MOHAP remote prescription framework finalization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Glanbia |
| Eli Lilly and Company |
| VIVUS LLC |
| Dardoc Health Technologies Limited |
| Novo Nordisk |
| Herbalife |
| Atkins Nutritionals |
| Nestlé Health Science |
| Others |
Cost & Logistics Intelligence
Sovereign-backed healthcare platforms and family-owned supplement distributors anchor UAE supply networks, translating procurement scale into pricing discipline that compresses margins for mid-tier competitors lacking hospital affiliation or direct-selling infrastructure.
Pricing Analysis
Bundled metabolic rehabilitation packages command premium positioning against unbundled supplement-only transactions. Three-tier pricing structure across premium, standard, and economy levels separates physician-supervised programs from direct-selling subscriptions and mass-market pharmacy SKUs. Price differentiation rests on clinical validation grade and corporate wellness contract scale. Cost compression in the economy tier intensifies because MOHAP's labeling transparency rules force reformulation investments. Individual consumers in Northern Emirates exhibit highest price sensitivity; corporate procurement officers in Abu Dhabi sovereign entities show lowest.
Supply Chain Analysis
MOHAP food supplement registration and Dubai Health Authority medical device classification create dual certification gating that filters vendor participation. Active pharmaceutical ingredients for GLP-1 agonists draw from Denmark, Switzerland, and the United States. Cold-chain logistics, peptide synthesis substrates, and specialized bariatric instrumentation constitute critical input dependencies. Single-source vulnerability runs through European API suppliers exposed to geopolitical friction. Distribution runs through hospital-affiliated pharmacies, direct-selling networks, and e-commerce platforms navigating telemedicine licensing evolution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE weight loss market functions as a stable compounder, with employer mandate expansion and medical tourism infrastructure providing durable demand underpinnings that resist cyclical fluctuation.
For Market Incumbents: Lock in corporate wellness contract renewals through outcome-verified BMI reduction guarantees before competitors secure MOHAP telemedicine licenses. Deepen backward integration into clinical-grade meal replacement manufacturing to defend margin position against import-dependent API suppliers facing cold-chain disruption. Channel control through Dubai Healthcare City clinic networks represents the critical defensive lever against emerging telemedicine entrants. For New Entrants and Emerging Players: AI-enabled glucose monitoring integration offers a technology-first wedge into the home-based consumer segment, displacing supplement-only incumbents lacking biometric hardware capabilities. Ras Al Khaimah's emerging hospitality infrastructure presents the most penetrable geography for residential metabolic rehabilitation programs targeting GCC medical tourists. A telemedicine-first go-to-market angle bypasses physical infrastructure requirements while MOHAP's remote prescription framework remains in draft. For Investors and Strategic Acquirers: Valuations sit cheapest among direct-selling networks with established UAE distributor bases but lagging biometric integration capabilities. The five-to-ten-year viability window favors clinical-grade service providers with hospital affiliations over mass-market supplement brands facing labeling compliance cost inflation. The signal to watch is MOHAP's finalization of remote pharmaceutical prescription rules, which would re-rate telemedicine-enabled platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Telemedicine Licensing Acquisition | MOHAP's draft remote prescription framework enables geographic expansion without physical clinic infrastructure. |
| Corporate Wellness Contract Consolidation | Abu Dhabi sovereign wealth-linked entities now tie milestone payments to documented waist circumference reduction. |
| Continuous Glucose Monitoring Integration | Hardware-enabled coaching contracts compress margins for traditional supplement-only providers lacking biometric capabilities. |
| Ras Al Khaimah Facility Development | Lower operational costs and emerging hospitality infrastructure create white space for residential metabolic rehabilitation. |
| Dual Certification Investment | Simultaneous MOHAP food supplement registration and Dubai Health Authority medical device classification accelerates commercialization timelines. |
Research Approach
Multiple input streams — primary interviews with bariatric surgeons, corporate wellness procurement officers, and MOHAP regulatory affairs specialists; secondary validation through Dubai Health Authority filings, MOHAP supplement registration databases, and hospital procurement records — were reconciled through bottom-up and top-down triangulation.
Historical trend analysis was cross-referenced against panel input from metabolic clinic operators and pharmaceutical distribution executives. The forecast framework segments by product type, consumer archetype, distribution channel, and service delivery modality across the analysis window. CAGRs were derived from demand elasticity modeling and institutional procurement pipeline visibility, with specific weighting for medical tourism flows and employer mandate expansion trajectories.
The model holds under stable regulatory enforcement and continued medical tourism access; deviation in MOHAP telemedicine licensing timelines or GCC cross-border patient mobility restrictions would shift trajectory. Forecasts reflect documented assumptions regarding corporate wellness mandate penetration and cold-chain logistics reliability. A model refresh is warranted upon material change in MOHAP's remote prescription framework finalization or national insurance regulator pilot program expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Weight Control Products Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Yoga Market
Health and Wellness
Weight Management Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Sports and Fitness Biohacking Market