
 UK Sports Nutrition Market | 2026-2036
UK Sports Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sports Nutrition Market Outlook
Precision fermentation technology is reconfiguring how alternative proteins achieve amino acid completeness in sports nutrition formulations. Myprotein leverages its Manchester-based manufacturing infrastructure to control supply chain costs across European distribution. Grenade sustains brand momentum through protein bar texture innovation that differentiates from conventional whey-based competitors. Science in Sport anchors its position in elite cycling and triathlon channels where batch-tested certification commands premium placement.
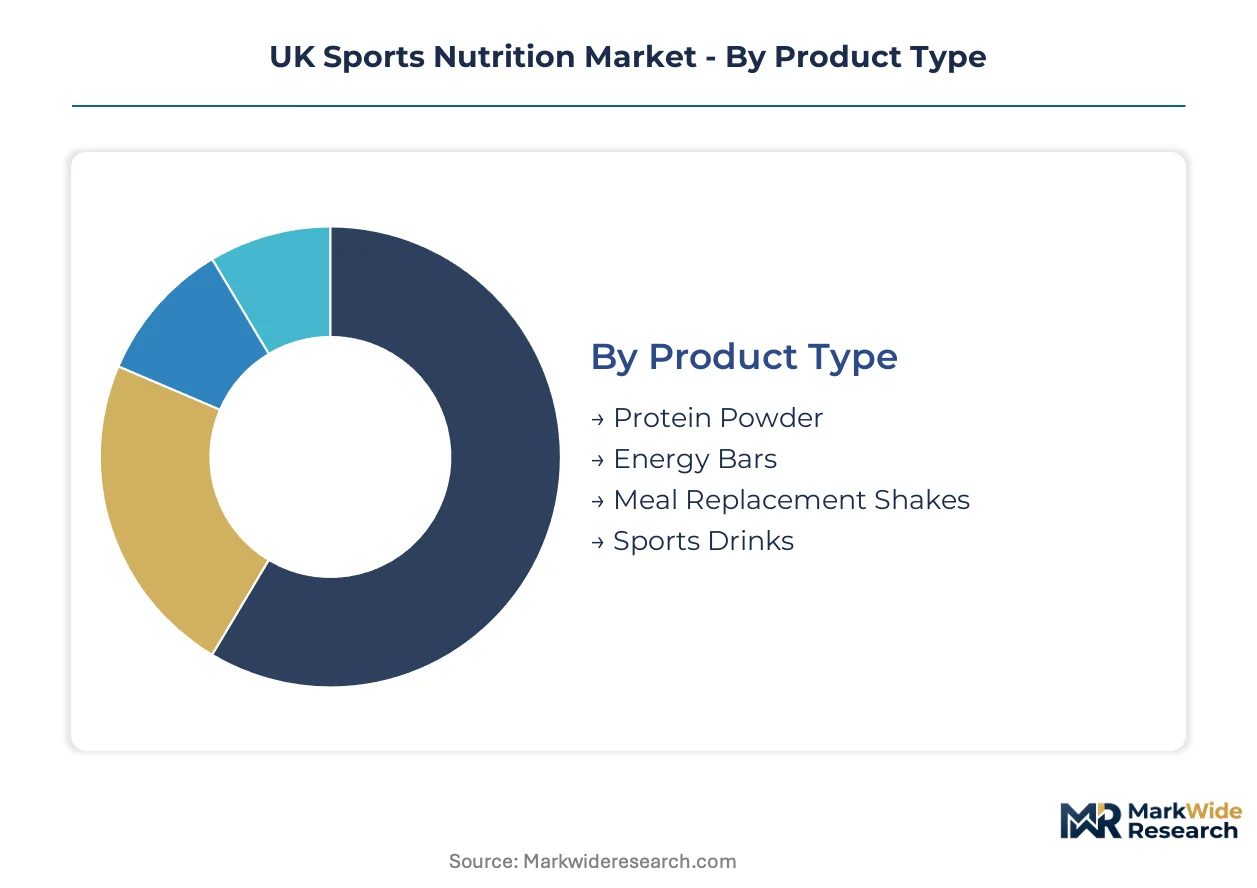
Sports nutrition encompasses formulated consumables engineered to deliver targeted macronutrient ratios, typically featuring protein concentrations between 15 and 30 grams per serving alongside functional additives such as creatine monohydrate, beta-alanine, or caffeine matrices. These products serve to accelerate muscle protein synthesis, replenish glycogen stores, or enhance metabolic efficiency during and after physical exertion. Protein powder occupies the largest revenue pool within product type segmentation, though energy bars demonstrate faster velocity as on-the-go consumption displaces shaker-bottle rituals among time-constrained consumers. The distribution channel structure tilts toward online retail where subscription models capture recurring revenue, while specialty stores retain importance for first-time buyers seeking formulation guidance from trained staff.
The Food Standards Agency governs novel food approvals and health claim substantiation, requiring clinical evidence before brands market performance benefits to UK consumers. BSI standards for contaminant testing and Informed Sport certification programs shape procurement criteria for professional sports organizations and Olympic training facilities. Stakeholders must monitor evolving EFSA-influenced protein health claim frameworks and the Competition and Markets Authority's scrutiny of influencer marketing disclosures in fitness social media channels.
Market Dynamics
Precision fermentation infrastructure is consolidating supply chain control among UK manufacturers while the Food Standards Agency's novel food pathway accelerates regulatory clearance for insect-derived and lab-cultivated protein formats.
Growth Catalysts
- Elite Sports Procurement Mandates:Professional football clubs and rugby academies now require batch-tested certification for all nutritional supplements, creating institutional demand for verified supply chains.
- FSA Novel Food Pathway:The streamlined authorization process reduces time-to-market for fermented protein sources and insect-derived ingredients, compressing innovation cycles for domestic formulators.
- Urban Fitness Clustering:Boutique studio density in Greater London and CrossFit community expansion in Manchester concentrate addressable demand for premium protein formats.
Market Restraints
- Whey Protein Input Volatility:Dairy commodity price swings transmit directly to formulation costs, squeezing margin structures for mid-tier brands dependent on conventional milk-derived isolates.
- Supply Concentration Risk:European contract manufacturing for precision fermentation remains concentrated in Netherlands and Denmark facilities, exposing UK brands to single-source dependencies.
- EFSA Health Claim Friction:Pending European determinations on protein-specific claims create regulatory uncertainty that delays marketing investment and product positioning strategies.
Strategic Opportunities
- Northern England Penetration:Leeds and Liverpool metropolitan areas show underdeveloped specialty retail presence relative to per-capita gym membership density, suggesting whitespace for guided-purchase formats.
- Subscription Model Convergence:Direct-to-consumer recurring revenue platforms paired with app-based coaching integrations are capturing lifetime value from time-constrained professionals.
- Informed Sport Certification Tailwind:Procurement criteria at Olympic training facilities and professional sports organizations now mandate third-party contaminant testing, creating premium tier differentiation.
Industry Challenges
- Formulation Talent Scarcity:Food scientists with dual competency in sports physiology and novel protein processing command premium compensation, constraining R&D expansion for emerging brands.
- Legacy System Integration:Established manufacturers face friction retrofitting precision fermentation capacity into Manchester-based powder production lines originally architected for conventional whey processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sports Nutrition Market |
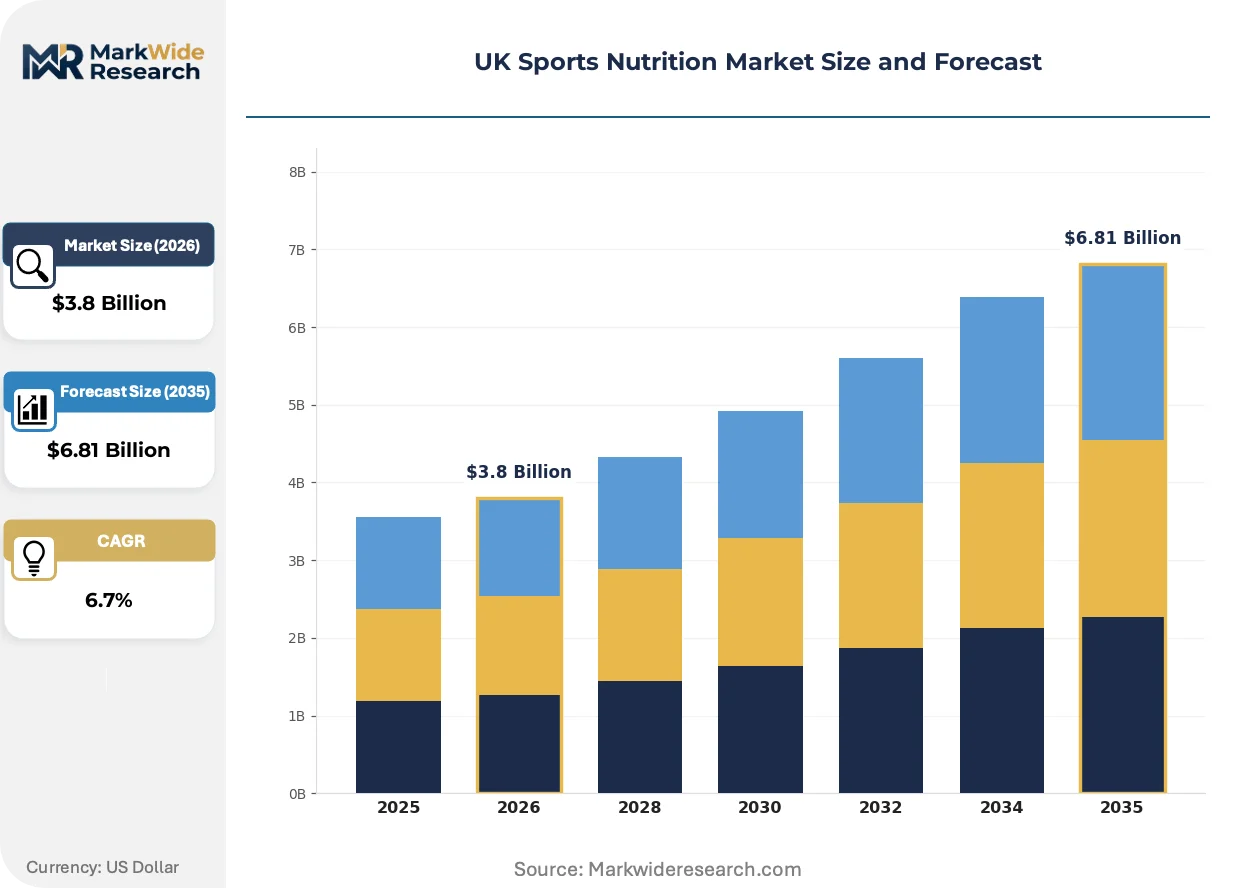
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powder, Energy Bars, Meal Replacement Shakes, Sports Drinks End User: Athletes, Fitness Enthusiasts, Casual Gym-Goers, Health-Conscious Individuals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Convenience Stores Form: Powder, Liquid, Bar, Tablet |
| Companies Covered | Grenade, Myprotein, Science in Sport, Bulk, Optimum Nutrition, Holland & Barrett Retail Limited, Glanbia Performance Nutrition, Reflex Nutrition, PhD Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sports Nutrition Market Strategic Shifts
Protein sourcing technology and distribution architecture are undergoing simultaneous transformation, with fermentation-derived amino acid profiles and direct-to-consumer subscription platforms displacing legacy supply models.
Precision fermentation technology is migrating from niche alternative protein applications into mainstream sports nutrition formulations. Manchester-based manufacturers are adopting bioreactor infrastructure to achieve amino acid completeness without dairy dependency. This migration from conventional whey isolates is compressing cost structures for plant-forward brands while challenging established dairy-centric supply relationships.
BSI contaminant testing standards and Informed Sport certification requirements are tightening procurement criteria across UK professional sports organizations. The Food Standards Agency coordinates with UK Anti-Doping to align batch-testing protocols, forcing reformulation investments from brands serving elite athletic channels. Olympic training facilities now require documentary evidence of third-party verification, shifting competitive advantage toward compliance-invested suppliers.
On-the-go consumption patterns are fragmenting traditional shaker-bottle rituals among time-constrained urban professionals. Energy bars and ready-to-drink formats displace powder-based preparation in Greater London boutique fitness studios, where convenience commands premium pricing. Manchester's expanding CrossFit communities demonstrate similar behavioral rotation, with subscription-box delivery models capturing recurring revenue from athletes prioritizing portability over cost-per-gram optimization.
UK Sports Nutrition Market Segmentation
Sports nutrition purchasing patterns diverge sharply across consumption contexts, with elite athletic procurement demanding batch-tested certification while casual consumers prioritize convenience formats. Understanding these segment boundaries clarifies where formulation investment yields margin expansion versus where cost engineering dominates competitive positioning.
Product Type:
Cycle times vary dramatically: powder formulations turn inventory slowly due to bulk purchasing patterns, while ready-to-drink formats and bar formats rotate faster through convenience-oriented channels.
- Protein Powder:Whey and plant-based isolates delivering 15-30g protein per serving remain the revenue anchor, with Manchester-based manufacturers controlling European supply chain costs. Demand concentrates in Greater London boutique studios where subscription models capture recurring bulk purchases from committed athletes.
- Energy Bars:Texture innovation differentiates competitors as on-the-go consumption displaces shaker-bottle rituals among time-constrained professionals. Manchester's CrossFit communities demonstrate the fastest velocity here, with portability commanding premium pricing over cost-per-gram optimization.
- Meal Replacement Shakes:Complete macronutrient profiles targeting weight management and busy schedules.
- Sports Drinks:Electrolyte and carbohydrate matrices for hydration and glycogen replenishment during exertion.
Protein powder dominates installed base. Energy bars are where expansion concentrates.
End User:
Cost tiers stratify sharply, with elite athletic channels absorbing certification premiums while mass-market segments drive volume through price-competitive formulations.
- Athletes:Professional football clubs and rugby academies mandate Informed Sport batch-tested certification, creating institutional demand for verified supply chains. Olympic training facilities require documentary evidence of third-party verification, shifting competitive advantage toward compliance-invested suppliers.
- Fitness Enthusiasts:Dedicated gym practitioners and boutique studio members purchasing premium formats with functional additives like creatine monohydrate or beta-alanine.
- Casual Gym-Goers:Intermittent exercisers seeking entry-level protein supplementation without specialized performance claims.
- Health-Conscious Individuals:Broader wellness seekers purchasing sports nutrition adjacent to general dietary improvement goals.
Athletes command premium pricing tiers. Fitness enthusiasts are climbing the fastest in absolute numbers.
Distribution Channel:
Volume flows concentrate through digital infrastructure, though physical retail retains critical importance for first-time buyers requiring formulation guidance.
- Online Retail:Direct-to-consumer subscription platforms paired with app-based coaching integrations capture lifetime value from time-constrained professionals. Myprotein leverages Manchester-based manufacturing infrastructure to control supply chain costs across European distribution through this channel.
- Specialty Stores:Trained staff provide guidance for first-time buyers navigating protein type and dosage decisions, with Leeds and Liverpool showing underdeveloped presence relative to gym membership density.
- Supermarkets:Mass-market penetration for established brands with simplified product ranges.
- Convenience Stores:Impulse and emergency replenishment for ready-to-drink and bar formats.
Online retail captures recurring revenue. Specialty stores are where customer acquisition concentrates.
Form:
Supply concentration favors powder production at Manchester-based facilities, while liquid and bar formats depend on contract manufacturing partnerships.
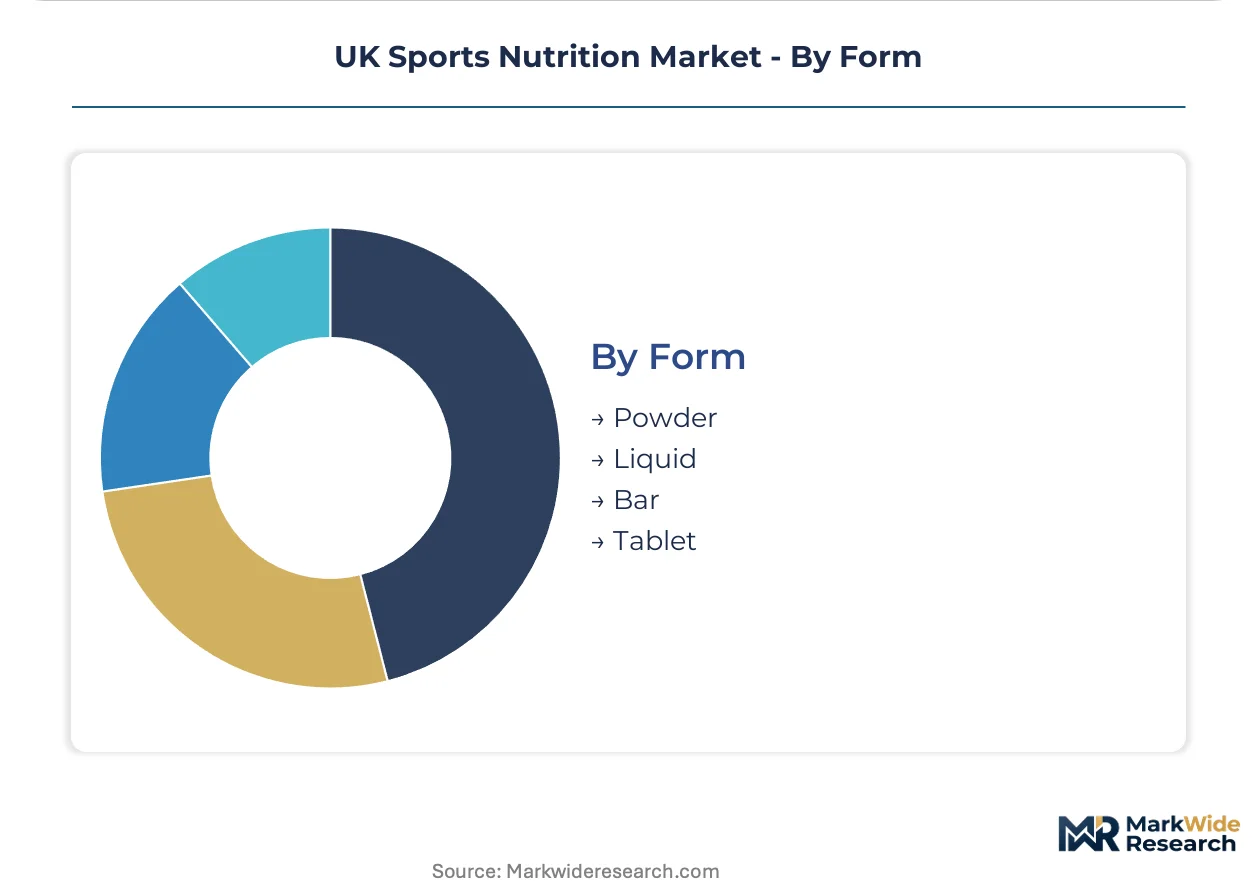
- Powder:The dominant format enabling customizable dosing and cost-efficient protein delivery, produced through legacy infrastructure now facing retrofitting challenges for precision fermentation integration.
- Liquid:Ready-to-drink formats gaining share in Greater London boutique fitness studios where convenience commands premium pricing.
- Bar:Energy and protein bars displacing powder rituals among urban professionals prioritizing portability.
- Tablet:Compressed formats for specific functional additives like creatine or caffeine matrices.
Powder dominates manufacturing capacity. Liquid formats are gaining share fastest in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Elite athletic procurement mandates and boutique fitness clustering concentrate demand in England's metropolitan corridors, while regulatory frameworks from the Food Standards Agency shape formulation standards nationwide.
Greater London
Boutique fitness studio density and time-constrained professional demographics drive premium protein consumption. The Food Standards Agency's novel food authorization pathway accelerates clearance for fermented protein innovations targeting urban consumers. Canary Wharf and Shoreditch clusters demonstrate the fastest adoption of subscription-based direct-to-consumer delivery models.
Manchester
CrossFit community expansion and precision fermentation infrastructure investment anchor northern demand. Manchester-based manufacturers leverage legacy powder production lines while retrofitting bioreactor capacity for alternative protein formats. The city's manufacturing base supplies European distribution through controlled supply chain costs.
Leeds
Underdeveloped specialty retail presence relative to per-capita gym membership density creates whitespace for guided-purchase formats. National Health Service wellness initiatives indirectly stimulate sports nutrition awareness among health-conscious populations. The metropolitan area shows concentrated demand for entry-level protein supplementation without specialized performance claims.
Liverpool
Intermittent exerciser demographics and casual gym-goer segments dominate purchasing patterns. Local procurement from supermarket and convenience channels outpaces online subscription adoption compared to southern counterparts. The city's fitness infrastructure expansion lags protein consumption growth, suggesting channel development opportunities.
Scotland
Rugby academy networks and elite athletic training facilities mandate Informed Sport batch-tested certification for institutional procurement. Scottish Government health improvement programs intersect with sports nutrition retail through pharmacy and wellness store channels. Edinburgh and Glasgow clusters concentrate demand for contaminant-verified formulations serving professional sports organizations.
UK Sports Nutrition Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base fragments between vertically integrated manufacturers with captive production and brands dependent on contract manufacturing partnerships. Three archetypes dominate: certification-invested suppliers serving elite athletic channels, convenience-format innovators capturing urban professional demand, and cost-engineered mass-market operators. Competitive moves concentrate on subscription platform development and precision fermentation capacity acquisition.
Among UK-based operators, Myprotein, Grenade, and Science in Sport exemplify distinct strategic positions within this structure. Myprotein occupies the scale-driven manufacturing tier with Manchester-based infrastructure controlling European distribution economics. Grenade represents the format-innovation archetype, differentiating through texture and portability engineering that commands premium positioning. Science in Sport anchors the compliance-invested supplier category, serving elite cycling and triathlon channels where batch-tested certification creates procurement barriers for competitors.
| Leading Market Players |
|---|
| Grenade |
| Myprotein |
| Science in Sport |
| Bulk |
| Optimum Nutrition |
| Holland & Barrett Retail Limited |
| Glanbia Performance Nutrition |
| Reflex Nutrition |
| PhD Nutrition |
| Others |
Value Chain & Pricing Dynamics
Channel Tunnel freight corridors connecting Manchester manufacturing to continental European distribution determine landed cost differentials that compress margin structures for mid-tier brands while enabling premium positioning for certification-invested suppliers serving elite athletic procurement channels.
Pricing Analysis
Cost-plus contracts indexed to dairy commodity benchmarks govern whey isolate procurement, with pricing stratifying across Informed Sport-certified premium tiers, standard batch-tested formulations, and economy-grade mass-market offerings. Price differentiation hinges on certification grade and volume scale, with Olympic training facilities absorbing certification premiums while casual gym-goers drive volume through price-competitive alternatives. Cost compression in mid-tier whey-based formulations is intensifying because dairy commodity volatility transmits directly to formulation economics. Casual gym-goers exhibit highest price sensitivity; professional sports organizations demonstrate lowest sensitivity due to procurement mandate requirements.
Supply Chain Analysis
Upstream feedstock for precision fermentation draws from Netherlands and Denmark bioreactor facilities, with whey protein concentrates sourcing from domestic dairy processing infrastructure. Key inputs include fermentation-derived amino acid profiles, insect protein meal, and conventional dairy isolates. Single-source vulnerability in European contract manufacturing for precision fermentation exposes UK brands to supply disruption. Distribution runs through direct-to-consumer subscription platforms paired with Manchester-based powder production for European fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in northern England metropolitan corridors where gym membership density outpaces specialty retail presence, with on-the-go consumption patterns creating format-level niches for portability-engineered products.
For Market Incumbents: Insulate certification-invested supply chains through backward integration into Manchester-based precision fermentation capacity, securing batch-tested production autonomy against emerging plant-forward competitors. Deepen channel control in Greater London boutique studio networks before subscription-model convergence commoditizes customer acquisition economics.
For New Entrants and Emerging Players: Build out guided-purchase formats in Leeds and Liverpool where per-capita gym membership density exceeds specialty retail presence, targeting entry-level protein supplementation for intermittent exercisers. Prioritize app-based coaching integration as the go-to-market anchor for recurring revenue capture.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified food conglomerates with underperforming sports nutrition divisions lacking Informed Sport certification infrastructure. Long-term viability favors compliance-invested suppliers with captive Manchester manufacturing and established elite athletic procurement relationships. Monitor EFSA protein health claim determinations as the inflection signal for marketing investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Acquisition | Manchester-based bioreactor infrastructure enables amino acid completeness without dairy dependency. |
| Informed Sport Certification Investment | Batch-tested verification creates procurement barriers at Olympic training facilities and professional clubs. |
| Direct-to-Consumer Subscription Platform | App-based coaching integrations capture lifetime value from time-constrained urban professionals. |
| Texture Innovation for Bar Formats | Portability engineering commands premium pricing over cost-per-gram optimization in CrossFit communities. |
| Northern England Specialty Retail Expansion | Guided-purchase formats address whitespace in Leeds and Liverpool relative to gym membership density. |
Study Parameters
A standing panel of sports nutrition formulators, procurement officers at professional football clubs, specialty retail category managers, and Food Standards Agency regulatory specialists provided ongoing calibration throughout the research process. Primary interview intelligence combined with secondary validation from FSA novel food authorization records, BSI contaminant testing standards documentation, Informed Sport certification databases, and UK Anti-Doping procurement guidelines. Bottom-up segment sizing triangulated against top-down market envelope checks.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation modeling across product type, end user tier, distribution channel, and regional consumption cluster. CAGRs derived from elasticity-adjusted demand curves incorporating gym membership trajectory, boutique studio expansion rates, and protein format substitution patterns. Forecast inputs included precision fermentation capacity buildout timelines and FSA authorization pipeline velocity for novel protein sources.
Stress conditions across dairy commodity volatility bands, EFSA health claim determination delays, and precision fermentation scale-up timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subscription-model adoption curves and elite athletic procurement mandate expansion. Cross-checking against gym membership association data and retail audit velocity metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Germany Sports Nutrition Market
Sports Nutrition
North America Sports Nutrition Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Sports Supplement Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Hydration Supplement Market
Sports Nutrition
Weight Management Products Market
Sports Nutrition
Europe Weight Management Supplement Market