
 Weight Control Products Market | 2026-2036
Weight Control Products Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Control Products Market Intelligence
The NSF Certified for Sport standard, which verifies products are free from banned substances, is redrawing the competitive landscape for supplements targeting athletes. Shaklee leverages its long-standing brand reputation and multi-level marketing channels to reach a broad consumer base. Purium differentiates through its focus on organic and non-GMO certified products, appealing to specific health-conscious buyers. It Works! Global competes by bundling its products into targeted weight management programs.
Weight control products encompass a range of specially formulated foods, beverages, and dietary supplements designed to assist in weight loss or maintenance. These items often feature controlled calorie counts and specific macronutrient ratios like high protein or low carbohydrate content. Meal replacements and dietary supplements represent the largest product categories, driven by convenience and perceived efficacy. Within distribution channels, online retail is expanding rapidly, challenging the traditional dominance of health stores and pharmacies.
The regulatory environment is defined by bodies like the US Food and Drug Administration (FDA), the European Medicines Agency (EMA), and China's NMPA, which govern health claims and ingredient safety. These regulations dictate labeling requirements and market access, directly impacting product formulation and marketing strategies. Navigating the patchwork of international food safety and advertising standards remains a critical challenge for companies seeking to expand their geographic footprint.
Market Dynamics
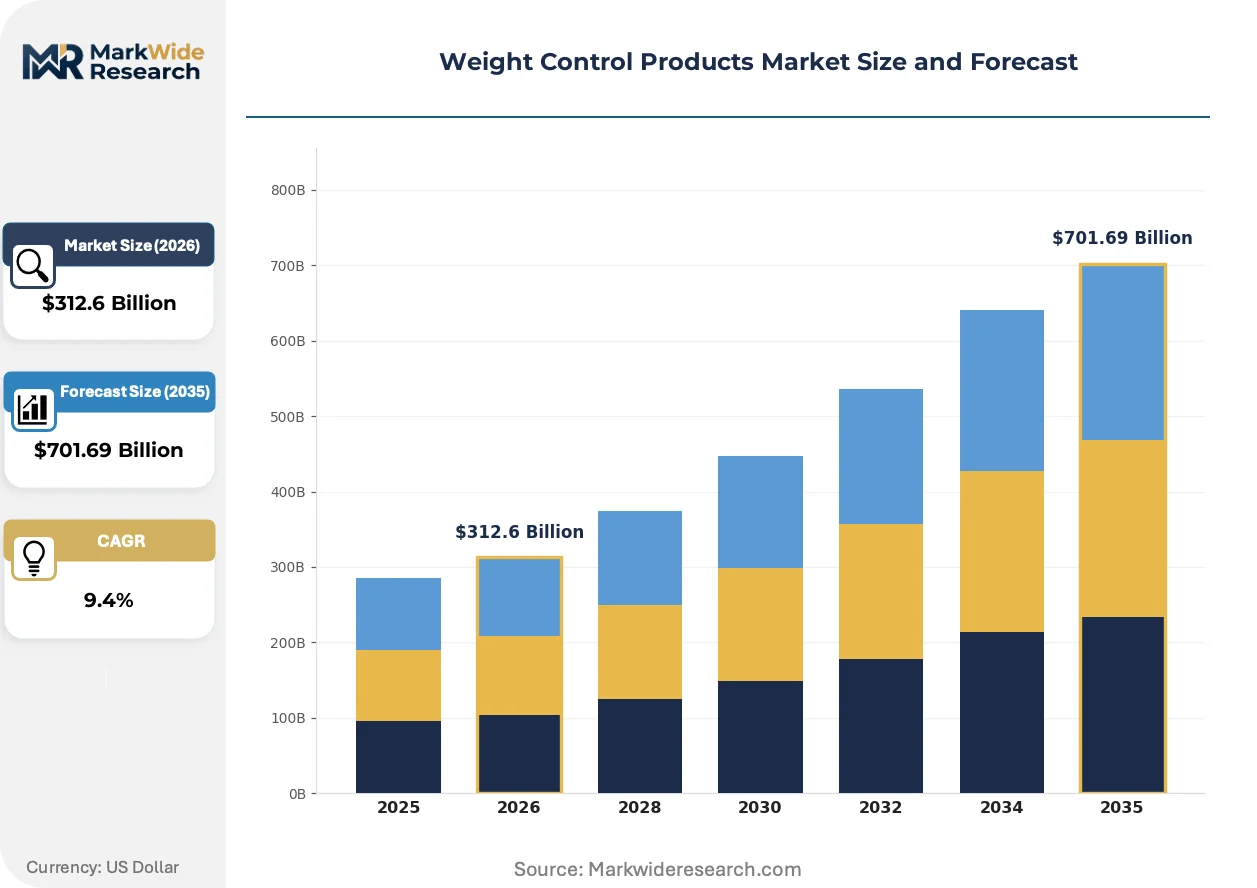
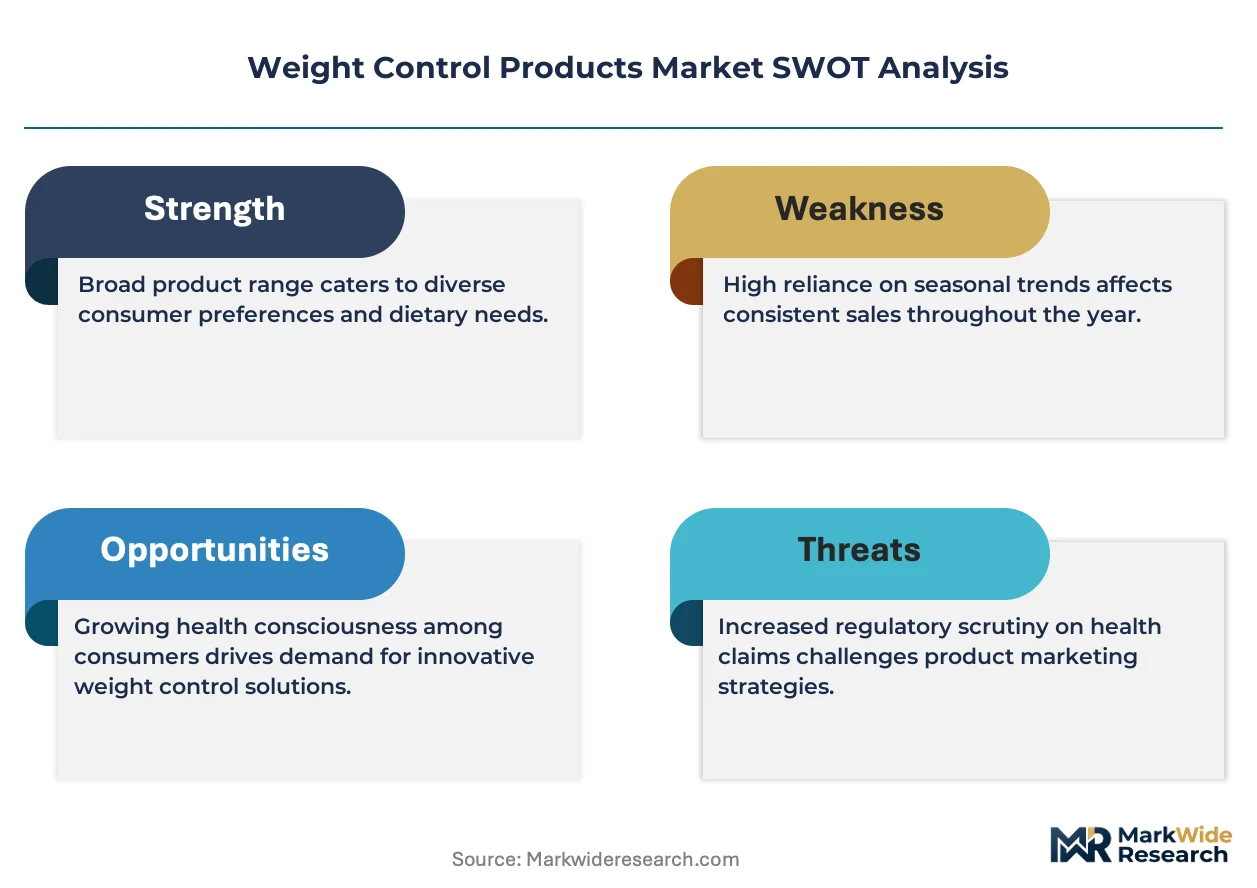
The central dynamic shaping the weight control products market is the collision between escalating consumer demand for personalized, effective solutions and tightening global regulatory frameworks governing health claims. This tension is forcing a pivot from broad marketing to evidence-backed product formulation, particularly as bodies like the FDA and EMA increase scrutiny.
Growth Catalysts
- Preventative Health Initiatives:Government-led public health campaigns in countries like the United States and the UK that promote healthy weight and lifestyle choices are expanding the addressable consumer base for weight management products.
- Demand for Functional Foods:Growing interest among fitness enthusiasts and athletes for meal replacements and supplements with specific macronutrient profiles, such as high-protein or low-carbohydrate, fuels product innovation and category growth.
- E-commerce Channel Expansion:The proliferation of online retail and direct-to-consumer websites provides brands with broader market access, bypassing the limitations of traditional brick-and-mortar pharmacies and health stores.
Market Restraints
- Stringent Health Claim Regulations:Regulatory bodies, including the US FDA and Europe's EFSA, impose strict rules on marketing claims, requiring extensive scientific substantiation which increases compliance costs and limits advertising freedom.
- Ingredient Price Volatility:The market is susceptible to price fluctuations for key inputs like whey protein, pea protein, and specialized botanical extracts, which can compress manufacturer profit margins.
- Consumer Skepticism and Brand Trust:A history of products with exaggerated or false claims has created a high degree of consumer skepticism, posing a significant barrier for new entrants needing to establish credibility.
Strategic Opportunities
- Personalized Nutrition Services:Integrating DNA analysis or biomarker tracking with customized meal plans and supplement regimens offers a significant opportunity to provide highly differentiated, premium-priced solutions.
- Plant-Based Formulations:There is a substantial opportunity in developing and marketing vegan and plant-based weight control products to cater to the underserved but growing consumer segment avoiding animal-derived ingredients.
- Athlete-Focused Certifications:Pursuing third-party verifications like NSF Certified for Sport allows brands to target elite athletes and discerning consumers, creating a defensible niche in the premium supplement segment.
Industry Challenges
- Navigating Global Regulatory Patchwork:Companies face significant operational complexity in formulating products that simultaneously comply with the disparate ingredient and labeling standards of the FDA, EMA, and China's NMPA.
- Ensuring Supply Chain Integrity:Maintaining and documenting a fully transparent supply chain to support organic or non-GMO claims is a major logistical and financial challenge for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Control Products Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $701.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meal Replacements, Dietary Supplements, Snacks, Beverages Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Customer Type: Fitness Enthusiasts, Diabetics, Weight Watchers, General Consumers Formulation: Organic, Non-GMO, Gluten-Free, Low-Carb |
| Companies Covered | Cambridge Diet, Purium, Vida Divina, CTFO, Visi, Shaklee, Truvy, Saba, It Works! Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Control Products Market Strategic Shifts & Innovations
Product development is pivoting toward scientifically validated ingredients and personalized solutions. The integration of digital health tools with nutritional products is creating a new paradigm where consumer data directly informs formulation, moving the industry beyond one-size-fits-all approaches toward targeted, outcome-based programs.
Microbiome-centric formulations that incorporate prebiotics and probiotics represent a significant product evolution. Health-conscious consumers are increasingly adopting these products based on research linking gut health to metabolism and weight management. This focus on the gut-brain axis is fragmenting the market away from simple meal replacements toward specialized nutritional therapies designed for metabolic health.
The US FDA's more stringent enforcement of dietary supplement labeling, mirrored by similar actions from the European Food Safety Authority, is a defining regulatory shift. This pressure compels manufacturers to invest in clinical validation for health claims, elevating the cost and complexity of product development. The dietary supplement category is most affected, pushing brands to prioritize transparency and third-party certifications to secure consumer confidence.
A notable behavioral shift is the move from transactional product purchases to subscription-based wellness programs. Consumers are opting for comprehensive packages that bundle supplements or meal replacements with digital coaching and community support. This model is disrupting sales through traditional retail channels like pharmacies, favoring direct-to-consumer brands that foster long-term customer engagement, a pattern especially visible in the United States.
Weight Control Products Market Segmentation
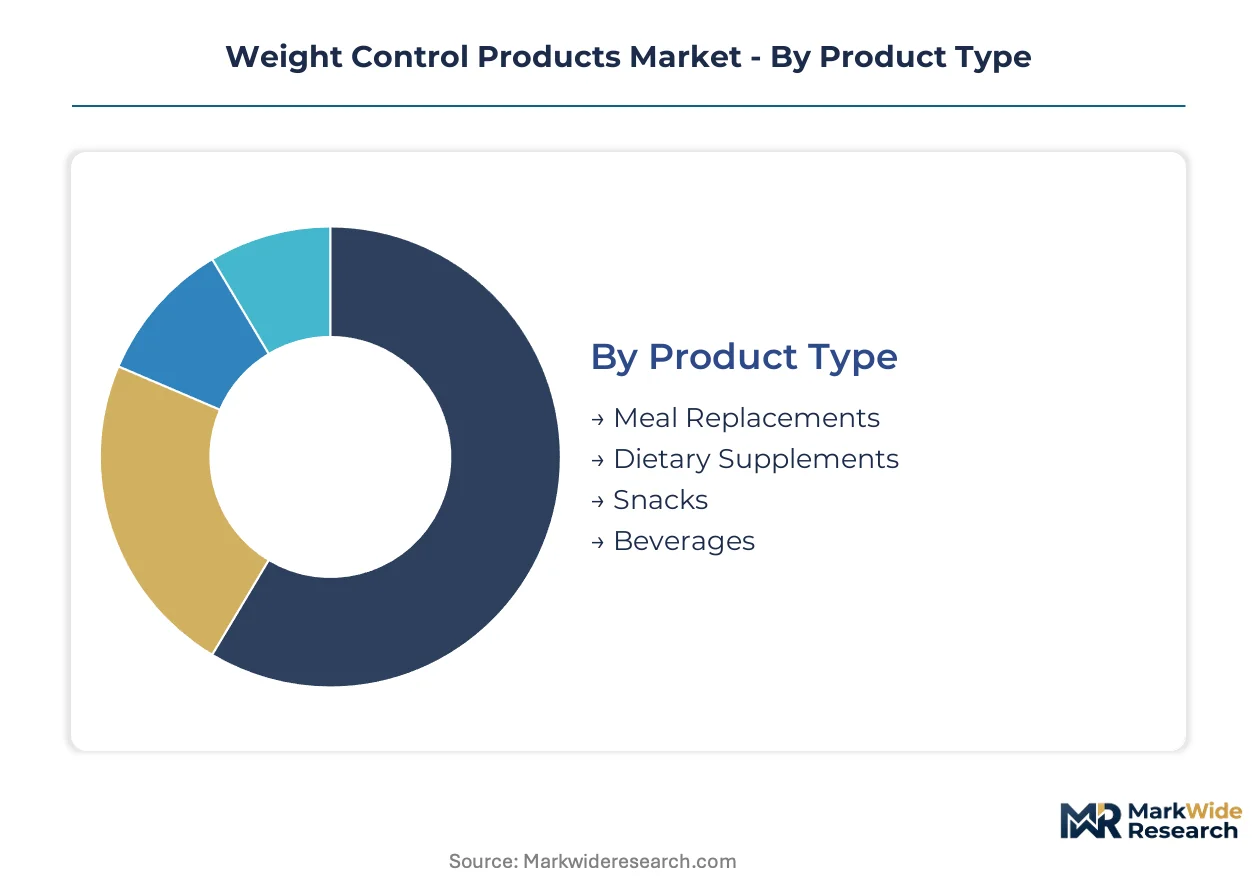
Segmentation analysis reveals the diverse needs driving the weight control products market, allowing companies to tailor offerings for specific consumer groups. Understanding these distinct segments helps manufacturers optimize product development and distribution strategies. This detailed breakdown highlights areas of concentrated demand and emerging opportunities.
Product Type:
The Product Type category faces significant substitution pressure, particularly from conventional foods for snacks and beverages, requiring specialized formulations to justify premium pricing.
- Meal Replacements:These products offer a nutritionally complete substitute for a traditional meal, typically provided as shakes, bars, or powdered mixes. Demand concentrates among individuals seeking structured weight loss programs in the United States, driven by their convenience and controlled calorie content.
- Dietary Supplements:These include vitamins, minerals, herbs, and other ingredients designed to supplement the diet, often targeting specific metabolic functions. The global demand for these is high in Europe, where consumers seek targeted solutions for energy and fat metabolism.
- Snacks:Specially formulated snacks with controlled calories or macronutrients cater to consumers seeking healthier alternatives between meals.
- Beverages:Weight control beverages include protein drinks, low-calorie shakes, and functional teas, appealing to consumers prioritizing hydration and specific nutrient intake.
Meal Replacements retain significant volume leadership; Dietary Supplements hold the steepest expansion curve.
Distribution Channel:
The Distribution Channel category reflects how product accessibility influences purchasing volume, with certain channels capturing larger consumer bases due to convenience and reach.
- Online Retail:This channel encompasses e-commerce platforms and direct-to-consumer websites, providing broad market access and often competitive pricing. Demand is accelerating in Germany, where digital platforms offer extensive product variety and discreet purchasing options.
- Supermarkets:Large grocery stores offer a wide array of weight control products alongside conventional groceries, benefiting from high foot traffic and routine shopping behaviors. Volume concentration occurs in Canada, where consumers integrate these purchases into weekly food shopping.
- Health Stores:Specialized health stores cater to consumers seeking expert advice and niche, premium weight control products, often emphasizing organic or natural formulations.
- Pharmacies:Pharmacies distribute weight control products, often alongside medical advice, appealing to consumers seeking trusted, regulated options for health management.
Online Retail is gaining share fastest, while Supermarkets maintain broad consumer reach.
Customer Type:
The Customer Type category highlights distinct application needs, with each segment requiring tailored product features and marketing approaches to address specific health objectives.
- Fitness Enthusiasts:This segment comprises individuals focused on athletic performance, muscle building, and body composition, often seeking high-protein meal replacements and performance-enhancing supplements. Demand is strong in Australia, driven by a pervasive sports culture and active lifestyles.
- Diabetics:This group requires products with controlled sugar content and specific macronutrient profiles to manage blood glucose levels and weight. The market for these products is expanding in India, as dietary interventions become critical for diabetes management.
- Weight Watchers:Individuals actively engaged in structured weight loss programs seek calorie-controlled and portion-specific products to support their dietary goals.
- General Consumers:This broad segment includes individuals seeking healthier lifestyle choices, often opting for low-calorie or functional food options for overall wellness.
Fitness Enthusiasts drive innovation, and Diabetics represent a critical medical nutrition segment.
Formulation:
The Formulation category influences product margin significantly, as specialized ingredients and certifications often command premium pricing and appeal to discerning consumers.
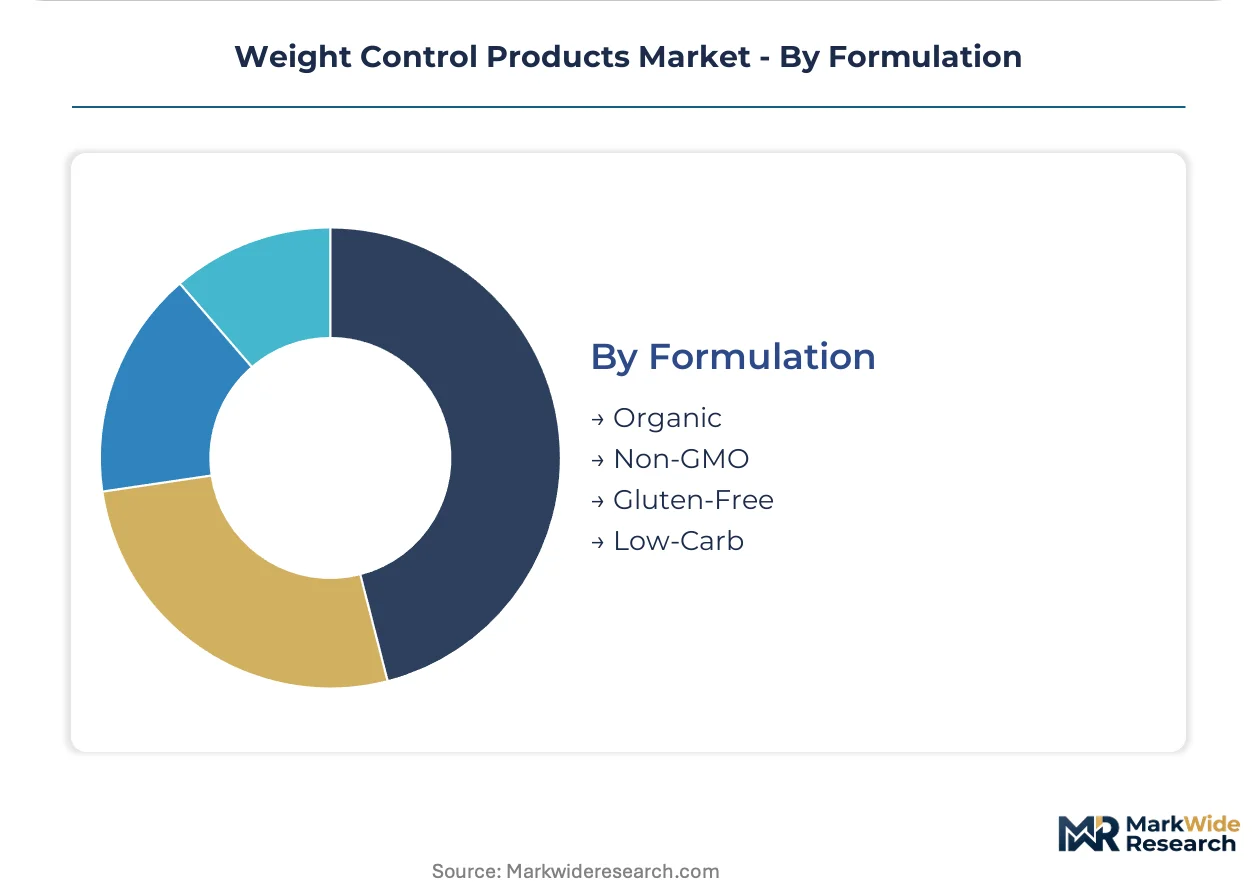
- Organic:These products are made from ingredients cultivated without synthetic pesticides, fertilizers, or genetically modified organisms, appealing to health-conscious consumers. Demand for organic formulations is high in France, reflecting strong consumer preference for natural and clean label products.
- Non-GMO:Products free from genetically modified organisms appeal to consumers concerned about food safety and natural ingredient sourcing. This formulation gains traction in Japan, where consumers prioritize transparency in food production and ingredient origin.
- Gluten-Free:Formulations free from gluten cater to individuals with celiac disease or gluten sensitivity, providing safe dietary options for weight management.
- Low-Carb:Products designed with reduced carbohydrate content support ketogenic or low-carb diets, popular among consumers aiming for weight loss and metabolic control.
Organic formulations command higher price points, while Low-Carb options address a specific dietary trend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-led public health campaigns promoting healthy weight and lifestyle choices significantly influence the weight control products market. Preventative health initiatives in countries like the United States expand the addressable consumer base. Tightening regulatory frameworks from bodies such as the US FDA also shape product development and market access.
United States
Demand for structured weight loss programs and convenience drives the market in the United States. The US FDA's stricter dietary supplement labeling requirements influence product formulation and marketing claims. Major metropolitan areas like New York and Los Angeles see high demand for personalized nutrition services and subscription-based wellness programs.
Germany
Online retail expansion accelerates demand for weight control products across Germany. The European Medicines Agency (EMA) and EFSA regulations govern health claims, requiring scientific substantiation for products sold. Digital platforms in cities such as Berlin and Hamburg offer extensive product variety and discreet purchasing options for consumers.
Australia
Fitness enthusiasts and a pervasive sports culture fuel strong demand for high-protein meal replacements in Australia. The Therapeutic Goods Administration (TGA) regulates dietary supplements, ensuring product safety and efficacy. Active lifestyles in urban centers like Sydney and Melbourne contribute to the uptake of performance-enhancing supplements.
India
Diabetics represent a critical medical nutrition segment in India, driving demand for specialized weight control products. The Food Safety and Standards Authority of India (FSSAI) oversees food safety and labeling standards for dietary interventions. Dietary interventions in Mumbai and Delhi become crucial for diabetes management, fueling product expansion.
Japan
Consumers prioritizing transparency and natural ingredient sourcing drive demand for non-GMO certified formulations in Japan. The Ministry of Health, Labour and Welfare (MHLW) regulates health foods and functional foods, impacting product development. Urban consumers in Tokyo and Osaka seek clean label weight control options, valuing ingredient origin.
Weight Control Products Market Key Industry Players
Player mix skews toward established brands leveraging reputation alongside specialized entrants targeting niche segments. The market exhibits a tiered structure, from broad-appeal convenience products to premium, certified formulations. Strategic archetypes include multi-level marketing organizations, organic-focused brands, and those bundling products into comprehensive programs. Companies are engaging in portfolio diversification to meet varied consumer needs and pursuing strategic partnerships to expand distribution.
Within the organic-focused archetype, Purium exemplifies a strategy centered on non-GMO certified products, appealing to specific health-conscious buyers seeking transparency. Shaklee, leveraging its long-standing brand reputation, occupies a position anchored by extensive multi-level marketing channels, effectively reaching a broad consumer base across diverse demographics. It Works! Global sits within the program-centric segment, offering bundled product solutions for targeted weight management programs, fostering long-term customer engagement through comprehensive packages. These players represent distinct approaches to market penetration and consumer engagement, from clean-label specialization to broad-reach distribution and integrated wellness solutions.
| Leading Market Players |
|---|
| Cambridge Diet |
| Purium |
| Vida Divina |
| CTFO |
| Visi |
| Shaklee |
| Truvy |
| Saba |
| It Works! Global |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for key protein isolates and botanical extracts lock in both ingredient access and provide price visibility for weight control product manufacturers. This market faces significant pricing pressure from commodity input volatility, directly impacting product margins across various categories.
Pricing Analysis
Certification level (NSF Certified for Sport, Organic, Non-GMO) creates the primary spread in weight control product pricing, differentiating premium offerings. The dominant pricing model is transactional, with a growing shift towards subscription-based wellness programs for long-term engagement. Price differentiation also stems from brand premium and specialized formulation claims, such as microbiome-centric ingredients. Pricing softness is evident in the general consumer segment due to intense competition and consumer skepticism, while fitness enthusiasts demonstrate lower price sensitivity for performance-oriented products.
Supply Chain Analysis
The need for consistent inventory levels for high-demand protein powders and meal replacements influences supply chain design. Geographic supply concentration for key ingredients includes whey protein from the United States and Europe, and specialized botanicals from India and China. The supply chain relies heavily on raw materials like pea protein, whey protein, and various vitamin premixes. Ingredient price volatility for these core inputs presents a significant structural risk. Distribution runs through a hybrid model, combining direct-to-consumer online channels with traditional retail and pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the convergence of personalized nutrition technologies and increasing regulatory scrutiny from bodies like the US FDA.
For Market Incumbents: Consolidate market share through strategic acquisitions of specialized ingredient suppliers or digital health platforms. Invest in clinical validation for existing product lines to counter consumer skepticism and comply with stricter health claim regulations. Defend against emerging niche entrants by expanding portfolio diversification into plant-based and microbiome-centric formulations. Leverage established distribution networks to maintain broad consumer reach against online challengers.
For New Entrants and Emerging Players: Pursuing NSF Certified for Sport fast-track certification offers a critical entry point into the premium athlete segment. Target underserved niches like highly personalized dietary solutions integrating biomarker data or specialized medical nutrition for specific health conditions. The most penetrable segment is health-conscious consumers seeking transparent, clean-label plant-based options. A strong go-to-market angle involves subscription models bundled with digital coaching and community support.
For Investors and Strategic Acquirers: Mid-cap companies specializing in scientifically validated ingredients or proprietary digital health platforms represent attractive acquisition targets. The long-term viability of this market over a 5-10 year window is robust, fueled by preventative health trends and an aging population. A critical signal to watch is the adoption rate of personalized nutrition services, indicating a shift towards outcome-based solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Clinical Validation | Enhances product credibility and secures regulatory compliance for health claims. |
| Expand Plant-Based Offerings | Captures the growing vegan and flexitarian consumer segments for weight management. |
| Integrate Digital Health Tools | Provides personalized solutions and fosters long-term customer engagement through data. |
| Secure Third-Party Certifications | Builds consumer trust and opens access to premium, athlete-focused market segments. |
| Develop Subscription Wellness Programs | Disrupts traditional retail by offering comprehensive packages and recurring revenue. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and secondary market reports anchors the qualitative findings. Primary research involved in-depth discussions with product development executives, regulatory affairs leads, e-commerce platform managers, and nutritionists. Secondary data sources included US FDA filings, European Food Safety Authority publications, academic journals, and consumer health databases, supporting bottom-up and top-down triangulation.
Sensitivity analysis across the modeling period informed the forecast framework, accounting for various market conditions. Segmentation dimensions modeled included product type, distribution channel, customer type, formulation, and regional regulatory cluster. Compound annual growth rates were derived from historical data analysis and projected market dynamics. Key forecast inputs included consumer health spending patterns and regulatory compliance costs for dietary supplements.
Decision-makers should treat outputs as directional under current regulatory frameworks and consumer behavior; material deviation would warrant model refresh. Forecasts reflect assumptions regarding sustained preventative health initiatives and stable raw material supply. Sudden shifts in regulatory enforcement or significant disruptions to global supply chains could alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Health and Wellness Products Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Yoga Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Weight Management Market
Health and Wellness
Brain Fitness Market