
 Global Body Fat Reduction Market | 2026-2036
Global Body Fat Reduction Market Size, Share, and Industry Trends Forecast 2026-2036
Global Body Fat Reduction Market Foresight
The capital-intensity divergence between integrated device manufacturers and standalone technology licensors is unwinding competitive stability in body fat reduction. AbbVie leverages its pharmaceutical infrastructure to anchor clinical credibility across physician-administered segments. Cynosure competes through laser and radiofrequency platforms that dominate dermatology center procurement. Alma Lasers extends its position via multi-modality portfolios spanning cryolipolysis through EMS-based toning systems.
Body fat reduction encompasses non-invasive and minimally invasive technologies that disrupt adipocyte structure through thermal, cryogenic, acoustic, or electromagnetic energy delivery, typically operating at temperatures between minus eleven degrees Celsius and forty-three degrees Celsius or frequencies from one megahertz to forty megahertz depending on modality. The primary commercial purpose centers on circumference reduction and body contouring without surgical intervention, serving patients seeking alternatives to liposuction. Cryolipolysis devices command premium placement in medical spas due to established efficacy protocols and longer treatment intervals that optimize capital utilization. Radiofrequency equipment penetrates wellness centers through lower per-session costs and combined skin tightening applications. Portable devices represent the fastest-expanding deployment category as fitness studios integrate adjunct body sculpting into membership offerings.
FDA clearance requirements for class II medical devices govern commercialization pathways in the United States, while EMA medical device regulation and CE marking obligations structure European market access for energy-based fat reduction platforms. ISO thirteen four eighty-five quality management standards and IEC six zero six zero one safety specifications further constrain manufacturing and distribution capabilities across jurisdictions. Stakeholders must monitor evolving reimbursement classifications for non-invasive body contouring as private insurers and national health systems reassess coverage policies for aesthetic versus functional indications.
Market Dynamics
The body fat reduction market is restructuring around modality convergence, where single-platform devices combining cryolipolysis with radiofrequency or electromagnetic muscle stimulation are displacing standalone systems and compressing capital deployment cycles for clinic operators.
Growth Catalysts
- FDA 510(k) clearance pathway acceleration:Streamlined premarket notification for cryolipolysis and radiofrequency devices compresses commercialization timelines, enabling faster platform launches by device manufacturers.
- Medical spa channel expansion:Aesthetic clinic networks in Brazil, South Korea, and the United States are standardizing non-invasive body contouring as core service offerings, driving recurring capital expenditure on multi-modality systems.
- Electromagnetic muscle stimulation integration:EMS-based toning modules are attaching to fat reduction platforms, creating bundled service protocols that extend patient visit frequency and device utilization rates.
Market Restraints
- High capital intensity for cryolipolysis hardware:Precision cooling systems and vacuum-applicator arrays require substantial upfront investment, limiting procurement to well-capitalized clinic chains and hospital outpatient departments.
- Supply concentration in laser diode manufacturing:German and Japanese component suppliers control critical semiconductor sources for radiofrequency and laser platforms, exposing device assemblers to input bottlenecks and extended lead times.
- Efficacy variability across adipose tissue densities:Cryolipolysis demonstrates reduced circumference reduction in fibrous adipose compartments, constraining addressable patient populations and requiring pre-treatment screening protocols.
Strategic Opportunities
- Portable device penetration into fitness studios:Lower-power radiofrequency and ultrasound cavitation systems are entering gym membership bundles as adjunct body sculpting services, opening volume channels outside traditional medical aesthetics.
- EMA Medical Device Regulation harmonization:Unified CE marking pathways across EU member states reduce regulatory fragmentation, enabling centralized manufacturing and distribution scale for European market entry.
- Combination therapy protocol development:Sequential cryolipolysis and radiofrequency treatment regimens are demonstrating enhanced skin tightening outcomes, creating premium service tiers and extended patient retention models.
Industry Challenges
- Technician certification and training standardization:Operator skill variation across energy-based modalities affects treatment consistency and adverse event rates, requiring structured competency frameworks and ongoing education investments.
- Reimbursement classification ambiguity:Private insurers and national health systems maintain inconsistent coverage determinations for aesthetic versus functional body contouring indications, complicating patient financing and clinic revenue predictability.
- IP licensing complexity in multi-modality platforms:Patent thickets spanning thermal, cryogenic, and electromagnetic technologies create royalty stacking and freedom-to-operate risks for integrated device development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Body Fat Reduction Market |
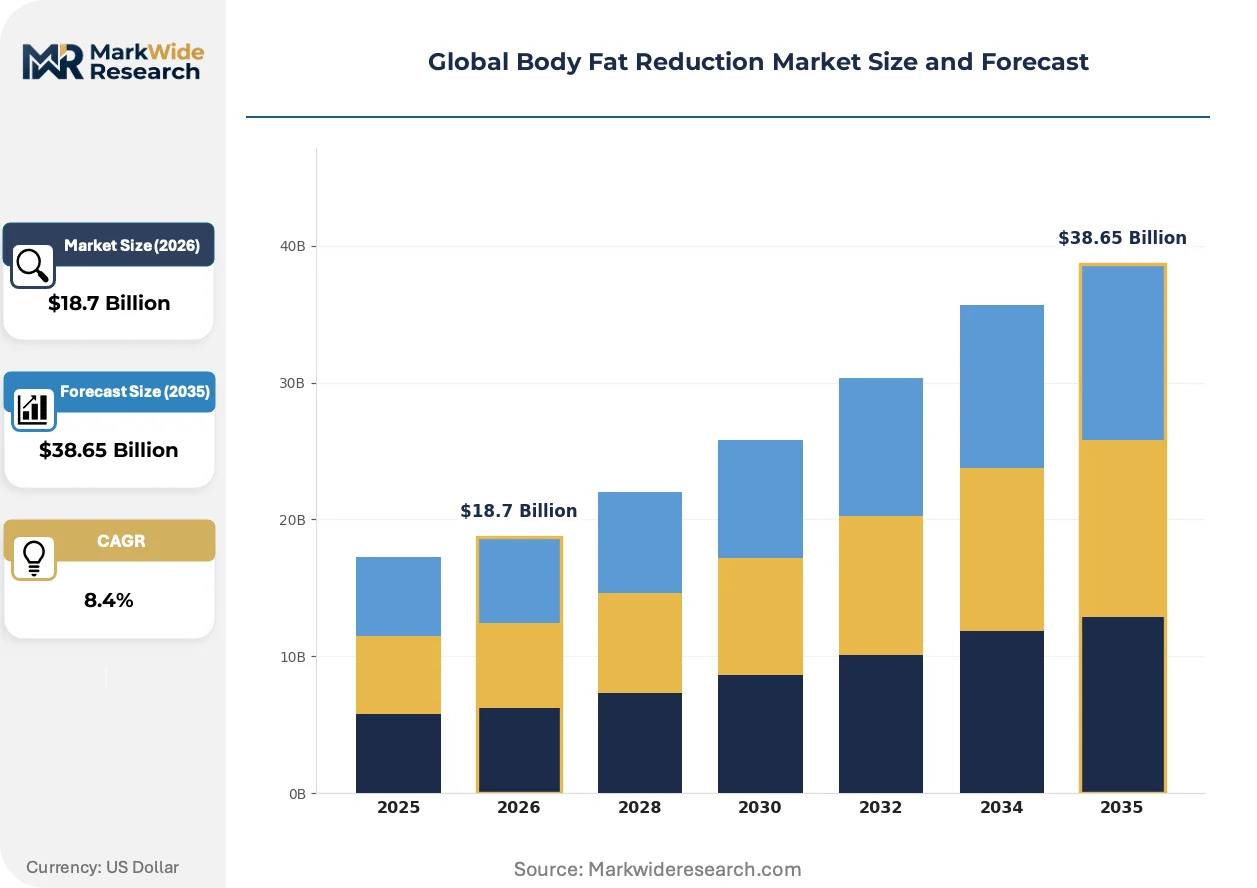
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryolipolysis Devices, Radiofrequency Equipment, Ultrasound Cavitation, Laser Therapy Machines, EMS Devices, Others Application: Weight Management, Postpartum Recovery, Muscle Toning, Skin Tightening, Cellulite Reduction End User: Medical Spas, Cosmetic Clinics, Dermatology Centers, Wellness Centers, Fitness Studios Deployment Type: Standalone Units, Integrated Systems, Portable Devices, Clinic-Based Systems |
| Companies Covered | AbbVie, Cynosure, Cutera, BTL Aesthetics, Candela, Alma Lasers, Lumenis, Venus Concept, InMode, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Body Fat Reduction Market Shifts & Advancements
Device architecture is fragmenting into divergent performance tiers, with premium medical-grade platforms separating from consumer-accessible portable systems and creating distinct competitive arenas with incompatible technical specifications and service models.
Radiofrequency adipose tissue heating is bifurcating the market into high-frequency systems operating at forty megahertz for deep dermal penetration versus lower-frequency alternatives targeting superficial fat layers. Dermatology centers in Germany and Japan are adopting the high-frequency variants for combined skin tightening applications, while wellness studios in the United States favor lower-cost, lower-frequency equipment. This technical divergence is bifurcating procurement patterns and compressing mid-range product viability.
EMA Medical Device Regulation and FDA 510(k) pathway harmonization efforts are converging clinical evidence requirements for energy-based fat reduction platforms, forcing manufacturers to design unified trial protocols that satisfy both jurisdictions simultaneously. Device sponsors must now structure pivotal studies with endpoints acceptable to both regulators, extending premarket development timelines but reducing redundant regulatory expenditure. European notified bodies and US FDA reviewers are coordinating predicate device identification, accelerating clearance for incremental platform improvements.
Clinic procurement is consolidating around leasing and subscription models rather than capital purchase, with aesthetic device financiers in South Korea and Brazil structuring per-treatment revenue-sharing arrangements that align equipment vendors with clinic utilization rates. This financing pivot is displacing traditional outright sale relationships and forcing manufacturers to develop recurring revenue service capabilities. Medical spa chains in São Paulo and Seoul are driving this transition, demanding outcome-linked payment structures that transfer utilization risk to equipment suppliers.
Global Body Fat Reduction Market Segmentation
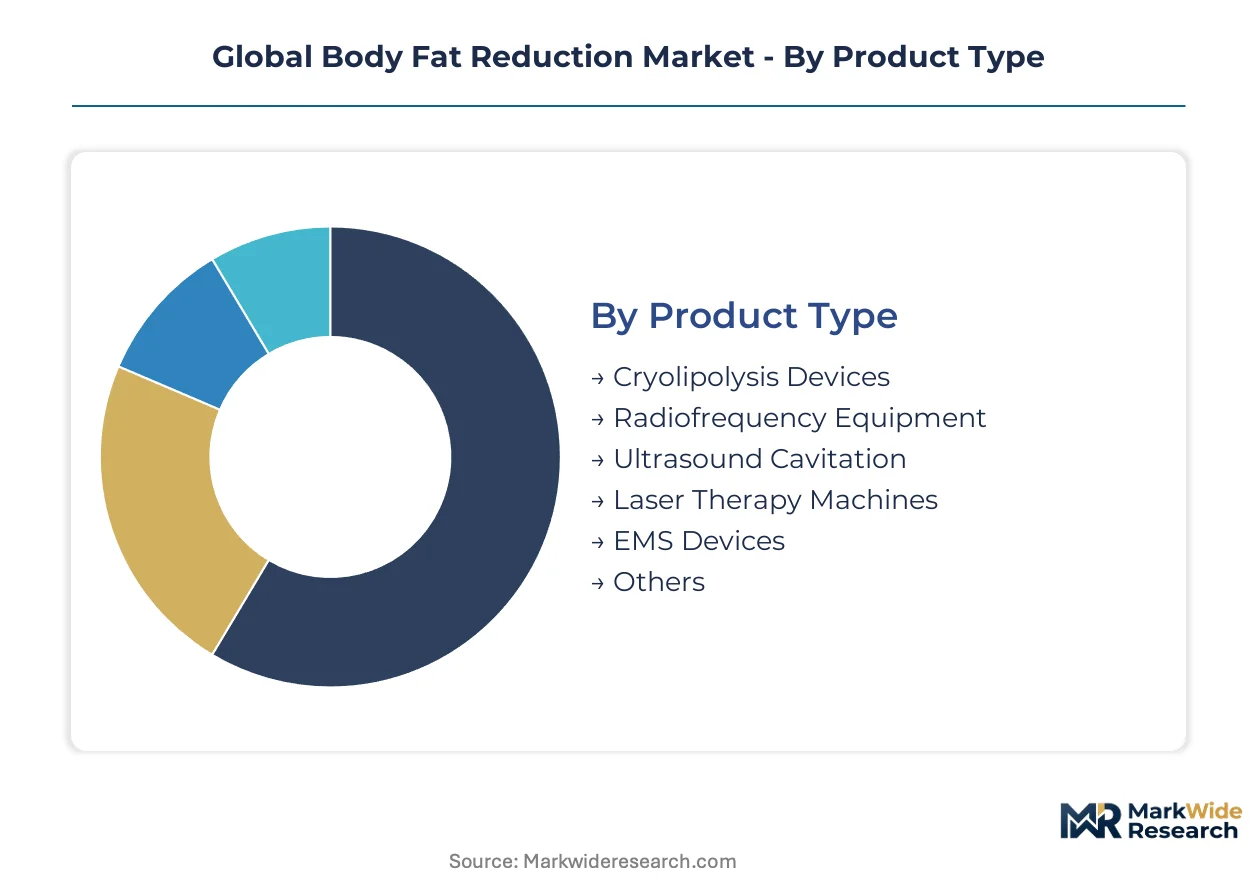
Segmentation in body fat reduction reveals divergent capital deployment patterns across channels. Medical spas and cosmetic clinics prioritize different modality combinations based on patient throughput economics and service bundling strategies.
Product Type:
Cryolipolysis and radiofrequency equipment flow through medical spa networks, while ultrasound cavitation and portable EMS devices penetrate fitness studio channels.
- Cryolipolysis Devices:Precision cooling systems operating at minus eleven degrees Celsius employ vacuum-applicator arrays to induce adipocyte apoptosis through controlled thermal injury. Demand concentrates in Brazil's aesthetic medicine corridor, where São Paulo clinic chains deploy multi-applicator configurations to maximize hourly patient throughput.
- Radiofrequency Equipment:These platforms deliver thermal energy at frequencies up to forty megahertz to disrupt adipose structure while stimulating collagen remodeling. Dermatology centers in Germany favor high-frequency variants for combined skin tightening, compressing procurement timelines for integrated platforms.
- Ultrasound Cavitation:Acoustic energy devices operating at one to three megahertz create cavitation bubbles to lyse fat cells without thermal damage.
- Laser Therapy Machines:Diode and Nd:YAG laser platforms target superficial adipose layers through photothermal mechanisms.
- EMS Devices:Electromagnetic muscle stimulation systems induce supramaximal contractions for adjunctive toning applications.
- Others:Emerging modalities including injectable adipolytics and microwave-based platforms occupy niche commercial positions.
Cryolipolysis devices dominate installed base in premium medical aesthetics. EMS devices and portable radiofrequency units represent where expansion concentrates fastest.
Application:
Weight management protocols command the highest per-patient revenue, while muscle toning applications show steepest volume growth in fitness-integrated channels.
- Weight Management:Circumference reduction protocols targeting abdominal and flank adiposity generate recurring treatment cycles with established efficacy endpoints. Medical spas in South Korea structure membership packages around sequential cryolipolysis sessions, locking in twelve-month patient retention.
- Postpartum Recovery:Diastasis recti and localized fat deposits following pregnancy drive demand for combined radiofrequency and EMS protocols. Cosmetic clinics in Brazil's Rio de Janeiro corridor specialize in postpartum service lines, differentiating through technician certification in maternal aesthetic medicine.
- Muscle Toning:Electromagnetic stimulation protocols target rectus abdominis and gluteal muscle hypertrophy without exercise load.
- Skin Tightening:Thermal collagen remodeling applications attach to fat reduction for comprehensive contouring outcomes.
- Cellulite Reduction:Subdermal tissue remodeling targets fibrous septae and superficial fat herniation.
Weight management anchors revenue per clinic. Muscle toning applications are climbing the fastest as fitness studios adopt adjunct body sculpting services.
End User:
Capital intensity separates medical spa procurement from wellness center purchasing, with dermatology centers occupying a mid-tier position on equipment specifications.
- Medical Spas:These facilities deploy premium cryolipolysis and multi-modality platforms in standardized treatment room configurations. São Paulo and Seoul medical spa chains drive leasing model adoption, demanding outcome-linked payment structures from equipment vendors.
- Cosmetic Clinics:Physician-directed facilities combine surgical and non-surgical offerings with higher regulatory compliance burdens. Brazil's aesthetic medicine corridor concentrates procurement volume for ultrasound cavitation systems.
- Dermatology Centers:Skin-focused practices prioritize radiofrequency platforms with proven dermal remodeling endpoints.
- Wellness Centers:Holistic health facilities favor lower-frequency radiofrequency equipment with combined relaxation positioning.
- Fitness Studios:Gym-integrated locations deploy portable ultrasound and EMS devices as membership add-ons.
Medical spas dominate capital deployment. Fitness studios are gaining share fastest through portable device integration.
Deployment Type:
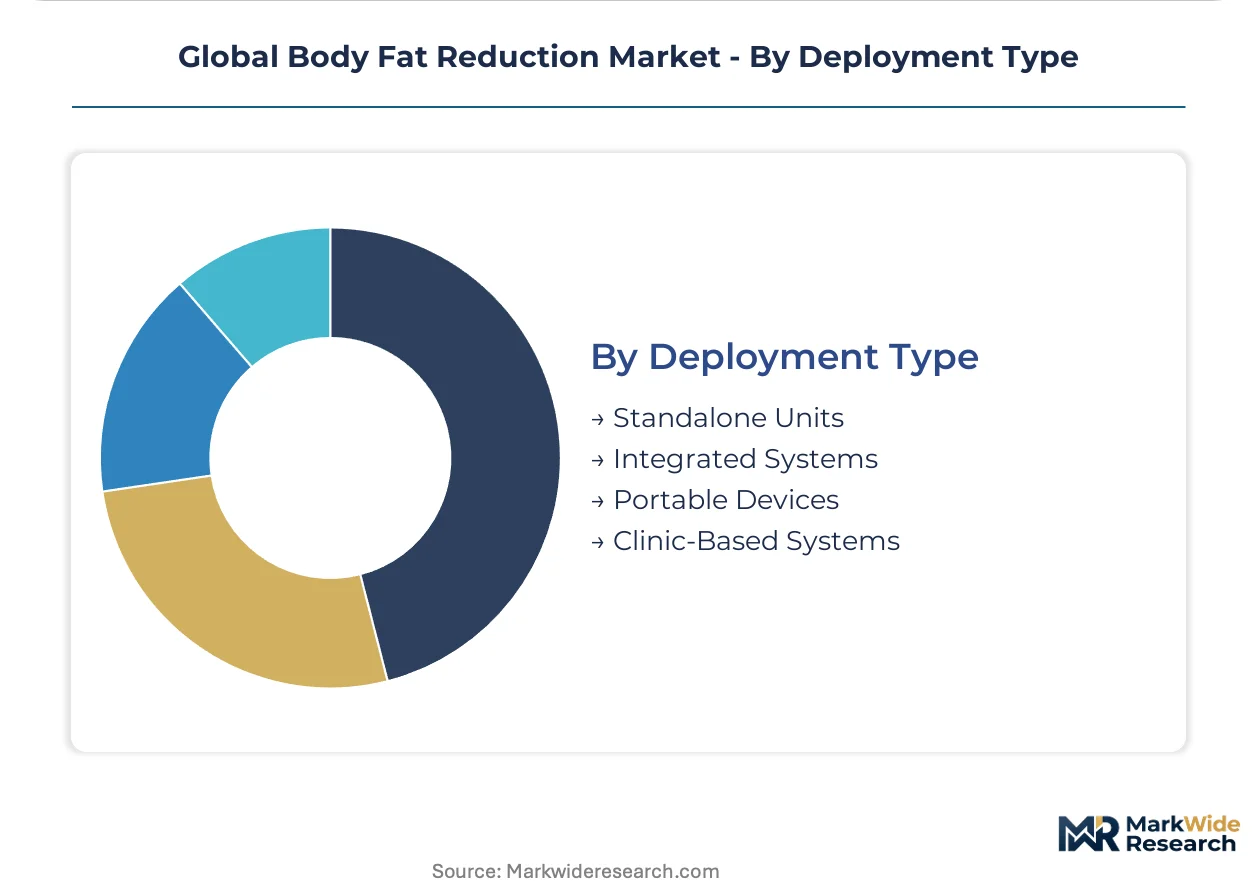
Procurement patterns bifurcate between capital purchase for standalone units and subscription models for integrated systems.
- Standalone Units:Single-modality devices with dedicated treatment protocols and simplified operator interfaces. Cosmetic clinics in the United States favor standalone cryolipolysis systems for predictable maintenance schedules and established FDA 510(k) predicates.
- Integrated Systems:Multi-modality platforms combining cryolipolysis, radiofrequency, and EMS in configurable architectures. Medical spa chains in South Korea demand integrated systems to minimize floor space and cross-train technical staff across service lines.
- Portable Devices:Lower-power systems designed for mobility between treatment locations or fitness studio integration.
- Clinic-Based Systems:Fixed installations with hardwired electrical and cooling infrastructure for high-throughput operations.
Standalone units dominate legacy installed base. Integrated systems and portable devices represent where manufacturer expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net import dependence for cryolipolysis hardware concentrates in Brazil and South Korea, while the United States and Germany maintain balanced trade in radiofrequency platforms. Device assemblers in Japan and China supply critical laser diodes to clinic operators across multiple jurisdictions.
United States
FDA 510(k) clearance pathways accelerate commercialization timelines for cryolipolysis and radiofrequency devices. The regulator's streamlined premarket notification process compresses platform launch schedules. Medical spa chains in Los Angeles and Miami drive leasing model adoption for multi-modality systems.
Brazil
São Paulo clinic chains deploy multi-applicator cryolipolysis configurations to maximize hourly patient throughput. ANVISA medical device registration requirements structure market access for imported energy-based platforms. Rio de Janeiro cosmetic clinics specialize in postpartum service lines with technician certification in maternal aesthetic medicine.
South Korea
MFDS medical device approvals govern commercialization of integrated EMS and radiofrequency platforms. Seoul medical spa chains demand outcome-linked payment structures from equipment vendors. Bundled membership packages around sequential cryolipolysis sessions lock in twelve-month patient retention.
Germany
Dermatology centers in Munich and Frankfurt favor high-frequency radiofrequency variants operating at forty megahertz for combined skin tightening applications. CE marking under MDR and ISO 13485 quality management standards constrain manufacturing and distribution capabilities. Procurement concentrates on integrated platforms with proven dermal remodeling endpoints.
Japan
PMDA medical device reviews structure approval timelines for laser and ultrasound cavitation systems. METI industrial policy supports domestic laser diode manufacturing for radiofrequency platform components. Tokyo aesthetic clinics drive adoption of combination therapy protocols pairing cryolipolysis with thermal collagen remodeling.
Global Body Fat Reduction Market Competitive Landscape
Concentration sits with integrated device manufacturers possessing pharmaceutical infrastructure and multi-modality portfolios. The vendor base spans three tiers: pharmaceutical-backed platforms, dedicated aesthetic device specialists, and emerging portable system developers. Competitive moves center on modality convergence through technology licensing and per-treatment revenue-sharing arrangements that transfer utilization risk to equipment suppliers.
Within the pharmaceutical-backed tier, AbbVie leverages clinical credibility across physician-administered segments. Among dedicated aesthetic specialists, Cynosure and Alma Lasers exemplify divergent platform strategies—Cynosure anchors dermatology center procurement through laser and radiofrequency systems, while Alma Lasers occupies a position spanning cryolipolysis through EMS-based toning portfolios. These three companies represent the capital-intensity divergence unwinding competitive stability in body fat reduction.
| Leading Market Players |
|---|
| AbbVie |
| Cynosure |
| Cutera |
| BTL Aesthetics |
| Candela |
| Alma Lasers |
| Lumenis |
| Venus Concept |
| InMode |
| Others |
Supply & Pricing Matrix
FDA 510(k) clearance tiers gate both supplier qualification and price stratification in body fat reduction equipment, with Class II medical device predicates creating dual barriers that concentrate premium pricing power among incumbent manufacturers while compressing margins for uncertified entrants seeking wellness channel placement.
Pricing Analysis
Medical spa chains anchor pricing stratification across premium, standard, and economy tiers in body fat reduction equipment. Price differentiation hinges on FDA clearance status and multi-modality configuration, with cleared cryolipolysis platforms commanding substantial premiums over uncertified alternatives. Pricing pressure intensifies in portable device segments as fitness studios negotiate volume-based procurement agreements. Wellness centers exhibit highest price sensitivity, while hospital outpatient departments prioritize certification compliance over acquisition cost.
Supply Chain Analysis
German and Japanese laser diode manufacturing concentrates supply risk for radiofrequency platform assemblers. Critical inputs span precision cooling compressors, vacuum-applicator arrays, and semiconductor RF generators. Single-source vulnerability in cryogenic component sourcing exposes device manufacturers to extended lead time disruptions. Distribution runs through medical device distributors in São Paulo and Seoul, with direct-to-clinic leasing models gaining share in South Korea and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment creates defendable moats in body fat reduction, as FDA 510(k) predicate accumulation and clinical evidence libraries raise switching costs for clinic operators evaluating platform migrations.
For Market Incumbents: Fortify position through backward integration into laser diode supply and captive manufacturing of precision cooling subsystems. Emerging portable device developers threaten wellness channel erosion, requiring incumbents to deploy certification leverage and clinical data libraries as defensive barriers. Capacity expansion in São Paulo and Seoul clinic networks anchors utilization-linked revenue streams. For New Entrants and Emerging Players: Lead with portable EMS and lower-frequency radiofrequency systems targeting fitness studio channels in the United States and Germany. White-space concentration sits in gym-integrated body sculpting memberships and postpartum recovery service lines in Brazil's Rio de Janeiro corridor. Direct-to-consumer financing partnerships unlock patient acquisition outside medical spa gatekeepers. For Investors and Strategic Acquirers: EMA Medical Device Regulation harmonization reshapes the acquisition landscape for European market entry capabilities. Long-term viability favors targets possessing multi-modality patent portfolios and established predicate device relationships with notified bodies. Watch FDA 510(k) clearance velocity as inflection signal for platform competitiveness and clinic procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Acceleration | Streamlined premarket notification compresses commercialization timelines for cryolipolysis platforms in United States medical spa networks. |
| Multi-Modality Platform Integration | Combined cryolipolysis-radiofrequency-EMS architectures displace standalone systems and optimize clinic floor space utilization. |
| Leasing and Subscription Model Adoption | Per-treatment revenue-sharing arrangements align equipment vendors with utilization rates in São Paulo and Seoul chains. |
| Portable Device Fitness Channel Penetration | Lower-power ultrasound and EMS systems enter gym membership bundles as adjunct body sculpting services outside medical aesthetics. |
| EMA MDR Harmonization Compliance | Unified CE marking pathways enable centralized manufacturing scale for European market entry and predicate device leverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with medical spa directors, biomedical engineers at device manufacturers, clinic procurement managers, and regulatory affairs specialists at notified bodies. Secondary validation drew from FDA 510(k) premarket notification databases, EMA medical device registration filings, ANVISA import records, and ISO 13485 quality management audit reports. Bottom-up installed base estimates triangulated against top-down market value reconstructions across modality and channel segments.
Across the analysis window, the forecast framework modeled volume and value trajectories through cryolipolysis, radiofrequency, ultrasound cavitation, laser therapy, and EMS product categories; weight management, postpartum recovery, muscle toning, skin tightening, and cellulite reduction applications; and medical spa, cosmetic clinic, dermatology center, wellness center, and fitness studio end users. CAGRs derived from historical penetration curves adjusted for regulatory clearance timelines and channel financing model transitions. Procedure volume per clinic and equipment replacement cycles fed utilization-linked revenue projections.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance velocity, laser diode supply stability, and clinic leasing model adoption would require recalibration. Practitioners should keep alternative scenarios live as EMA MDR enforcement intensity and private insurer reimbursement classification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Europe Weight Management Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Weight Management Market
Health and Wellness
Smart Wellness Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Yoga Market