
 Smart Breathing Trainer Market | 2026-2036
Smart Breathing Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Breathing Trainer Market Insights
Chinese sensor manufacturers are decoupling from legacy semiconductor supply chains by building dedicated MEMS foundries for respiratory wearables. Airofit A/S leverages its Copenhagen engineering base to sustain premium positioning in athletic respiratory conditioning. Powerbreathe International Ltd. anchors the United Kingdom's clinical rehabilitation segment with NHS procurement relationships. Oxa Life Ltd. differentiates through Swiss-designed textile-integrated biosensors that occupy the luxury wellness channel.
A smart breathing trainer is a digital therapeutic or wellness device that measures respiratory metrics—tidal volume, inhalation rate, and breath-hold capacity—through pressure transducers, capacitive sensing, or acoustic analysis, then delivers real-time biofeedback via haptic or visual cues to improve lung function, stress regulation, or athletic performance. Wearable devices command the highest margin pool due to hardware-software integration complexity and recurring subscription attach rates, while mobile applications face commoditization from wellness app store saturation. Artificial Intelligence segments extract premium pricing through personalized adaptive protocols, though Bluetooth-enabled baseline trainers still dominate unit volumes in price-sensitive channels.
FDA software-as-medical-device guidelines in the United States require clinical validation for claims targeting asthma or COPD management, while the EU MDR and CE marking framework in Europe impose biocompatibility and electromagnetic compatibility standards on wearable form factors. Health Canada and TGA in Australia maintain parallel but less stringent wellness-device pathways that permit broader marketing claims. Stakeholders must monitor whether regulators reclassify general wellness breathing trainers as medical devices as clinical evidence accumulates.
Market Dynamics
FDA software-as-medical-device validation requirements for respiratory health claims are compressing commercialization timelines and forcing hardware-software separation strategies across the competitive landscape.
Growth Catalysts
- Athletic biometric conditioning:Olympic training centers in Germany have institutionalized pulmonary protocols, creating procurement templates that cascade into corporate wellness programs across Western Europe.
- EU MDR wearable certification:CE marking for biocompatible form factors enables premium positioning in clinical rehabilitation channels, differentiating compliant hardware from wellness-only competitors.
- MEMS sensor localization:Chinese foundries dedicated to respiratory wearables are decoupling from legacy semiconductor supply chains, reducing component lead times for pressure transducer integration.
Market Restraints
- Clinical validation cost structure:FDA 510(k) pathways for asthma and COPD management claims require multi-center respiratory studies that exhaust mid-cap development budgets.
- Supply concentration in Nordic design houses:Copenhagen and Swiss engineering clusters control textile-integrated biosensor IP, creating licensing bottlenecks for wearable form factor entrants.
- Acoustic analysis substitution:Smartphone-native breath detection apps commoditize baseline respiratory metrics without hardware investment, pressuring standalone trainer pricing.
Strategic Opportunities
- Health Canada wellness pathway:Less stringent marketing claim permissions permit broader stress regulation positioning ahead of potential FDA reclassification.
- AI-adaptive protocol convergence:Machine learning personalization engines are merging with haptic feedback hardware to capture subscription revenue pools in athletic performance segments.
- NHS procurement standardization:United Kingdom clinical rehabilitation relationships provide reference architectures for national health system adoption across Commonwealth markets.
Industry Challenges
- Electromagnetic compatibility testing:EU MDR biocompatibility and EMC certification timelines extend wearable commercialization by 14-18 months, consuming working capital.
- Bluetooth protocol fragmentation:Legacy baseline trainers require firmware rearchitecture to support adaptive AI protocols, creating integration complexity with existing mobile application ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Breathing Trainer Market |
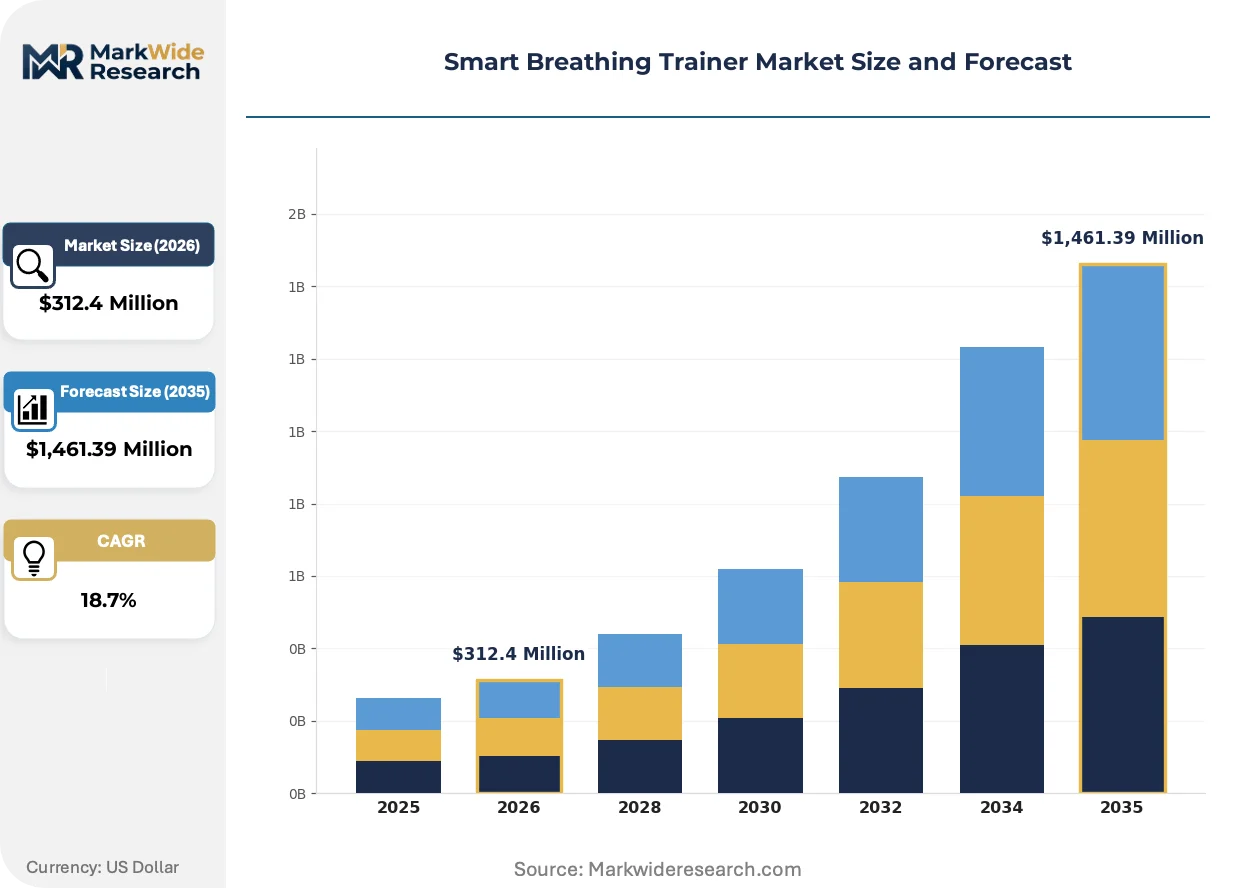
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,461.39 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Mobile Applications, Smart Inhalers, Breathing Sensors End User: Health Enthusiasts, Patients with Respiratory Issues, Athletes, Seniors Technology: Bluetooth, Cloud Computing, Artificial Intelligence, IoT Distribution Channel: Online Retail, Direct Sales, Medical Supply Stores, Pharmacies |
| Companies Covered | Oxa Life Ltd., Airofit A/S, Powerbreathe International Ltd., B-Arm Medical Co. Ltd., Oumua Inc., CHASKi Health Technologies Inc., Hexoskin, Prana Tech LLC, Breathwrk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Breathing Trainer Market Trends and Innovations
Respiratory wearable architecture is bifurcating between medical-grade validation pathways and wellness-native distribution, with sensor integration density determining margin capture.
Textile-integrated capacitive sensing is expanding into athletic performance monitoring by embedding conductive yarns directly into compression garments. Professional cycling teams and Nordic skiing programs have adopted these form factors for continuous respiratory load tracking during training. This convergence of apparel and medical device engineering is expanding into luxury wellness channels where hardware disappears into daily wear.
REACH substance restrictions and EU MDR biocompatibility standards are forcing material substitutions in skin-contact respiratory wearables. Manufacturers must reformulate elastomeric seals and adhesive interfaces to eliminate phthalates and latex proteins. German Olympic training centers and Swiss rehabilitation clinics are prioritizing compliant suppliers, creating procurement preference shifts that disadvantage non-European component sources.
Subscription unbundling from hardware is compressing customer acquisition economics in the direct-to-consumer channel. Athletic programs and corporate wellness buyers now expect software personalization layers separate from initial device purchase. Germany's pulmonary conditioning protocol adoption demonstrates this most visibly, where training centers negotiate enterprise software licenses independent of per-unit hardware procurement.
Smart Breathing Trainer Market Segmentation
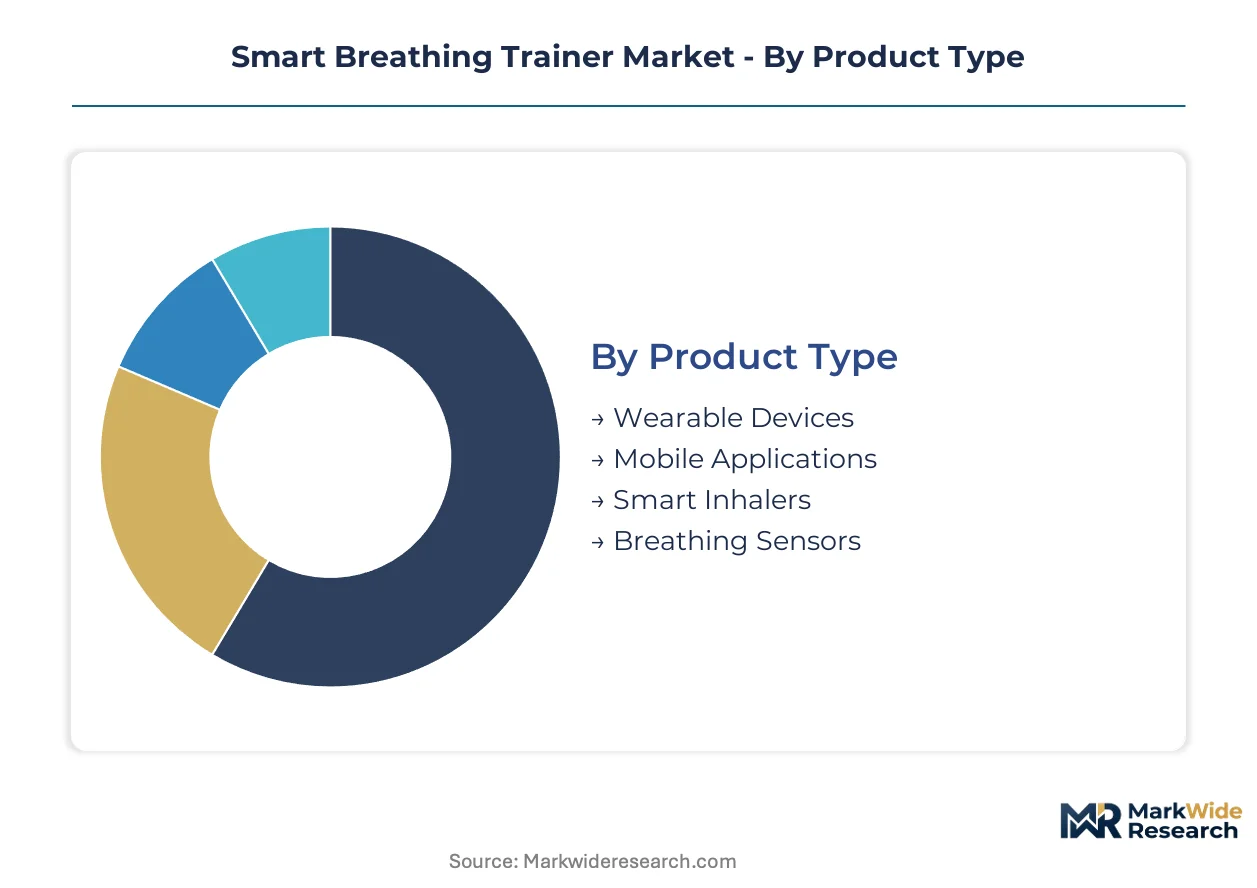
Product architecture and end-use specialization determine margin capture in smart breathing trainers. Hardware-software integration complexity and regulatory pathway selection create divergent competitive dynamics across segment boundaries.
Product Type:
Hardware investment thresholds and subscription attach rates segment buyer economics.
- Wearable Devices:Pressure transducers and textile-integrated biosensors embedded in garments or mouthpieces deliver continuous respiratory load tracking. German Olympic training centers and Swiss rehabilitation clinics prioritize CE-marked biocompatible form factors for institutional procurement.
- Mobile Applications:Smartphone-native acoustic analysis detects breath patterns without dedicated hardware. Wellness app store saturation compresses pricing power despite zero marginal distribution cost.
- Smart Inhalers:Dose-capture sensors synchronized with respiratory timing support asthma and COPD management protocols. FDA software-as-medical-device validation requirements constrain commercialization timelines for health claims.
- Breathing Sensors:Standalone pressure transducers or capacitive modules integrate into third-party training equipment. Chinese MEMS foundries are reducing component lead times for this modular category.
Wearable devices lead on scale; smart inhalers lead on momentum.
End User:
Performance objectives and clinical necessity shape feature requirements and price elasticity.
- Athletes:Pulmonary conditioning protocols demand real-time biometric feedback with haptic cueing for load management. Nordic skiing and professional cycling programs drive textile-integrated form factor adoption.
- Patients with Respiratory Issues:Clinical validation requirements for asthma and COPD management claims impose FDA 510(k) or EU MDR certification burdens. NHS procurement relationships in the United Kingdom anchor this segment's reference architecture.
- Health Enthusiasts:Stress regulation and general wellness positioning permits broader marketing claims under Health Canada and TGA pathways. Direct-to-consumer channels dominate with subscription-unbundled pricing models.
- Seniors:Simplified interfaces and fall-safe form factors prioritize usability over advanced biometric granularity. Corporate wellness programs in Germany are extending pulmonary protocols to this demographic.
Athletes lead on scale; patients with respiratory issues lead on momentum.
Technology:
Connectivity architecture determines data processing location and personalization depth.
- Artificial Intelligence:Machine learning engines generate adaptive training protocols from longitudinal respiratory pattern analysis. Athletic performance segments extract premium subscription pricing through personalization layers.
- Bluetooth:Low-energy protocols enable real-time biofeedback from wearable sensors to mobile interfaces. Legacy baseline trainers require firmware rearchitecture to support AI-adaptive convergence.
- Cloud Computing:Centralized data aggregation supports population-level respiratory health analytics and remote clinician monitoring. EU GDPR compliance adds data governance overhead for European deployments.
- IoT:Sensor mesh integration with environmental monitors contextualizes breathing metrics against air quality and altitude variables. Smart home ecosystem partnerships expand distribution reach.
Bluetooth leads on scale; artificial intelligence leads on momentum.
Distribution Channel:
Channel selection constrains marketing claim permissibility and customer acquisition economics.
- Direct Sales:Enterprise licensing to Olympic training centers and corporate wellness programs separates software subscriptions from hardware procurement. Germany's pulmonary protocol standardization demonstrates this model's traction.
- Online Retail:Direct-to-consumer platforms compress margins through price transparency and review-driven selection. Subscription unbundling from initial device purchase is reshaping unit economics.
- Medical Supply Stores:Clinical rehabilitation channel access requires CE marking or FDA clearance for respiratory health claims. Staff training on biometric interpretation adds operational overhead.
- Pharmacies:Point-of-care positioning adjacent to respiratory medication creates cross-sell opportunities for smart inhaler categories. Pharmacist recommendation influence varies by national healthcare system structure.
Online retail leads on scale; direct sales leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redirecting manufacturing investment toward jurisdictions with streamlined wellness-device pathways, while clinical validation requirements concentrate high-margin production in established certification hubs.
United States
FDA software-as-medical-device guidelines tighten validation requirements for respiratory health claims targeting asthma and COPD management. The agency's 510(k) pathway demands multi-center clinical studies that compress commercialization timelines for mid-cap developers. Boston and San Francisco Bay Area clusters concentrate digital therapeutic engineering talent for compliant hardware-software integration.
Germany
Olympic training centers in Cologne and corporate wellness programs in Munich have institutionalized pulmonary conditioning protocols at scale. EU MDR biocompatibility and electromagnetic compatibility standards enable premium CE-marked positioning for wearable form factors. Baden-Württemberg's medical device engineering corridor supplies textile-integrated biosensor expertise to rehabilitation clinics across Western Europe.
China
Dedicated MEMS foundries in Shenzhen and Shanghai are decoupling respiratory wearable production from legacy semiconductor supply chains. The national pharmaceutical regulator maintains less stringent wellness-device marketing claim permissions than FDA pathways. Yangtze River Delta manufacturing clusters are reducing pressure transducer component lead times for modular breathing sensor exports.
Switzerland
Swissmedic certification anchors luxury wellness channel positioning for textile-integrated biosensor devices. REACH substance restrictions and biocompatibility standards drive material reformulation in skin-contact respiratory wearables. Zurich and Geneva design houses control conductive yarn IP for compression garment form factors adopted by Nordic skiing programs.
United Kingdom
NHS procurement relationships in London and Manchester anchor clinical rehabilitation segment reference architectures. MHRA parallel recognition agreements with EU MDR frameworks maintain CE-marking equivalence for post-Brexit medical device distribution. Cambridge and Oxford research corridors supply respiratory pattern analysis expertise to Commonwealth health system adoption templates.
Smart Breathing Trainer Market Competitive Landscape
Danish and Swiss producers anchor the premium tier; Chinese fabricators hold cost-optimized component supply. The vendor base splits between clinical validation specialists and wellness-native entrants, with regulatory pathway selection determining margin capture. Three archetypes dominate: Nordic design houses with textile-integrated IP, NHS-anchored clinical rehabilitation suppliers, and MEMS-integrated hardware platforms. Capacity expansion into dedicated respiratory foundries and strategic licensing of conductive yarn patents constitute the primary competitive moves.
Among Copenhagen-based engineering clusters, Airofit A/S occupies a position exemplifying athletic respiratory conditioning specialization. Powerbreathe International Ltd. anchors the United Kingdom's clinical rehabilitation archetype through institutional procurement relationships. Oxa Life Ltd. represents the Swiss-designed luxury wellness tier, with textile-integrated biosensor positioning that commands premium channel placement.
| Leading Market Players |
|---|
| Oxa Life Ltd. |
| Airofit A/S |
| Powerbreathe International Ltd. |
| B-Arm Medical Co. Ltd. |
| Oumua Inc. |
| CHASKi Health Technologies Inc. |
| Hexoskin |
| Prana Tech LLC |
| Breathwrk |
| Others |
Pricing and Supply Chain Analysis
Textile-integrated capacitive sensing migration is compressing hardware bill-of-materials while concentrating IP licensing power in Swiss and Copenhagen design houses. German Olympic training centers and NHS procurement frameworks now demand CE-marked biocompatible form factors, forcing cost premiums for compliant suppliers while Chinese MEMS foundries undercut modular component pricing.
Pricing Analysis
Direct-to-consumer channel margins face compression from subscription unbundling expectations, with enterprise software licenses to corporate wellness programs commanding premium positioning. Price differentiation hinges on FDA software-as-medical-device certification tier and textile-integrated sensor density. Pricing pressure stems from smartphone-native acoustic analysis apps commoditizing baseline respiratory metrics. Health enthusiasts exhibit highest price sensitivity; clinical rehabilitation channels show lowest elasticity due to institutional procurement standards.
Supply Chain Analysis
Dual-sourcing mandates from German Olympic training centers and Swiss rehabilitation clinics are fragmenting pressure transducer procurement across Shenzhen MEMS foundries and Baden-Württemberg component suppliers. The supply chain draws from China for capacitive sensing modules, Switzerland for conductive yarn IP, and Germany for electromagnetic compatibility testing infrastructure. Single-source vulnerability concentrates in Nordic textile-integrated biosensor licensing. Distribution runs through direct enterprise sales for institutional buyers and online retail for wellness-native consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as athletic biometric conditioning and clinical validation requirements concentrate procurement around certified premium specifications. Demand is shifting toward AI-adaptive protocol hardware-software bundles that command recurring revenue attach rates.
For Market Incumbents: Acquire conductive yarn patent portfolios to secure textile-integrated form factor exclusivity against emerging Chinese MEMS-integrated hardware platforms. Deepen backward integration into dedicated respiratory MEMS foundries to reduce component lead time exposure. Prioritize EU MDR electromagnetic compatibility certification investment to defend institutional channel access against wellness-native entrants lacking clinical validation infrastructure. For New Entrants and Emerging Players: The mid-tier price gap between Swiss luxury wellness devices and Chinese modular sensors offers white-space positioning for Health Canada-compliant stress regulation trainers. Target corporate wellness programs in Commonwealth markets seeking NHS-referenceable clinical architectures without FDA 510(k) validation burdens. Pursue pharmacist recommendation partnerships in national healthcare systems with point-of-care distribution density. For Investors and Strategic Acquirers: Valuations sit cheapest among Bluetooth-enabled baseline trainer manufacturers facing firmware rearchitecture costs for AI protocol convergence. Long-term viability favors clinical validation specialists with institutional procurement relationships over wellness-native app developers facing commoditization. Monitor FDA reclassification signals for general wellness breathing trainers as clinical evidence accumulates—this regulatory shift would reshape margin pools materially.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR biocompatibility certification unlocks German Olympic training center procurement templates. |
| Software Companion Development | Subscription-unbundled AI-adaptive protocols capture recurring revenue from enterprise wellness licenses. |
| Hospital System Partnership | NHS procurement relationships provide reference architectures for Commonwealth health system adoption. |
| Backward Integration into MEMS Foundries | Captive pressure transducer production insulates against legacy semiconductor supply chain volatility. |
| Reimbursement Strategy | FDA software-as-medical-device clearance enables asthma and COPD management claims for payer coverage. |
Research Methodology
Coverage spans Germany, Switzerland, the United Kingdom, China, and the United States, with primary inputs from each market cluster. The analysis combines interviews with respiratory device engineering leads, NHS procurement managers, Olympic training center performance directors, and MEMS foundry operations heads with secondary validation from FDA 510(k) filings, EU MDR certification databases, and hospital procurement contract registries. Bottom-up segment sizing triangulates against top-down macroeconomic respiratory health expenditure trends.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. The analytical framework models product type, end user, technology architecture, and distribution channel dimensions, with regulatory pathway selection as a cross-cutting stratifier. CAGRs derive from segment-level growth rate blending weighted by base-year revenue contribution. Forecast inputs include MEMS sensor cost curves and institutional procurement cycle timing.
Caveats apply where FDA reclassification of wellness devices or REACH substance restriction expansions could materially shift the outlook. Deviation in EU MDR certification timeline enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Yoga Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Brain Fitness Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Global Body Fat Reduction Market