
 ACF Supplements Market | 2026-2036
ACF Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
ACF Supplements Market Outlook
The ACF Supplements Market is recalibrating around a widening gap between premium clinically validated formulations and commodity-grade alternatives. Glanbia Nutritionals leverages its dairy-derived protein expertise to anchor the premium tier with sports-specific positioning. NOW Foods competes on third-party testing transparency and value-oriented SKUs across mass retail channels. Herbalife Nutrition controls a direct-to-consumer infrastructure that sustains recurring revenue in personalized nutrition programs.
Animal component-free supplements exclude all materials derived from animal tissue, serum, or byproducts, relying instead on plant fermentation, microbial expression systems, or synthetic biology pathways to deliver bioactive compounds such as recombinant proteins, algae-derived omega fatty acids, and mineral chelates for cell culture and human consumption. Protein powders dominate current manufacturing volume, though herbal extracts represent the fastest-expanding margin pool as adaptogenic positioning commands shelf-space premiums. Gummies as a delivery form are displacing conventional tablets among senior and vegan target consumers who prioritize palatability compliance.
EFSA novel food assessments and FDA cGMP enforcement for dietary supplements collectively elevate barrier costs for new entrants while rewarding batch-traceable supply chains. The EU Green Deal's bioeconomy targets and REACH chemical safety registrations further constrain raw material sourcing flexibility for European formulators. Stakeholders must monitor evolving serum-free certification standards from ISO working groups and decide whether to absorb compliance costs or exit marginal product lines.
Market Dynamics
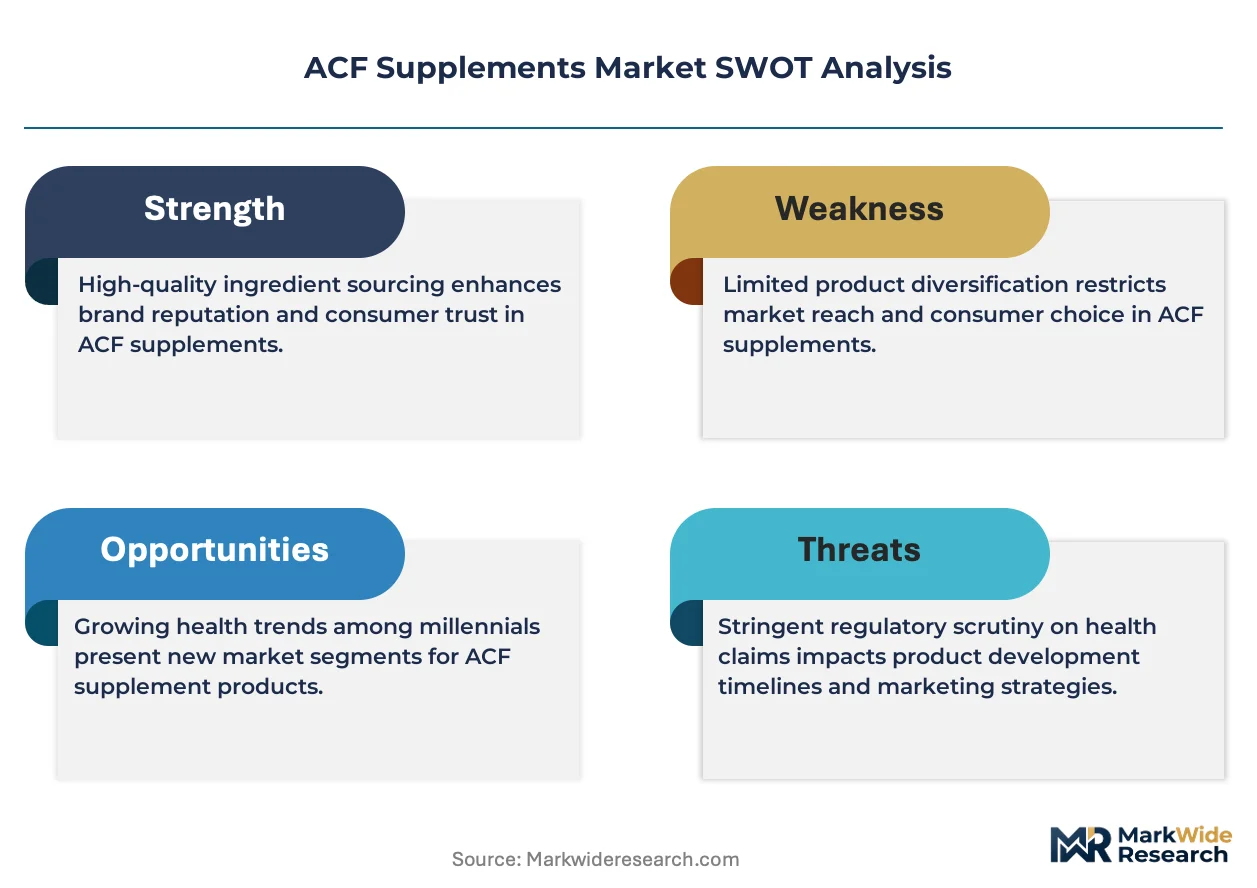
Clean-label certification mandates from EFSA and FDA are bifurcating the ACF Supplements Market into traceable premium supply chains and opaque commodity channels. Formulators now face irreversible compliance cost structures that favor scaled operators with batch-traceable infrastructure.
Growth Catalysts
- Sports Nutrition Adoption:Fitness enthusiasts in Germany and the United States are driving volume for clinically validated protein isolates and adaptogenic formulations.
- EFSA Novel Food Pathways:Streamlined assessments for microbial-derived proteins accelerate time-to-market for fermentation-based bioactives.
- Gummy Delivery Conversion:Senior and vegan consumer segments prioritize palatability compliance, displacing conventional tablet formats at mass retail.
Market Restraints
- REACH Chemical Registration Burden:EU Green Deal bioeconomy targets constrain raw material sourcing flexibility for European mineral chelate suppliers.
- Serum-Free Certification Complexity:ISO working group standards elevate barrier costs for cell culture supplement entrants without existing quality infrastructure.
- Algae Omega Fatty Acid Supply Concentration:Limited fermentation capacity in specific coastal zones creates input volatility for DHA/EPA formulations.
Strategic Opportunities
- Direct-to-Consumer Infrastructure:Personalized nutrition programs with recurring revenue models bypass traditional retail margin compression.
- Synthetic Biology Convergence:Integration of precision fermentation with AI-driven strain optimization unlocks novel recombinant protein economics.
- FDA cGMP Enforcement Tailwinds:Elevated compliance requirements reward batch-traceable supply chains with shelf-space access at institutional buyers.
Industry Challenges
- Formulation Talent Scarcity:Shortage of specialists trained in microbial expression systems and plant-fermentation scale-up constrains R&D throughput.
- Third-Party Testing Capex:Independent laboratory verification infrastructure requires substantial capital deployment before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ACF Supplements Market |
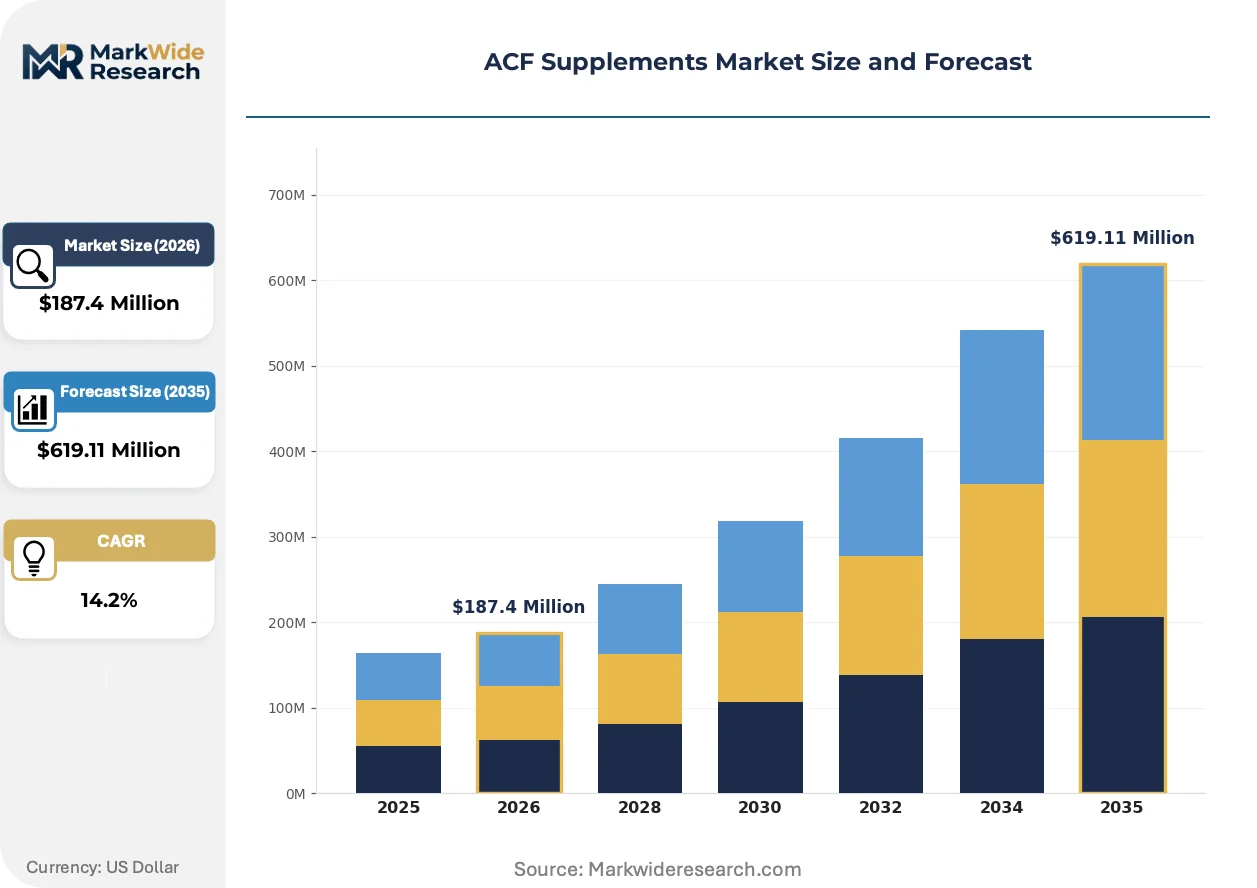
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Powders, Vitamins, Minerals, Herbal Extracts Target Consumer: Athletes, Fitness Enthusiasts, Seniors, Vegans Form: Powders, Capsules, Tablets, Gummies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | Glanbia Nutritionals, Herbalife Nutrition, NOW Foods, Nestlé Health Science, Herbaland Naturals, STEMCELL Technologies Inc., Kerry Inc., Xell AG, InVitria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ACF Supplements Market Strategic Shifts
Precision fermentation infrastructure is consolidating around industrial biotechnology platforms that displace traditional extraction methods. Three interconnected developments are compressing development timelines and reshaping competitive boundaries.
Microbial expression systems for recombinant protein production are consolidating manufacturing volume previously captured by animal-derived isolates. Biopharma contract manufacturers with existing fermentation capacity are retrofitting lines for dietary supplement-grade outputs. This technology is consolidating margin pools toward vertically integrated biotech platforms with captive strain libraries.
EFSA novel food assessment harmonization with FDA Generally Recognized as Safe determinations is compressing dual-market registration timelines. European formulators now parallel-track submissions to capture synchronized launch windows. Cell culture supplement categories face the steepest documentation requirements under this regulatory convergence.
Adaptogenic herbal extract positioning commands shelf-space premiums as procurement patterns concentrate around clinically substantiated SKUs. Mass retail buyers now require peer-reviewed efficacy data before category placement, displacing legacy proprietary blend formulations. Germany's pharmacy channel exemplifies this certification-driven preference shift most acutely.
ACF Supplements Market Segmentation
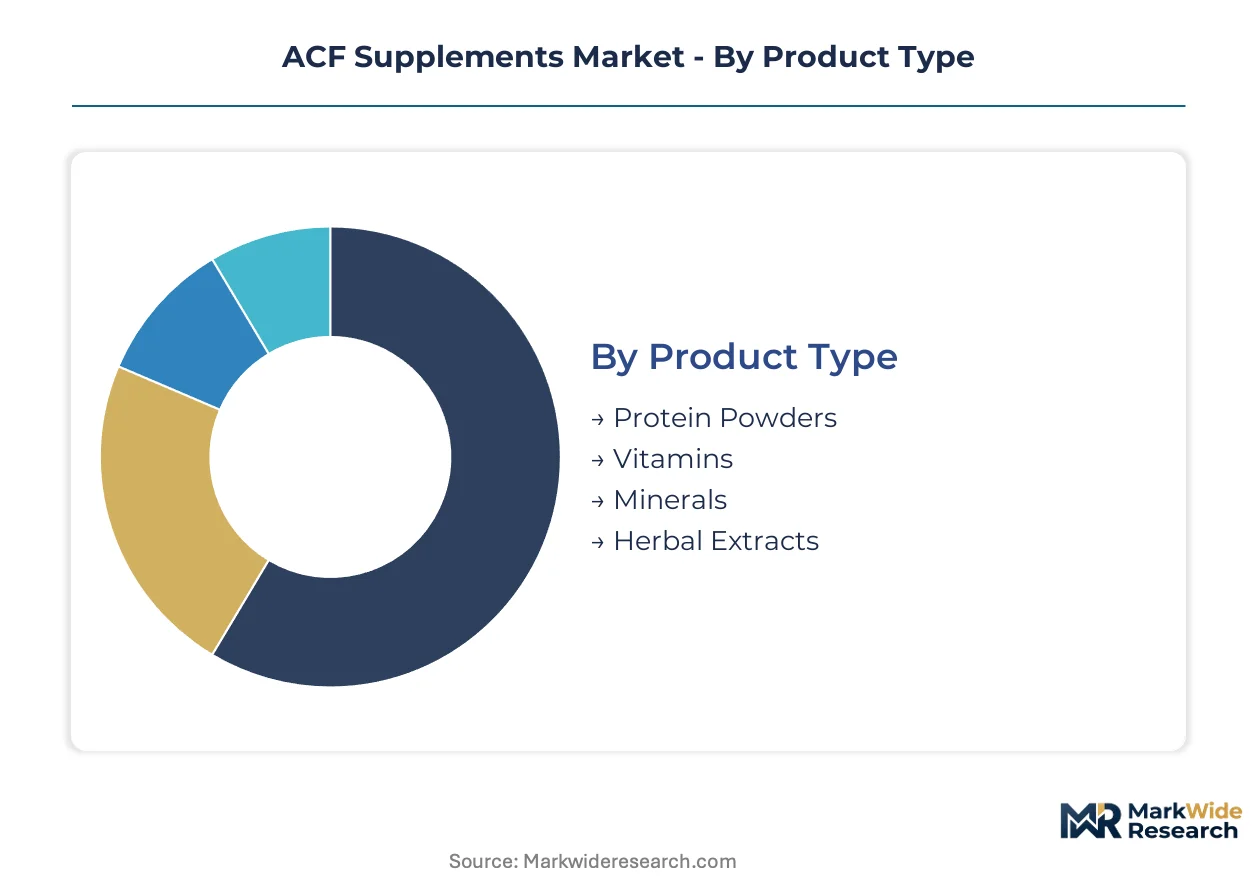
Segmentation in the ACF Supplements Market reveals how formulation requirements diverge across certification tiers, delivery technologies, and channel economics. Manufacturers must align production assets with specific traceability standards and palatability demands rather than pursuing undifferentiated scale.
Product Type:
Standardization dominates commodity-grade mineral and vitamin production, while protein isolates and herbal extracts command premium customization for sports and adaptogenic positioning.
- Protein Powders:Dairy-derived and microbial-fermented isolates supply the bulk of manufacturing volume. Demand concentrates among German and US fitness enthusiasts seeking clinically validated amino acid profiles with batch-traceable supply chains.
- Herbal Extracts:Adaptogenic formulations featuring ashwagandha and rhodiola require substantiated efficacy data for pharmacy channel placement. Procurement in Germany's pharmacy network prioritizes peer-reviewed studies over proprietary blends.
- Vitamins:Synthetic and fermentation-derived compounds serve cost-sensitive mass retail with standardized potency specifications.
- Minerals:Chelated forms face REACH registration constraints in Europe, limiting sourcing flexibility for bioeconomy-compliant suppliers.
Leading the category by volume: Protein Powders. Expanding most quickly: Herbal Extracts.
Target Consumer:
Athlete-grade certification requirements create the steepest margin tier, while senior and vegan segments drive format innovation through palatability preferences.
- Fitness Enthusiasts:Clinically validated protein isolates and adaptogenic stacks dominate purchasing. US specialty retail channels reward third-party tested SKUs with premium shelf positioning.
- Athletes:Competition-grade formulations require banned-substance certification and lot-level traceability. German sports nutrition infrastructure sustains recurring demand for dairy-derived and microbial protein sources.
- Seniors:Gummy delivery formats displace tablets due to compliance advantages. Palatability requirements reshape procurement toward flavor-masked mineral chelates.
- Vegans:Animal component-free certification mandates exclude all serum-derived inputs. Algae-sourced omega fatty acids and plant-fermented proteins anchor formulation choices.
Highest certification burden: Athletes. Steepest format conversion: Seniors.
Form:
Manufacturing asset intensity separates powder bulk production from precision-dosed capsules and emerging gummy infrastructure.
- Powders:Bulk production scales through existing dairy and fermentation facilities. Sports nutrition volume in Germany and the United States flows through this format.
- Gummies:Senior and vegan compliance preferences drive displacement of conventional tablets. Gelatin-free pectin bases require modified production lines and moisture-controlled packaging.
- Capsules:Two-piece hard shells and softgels serve mineral and omega fatty acid delivery with precise unit dosing.
- Tablets:Compression economics favor high-volume vitamin and mineral production, though share erodes in palatability-sensitive segments.
Dominant by manufacturing throughput: Powders. Gaining share fastest: Gummies.
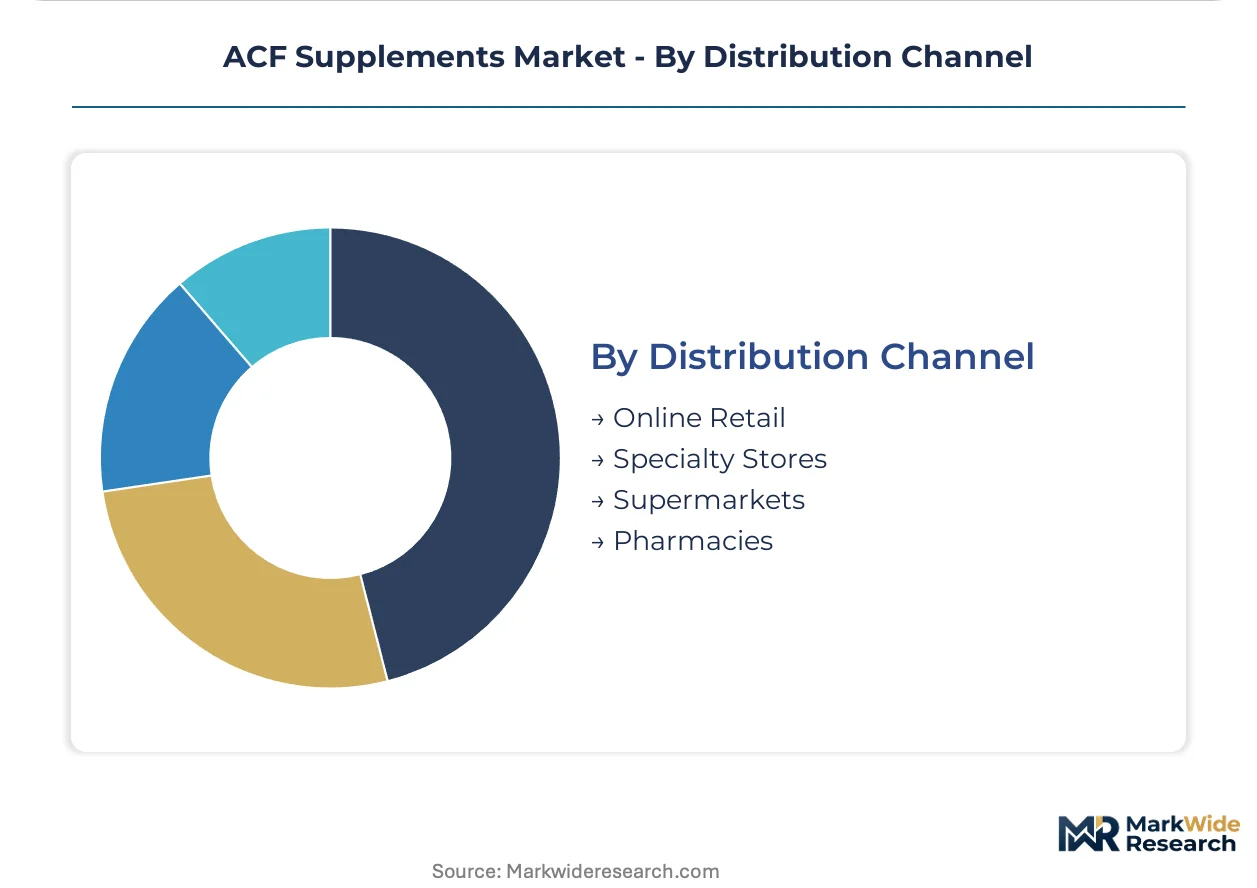
Distribution Channel:
Channel economics bifurcate between traceability-demanding institutional buyers and convenience-oriented direct-to-consumer platforms.
- Specialty Stores:Sports nutrition retailers in Germany and the United States require third-party testing documentation and clinically substantiated SKUs. Batch-traceable supply chains secure shelf access.
- Online Retail:Direct-to-consumer infrastructure sustains recurring revenue through personalized nutrition subscriptions. Herbalife Nutrition's model exemplifies this channel's economics.
- Pharmacies:Germany's pharmacy channel enforces the strictest efficacy documentation requirements. EFSA novel food assessments and peer-reviewed data precede category placement.
- Supermarkets:Mass retail buyers prioritize value-oriented SKUs with clean-label certification for mainstream consumer penetration.
Highest certification barrier: Pharmacies. Fastest infrastructure buildout: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mannheim's pharmaceutical corridor anchors European ACF supplement certification infrastructure, while fermentation capacity clusters along coastal zones in the United States and Asia-Pacific.
United States
Fitness enthusiasts in California and Texas drive demand for clinically validated protein isolates. FDA cGMP enforcement elevates compliance costs for dietary supplement manufacturers. Boston's biotech corridor hosts precision fermentation facilities retrofitting biopharma lines for supplement-grade outputs.
Germany
Pharmacy channel procurement concentrates around peer-reviewed efficacy documentation for adaptogenic formulations. EFSA novel food assessments govern microbial-derived protein approvals. Mannheim and Frankfurt sustain sports nutrition infrastructure with batch-traceable supply chains for athlete-grade certification.
China
Precision fermentation capacity expansion targets recombinant protein production for domestic and export markets. NMPA and SAMR oversight aligns with dual carbon goals constraining traditional extraction methods. Yangtze River Delta biotech parks integrate AI-driven strain optimization platforms.
Canada
Algae-sourced omega fatty acid production concentrates in coastal British Columbia with limited fermentation capacity creating input volatility. Health Canada and PMRA regulate novel food submissions for microbial expression systems. Vancouver's biotechnology cluster advances serum-free certification standards.
India
Contract manufacturing demand rises for plant-fermented protein exports to European and North American markets. FSSAI and CDSCO navigate novel food pathways for microbial-derived bioactives. Hyderabad and Bengaluru host fermentation scale-up facilities serving global supplement formulators.
ACF Supplements Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-tier differentiation, with traceable supply chains commanding institutional buyer access. The vendor base stratifies between dairy-derived protein specialists, direct-to-consumer platform operators, and fermentation-technology integrators. Three archetypes dominate: vertically integrated biotech platforms with captive strain libraries, third-party testing transparent value players, and personalized nutrition subscription infrastructure owners. Competitive moves concentrate on batch-traceable supply chain investments and precision fermentation capacity expansion.
Within the dairy-derived protein archetype, Glanbia Nutritionals represents premium-tier sports nutrition positioning. NOW Foods occupies the third-party testing transparency tier with mass retail value orientation. Herbalife Nutrition exemplifies direct-to-consumer infrastructure economics through recurring revenue subscription models.
| Leading Market Players |
|---|
| Glanbia Nutritionals |
| Herbalife Nutrition |
| NOW Foods |
| Nestlé Health Science |
| Herbaland Naturals |
| STEMCELL Technologies Inc. |
| Kerry Inc. |
| Xell AG |
| InVitria |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal bioeconomy targets gate qualified supply for premium-tier ACF supplement positioning, constraining raw material sourcing flexibility while elevating batch-traceable certification costs that filter commodity-grade competitors from institutional buyer access. REACH chemical registration burdens and FDA cGMP enforcement collectively reshape supplier economics, compressing margins for non-compliant operators and concentrating pricing power among scaled players with captive fermentation infrastructure.
Pricing Analysis
Yield-linked pricing for microbial-derived protein isolates anchors value capture for fermentation-technology integrators serving German pharmacy and US specialty retail channels. Three-tier pricing structure across premium athlete-grade certification, standard clean-label compliance, and economy-grade commodity supply reflects divergence in third-party testing depth and lot-level traceability. Cost compression in commodity mineral chelates intensifies due to algae omega fatty acid supply concentration in limited coastal fermentation zones. Senior and vegan consumer segments demonstrate lowest price sensitivity for palatability-optimized gummy formats, while mass retail supermarket buyers prioritize value-oriented SKUs with baseline EFSA novel food compliance.
Supply Chain Analysis
Direct-to-specialty-retail channels handle clinically validated protein isolate demand from German fitness enthusiasts and US sports nutrition buyers, while direct-to-consumer infrastructure sustains recurring subscription revenue for personalized nutrition programs. Manufacturing concentration clusters in Germany's Mannheim pharmaceutical corridor, US coastal biotech zones around Boston, and China's Yangtze River Delta precision fermentation parks. Raw material sourcing draws from microbial expression systems, algae-derived omega fatty acids, and plant-fermented protein substrates. Single-source vulnerability in DHA/EPA fermentation capacity creates input volatility for European formulators navigating REACH registration constraints. Distribution runs through batch-traceable supply chains for institutional pharmacy and specialty retail placement, with online platforms capturing margin from personalized subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food assessment harmonization with FDA cGMP enforcement erects a compliance moat that rewards incumbent investments in batch-traceable infrastructure while elevating barrier costs beyond reach for undercapitalized entrants.
For Market Incumbents: Cement premium-tier positioning through captive precision fermentation capacity expansion in Germany's Mannheim corridor and US coastal biotech zones, insulating against microbial expression system talent scarcity that constrains R&D throughput for commodity competitors. Deepen backward integration into AI-driven strain optimization platforms to lock in recombinant protein yield advantages and defend margin position against biopharma contract manufacturers retrofitting lines for supplement-grade outputs.
For New Entrants and Emerging Players: Direct-to-consumer subscription infrastructure represents the most penetrable white-space target, bypassing pharmacy channel efficacy documentation requirements that block mass retail placement for unproven formulations. Synthetic biology convergence with personalized nutrition programs offers a defensible go-to-market angle, leveraging recurring revenue models to fund gradual certification investments for eventual institutional channel access.
For Investors and Strategic Acquirers: FDA cGMP enforcement tailwinds accelerating shelf-space consolidation at institutional buyers is the leading indicator that vertically integrated biotech platforms with captive strain libraries will capture disproportionate margin expansion across the analysis window. Acquisition focus should center on fermentation-technology integrators with existing EFSA novel food approvals and scalable microbial expression systems, with serum-free certification standard finalization from ISO working groups serving as the critical inflection signal for regulatory-driven competitive repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captures recombinant protein economics from biopharma line retrofits in Boston and Mannheim clusters. |
| EFSA Novel Food Parallel-Track Submission | Compresses dual-market registration timelines for microbial-derived bioactives in EU and US corridors. |
| Direct-to-Consumer Infrastructure Buildout | Bypasses pharmacy channel margin compression through personalized nutrition subscription economics. |
| Serum-Free Certification Investment | Secures ISO working group compliance for cell culture supplement categories ahead of standard finalization. |
| Algae Omega Supply Diversification | Mitigates DHA/EPA input volatility from coastal fermentation zone concentration through multi-source contracting. |
Study Parameters
Document review covered EFSA novel food assessment databases, FDA cGMP enforcement records, and REACH chemical registration filings, complemented by interviews with formulation scientists at precision fermentation facilities, regulatory affairs leads navigating dual-market submissions, procurement directors at German pharmacy networks, sports nutrition brand managers, and contract manufacturing executives in India and China. Secondary validation drew from customs trade data for protein isolate flows, SEC filings for publicly traded nutrition platforms, and ISO working group draft standards for serum-free certification. Bottom-up demand modeling for protein powder, herbal extract, vitamin, and mineral segments was cross-referenced against top-down market sizing from fermentation capacity disclosures and retail channel audit data.
Historical growth trajectories for sports nutrition adoption and gummy format conversion were cross-referenced against panel input from specialty retail buyers and direct-to-consumer platform operators. Segmentation dimensions spanned product type, target consumer certification tier, delivery form manufacturing asset intensity, and distribution channel traceability requirements. CAGRs were derived from trend extrapolation anchored to EFSA assessment timeline acceleration and FDA enforcement intensity patterns, with precision fermentation yield improvements and algae omega supply constraints serving as industry-specific forecast inputs across the projection horizon.
Caveats apply where EFSA novel food pathway delays, REACH registration scope expansions, or algae fermentation capacity disruptions could materially shift the outlook for microbial-derived bioactive commercialization timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Arginine Supplement Market
Sports Nutrition
Creatine Monohydrate Market
Sports Nutrition
L-Carnitine Supplements Market
Sports Nutrition
B2B Sports Nutrition Market
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
North America Protein Based Sports Drinks Market
Sports Nutrition
Energy and Protein Bars Market
Sports Nutrition
Japan Sports Drink Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
United States Weight Management Market
Sports Nutrition
Caloric Supplements Market
Sports Nutrition
UK Sports Nutrition Market
Sports Nutrition
Cricket Protein Powder Market
Sports Nutrition
Germany Sports Nutrition Market