
 Smart Wellness Market | 2026-2036
Smart Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Wellness Market Outlook
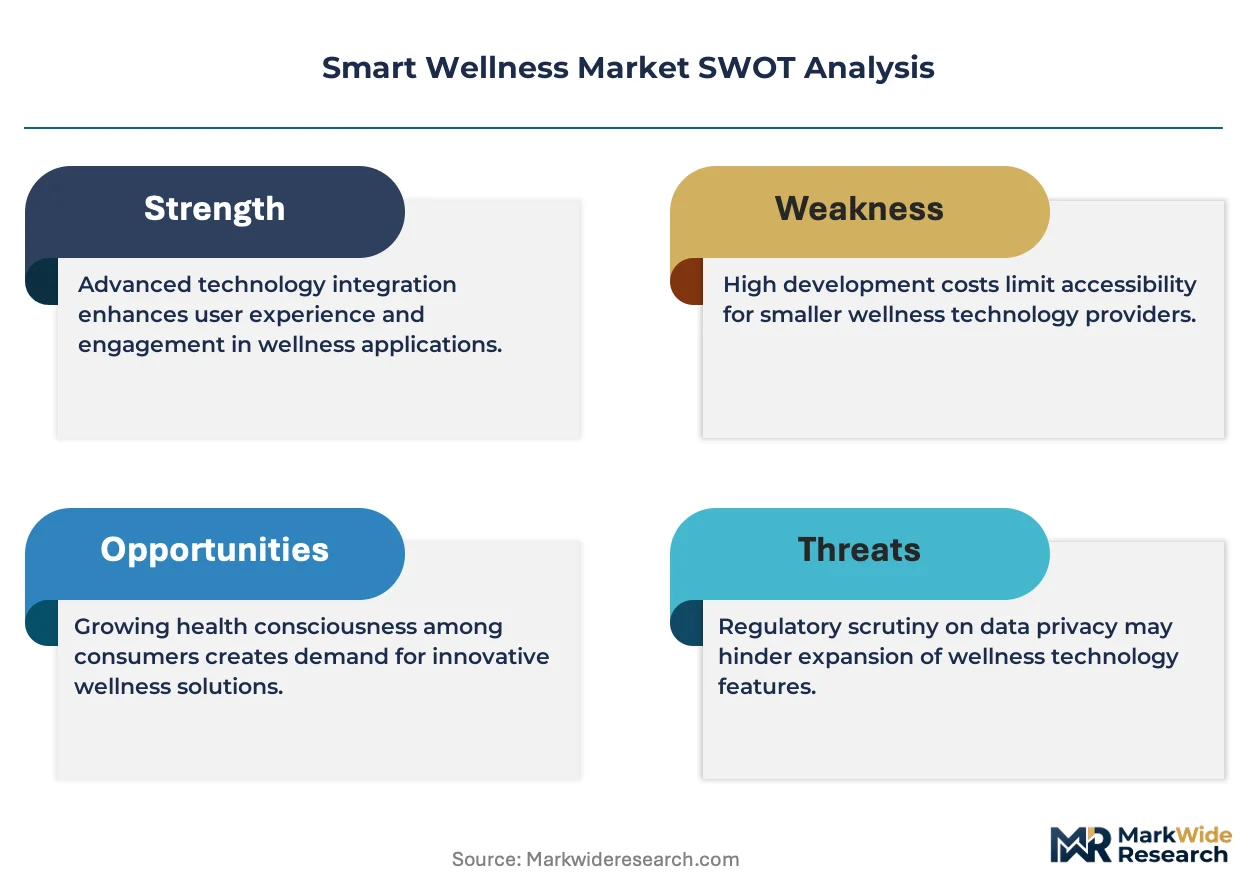
The EU AI Act is recalibrating compliance costs for biometric wellness algorithms, forcing smaller wearable OEMs to restructure data governance architectures. Apple Inc. leverages its vertically integrated HealthKit ecosystem to sustain premium positioning across consumer and clinical channels. Samsung Electronics Co., Ltd. anchors its Galaxy Watch portfolio through FDA-cleared sleep apnea detection, while Garmin Ltd. dominates aviation and marine wellness niches with specialized physiological monitoring.
Smart wellness encompasses sensor-integrated hardware and software systems that capture, analyze, and act upon biometric, behavioral, and environmental data to optimize individual health outcomes. Core functional parameters include photoplethysmography (PPG) for heart rate variability, accelerometry for activity classification, and machine learning inference at the edge for real-time coaching. Wearable devices and connected health devices occupy the largest installed base, though smart rings are recording the fastest attach rate among privacy-conscious users seeking minimal form factors. Wellness coaching applications capture disproportionate recurring revenue through subscription models, while fitness monitoring remains the most mature segment with compressed hardware margins.
FDA 510(k) clearances for irregular rhythm notification and the EU AI Act's risk-based classification for biometric inference engines are tightening product standards while expanding reimbursable use cases for clinically validated devices. Japan's PMDA and South Korea's MFDS are converging on harmonized software-as-a-medical-device frameworks that reduce dual-market registration friction. Stakeholders must decide whether to absorb escalating regulatory compliance costs or exit clinical-adjacent segments in favor of purely consumer-grade wellness positioning.
Market Dynamics
The EU AI Act's risk-based classification for biometric inference engines is forcing platform providers to restructure algorithmic governance architectures and absorb compliance costs that disproportionately burden smaller wearable OEMs.
Growth Catalysts
- FDA 510(k) clearances for irregular rhythm notification:Expanding reimbursable use cases for clinically validated devices in employer-sponsored preventive health programs across the United States.
- Japan PMDA and South Korea MFDS harmonization:Converging software-as-a-medical-device frameworks reducing dual-market registration friction for connected health platforms.
- Photoplethysmography edge inference:Enabling real-time heart rate variability coaching without cloud dependency, accelerating adoption among privacy-conscious enterprise wellness buyers.
Market Restraints
- EU AI Act compliance cost concentration:Algorithmic transparency mandates for biometric data processing impose disproportionate burden on mid-tier sensor manufacturers lacking captive legal resources.
- Accelerometer and PPG sensor supply concentration:Critical optical and motion sensing components face single-source dependency risk from East Asian specialty foundries.
- Clinical validation timeline friction:FDA 510(k) clearance pathways for sleep apnea detection and arrhythmia notification extend product launch cycles by 18-36 months versus consumer-grade alternatives.
Strategic Opportunities
- Smart ring form factor acceleration:Minimal biometric capture devices recording fastest attach rates among privacy-conscious users seeking discrete physiological monitoring without wrist-worn visibility.
- Wellness coaching application recurring revenue:Subscription-based behavioral intervention platforms capturing disproportionate lifetime value versus compressed-margin hardware sales.
- Aviation and marine specialized monitoring:Garmin's dominance in pilot and mariner physiological safety creates defensible niche for hypoxia and fatigue detection systems with regulatory tailwinds from FAA and maritime safety frameworks.
Industry Challenges
- Machine learning edge deployment talent scarcity:Embedded AI inference optimization for ultra-low-power wearables requires rare cross-functional expertise spanning signal processing, firmware architecture, and clinical validation protocols.
- Legacy electronic health record integration complexity:HealthKit and proprietary platform APIs create fragmented data exchange standards that complicate enterprise wellness program deployment at scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Wellness Market |
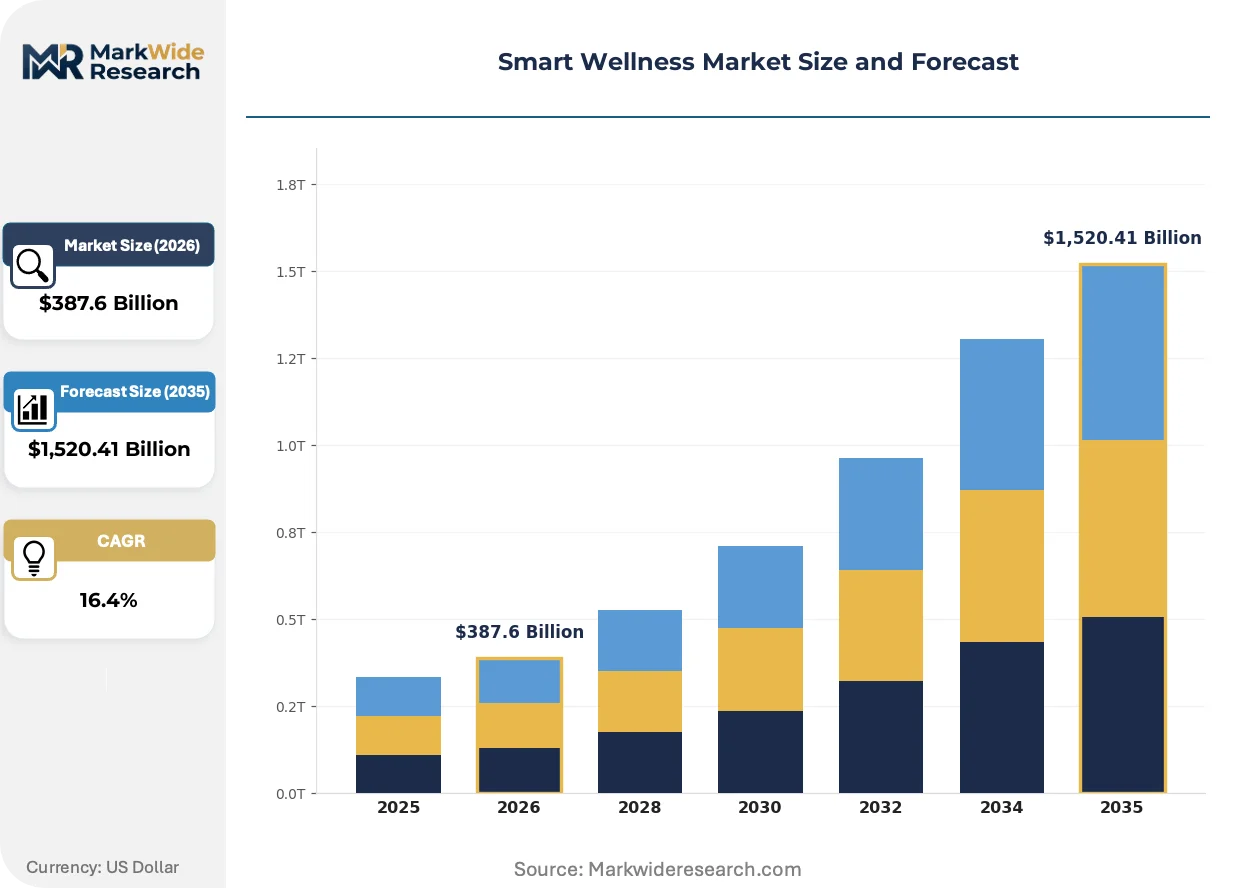
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,520.41 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Smart Rings, Fitness Trackers, Connected Health Devices Technology: IoT, AI, Bluetooth, NFC Application: Fitness Monitoring, Health Management, Sleep Tracking, Wellness Coaching End User: Consumers, Healthcare Providers, Corporate Wellness Programs, Fitness Enthusiasts |
| Companies Covered | Apple Inc., Google LLC, Garmin Ltd., Samsung Electronics Co., Ltd., Oura Health Oy, WHOOP, Inc., Philips Healthcare, Omron Healthcare, Peloton Interactive, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Wellness Market Strategic Shifts
Biometric sensor fusion is compressing form factors while expanding clinical-grade measurement capabilities, reshaping competitive positioning across consumer wellness and regulated medical device boundaries.
Photoplethysmography is converging with accelerometry and galvanic skin response in multi-modal sensor arrays. Samsung's FDA-cleared sleep apnea detection Galaxy Watch implementations demonstrate clinical validation pathways for consumer hardware. This convergence is enabling single-device replacement of discrete medical and fitness monitors, compressing addressable market fragmentation.
The EU AI Act's biometric data processing requirements recalibrate compliance architectures for algorithmic wellness coaching. Risk classification tiers force transparency documentation for inference engines processing heart rate variability and stress indicators. Wearable OEMs serving European enterprise wellness programs face accelerated restructuring of data governance frameworks to maintain market access.
Employer-sponsored wellness procurement is consolidating around outcome-validated platform contracts. Fortune 500 benefits administrators now require clinical evidence packages before connected health device deployment. This behavioral shift concentrates purchasing power among vertically integrated platform providers with captive validation resources, most visible in United States self-insured employer segments where medical cost reduction mandates drive vendor selection criteria.
Smart Wellness Market Segmentation
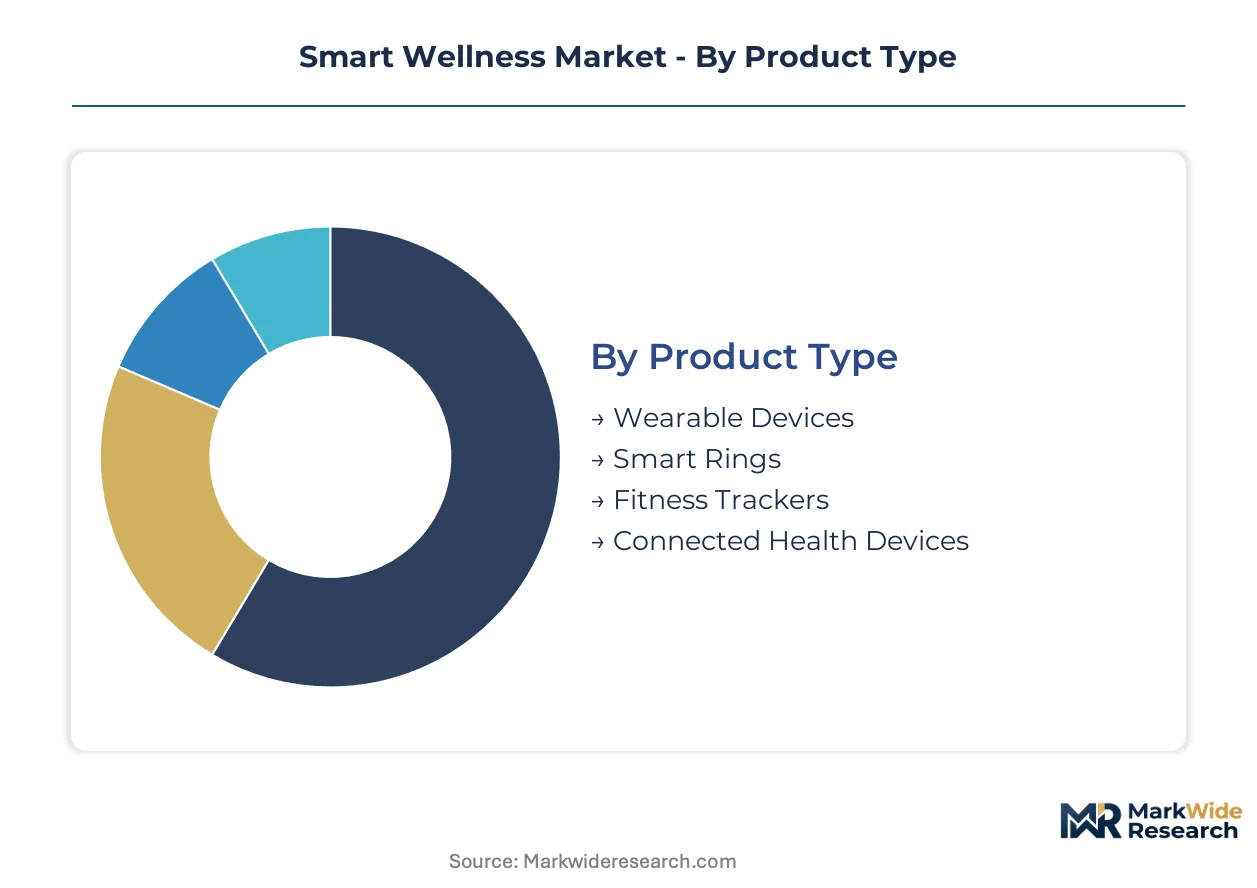
Smart wellness market segmentation reveals stark divergence between standalone consumer hardware and embedded clinical systems. Each dimension carries distinct margin profiles, regulatory exposure, and integration complexity that reshape vendor strategic positioning.
Product Type:
Standalone devices dominate consumer channels while embedded biometric modules penetrate clinical and enterprise systems through OEM partnerships.
- Wearable Devices:Wrist-worn form factors integrate PPG, accelerometry, and galvanic skin response in multi-sensor arrays. Demand concentrates in United States employer-sponsored preventive health programs where FDA 510(k) clearances for irregular rhythm notification unlock reimbursable deployment.
- Smart Rings:Minimal form factor captures discrete physiological monitoring through optical heart rate and SpO2 sensing. Privacy-conscious users across Germany and France drive fastest attach rates as EU AI Act transparency mandates favor low-visibility biometric capture without persistent cloud dependency.
- Fitness Trackers:Entry-level hardware with compressed margins serves price-sensitive consumers through basic step counting and calorie estimation.
- Connected Health Devices:Clinical-adjacent hardware including blood pressure monitors and pulse oximeters bridges consumer wellness and regulated medical device boundaries.
Wearable devices lead volumes today; smart rings are gaining share fastest.
Technology:
Cost tier stratification separates premium edge-inference stacks from commodity connectivity protocols in hardware bill-of-materials.
- IoT:Device-to-cloud telemetry architectures enable longitudinal health data aggregation for employer wellness analytics platforms.
- AI:On-device machine learning inference for real-time coaching commands premium positioning in clinical-adjacent segments. United States-based platform providers absorb escalating FDA validation costs to maintain reimbursable use case access.
- Bluetooth:Ubiquitous short-range wireless protocol pairs wearables with smartphones for data synchronization and firmware updates.
- NFC:Contactless authentication enables gym access and payment integration in hybrid wellness-commerce applications.
Bluetooth leads volumes today; AI is expanding most quickly.
Application:
Customer type determines whether applications monetize through one-time hardware sale or recurring subscription revenue.
- Fitness Monitoring:Mature segment with saturated consumer penetration and compressed hardware margins. Basic activity classification through accelerometry faces commoditization pressure from smartphone-native alternatives.
- Health Management:Chronic condition tracking including glucose monitoring and medication adherence attracts healthcare provider procurement in United States accountable care organizations.
- Sleep Tracking:Multi-modal sensing combining accelerometry with optical heart rate variability for sleep stage estimation. Samsung's FDA-cleared sleep apnea detection implementations demonstrate clinical validation pathways expanding reimbursable deployment.
- Wellness Coaching:Subscription-based behavioral intervention platforms capture disproportionate lifetime value through personalized nudge algorithms and human coach escalation.
Fitness monitoring leads volumes today; wellness coaching is climbing the fastest.
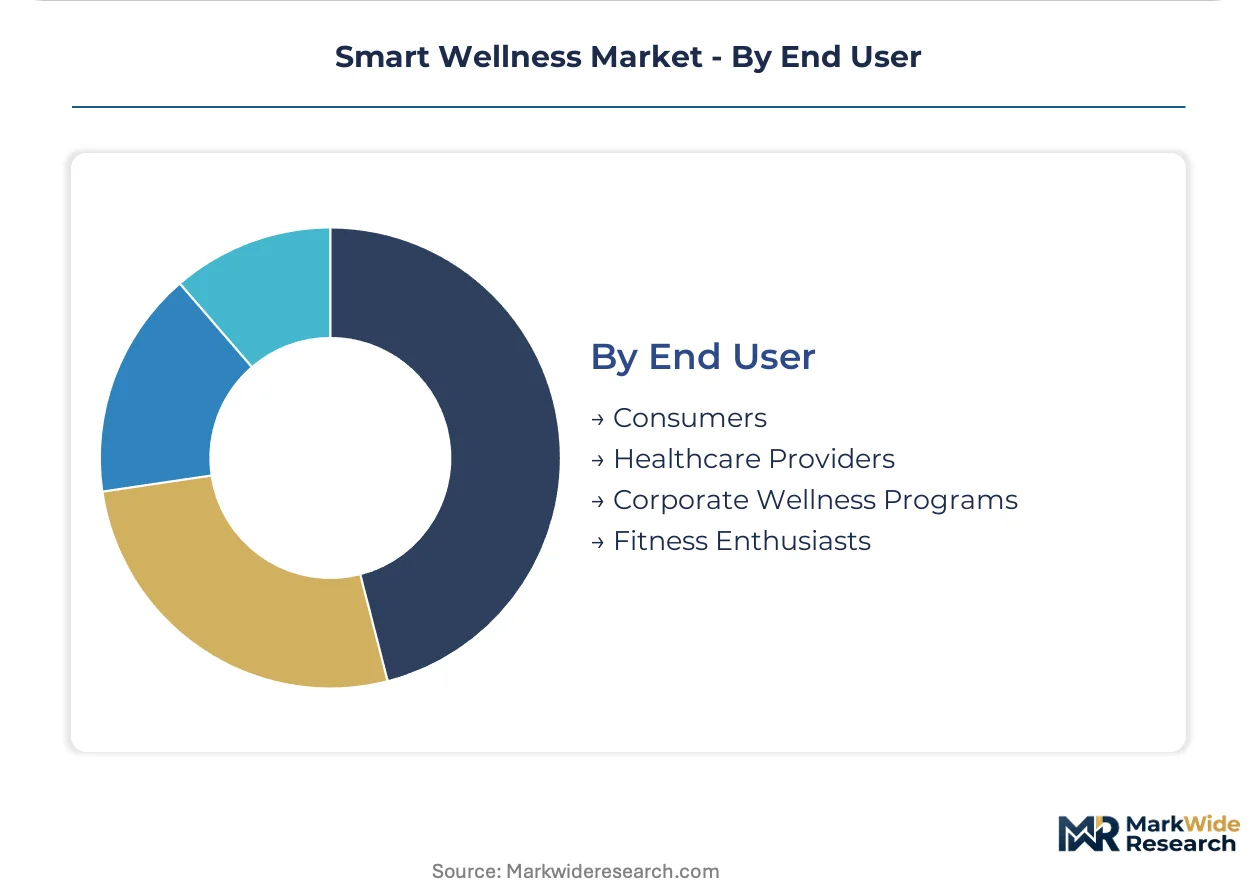
End User:
Volume concentration sits with consumer direct-to-channel while margin expansion concentrates in enterprise and clinical procurement.
- Consumers:Mass-market retail channel drives hardware volume through brand recognition and ecosystem lock-in effects.
- Healthcare Providers:Hospital systems and physician networks demand clinical evidence packages before connected health device deployment, concentrating purchasing power among vertically integrated platform providers with captive validation resources.
- Corporate Wellness Programs:Fortune 500 benefits administrators in United States self-insured employer segments require outcome-validated platform contracts with medical cost reduction documentation.
- Fitness Enthusiasts:Performance-oriented segment prioritizes granular physiological metrics for training optimization and recovery management.
Consumers lead volumes today; corporate wellness programs are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumer wellness hardware originated in United States technology corridors during the 2010s fitness tracker boom, then diffused through East Asian manufacturing clusters and European regulatory laboratories. Distribution now tracks employer-sponsored health program procurement and clinical validation infrastructure density.
United States
Fortune 500 self-insured employers drive connected health platform procurement through medical cost reduction mandates. FDA 510(k) clearances for irregular rhythm notification and sleep apnea detection expand reimbursable deployment pathways. Silicon Valley and Greater Boston concentrate venture-backed wellness coaching application developers with captive clinical validation resources.
China
Domestic wearable OEMs capture mass-market volume through price-competitive fitness trackers and basic health monitors. NMPA software-as-a-medical-device frameworks accelerate regulatory approval timelines for algorithmic wellness applications. Shenzhen manufacturing clusters supply photoplethysmography and accelerometer modules to global device assemblers.
Germany
Industrial insurance funds (Betriebskrankenkassen) subsidize preventive health technology procurement for mid-sized employer programs. EU AI Act algorithmic transparency mandates impose compliance restructuring costs on biometric inference engine deployments. Munich and Berlin host precision health startups specializing in privacy-preserving edge computation for enterprise wellness buyers.
Japan
Aging demographic density drives demand for chronic condition monitoring and medication adherence platforms. PMDA harmonization with South Korean MFDS frameworks reduces dual-market registration friction for connected health device exporters. Tokyo-Osaka corridor concentrates consumer electronics conglomerates with captive sensor fabrication and clinical trial infrastructure.
South Korea
Chaebol-affiliated electronics manufacturers leverage vertical component integration for premium smartwatch positioning. MFDS software-as-a-medical-device guidelines enable faster clinical validation pathways than FDA counterparts. Seoul Capital Area hosts biometrics research institutes partnering with wearable OEMs on photoplethysmography algorithm development.
Smart Wellness Market Competitive Environment
The competitive structure tilts toward vertically integrated technology conglomerates with captive health platform ecosystems. Three distinct tiers operate: premium ecosystem providers with clinical validation resources, specialized wearable OEMs focused on form factor innovation, and commodity hardware assemblers serving price-sensitive consumer segments. Dominant competitive moves include strategic partnerships with employer wellness program administrators and backward integration into sensor component supply.
Within the premium ecosystem tier, Apple Inc. and Samsung Electronics Co., Ltd. occupy positions defined by vertical control over hardware-software-health data architectures. Garmin Ltd. exemplifies specialization strategy, anchoring aviation and marine wellness niches where regulatory tailwinds from FAA and maritime safety frameworks create defensible market positions. These three entities represent contrasting archetypes: full-stack consumer health platforms, diversified electronics conglomerates with medical device adjacencies, and segment-focused physiological monitoring specialists.
| Leading Market Players |
|---|
| Apple Inc. |
| Google LLC |
| Garmin Ltd. |
| Samsung Electronics Co., Ltd. |
| Oura Health Oy |
| WHOOP, Inc. |
| Philips Healthcare |
| Omron Healthcare |
| Peloton Interactive, Inc. |
| Others |
Value Chain & Pricing Dynamics
Photoplethysmography sensor module pricing cascades through East Asian specialty foundries into three distinct hardware tiers, with FDA 510(k) certification premiums compressing margins for mid-tier wearable OEMs lacking captive clinical validation resources.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clinically validated devices with FDA 510(k) clearances from consumer-grade wellness hardware and basic fitness trackers. Price differentiation rests on certification grade and volume scale, with Fortune 500 employer wellness programs absorbing premium positioning for outcome-validated platforms. Cost compression in the mid-tier is intensifying because EU AI Act compliance costs disproportionately burden smaller sensor manufacturers. Fitness enthusiasts demonstrate highest price sensitivity, while corporate wellness buyers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for photoplethysmography optical sensors and accelerometer MEMS fabrication. Raw material dependencies include indium phosphide wafers, specialty optical coatings, and lithium-polymer battery cells. Supply chain risk centers on tariff exposure from East Asian component routing through Shenzhen assembly clusters. Distribution runs through enterprise wellness program administrators and direct-to-consumer retail channels, with employer-sponsored procurement consolidating purchasing power among vertically integrated platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Wellness Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany and France create cost disadvantages against United States-based clinical validation infrastructure.
For Market Incumbents: Lock in employer wellness program contracts through outcome-based pricing tied to medical cost reduction documentation. Absorb escalating FDA 510(k) validation costs to maintain reimbursable use case access against emerging sensor-fusion entrants. Deepen backward integration into photoplethysmography module supply to secure component availability during East Asian foundry allocation cycles. For New Entrants and Emerging Players: Edge AI inference optimization for ultra-low-power wearables offers a technology-first wedge into the aviation and marine monitoring niche where Garmin's dominance has left hypoxia detection systems underpenetrated. Target smart ring form factors among privacy-conscious German and French enterprise buyers seeking EU AI Act-compliant biometric capture. Pursue direct partnerships with industrial insurance funds (Betriebskrankenkassen) for subsidized preventive health technology deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with wellness coaching application developers possessing proprietary behavioral intervention algorithms and recurring subscription revenue models. Long-term viability hinges on clinical evidence package depth and employer wellness program administrator relationships. Watch FDA 510(k) clearance velocity for irregular rhythm notification and sleep apnea detection as inflection indicators for reimbursable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | FDA 510(k) clearances for sleep apnea detection unlock Fortune 500 employer procurement pathways. |
| Edge AI Firmware Development | On-device photoplethysmography inference reduces cloud dependency for EU AI Act compliance. |
| Employer Wellness Partnership | Self-insured benefits administrators concentrate purchasing power among outcome-validated platform providers. |
| Smart Ring Form Factor Expansion | Minimal biometric capture devices record fastest attach rates among privacy-conscious enterprise buyers. |
| Sensor Supply Backward Integration | Captive photoplethysmography module production mitigates single-source dependency from East Asian foundries. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with wearable OEM product managers, employer wellness program benefits administrators, FDA regulatory consultants, and hospital biomedical engineers with secondary validation against SEC filings, FDA 510(k) clearance databases, EU AI Act implementation guidance, and GPO contract records. Bottom-up sensor shipment modeling and top-down employer wellness spending estimates triangulated market sizing.
Segment-weighting across product type, technology tier, application use case, and end-user channel shaped the analytical framework over the projection horizon. CAGRs derived from longitudinal employer procurement data and biometric sensor attach rate trajectories. Modeled inputs included FDA 510(k) clearance timelines, EU AI Act compliance cost absorption rates, and photoplethysmography algorithm accuracy benchmarks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory harmonization between PMDA and MFDS frameworks, East Asian foundry capacity allocation, and employer wellness program reimbursement policy shifts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Yoga Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Weight Management Market