
 Australia and New Zealand Corporate Wellness Market | 2026-2036
Australia and New Zealand Corporate Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Australia and New Zealand Corporate Wellness Market Intelligence
Subscription-based mental health platforms is repositioning corporate wellness from episodic intervention to continuous employee engagement. Corporate Wellness Australia leverages its national clinician network to sustain geographic coverage across both countries. Complete Corporate Wellness anchors its competitive position through specialized mining-sector programs. Logic Health differentiates via technology-led biometric integration that extends traditional health assessment value.
Australia and New Zealand Corporate Wellness encompasses employer-funded programs designed to improve workforce physical health, psychological resilience, and productivity through structured interventions including health risk assessments, fitness programming, nutritional guidance, and counseling services. These programs typically deploy through digital platforms, onsite facilities, or hybrid models with measurable outcome tracking against absenteeism and presenteeism metrics. Mental Health Support programs command expanding budget allocation as psychological safety regulations tighten across both jurisdictions. Large Corporations represent the most mature buyer segment with established procurement frameworks, while Small Enterprises constitute the fastest-growing adoption cohort as cloud-based delivery reduces minimum program scale.
Safe Work Australia codes of practice and New Zealand's WorkSafe guidelines directly shape program design standards and vendor qualification requirements across the region. TGA oversight of wearable medical devices and MedSafe New Zealand regulation of digital therapeutic tools constrain technology-enabled service expansion. Australia's ISO 45003 psychological health management standard and New Zealand's alignment with AS/NZS 4801 safety frameworks create compliance-driven procurement criteria. Stakeholders must monitor evolving regulatory convergence between occupational health mandates and privacy protections as employee biometric data collection intensifies.
Market Dynamics
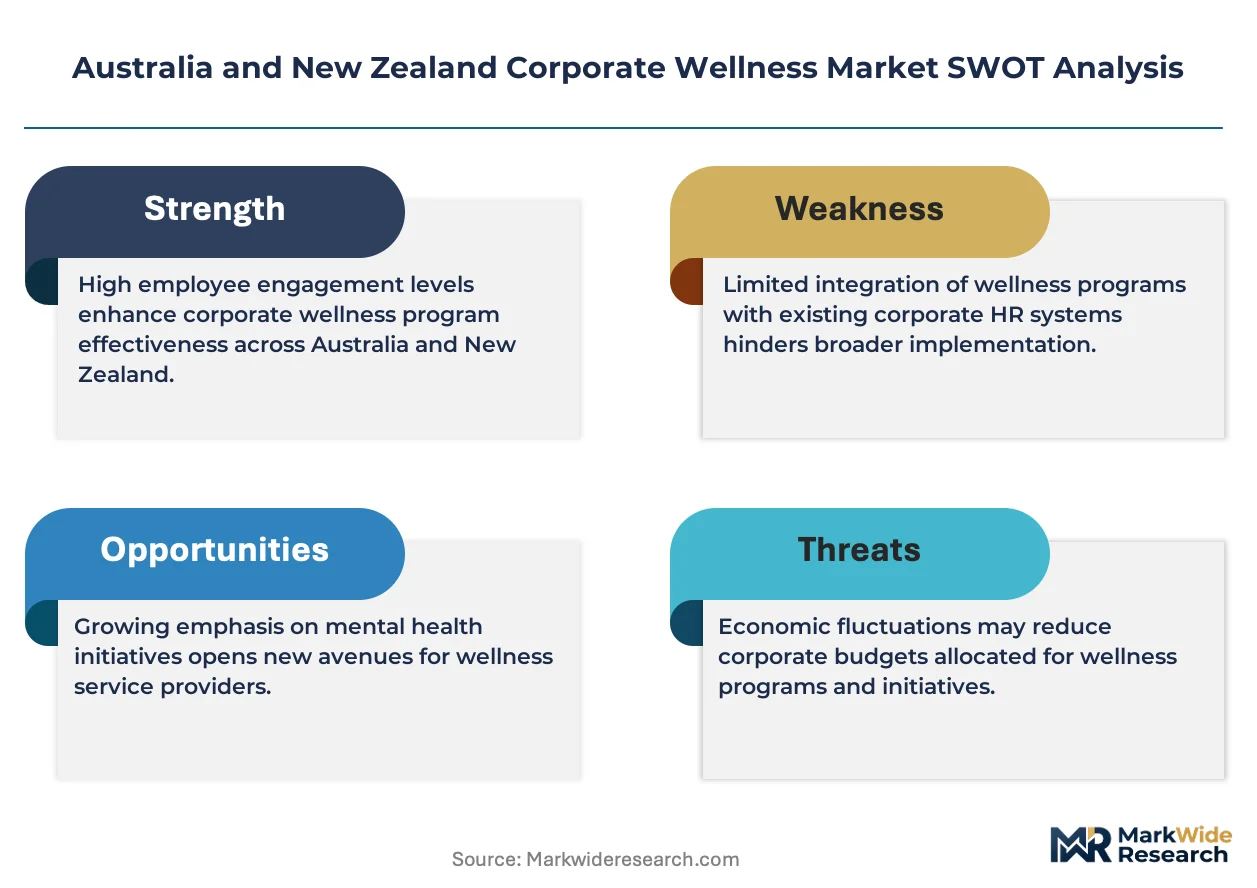
Psychological safety mandates across Australian and New Zealand jurisdictions are forcing employers to convert discretionary wellness spending into compliance-driven procurement with measurable biometric outcomes.
Growth Catalysts
- Fair Work Act psychological safety amendments:Australian employers face enforceable duties to eliminate psychosocial hazards, triggering mandatory wellness program adoption in mining and financial services headquarters.
- Cloud-based delivery platforms:Subscription mental health tools reduce minimum viable program scale, accelerating small enterprise penetration beyond traditional onsite service territories.
- Melbourne and Sydney headquarters density:Corporate concentration in these cities sustains premium onsite deployment economics for vendor networks.
Market Restraints
- TGA wearable medical device oversight:Therapeutic Goods Administration classification delays for biometric sensors constrain technology-enabled service rollout timelines.
- Specialized clinician supply concentration:Accredited psychological health practitioners cluster in metropolitan Australia, limiting rural New Zealand program quality parity.
- Data sovereignty requirements:Cross-border employee health information flows face MedSafe New Zealand and Australian Privacy Principle friction, complicating trans-Tasman corporate deployments.
Strategic Opportunities
- Queensland and Western Australia mining corridors:Fly-in-fly-out workforce isolation creates unmet demand for remote mental health monitoring beyond current vendor coverage.
- ISO 45003 certification services:Psychological health management system auditing represents adjacent revenue as employers seek compliance demonstration.
- Biometric-telehealth convergence:Integration of continuous glucose monitors with virtual counseling sessions extends program value beyond episodic interventions.
Industry Challenges
- Accredited psychological health practitioner scarcity:Workforce credentialing pipelines lag demand acceleration from regulatory mandate expansion.
- Legacy HR system integration complexity:Absenteeism tracking APIs lack standardization, forcing custom middleware development for outcome measurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia and New Zealand Corporate Wellness Market |
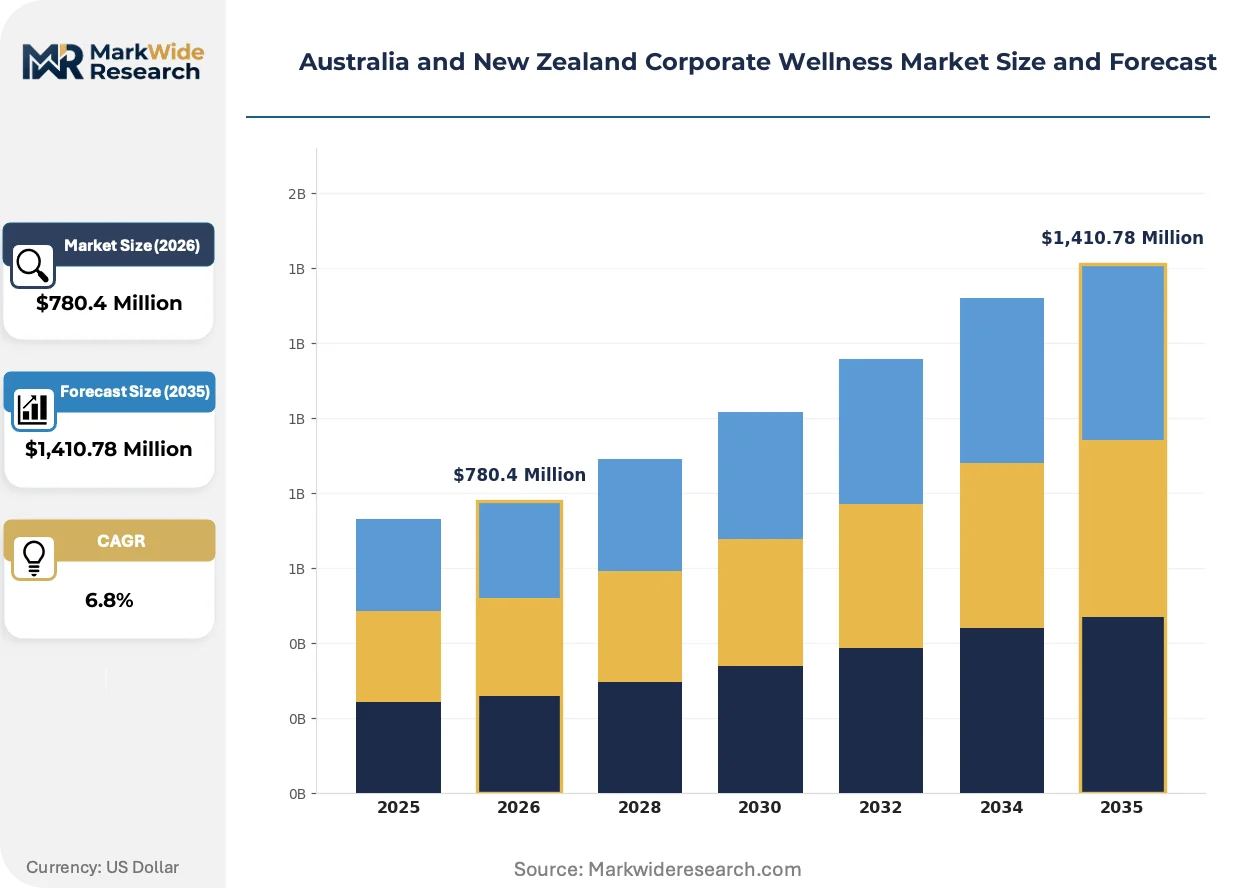
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,410.78 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Program Type: Health Assessments, Fitness Programs, Nutritional Counseling, Mental Health Support Delivery Mode: In-Person, Online Platforms, Hybrid, Workshops Employee Size: Small Enterprises, Medium Enterprises, Large Corporations, Multinationals Service Provider: Corporate Trainers, Wellness Coaches, Healthcare Providers, Fitness Institutions |
| Companies Covered | Corporate Wellness Australia, Complete Corporate Wellness, Corporate Work Health Australia, Healthbox NZ, Logic Health, Holistic Services Group, Workplace Wellness Australia, EvolvME, Health at Work, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia and New Zealand Corporate Wellness Market Strategic Shifts & Innovations
Digital therapeutic platforms are compressing service delivery timelines while regulatory convergence between occupational health and privacy frameworks is reshaping vendor qualification requirements.
Continuous biometric monitoring through wearable devices is electrifying preventive health engagement models. Mining sector employers in Western Australia deploy glucose and stress hormone sensors for shift workers, converting physiological data into real-time intervention triggers. This capability is compressing the gap between risk identification and clinical response from weeks to hours.
Safe Work Australia's codes of practice now explicitly incorporate psychological hazard identification alongside physical safety protocols. Industrial consequence mandates documented risk assessment for high-stress roles in financial services and extractive industries. Large corporations in Sydney respond by embedding certified psychological health officers within existing occupational health teams.
Subscription pricing for mental health platforms is displacing per-session fee structures among small enterprises. Annual licensing models reduce procurement friction for businesses below 200 employees, replacing traditional broker-mediated program selection. This shift concentrates most visibly in Auckland's professional services sector, where cloud-native vendors bypass incumbent onsite providers.
Australia and New Zealand Corporate Wellness Market Segmentation
Corporate wellness procurement in Australia and New Zealand fragments across program architecture, deployment technology, organizational scale, and vendor credentialing. Each segmentation axis reveals distinct margin structures and compliance obligations that reshape competitive positioning.
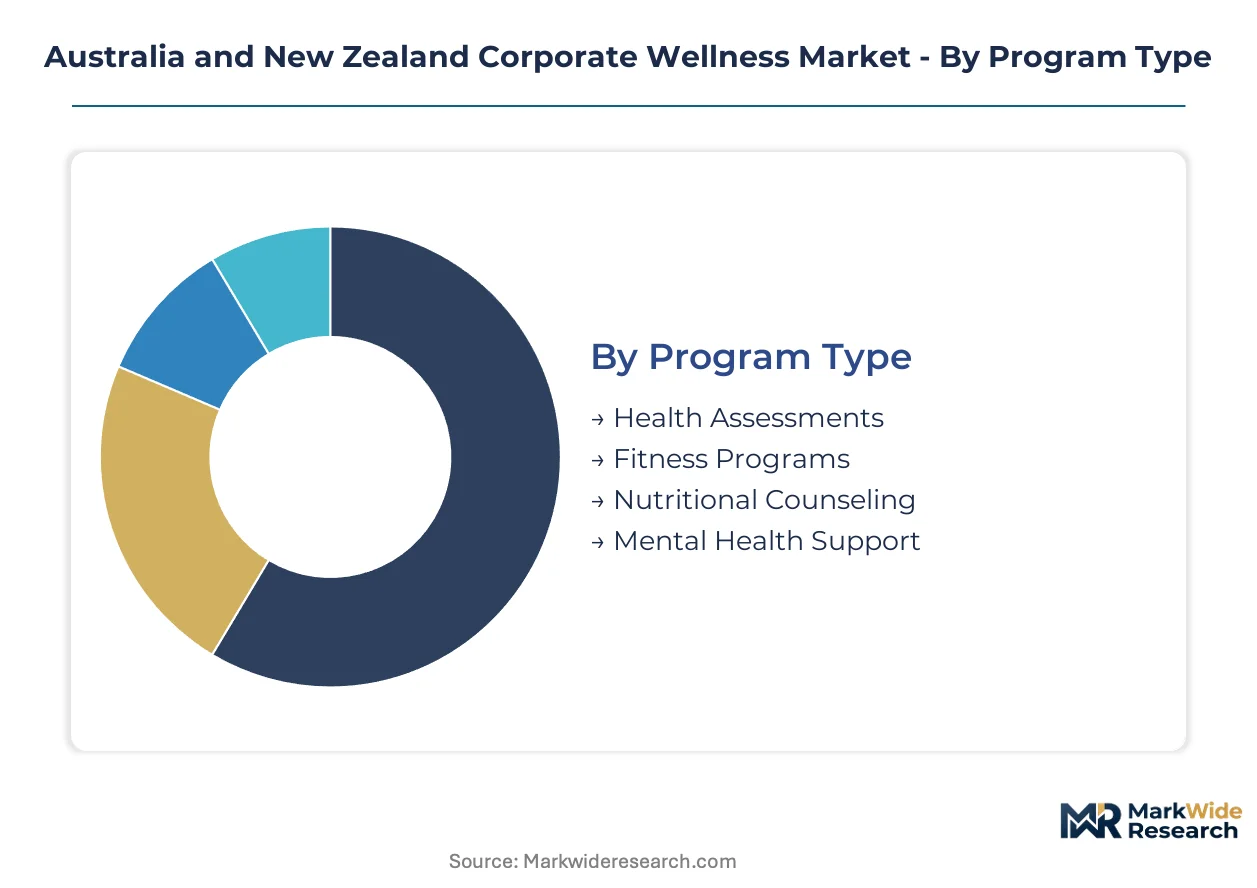
Program Type:
Standardized screening protocols anchor the low-complexity end while bespoke psychological interventions command premium pricing tiers.
- Mental Health Support:Subscription-based counseling platforms and crisis intervention hotlines address psychosocial hazard mandates under Fair Work Act amendments. Sydney and Melbourne financial services headquarters drive concentrated demand as regulatory enforcement tightens.
- Health Assessments:Biometric screening protocols encompassing cardiovascular markers, metabolic panels, and ergonomic evaluations establish baseline workforce risk profiles. Mining sector employers in Western Australia deploy these for fly-in-fly-out medical clearance.
- Fitness Programs:On-site gym facilities and movement coaching target physical resilience metrics.
- Nutritional Counseling:Dietary intervention programs address metabolic syndrome prevalence in sedentary occupational cohorts.
Most installed capacity flows through Health Assessments. Expansion is steepest in Mental Health Support.
Delivery Mode:
Capital intensity separates high-touch facility investments from scalable digital infrastructure plays.
- Online Platforms:Cloud-native mental health tools and asynchronous coaching portals eliminate geographic constraints. Auckland professional services firms adopt these fastest as subscription pricing displaces per-session brokerage.
- Hybrid:Blended models combining biometric wearables with virtual clinician check-ins optimize cost per outcome. Queensland mining corridors deploy this architecture for isolated workforce coverage.
- In-Person:Dedicated on-site wellness centers and face-to-face counseling sustain premium positioning.
- Workshops:Time-bounded group interventions for stress management and team resilience.
Hybrid deployments capture the largest share of new contract value. Online Platforms are climbing the fastest as vendor economics improve.
Employee Size:
Procurement sophistication scales with internal HR systems integration capacity and compliance liability exposure.
- Large Corporations:Established occupational health frameworks with dedicated wellness budgets and ISO 45003 certification pathways. Mining and financial services headquarters in Sydney and Melbourne anchor this segment.
- Small Enterprises:Cloud-based delivery reduces minimum viable program scale, accelerating adoption among businesses below 200 employees previously excluded from broker-mediated procurement.
- Medium Enterprises:Transitioning from ad-hoc wellness spending to structured program governance.
- Multinationals:Trans-Tasman policy harmonization challenges complicate unified wellness strategy deployment.
Large Corporations retain the deepest program penetration. Small Enterprises are gaining share fastest as platform economics democratize access.
Service Provider:
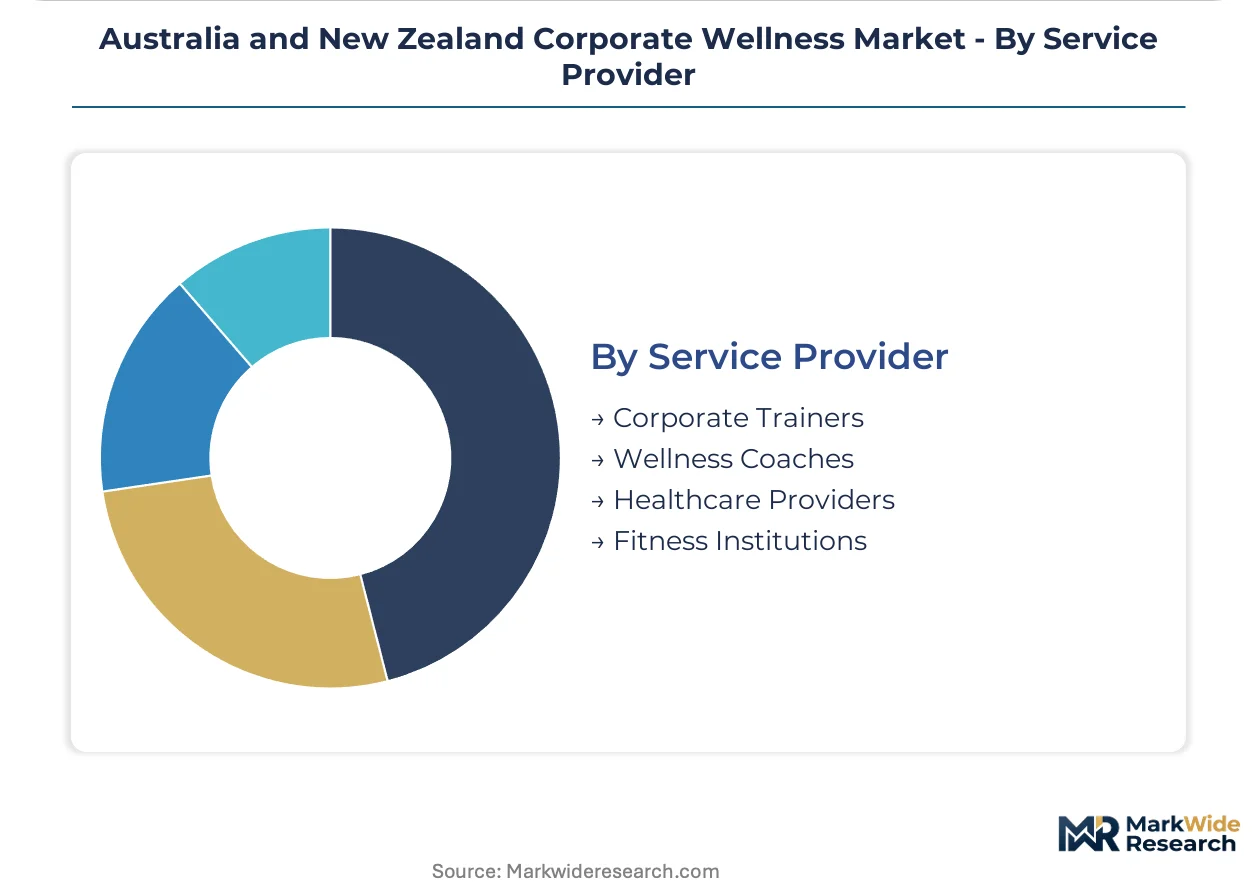
Credentialing requirements and liability coverage separate regulated clinical entities from coaching-based offerings.
- Healthcare Providers:Registered psychologists, general practitioners, and occupational therapists delivering clinically supervised interventions. TGA oversight of therapeutic claims constrains service scope expansion.
- Wellness Coaches:Behavior change specialists operating below clinical licensure thresholds with lower per-engagement cost structures.
- Corporate Trainers:Physical fitness and ergonomic instruction without medical diagnostic authority.
- Fitness Institutions:Commercial gym operators extending B2B corporate membership schemes.
Healthcare Providers dominate contract value in regulated industries. Wellness Coaches are expanding most quickly in small enterprise segments with lighter compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia commands the dominant share of corporate wellness expenditure across the Tasman region, while New Zealand's smaller market punches above its weight in digital platform adoption per capita.
New South Wales
Sydney's financial services headquarters cluster drives premium onsite wellness program deployment. Safe Work Australia codes of practice enforce psychological hazard identification protocols across banking and insurance employers. The Sydney CBD and North Sydney corridor concentrate vendor networks serving large corporations with ISO 45003 certification requirements.
Victoria
Melbourne's professional services density sustains hybrid delivery models combining biometric screening with virtual counseling. Australia's Fair Work Act psychosocial hazard amendments compel employer investment in structured mental health frameworks. The Melbourne metropolitan area anchors healthcare provider networks accredited for occupational psychology services.
Queensland
Fly-in-fly-out mining operations in the Bowen Basin and Surat Basin generate specialized demand for remote mental health monitoring. The state's Work Health and Safety Act alignment with national psychological safety standards mandates documented risk assessment for isolated workforces. Brisbane serves as the logistics hub for wellness vendors deploying to remote resource extraction sites.
Western Australia
Pilbara mining corridors and Perth headquarters operations command the highest per-employee wellness spending in the region. The state's resources sector safety regulator enforces fitness-for-work medical clearance protocols that incorporate biometric health assessments. Perth's central business district hosts specialized vendors serving the extractive industries with fly-in-fly-out workforce programs.
New Zealand
Auckland's professional services sector leads cloud-native mental health platform adoption among small enterprises. New Zealand's Health and Safety at Work Act mental health provisions create compliance-driven procurement comparable to Australian standards. The Auckland metropolitan area concentrates Healthbox NZ and other digital-first vendors bypassing traditional onsite service models.
Australia and New Zealand Corporate Wellness Market Key Industry Players
Top-tier vendors anchor the healthcare provider segment, while wellness coaches and fitness institutions occupy the lower-margin tiers. The market structure reflects regulatory credentialing requirements that separate clinically supervised interventions from behavior change coaching. Three archetypes dominate: national clinician networks, mining-sector specialists, and technology-led biometric integrators. Competitive moves concentrate on geographic coverage expansion and ISO 45003 certification service adjacencies.
Within the national network archetype, Corporate Wellness Australia and Complete Corporate Wellness exemplify scale-driven positions spanning both countries. Logic Health occupies a technology-forward tier, representing the biometric-telehealth convergence pattern visible across the industry. These three entities sit within a vendor landscape where geographic origin and service modality—not product differentiation—determine competitive boundaries.
| Leading Market Players |
|---|
| Corporate Wellness Australia |
| Complete Corporate Wellness |
| Corporate Work Health Australia |
| Healthbox NZ |
| Logic Health |
| Holistic Services Group |
| Workplace Wellness Australia |
| EvolvME |
| Health at Work |
| Others |
Cost & Logistics Intelligence
Psychological health practitioner concentration in metropolitan Australia widens pricing spreads between premium clinical services and economy-tier coaching programs, as rural New Zealand employers absorb elevated travel premiums for accredited workforce coverage.
Pricing Analysis
Capacity additions in cloud-native mental health platforms are reshaping price floors for small enterprise segments. Subscription SaaS-tiered models now dominate below 200-employee accounts, compressing per-seat costs against traditional per-session brokerage. Price differentiation hinges on TGA registration status and ISO 45003 certification tier. Pricing pressure intensifies in standardized screening protocols as wellness coaches displace healthcare providers in lighter-compliance segments. Small enterprises exhibit highest price sensitivity; mining sector buyers in Western Australia show lowest sensitivity due to fly-in-fly-out workforce isolation premiums.
Supply Chain Analysis
Freight logistics for biometric wearables and remote monitoring hardware concentrate supply chain costs in trans-Tasman deployments. Component sourcing draws from China for wearable sensors, USA for cloud infrastructure, and domestic Australia for clinician network accreditation. Raw material dependencies span lithium-ion batteries, medical-grade polymers, and semiconductor chips. Single-source vulnerability concentrates in TGA-approved device manufacturers facing classification delays. Distribution runs through vendor-managed inventory at Perth and Brisbane logistics hubs serving remote mining corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where New Zealand's lighter regulatory credentialing requirements enable faster service rollout at lower compliance cost than Australia's TGA oversight regime.
For Market Incumbents: Anchor competitive position through ISO 45003 certification service adjacencies as compliance demonstration demand accelerates. Deepen clinician network density in Queensland mining corridors before emerging digital-first entrants capture fly-in-fly-out workforce contracts. Defend against technology-led biometric integrators by embedding continuous monitoring capabilities into existing occupational health frameworks. For New Entrants and Emerging Players: The premium-economy pricing gap in mental health support services opens white-space at mid-tier hybrid delivery. Target Auckland's professional services sector with subscription platforms bypassing incumbent onsite providers. Penetrate Western Australia's Pilbara region through telehealth-biometric convergence for isolated shift workers. Pursue channel partnerships with mining sector safety consultants as primary go-to-market angle. For Investors and Strategic Acquirers: Healthcare providers with national clinician networks are the most active acquirer in this space, consolidating fragmented wellness coach segments. Long-term viability favors vendors with regulatory credentialing moats spanning both Australian and New Zealand jurisdictions. Target acquisition archetype: cloud-native platforms with established small enterprise subscriber bases. Watch TGA wearable classification timelines as inflection signal for technology-enabled service expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 45003 Certification Service Launch | Positions vendors for Fair Work Act compliance demonstration requirements across Sydney financial services headquarters. |
| Biometric-Telehealth Platform Integration | Compresses clinical response timelines from weeks to hours for Western Australia mining shift workers. |
| Clinician Network Expansion | Addresses accredited psychological health practitioner scarcity constraining rural New Zealand program quality parity. |
| Cloud-Native Subscription Model Rollout | Reduces procurement friction for Auckland professional services firms below traditional minimum program scales. |
| Queensland Mining Corridor Coverage Buildout | Captures unmet demand for remote mental health monitoring beyond current vendor geographic reach. |
Research Approach
Bottom-up employer-size modeling reconciled against top-down vendor capacity tracking forms the analytical core of this study. Primary interviews with occupational health officers, HR procurement leads, wellness platform executives, and mining sector safety directors combined with secondary validation against Safe Work Australia codes of practice, TGA device registration databases, Fair Work Commission guidance materials, and New Zealand WorkSafe guidelines. Triangulation across bottom-up program deployment counts and top-down expenditure estimates from corporate wellness budget disclosures anchored volume and value outputs.
Input-output matrices mapped program type, delivery mode, employee size, and service provider segmentation against regulatory compliance tier and geographic deployment cost. CAGRs derived from regression analysis of historical adoption curves adjusted for Fair Work Act amendment enforcement timelines and cloud platform penetration rates. Industry-specific forecast inputs incorporated psychological safety mandate expansion velocity and biometric wearable TGA classification pipeline status across the projection horizon.
Caveats apply where TGA regulatory delays, clinician supply pipeline constraints, or cross-border data sovereignty friction could materially shift the outlook. Forecasts reflect modeling assumptions about regulatory enforcement intensity and technology adoption elasticity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Weight Control Products Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Yoga Market
Health and Wellness
Smart Wellness Market
Health and Wellness
GCC Weight Management Market