
 Yoga Market | 2026-2036
Yoga Market Size, Share, and Industry Trends Forecast 2026-2036
Yoga Market Analysis
Natural rubber is pivoting away from PVC and TPE in premium mat production, compressing unit economics for mid-tier suppliers while elevating sustainability premiums. Alo Yoga leverages direct-to-consumer digital infrastructure to control pricing across North American markets. Manduka anchors its position through certified closed-cell manufacturing and lifetime product guarantees. Lululemon Athletica extends brand equity from apparel into mat and accessory categories, competing on lifestyle integration rather than price.
Yoga encompasses physical postures, breath control, and meditation practices delivered through equipment typically manufactured from natural rubber, cork, or polymer composites with density ratings between three and six pounds per cubic foot, designed to provide cushioning, grip, and joint protection during floor-based movement sequences. Mats and apparel together capture the dominant share of product-type revenue, with blocks and straps serving as higher-margin add-on purchases tied to beginner onboarding. In-person classes retain the largest delivery-mode revenue pool, though online sessions represent the fastest-expanding channel as platforms reduce customer acquisition costs through subscription models.
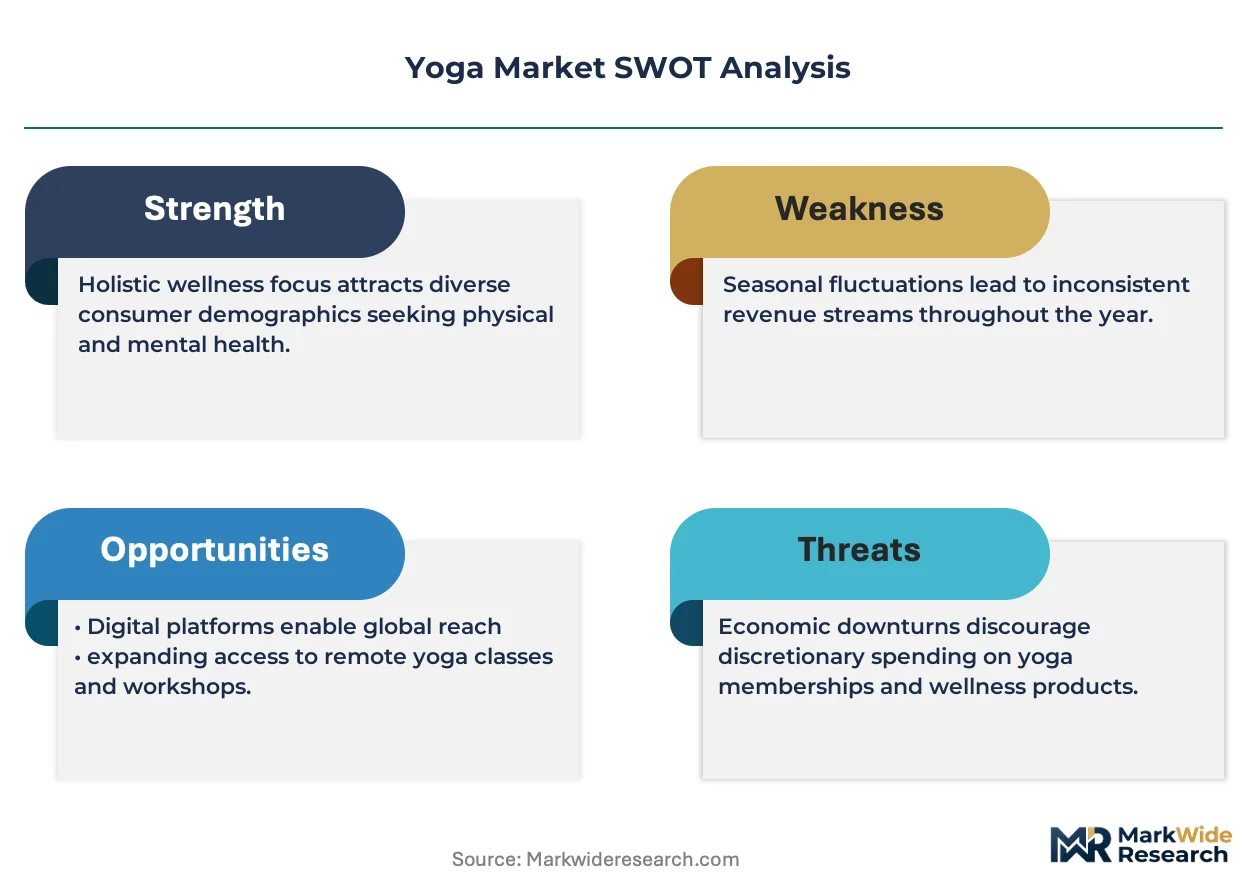
FDA oversight applies to wellness claims in wearable-integrated yoga technologies, while REACH and California Proposition 65 restrict phthalate and heavy-metal content in mat manufacturing, effectively filtering low-cost Asian suppliers from premium European and West Coast distribution. The EU Green Deal's extended producer responsibility frameworks will soon require take-back programs for synthetic equipment, reshaping sourcing decisions for brands serving European studios. Stakeholders must monitor how chemical compliance costs redistribute margin pools between integrated manufacturers and third-party assemblers.
Market Dynamics
REACH chemical safety standards and California's Proposition 65 are actively filtering low-cost Asian suppliers from premium European and West Coast distribution channels, forcing material substitutions toward PVC-free natural rubber formulations and compressing margins for mid-tier manufacturers unable to absorb compliance costs.
Growth Catalysts
- EU Green Deal extended producer responsibility:Mandatory take-back programs for synthetic equipment create circular economy infrastructure that premium brands leverage for differentiation. Studios in Germany and France now prioritize suppliers with certified closed-loop systems.
- Corporate wellness procurement:North American and European employers are consolidating mat and apparel orders through enterprise contracts, reducing customer acquisition costs for vendors with B2B certification capabilities.
- Natural rubber cultivation clusters:Kerala in India and Sri Lanka's mat-grade rubber plantations provide certified organic feedstock that commands sustainability premiums in United States and German direct-to-consumer channels.
Market Restraints
- Natural rubber price volatility:Climate disruption across Southeast Asian plantations creates input cost instability that synthetic-PVC competitors exploit during price-sensitive procurement cycles.
- Supply concentration in China:Polymer composite processing and TPE formulation capacity clusters in Guangdong province expose brands to single-point logistics disruptions and tariff exposure.
- Technical limitation in biodegradable polymers:Current plant-based alternatives lack the density durability of six-pound-per-cubic-foot closed-cell constructions, limiting performance-mat applications.
Strategic Opportunities
- Wearable-integrated yoga technologies:FDA-regulated biometric mat surfaces that track heart rate variability and pressure distribution open subscription revenue models for equipment-as-service platforms.
- India studio network expansion:Tier-two cities including Pune and Ahmedabad show underpenetrated demand for certified instructor training programs tied to manduka-style lifetime guarantee equipment.
- Subscription platform channel innovation:Digital-native studios bypass traditional retail markup by direct-shipping co-branded blocks and straps to monthly members, capturing higher-margin add-on revenue.
Industry Challenges
- REACH compliance timeline compression:ECHA's accelerated substance evaluation schedule forces reformulation cycles faster than traditional eighteen-month product development timelines allow.
- Closed-cell manufacturing capex intensity:Certified density-controlled production lines require seven-figure equipment investments that exclude emerging suppliers from premium tier qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yoga Market |
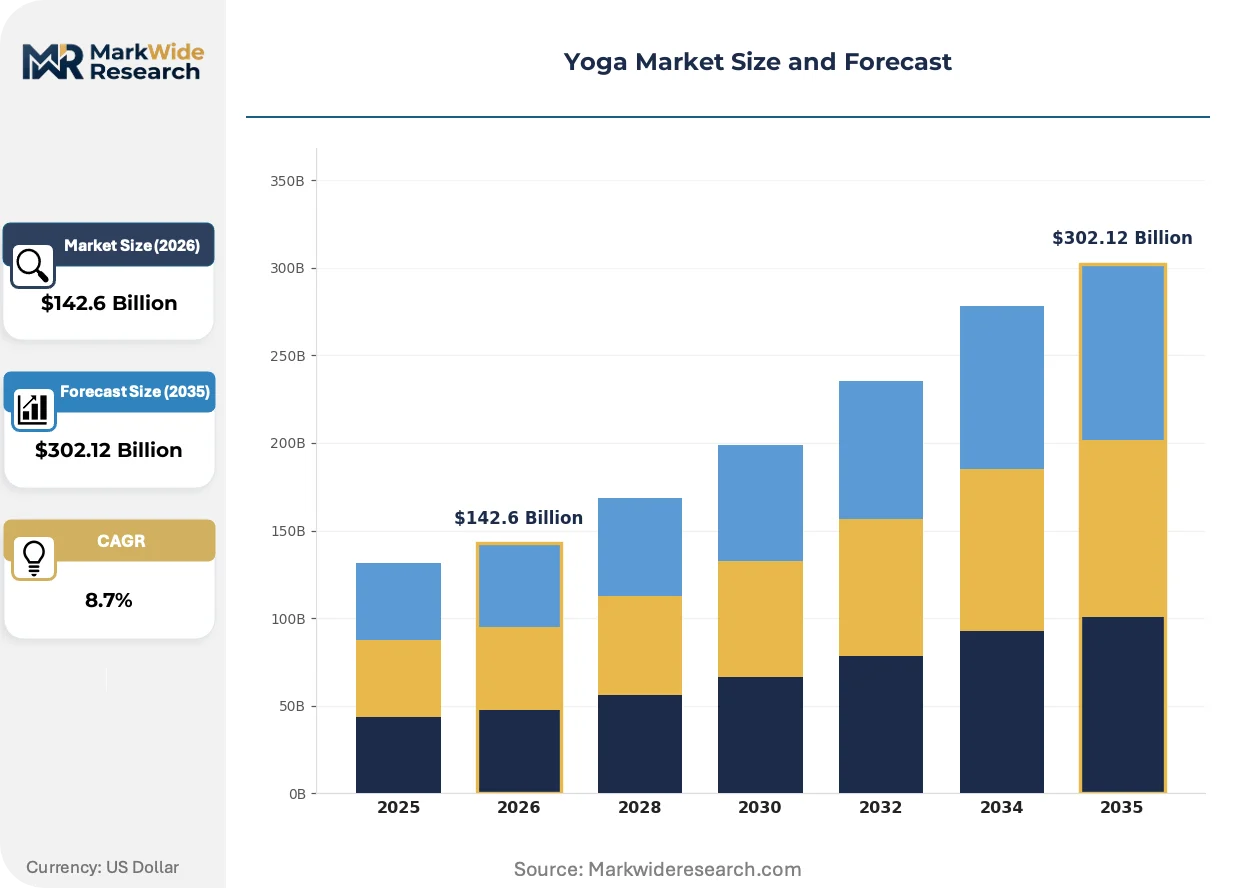
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $302.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mats, Blocks, Straps, Apparel Delivery Mode: In-Person Classes, Online Sessions, Workshops, Retreats Practice Style: Hatha, Vinyasa, Ashtanga, Kundalini Target Audience: Beginners, Intermediates, Professionals, Seniors |
| Companies Covered | YogaWorks, Alo Yoga, CorePower Yoga, Honor Yoga, Daily Yoga, Lululemon Athletica, Manduka, Glo Digital, Inc., Gaiam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yoga Market Emerging Trajectories
Material science convergence with digital health infrastructure is redefining how yoga equipment functions beyond passive cushioning, creating new value capture mechanisms through data integration and certified sustainable sourcing.
Sensor-embedded mat surfaces are automating real-time posture correction feedback through pressure-mapping algorithms. Boutique studios in New York and London are piloting these systems for premium membership tiers. The technology is automating instructor scalability by reducing hands-on adjustment needs during high-volume classes.
ECHA's 2023 update to REACH candidate list restrictions on medium-chain chlorinated paraffins has forced immediate reformulation of TPE grip layers. German distributors now require third-party lab certification for all imported mat inventory. Premium suppliers with in-house polymer laboratories are capturing shelf space previously held by price-competitive Asian exporters.
Direct-to-consumer subscription bundling is displacing traditional sporting goods retail as the dominant equipment acquisition channel. Alo Yoga's digital infrastructure demonstrates how lifestyle content integration drives recurring mat replacement cycles. This pattern concentrates in United States coastal markets where studio density supports same-day delivery logistics.
Yoga Market Segmentation
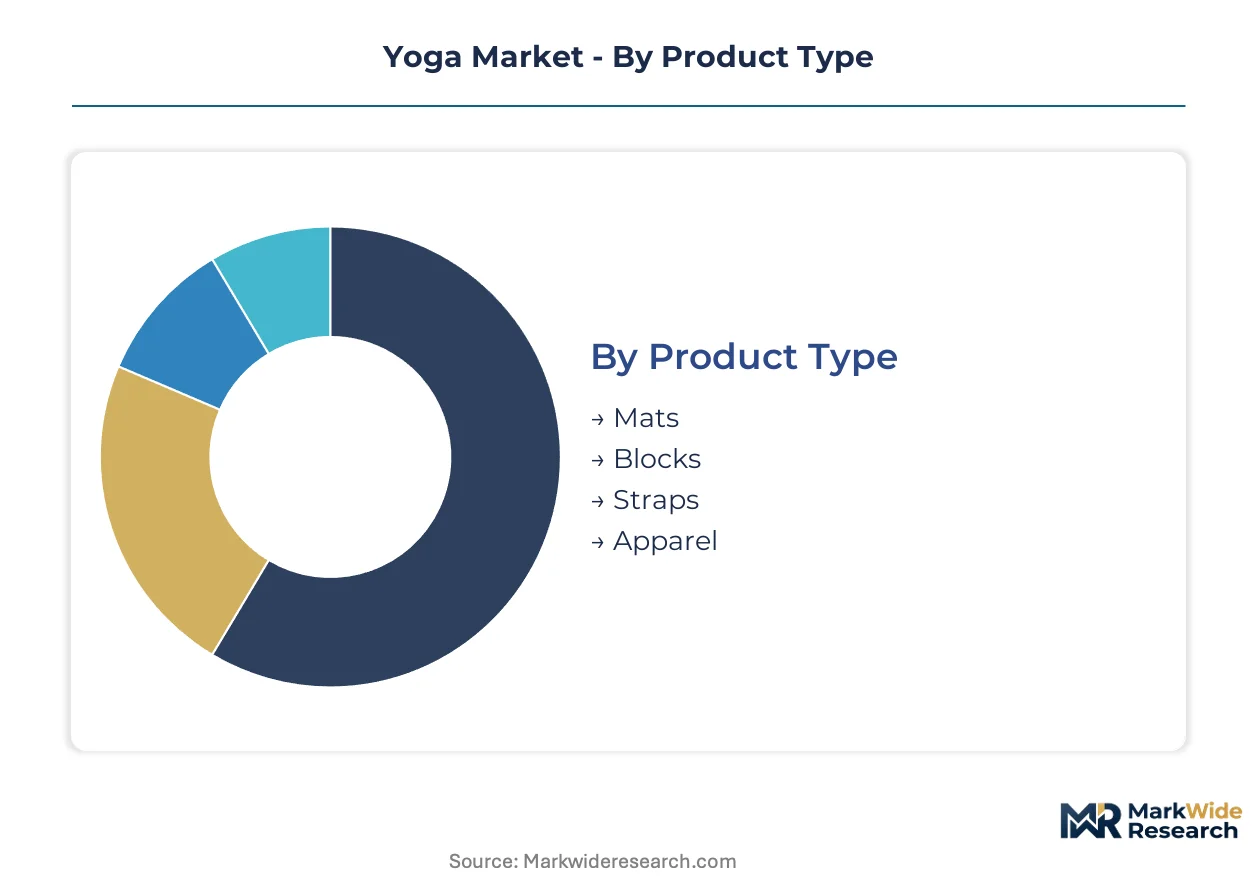
Product, delivery, style, and audience segments each trigger distinct regulatory and sourcing requirements. REACH compliance filters mat manufacturing by material grade, while FDA oversight applies to wearable-integrated delivery modes. Understanding these certification boundaries shapes procurement strategy across tiered price points.
Product Type:
REACH and California Proposition 65 impose divergent testing burdens across material compositions, with natural rubber formulations facing stricter heavy-metal thresholds than polymer alternatives.
- Mats:Closed-cell constructions with density ratings between three and six pounds per cubic foot dominate studio procurement in the United States and Germany. ECHA's 2023 medium-chain chlorinated paraffin restrictions have forced immediate TPE reformulation, compressing margins for suppliers without in-house polymer laboratories.
- Apparel:Moisture-wicking synthetic blends and organic cotton lines compete on lifestyle integration rather than price alone. Corporate wellness programs in North America now consolidate apparel orders through enterprise contracts, reducing customer acquisition costs for vendors with B2B certification capabilities.
- Blocks:Cork and foam constructions serve as higher-margin add-on purchases tied to beginner onboarding sequences in subscription platforms.
- Straps:Cotton and polyester webbing variants complete equipment bundles shipped direct-to-consumer by digital-native studios.
Mats sit at the top of the volume ranking, with apparel climbing the fastest as lifestyle brand extension accelerates.
Delivery Mode:
Channel selection determines customer acquisition economics and equipment bundling potential, with digital platforms capturing recurring revenue through subscription attach rates.
- In-Person Classes:Studio networks in the United States, China, and Germany anchor the largest revenue pool. Kerala-certified natural rubber mats command sustainability premiums in these markets as studios prioritize suppliers with closed-loop certification.
- Online Sessions:Subscription models reduce customer acquisition costs through automated equipment replenishment cycles. FDA-regulated biometric mat surfaces that track heart rate variability are piloting in New York and London boutique studios for premium membership tiers.
- Workshops:Intensive weekend formats drive concentrated block and strap purchases through instructor-curated equipment lists.
- Retreats:Destination programming in Sri Lanka and India integrates plantation-sourced mat-grade rubber into experiential pricing packages.
In-person classes hold the volume lead, while online sessions gain share fastest through platform scalability.
Practice Style:
Intensity and duration specifications shape equipment durability requirements and replacement cycle frequency across practitioner segments.
- Hatha:Gentle pacing and extended hold times demand thicker cushioning configurations, driving six-pound-density mat preferences among senior practitioners in Germany.
- Vinyasa:Dynamic flow sequences require superior grip surfaces, accelerating natural rubber adoption over PVC alternatives in United States coastal markets.
- Ashtanga:Rigorous six-day weekly practice schedules compress mat replacement cycles, supporting subscription-based replenishment models.
- Kundalini:Breath-focused and meditation-heavy formats reduce equipment dependency, limiting mat specification to basic cushioning tiers.
Hatha maintains the widest practitioner base, with Vinyasa expanding most quickly through studio network standardization.
Target Audience:
Skill level and age demographics correlate with price sensitivity, equipment bundling receptivity, and brand loyalty formation patterns.
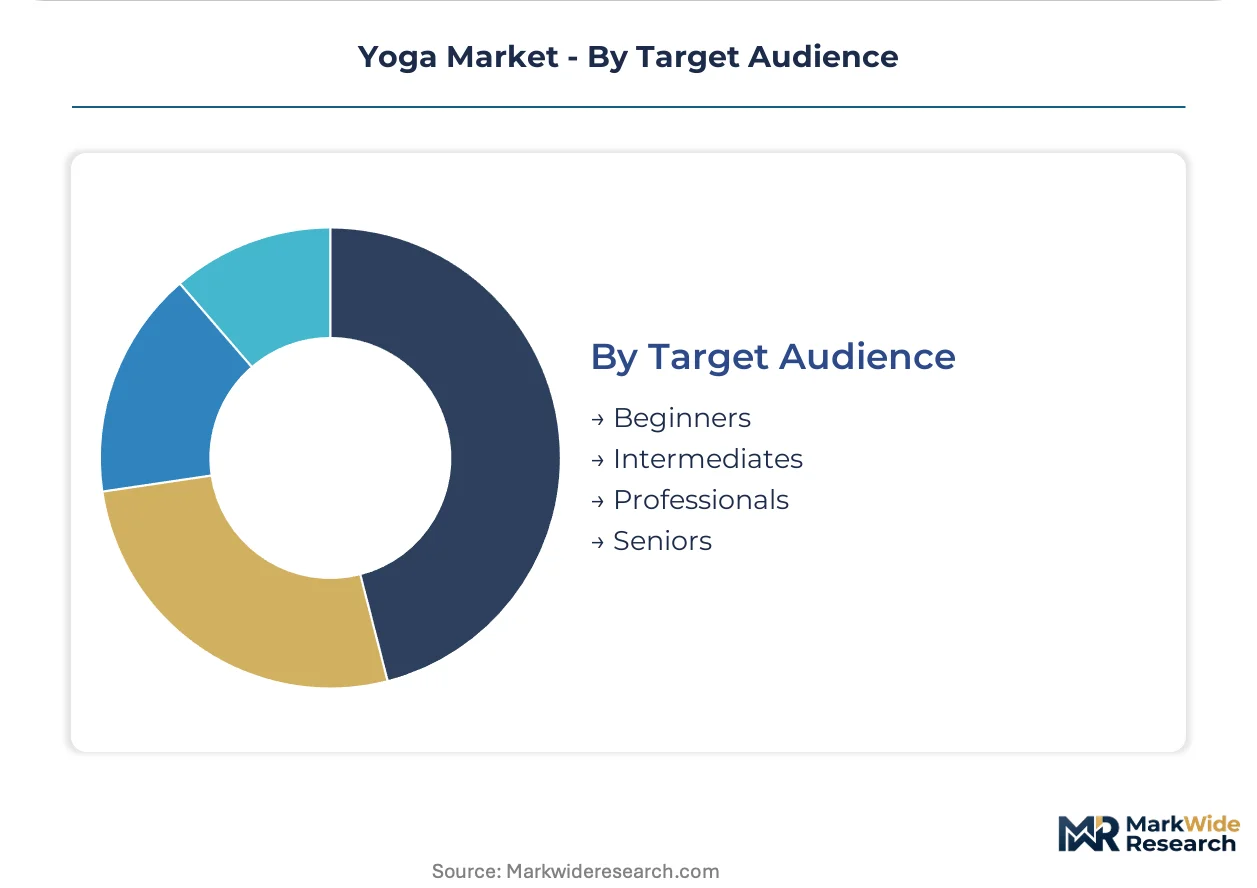
- Beginners:High churn risk and price sensitivity concentrate demand in entry-level mat and block bundles, with digital platforms capturing attach-through subscription onboarding sequences.
- Intermediates:Equipment upgrade cycles and style experimentation drive mid-tier natural rubber purchases as practitioners invest in home practice setups.
- Professionals:Instructor certification requirements in India and the United States mandate specific equipment standards, creating captive demand for lifetime-guarantee products.
- Seniors:Joint protection priorities elevate density specifications and thickness preferences, with Germany's aging population supporting premium cushioning segments.
Beginners represent the largest addressable population, with intermediates showing the steepest expansion trajectory as home practice adoption deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong province anchors global yoga equipment manufacturing, hosting polymer composite processing and TPE formulation capacity that supplies brands across North America and Europe. Kerala's certified organic rubber plantations in India and Sri Lanka's mat-grade feedstock operations provide sustainability-certified inputs for premium United States and German direct-to-consumer channels. REACH chemical safety standards and California's Proposition 65 filter low-cost Asian suppliers from these premium distribution corridors.
United States
Corporate wellness programs drive enterprise procurement of mats and apparel across North American employers, consolidating vendor relationships through B2B certification requirements. FDA oversight applies to wearable-integrated yoga technologies with biometric tracking capabilities. New York and Los Angeles studio networks anchor coastal demand for premium natural rubber formulations with density ratings between five and six pounds per cubic foot.
Germany
EU Green Deal extended producer responsibility frameworks mandate take-back programs for synthetic equipment, compelling studios in Berlin and Munich to prioritize suppliers with certified closed-loop systems. ECHA's 2023 medium-chain chlorinated paraffin restrictions forced immediate TPE reformulation across imported mat inventory. Bavaria's aging population supports premium cushioning segments targeting senior practitioners with joint protection priorities.
China
Guangdong province's polymer composite processing clusters expose brands to single-point logistics disruptions and tariff exposure despite manufacturing cost advantages. Domestic studio networks in Shanghai and Beijing expand as middle-class wellness adoption deepens. The country's national chemical safety regulator maintains evolving standards for phthalate content that lag behind REACH stringency, creating export-quality tiering.
India
Kerala's certified organic rubber plantations command sustainability premiums in United States and German direct-to-consumer channels through plantation-to-mat traceability. Tier-two cities including Pune and Ahmedabad show underpenetrated demand for certified instructor training programs. BIS certification requirements for equipment safety create compliance barriers for imported synthetic alternatives.
United Kingdom
London's boutique studio density supports same-day delivery logistics for direct-to-consumer subscription bundling of blocks and straps. GDPR compliance shapes data handling for wearable-integrated class platforms. The country's national chemical safety regulator enforces REACH-aligned restrictions that filter non-compliant Asian suppliers from premium distribution.
Yoga Market Vendor Landscape
Global majors compete with regional champions across digital infrastructure and material certification capabilities, creating tiered competitive dynamics. The vendor base separates into integrated manufacturers with in-house polymer laboratories and third-party assemblers dependent on outsourced formulation. Three archetypes dominate: lifestyle brands extending apparel equity into equipment, specialized mat manufacturers anchoring on certified closed-cell production, and digital-native platforms capturing subscription attach-through. Consolidation pressure concentrates in mid-tier suppliers unable to absorb REACH compliance costs, while premium players defend position through lifetime guarantee programs and certified sustainable sourcing.
Within the lifestyle brand archetype, Lululemon Athletica and Alo Yoga exemplify apparel-to-equipment extension strategies competing on lifestyle integration rather than price alone. Manduka occupies a position as the specialized manufacturer archetype, anchoring competitive differentiation through certified closed-cell manufacturing and lifetime product guarantees. Among digital-native platforms, Glo Digital, Inc. represents the subscription-first model capturing recurring revenue through platform scalability and automated equipment replenishment cycles.
| Leading Market Players |
|---|
| YogaWorks |
| Alo Yoga |
| CorePower Yoga |
| Honor Yoga |
| Daily Yoga |
| Lululemon Athletica |
| Manduka |
| Glo Digital, Inc. |
| Gaiam |
| Others |
Supply Flow & Price Mechanics
Closed-cell density-controlled manufacturing lines are compressing unit economics for mid-tier suppliers while elevating sustainability premiums for integrated producers with in-house polymer laboratories, simultaneously reshaping cost structures and supplier consolidation patterns across United States and German distribution channels.
Pricing Analysis
Natural rubber price volatility in Kerala and Sri Lanka passes through to mat retail tiers unevenly, with premium brands absorbing fluctuations through lifetime guarantee bundling while mid-tier competitors face margin compression. Three-tier pricing structure across premium, standard, and economy levels differentiates on REACH certification grade and density specification rather than raw material grade alone. Pricing pressure stems from ECHA's accelerated substance evaluation schedule forcing reformulation cycles faster than traditional product development timelines allow. Corporate wellness procurement teams show lowest price sensitivity due to enterprise contract consolidation, while individual beginners through direct-to-consumer channels exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from German and United States studio networks mandate multi-supplier qualification across Kerala-certified natural rubber plantations and Guangdong polymer composite processors, reducing single-point vulnerability. Geographic supply concentration centers on India, China, and Sri Lanka for feedstock and intermediate processing. Raw material dependencies include mat-grade natural rubber, TPE formulations, and cork block feedstock. Supply chain risk manifests as tariff exposure on Guangdong-sourced polymer composites amid evolving trade frameworks. Distribution runs through direct-to-consumer subscription platforms and studio network procurement channels, with traditional sporting goods retail losing share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as practitioner demand shifts toward six-pound-density closed-cell constructions with certified sustainable sourcing and lifetime guarantee backing.
For Market Incumbents: Extend certification investment into REACH-compliant closed-loop manufacturing to defend against emerging digital-native platforms with subscription attach-through models. Deepen backward integration into Kerala-certified organic rubber cultivation to secure feedstock cost stability against climate-driven price spikes. Prioritize B2B certification capabilities for corporate wellness procurement consolidation in North America. For New Entrants and Emerging Players: Enter via tier-two Indian cities including Pune and Ahmedabad where certified instructor training program demand outpaces equipment supply, leveraging plantation-to-mat traceability as differentiation against established synthetic competitors. Target subscription platform co-branding partnerships for blocks and straps to capture higher-margin add-on revenue without competing on mat manufacturing capex intensity. For Investors and Strategic Acquirers: Roll-up economics work for specialized mat manufacturers with certified closed-cell production because REACH compliance costs are filtering third-party assemblers from premium European distribution, creating acquisition targets at compressed valuations. Long-term viability favors integrated producers with in-house polymer laboratories over outsourced formulation models. Watch FDA clearance timelines for biometric mat surfaces as inflection indicator for equipment-as-service platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Certification Investment | EU Green Deal extended producer responsibility mandates create competitive moats for compliant suppliers in German studio networks. |
| Direct-to-Consumer Subscription Launch | Alo Yoga's digital infrastructure demonstrates how lifestyle content integration drives recurring mat replacement cycles in coastal United States markets. |
| Biometric Surface Development | FDA-regulated pressure-mapping algorithms open subscription revenue models for equipment-as-service platforms in New York boutique studios. |
| Plantation Integration | Kerala-certified organic rubber traceability commands sustainability premiums in United States and German direct-to-consumer channels. |
| B2B Certification Expansion | Corporate wellness procurement consolidation in North America reduces customer acquisition costs for vendors with enterprise contract capabilities. |
Methodological Framework
Multiple input streams — primary interviews with studio owners and equipment procurement managers, secondary trade data from customs records and certified organic rubber plantation disclosures, and regulatory filing analysis from ECHA and FDA — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates across the analysis window.
Data-stream reconciliation applied analytical frameworks modeling product type, delivery mode, practice style, and target audience dimensions throughout the forecast period. CAGRs were derived from segment-level volume and value trajectories calibrated against historical replacement cycle patterns and studio network expansion rates. Industry-specific forecast inputs included natural rubber price indices from Kerala auction markets and REACH compliance cost estimates from polymer laboratory investment disclosures.
Inputs from studio network operators and certified plantation cooperatives were available through the study window; gaps in real-time biometric mat surface pilot performance data introduce uncertainty bands around wearable-integrated technology adoption curves. Forecasts reflect assumptions on corporate wellness program penetration and ECHA substance evaluation timelines without specific regulatory calendar commitments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Weight Management Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Sports and Fitness Biohacking Market