
 Personal Fitness Trainer Market | 2026-2036
Personal Fitness Trainer Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Fitness Trainer Market Analytics
Subscription-based micro-financing and pay-per-session digital wallets are fragmenting capital requirements for new fitness studios. Planet Fitness leverages its asset-light franchise model to sustain national footprint expansion without heavy balance-sheet exposure. Equinox Holdings anchors premium positioning through captive real estate in dense urban corridors. Anytime Fitness competes on 24/7 access density, operating over four thousand locations through managed licensing structures.
A personal fitness trainer delivers structured exercise programming, biomechanical assessment, and progressive overload protocols calibrated to individual anthropometrics and metabolic markers. The service encompasses periodization design, movement screening, and recovery management to reduce injury incidence while improving cardiorespiratory and musculoskeletal performance. One-on-one training commands the deepest margin pools due to price inelasticity among high-net-worth clients and chronic-disease management referrals. Group classes generate volume throughput for fixed-cost studio infrastructure, while online coaching extends geographic reach beyond physical facility catchments.
FDA oversight of software-as-medical-device claims shapes how trainers deploy heart-rate variability and blood-glucose trend data in programming decisions. HIPAA compliance requirements govern data flows when trainers interface with employer-sponsored wellness platforms and insurance reimbursement pathways. OSHA ergonomic guidelines influence equipment selection and facility layout liability for commercial gym operators. Stakeholders must monitor evolving telehealth licensure portability rules that determine whether digital coaching crosses state or national regulatory boundaries.
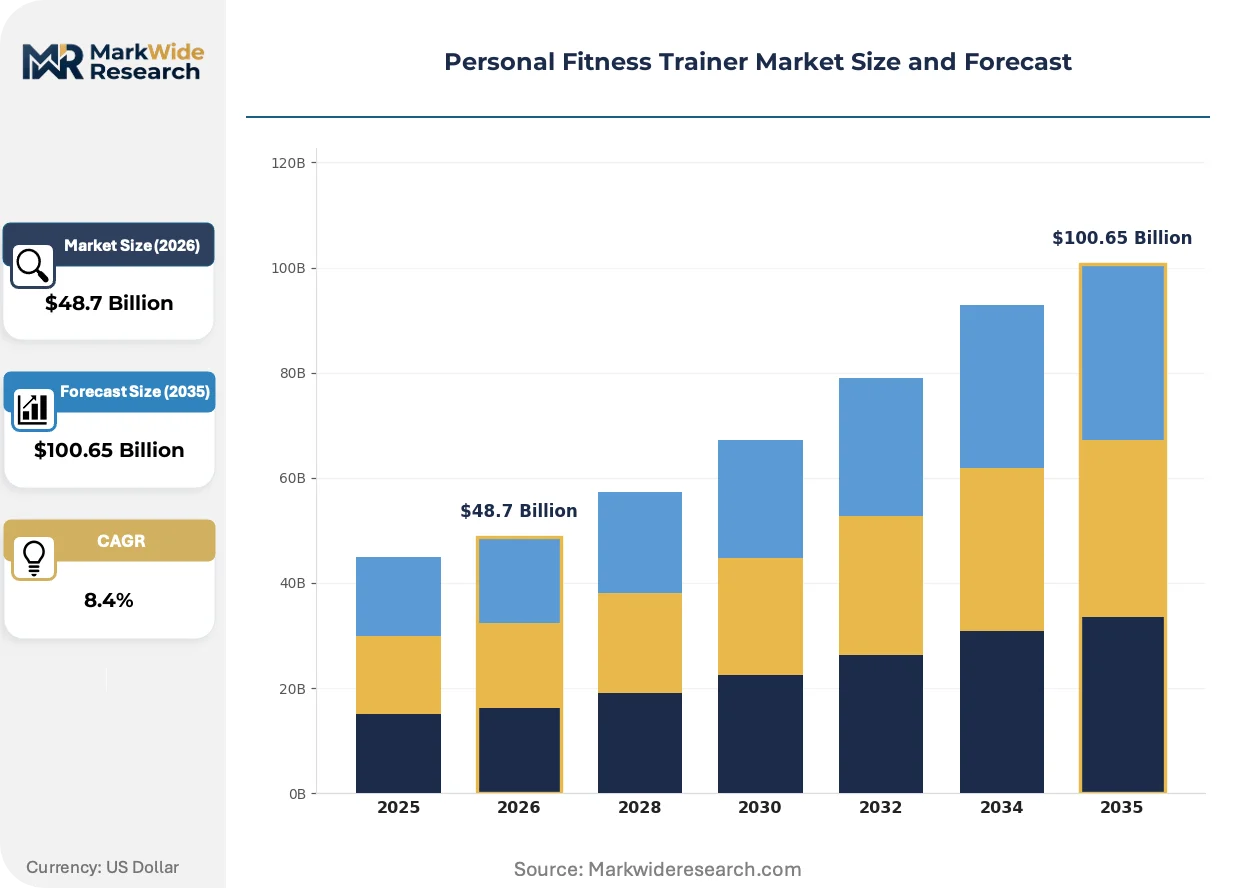
Market Dynamics
Wearable biometric integration and AI-driven workout personalization are compressing service delivery timelines while fragmenting price points across the personal fitness trainer landscape. Trainers now compete against algorithmic programming that replicates periodization protocols at marginal cost.
Growth Catalysts
- Corporate wellness mandates:Employer-sponsored platforms in the United States now subsidize structured fitness services as deductible preventive health expenditures under IRS Section 213. This channels institutional capital into trainer certification pipelines.
- Wearable data interoperability:Bluetooth-enabled heart-rate variability monitors and continuous glucose monitors generate real-time metabolic feedback loops. Trainers leverage this biostream to calibrate load prescription with precision previously requiring laboratory assessment.
- Chronic disease management referrals:Physician-directed exercise prescriptions for diabetes and hypertension patients create reimbursable care pathways. Trainers with clinical exercise physiology credentials capture this insured volume.
Market Restraints
- Certification fragmentation:Over two hundred credentialing bodies operate without unified competency standards. This variability degrades consumer trust and complicates insurer verification protocols.
- Labor supply concentration:Quality trainers cluster in dense urban corridors with premium disposable income. Secondary metropolitan areas face persistent talent scarcity and elevated recruitment costs.
- Platform disintermediation:AI coaching applications substitute algorithmic programming for human oversight at subscription price points below hourly trainer wages. This compresses entry-tier market viability.
Strategic Opportunities
- Telehealth licensure portability:Interstate compacts for health professional mobility are expanding to include exercise physiologists. Trainers can serve clients across state lines without redundant credentialing.
- Medicare Advantage integration:Supplemental benefit carve-outs for fitness programming create direct billing relationships between trainers and payers. This bypasses traditional out-of-pocket consumer payment friction.
- Biometric-AI convergence:Integration of sleep architecture data from Oura rings with training load algorithms enables recovery-optimized programming. Early adopters differentiate through quantified regeneration protocols.
Industry Challenges
- HIPAA compliance infrastructure:Trainers interfacing with employer wellness platforms must implement encrypted data architectures and business associate agreements. Small independent operators lack capital for compliant technology stacks.
- Continuing education velocity:Certification maintenance requires documented contact hours in evolving specialty domains. Time investment competes with revenue-generating client sessions.
- Facility liability exposure:OSHA ergonomic guidelines for commercial gym equipment selection create negligence exposure for trainers operating in multi-use spaces. Insurance premiums reflect this litigation risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Fitness Trainer Market |
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: One-on-One Training, Group Classes, Online Coaching, Hybrid Programs Client Type: Individual Clients, Corporate Clients, Athletes, Seniors Training Style: Strength Training, Cardio Conditioning, Flexibility Training, HIIT Experience Level: Beginner, Intermediate, Advanced, Professional |
| Companies Covered | Planet Fitness, Equinox Holdings, Anytime Fitness, Gold's Gym International, Technogym, Peloton, Orangetheory Fitness, F45 Training Holdings, Life Time Fitness, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Fitness Trainer Market Evolving Landscape
Algorithmic personalization engines are displacing static programming templates while regulatory scrutiny intensifies around software-as-medical-device claims. Service delivery models bifurcate between high-touch biometric coaching and fully automated digital protocols.
Continuous glucose monitoring is hybridizing metabolic fueling guidance with resistance training periodization. Athletes and metabolic health clients adopt Dexcom and FreeStyle Libre integrations to time carbohydrate intake around training windows. This convergence enables real-time nutritional periodization that was previously confined to elite sport science laboratories.
FDA oversight of software-as-medical-device claims is reshaping how heart-rate variability applications position their coaching outputs. Developers must navigate 510(k) clearance pathways when algorithms suggest specific exercise intensities for cardiac rehabilitation populations. This regulatory friction advantages established players with compliance infrastructure over garage-scale app developers.
Subscription fatigue among digital fitness consumers is fragmenting commitment patterns toward micro-session purchasing. Buyers now sample trainer services through single-session bookings before annual commitments. This behavior concentrates revenue volatility among independent operators while platform aggregators capture booking friction rents.
Personal Fitness Trainer Market Segmentation
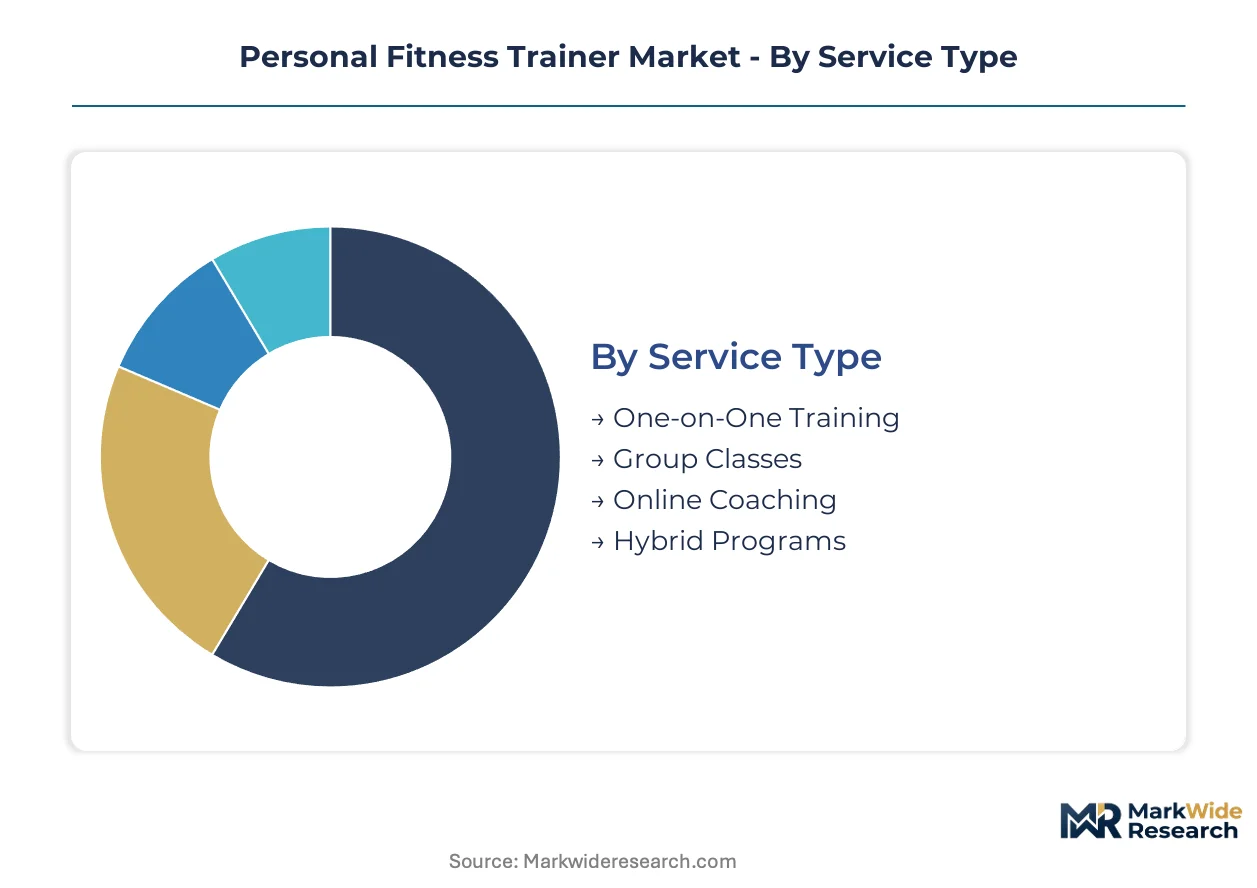
Service delivery models in the personal fitness trainer market exhibit sharply divergent capital intensity and client acquisition economics. Segmentation reveals which configurations sustain premium pricing versus which face algorithmic displacement.
Service Type:
Cycle times vary dramatically: one-on-one relationships renew monthly while online coaching subscriptions churn quarterly. Hybrid programs sit in between with seasonal commitment patterns tied to calendar-year wellness budgets.
- One-on-One Training:Direct biomechanical assessment and real-time form correction command the highest hourly rates. Demand concentrates among high-net-worth individuals in dense urban corridors like Manhattan and London, where price inelasticity persists despite AI coaching alternatives.
- Group Classes:Volume throughput amortizes fixed studio costs across twelve to twenty participants per session. Corporate wellness contracts in Germany and employer-sponsored platforms in the United States now subsidize group programming as preventive health expenditures.
- Online Coaching:Asynchronous programming delivery extends geographic reach beyond physical facility catchments. HIPAA-compliant platforms enable trainers to serve clients across state lines where telehealth licensure compacts apply.
- Hybrid Programs:Blended in-person and digital touchpoints optimize client retention through accountability layering. Medicare Advantage supplemental benefit carve-outs increasingly cover hybrid models for chronic disease management populations.
One-on-one training dominates installed base revenue. Online coaching is where expansion concentrates.
Client Type:
Procurement authority separates consumer-paid individual relationships from institutional contracting with standardized service-level agreements.
- Individual Clients:Direct out-of-pocket payment creates price transparency and loyalty stickiness. Subscription fatigue is fragmenting commitment patterns toward micro-session purchasing before annual commitments.
- Corporate Clients:Employer-sponsored wellness platforms channel institutional capital into trainer certification pipelines. IRS Section 213 deductibility in the United States treats structured fitness as preventive health expenditure.
- Athletes:Periodization design for competitive performance demands specialized credentials in exercise physiology. Continuous glucose monitoring integration enables real-time nutritional periodization previously confined to elite sport science laboratories.
- Seniors:Fall prevention and sarcopenia management drive physician-directed exercise prescriptions. Trainers with clinical exercise physiology credentials capture this insured volume through reimbursable care pathways.
Individual clients anchor current revenue pools. Corporate contracts are climbing the fastest as wellness mandates expand.
Training Style:
Equipment requirements and space utilization economics differentiate capital-light modalities from infrastructure-heavy programming.
- Strength Training:Progressive overload protocols require resistance equipment and racking systems that elevate facility liability exposure under OSHA ergonomic guidelines. Anytime Fitness competes on 24/7 access density for strength-focused members.
- Cardio Conditioning:Heart-rate variability monitoring and Bluetooth-enabled biometric feedback loops enable precision load prescription. FDA oversight of software-as-medical-device claims shapes how trainers deploy cardiac rehabilitation data.
- Flexibility Training:Lower equipment thresholds support independent operator entry with minimal capital requirements. Recovery management protocols reduce injury incidence while improving musculoskeletal performance metrics.
- HIIT:High-intensity interval programming maximizes caloric throughput per session minute for time-constrained professionals. Planet Fitness leverages asset-light franchise models to scale HIIT-accessible infrastructure nationally.
Strength training holds the deepest margin pools. HIIT is where volume throughput concentrates for fixed-cost studio infrastructure.
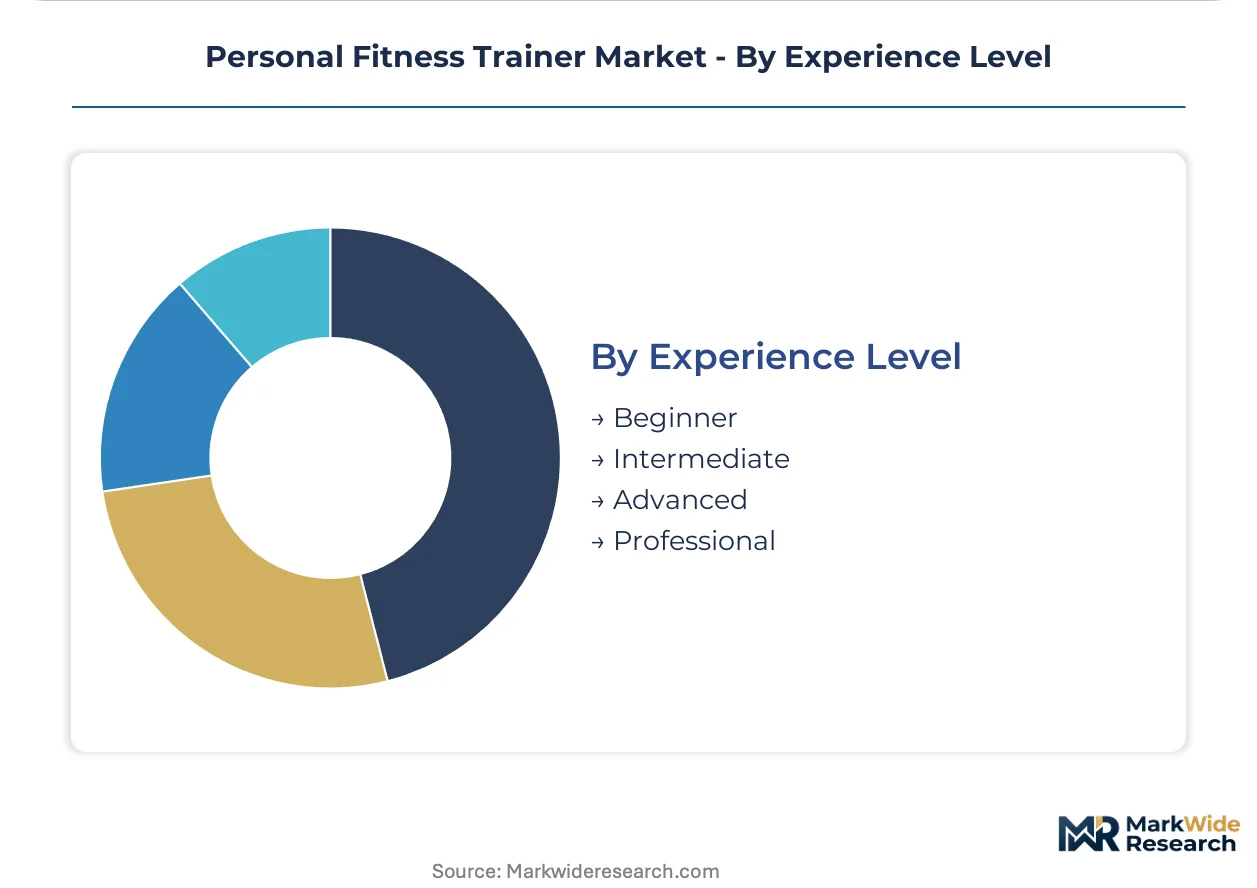
Experience Level:
Credential requirements and pricing power escalate non-linearly from entry-tier to professional programming.
- Beginner:Movement screening and foundational motor pattern development reduce injury incidence for deconditioned populations. Certification fragmentation across over two hundred credentialing bodies degrades consumer trust at this tier.
- Intermediate:Periodization design and progressive overload protocols require documented contact hours in evolving specialty domains. Continuing education velocity competes with revenue-generating client sessions for trainer time allocation.
- Advanced:Metabolic markers and anthropometric calibration demand laboratory-grade assessment integration. Biometric-AI convergence through sleep architecture data enables recovery-optimized programming differentiation.
- Professional:Elite sport science application requires clinical exercise physiology credentials and insurance reimbursement pathway navigation. Platform disintermediation through AI coaching applications compresses entry-tier viability but leaves professional tier intact.
Intermediate programming dominates client volume. Professional tier services are gaining share fastest through Medicare Advantage integration and chronic disease management referrals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRS Section 213 deductibility in the United States treats employer-sponsored fitness as preventive health expenditure, channeling institutional capital into trainer certification pipelines across multiple continents. Corporate wellness mandates in Germany and wearable biometric adoption in China are accelerating localized service delivery investments. Urban density clusters in London, Shanghai, and New York concentrate premium pricing power for high-touch coaching.
United States
Employer-sponsored wellness platforms subsidize structured fitness services through deductible preventive health expenditures. HIPAA compliance requirements govern data flows when trainers interface with insurance reimbursement pathways. Manhattan and Los Angeles anchor premium pricing pools where one-on-one training commands sustained price inelasticity among high-net-worth clients.
China
Continuous glucose monitoring adoption and wearable biometric integration are transforming metabolic fueling guidance in resistance training periodization. SAMR oversight shapes how fitness applications deploy algorithmic coaching outputs for consumer health claims. The Yangtze River Delta cluster around Shanghai concentrates demand for AI-driven workout personalization among affluent professionals.
Germany
Corporate wellness contracts now subsidize group programming as preventive health expenditures under national occupational health frameworks. DGUV ergonomic guidelines influence equipment selection and facility layout liability for commercial gym operators. Munich and Berlin anchor dense urban corridors where quality trainers cluster amid persistent secondary-market talent scarcity.
United Kingdom
Telehealth licensure portability expansion enables exercise physiologists to serve clients across devolved national boundaries without redundant credentialing. GDPR compliance requirements govern biometric data flows from wearable devices into coaching platforms. London's premium disposable income concentration sustains deep margin pools for personalized biomechanical assessment services.
Australia
Medicare Advantage-style supplemental benefit carve-outs for fitness programming are creating direct billing relationships between trainers and private payers. TGA oversight of software-as-medical-device claims shapes how heart-rate variability applications position cardiac rehabilitation outputs. Sydney and Melbourne anchor national demand for chronic disease management referrals through clinical exercise physiology credentials.
Personal Fitness Trainer Market Competitive Landscape
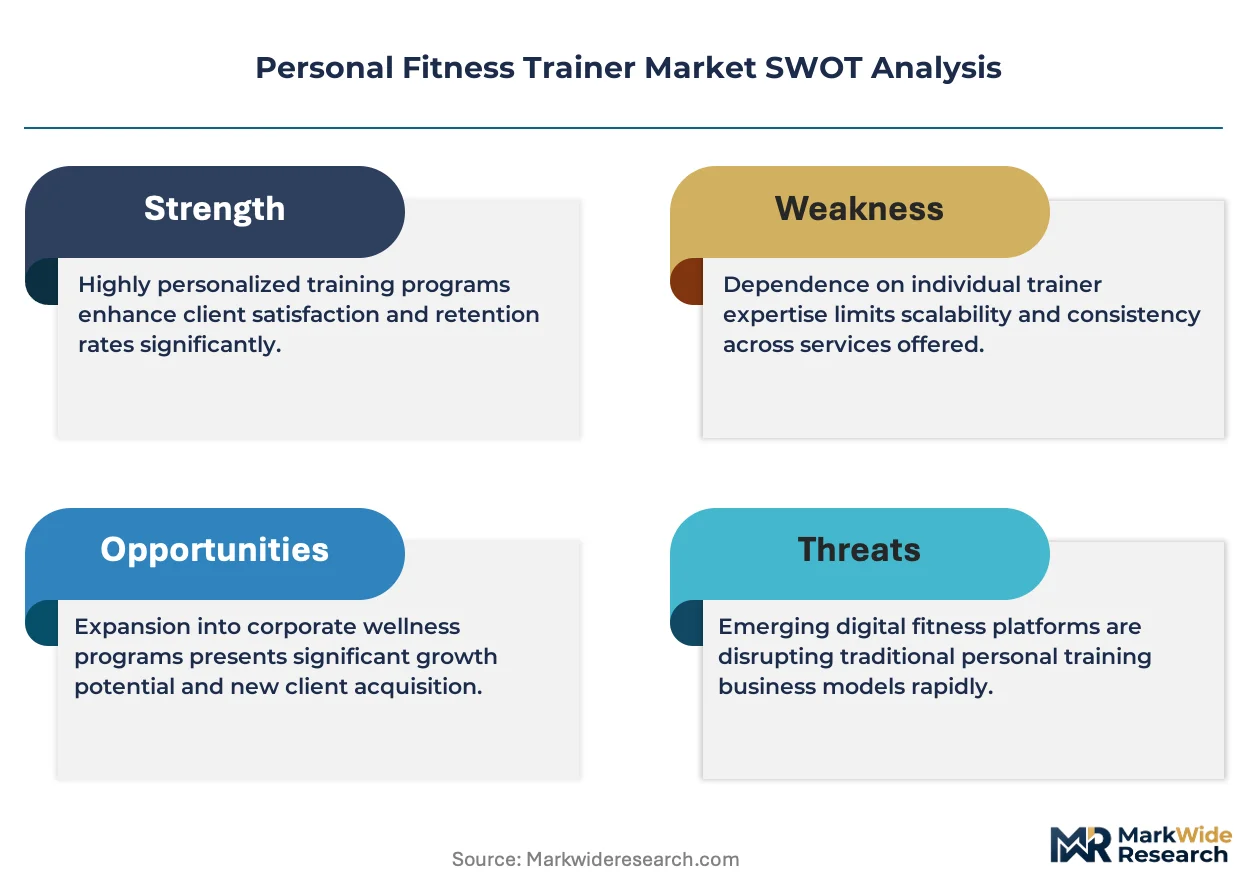
On the supply side, the industry is bifurcated between asset-light franchise operators and premium-tier captive real estate holders. Franchise licensing structures enable national footprint expansion without heavy balance-sheet exposure. Two strategic archetypes dominate: volume-driven 24/7 access density players and premium urban corridor specialists with integrated wellness ecosystems. Competitive moves concentrate on geographic licensing expansion and biometric-AI technology convergence to differentiate programming outputs.
Within the franchise-model tier, Planet Fitness and Anytime Fitness exemplify asset-light scaling architectures that minimize capital intensity per location. Equinox Holdings occupies the premium-tier position through dense urban real estate concentration and integrated wellness service stacking. Among technology-integrated operators, Peloton represents the algorithmic personalization vector that competes against human-delivered coaching at subscription price points below traditional hourly trainer wages.
| Leading Market Players |
|---|
| Planet Fitness |
| Equinox Holdings |
| Anytime Fitness |
| Gold's Gym International |
| Technogym |
| Peloton |
| Orangetheory Fitness |
| F45 Training Holdings |
| Life Time Fitness |
| Others |
Value Network & Pricing Analysis
HIPAA compliance infrastructure costs act as a tariff-like barrier that compresses margins for independent operators while widening spreads between premium biometric-integrated services and entry-tier digital alternatives. This regulatory chokepoint forces supply chain choices toward platform aggregators with capital for encrypted data architectures.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with clinical exercise physiology credentials commanding sustained price inelasticity among chronic disease management populations. Three-tier pricing structure across premium, standard, and economy levels stratifies by biometric integration depth and real-time coaching touchpoints. Cost compression in entry-tier digital subscriptions stems from AI coaching applications substituting algorithmic programming below hourly trainer wages. Corporate wellness contracts exhibit lowest price sensitivity due to IRS Section 213 deductibility, while individual micro-session purchasers show highest elasticity.
Supply Chain Analysis
Extended payment terms from platform aggregators now dominate supplier financing for independent trainers, compressing cash conversion cycles toward 60-90 day averages. Equipment manufacturing concentrates in China, Germany, and the United States, with wearable biometric devices drawing from Taiwanese semiconductor fabrication and South Korean sensor assembly. Single-source vulnerability persists in continuous glucose monitor supply chains tethered to Dexcom and Abbott production hubs. Distribution runs through franchise licensing structures that minimize capital intensity per location while capturing geographic exclusivity premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corporate wellness budget cycles position this market in early-stage recovery, with employer-sponsored platform expansion acting as the cyclical driver channeling institutional capital into certification pipelines.
For Market Incumbents: Build captive real estate moats in dense urban corridors like Manhattan and London where price inelasticity persists despite AI coaching alternatives. Defend against platform disintermediation by deepening Medicare Advantage integration for chronic disease management referrals. Pursue backward integration into wearable biometric data platforms to control algorithmic programming inputs. For New Entrants and Emerging Players: Secondary metropolitan areas in Germany and Australia represent the most penetrable entry point amid persistent talent scarcity and elevated recruitment costs. Telehealth licensure portability across state lines enables geographic arbitrage without redundant credentialing investments. Target corporate wellness contracts through IRS Section 213 deductible positioning as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA 510(k) clearance pathways for software-as-medical-device claims reshape the acquisition landscape toward established players with compliance infrastructure. Five-to-ten year viability favors vertically integrated operators combining physical facility networks with HIPAA-compliant digital platforms. Acquisition target archetype: mid-scale hybrid program providers with Medicare Advantage billing relationships. Watch telehealth licensure compact expansion as the signal for cross-border service scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric-AI Platform Integration | Oura ring and Dexcom data convergence enables recovery-optimized programming differentiation against algorithmic competitors. |
| Medicare Advantage Billing Partnership | Direct payer relationships bypass out-of-pocket friction for chronic disease management populations. |
| Telehealth Licensure Expansion | Interstate compacts unlock cross-state service delivery without redundant credentialing costs. |
| Corporate Wellness Contract Capture | IRS Section 213 deductibility channels institutional capital into trainer certification pipelines. |
| Clinical Credential Stacking | Exercise physiology certifications capture physician-directed referral volume through reimbursable care pathways. |
Research Methodology
A standing panel of fitness studio operators, corporate wellness procurement managers, exercise physiologists, and health insurance reimbursement specialists provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare Advantage supplemental benefit data, and franchise disclosure documents. Bottom-up location counts triangulated against top-down employer wellness expenditure estimates across the analysis window.
Scenario-bracketing framed volume and value outputs across service type, client type, training style, and experience level dimensions. CAGRs derived from fitted growth curves anchored to biometric adoption rates and corporate wellness mandate expansion. Forecast inputs incorporated wearable device shipment trajectories and telehealth licensure compact ratification timelines.
Macroeconomic conditions sit as an overlay; deviation in employer health benefit budgets or discretionary consumer spending would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory clarity on software-as-medical-device claims. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO