
 Personalized Retail Nutrition and Wellness Market | 2026-2036
Personalized Retail Nutrition and Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Retail Nutrition and Wellness Market Analysis
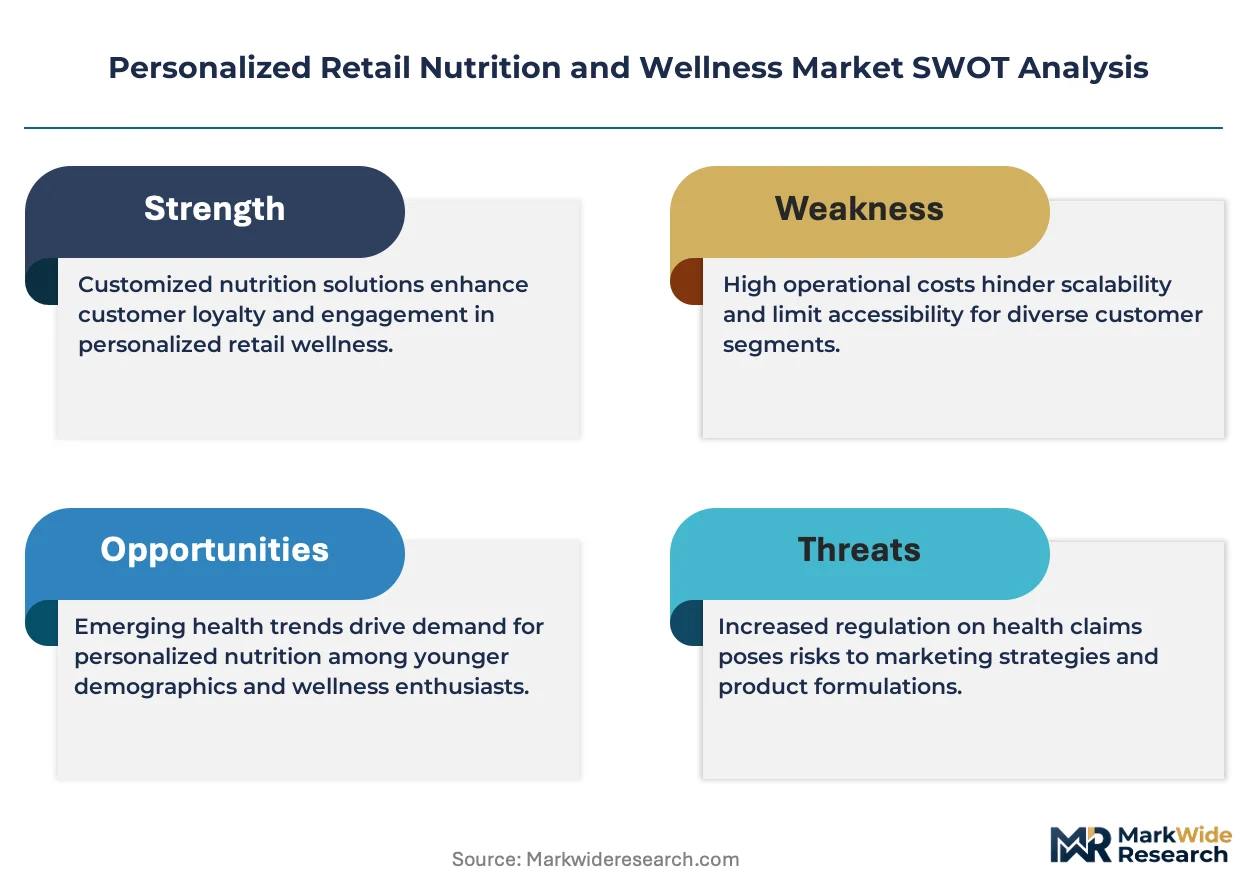
Clinical-grade personalization is rotating the market away from generic supplement shelves toward biometric-validated formulations. Viome Life Sciences leverages microbiome sequencing depth to sustain its technology leadership in gut-health customization. Cargill anchors its position through captive supply chains for traceable botanical extracts. Nutrigenomix differentiates via licensed practitioner channels that control genetic-data interpretation standards.
Personalized retail nutrition and wellness encompasses data-driven dietary interventions that match individual genetic profiles, microbiome compositions, and metabolic biomarkers to customized product formulations and coaching protocols, typically manufactured through small-batch compounding or algorithmically configured kit assembly with cold-chain integrity for live-culture components. Its commercial purpose centers on converting one-time supplement purchasers into recurring revenue streams through subscription-based biometric monitoring and iterative formula adjustments. Supplements currently occupy the largest margin pool due to repeat-purchase velocity and formulation IP barriers, while meal kits represent the fastest-growing product type as consumers seek execution support beyond pill-based regimens. Online retail channels dominate customer acquisition economics, though health stores retain higher average basket values through in-body composition testing and staff consultation.
The FDA oversees nutrigenetic health claims and dietary supplement labeling under DSHEA and emerging guidance for software-as-medical-device applications, while HIPAA governs consumer genetic data portability between testing laboratories and nutrition platforms. The EU's GDPR and the proposed EU AI Act constrain cross-border biometric algorithm training, creating compliance cost divergence for multinational operators. Stakeholders must monitor whether regulators classify microbiome-derived recommendations as medical advice, a determination that would trigger premarket authorization requirements and reshape competitive economics for direct-to-consumer brands.
Market Dynamics
DNA-based meal planning is fragmenting consumer loyalty from mass-market supplement brands toward biometric-validated subscription protocols, forcing incumbents to rebuild around recurring data relationships rather than shelf-space dominance.
Growth Catalysts
- HIPAA-compliant data portability:The US framework for genetic information exchange between testing laboratories and nutrition platforms removes friction from onboarding workflows. Direct-to-consumer brands capture subscribers faster when health records flow seamlessly.
- Microbiome sequencing depth:Advances in gut-health analytics enable formulation precision that generic probiotics cannot match. Health enthusiasts pay premium subscriptions for strain-level customization.
- Germany:Licensed practitioner channels in the EU's largest economy control genetic-data interpretation standards, creating trusted gatekeeper networks that validate premium pricing.
Market Restraints
- Cold-chain live-culture logistics:Probiotic formulations require temperature-controlled distribution that multiplies fulfillment costs versus ambient supplement shipping. Small-batch manufacturers absorb margin compression.
- FDA nutrigenetic claim uncertainty:Evolving guidance for DNA-based health recommendations creates labeling compliance risk. Brands delay marketing investments pending enforcement clarity.
- Botanical extract supply concentration:Traceable ingredient sourcing clusters in limited cultivation regions, exposing formulators to harvest volatility and adulteration risk.
Strategic Opportunities
- Employer wellness mandates:US corporate benefits managers seek biometric monitoring programs that reduce insurance premiums. Personalized nutrition vendors embed into HR procurement pipelines.
- EU AI Act algorithmic transparency:The proposed framework for biometric recommendation engines creates first-mover advantage for compliant platforms. Early certification builds B2B trust with EU health insurers.
- Meal kit execution support:Consumers abandon pill-only regimens for guided culinary protocols. Algorithmic recipe configuration with pre-portioned ingredients captures higher wallet share than supplements alone.
Industry Challenges
- Genetic counselor workforce scarcity:Interpretation of nutrigenomic reports requires specialized training that outpaces educational pipeline output. Platforms compete for limited credentialed staff.
- Software-as-medical-device classification ambiguity:The FDA's evolving stance on algorithmic health recommendations threatens product registration timelines. Engineering teams redesign architectures preemptively.
- Cross-border biometric data residency:GDPR constraints on EU citizen genetic information storage complicate cloud infrastructure architecture for US-headquartered platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Retail Nutrition and Wellness Market |
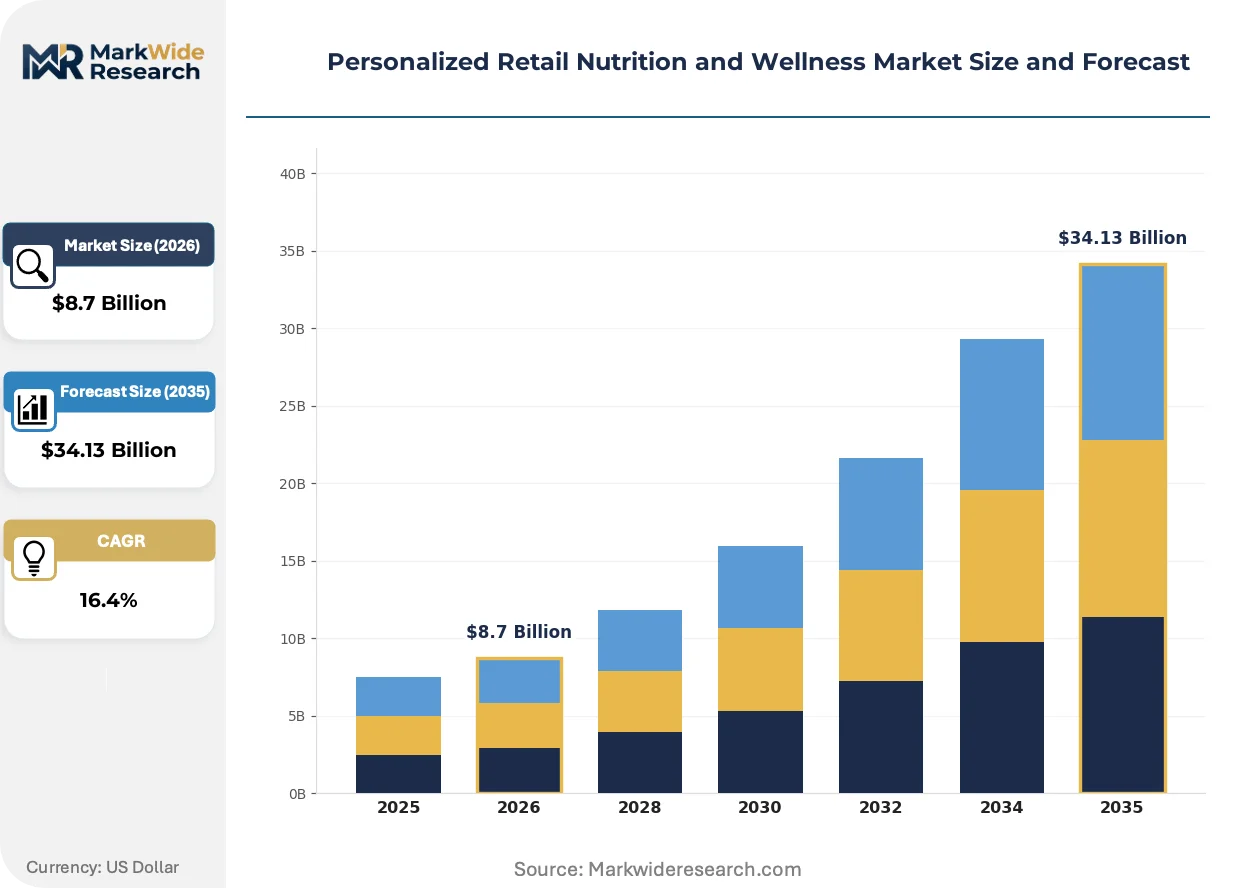
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Supplements, Meal Kits, Beverages, Nutritional Bars Customer Type: Health Enthusiasts, Diet-Conscious Individuals, Athletes, Casual Consumers Distribution Channel: Online Retail, Supermarkets, Health Stores, Specialty Shops Service Type: Personalized Plans, Consultations, Workshops, Subscription Services |
| Companies Covered | Nature's Lab, Cargill, Incorporated, Nature's Bounty, Bayer AG, PlateJoy LLC, Viome Life Sciences, Inc., Noom, Inc., Nutrigenomix, DNAfit (Prenetics Global), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Retail Nutrition and Wellness Market Emerging Trajectories
Continuous glucose monitoring integration is rewiring how consumers validate nutritional interventions, replacing trust in marketing claims with real-time metabolic feedback loops that demand iterative formula adjustment capabilities.
Multi-omics platforms combining genomic, microbiome, and metabolomic datasets are bifurcating the competitive landscape between point-solution vendors and integrated stack providers. Health systems and self-insured employers favor consolidated data architectures that reduce vendor fragmentation. Point-solution specialists face margin pressure as buyers consolidate procurement around platforms offering unified biometric dashboards.
The FDA's emerging framework for software-as-medical-device applications in nutrigenomics is compressing product development timelines for direct-to-consumer brands. Companies now pre-submit algorithmic recommendation engines for regulatory feedback before commercial launch. This procedural shift favors well-capitalized platforms with dedicated regulatory affairs functions over lean startups.
Subscription auto-replenishment with biometric-triggered formula adjustments is displacing static product purchases in the United States. Consumers expect their supplement protocols to evolve with quarterly microbiome retesting. Health stores respond by installing in-body composition analyzers that generate data justifying staff consultation fees and higher basket values versus online pure-plays.
Personalized Retail Nutrition and Wellness Market Segmentation
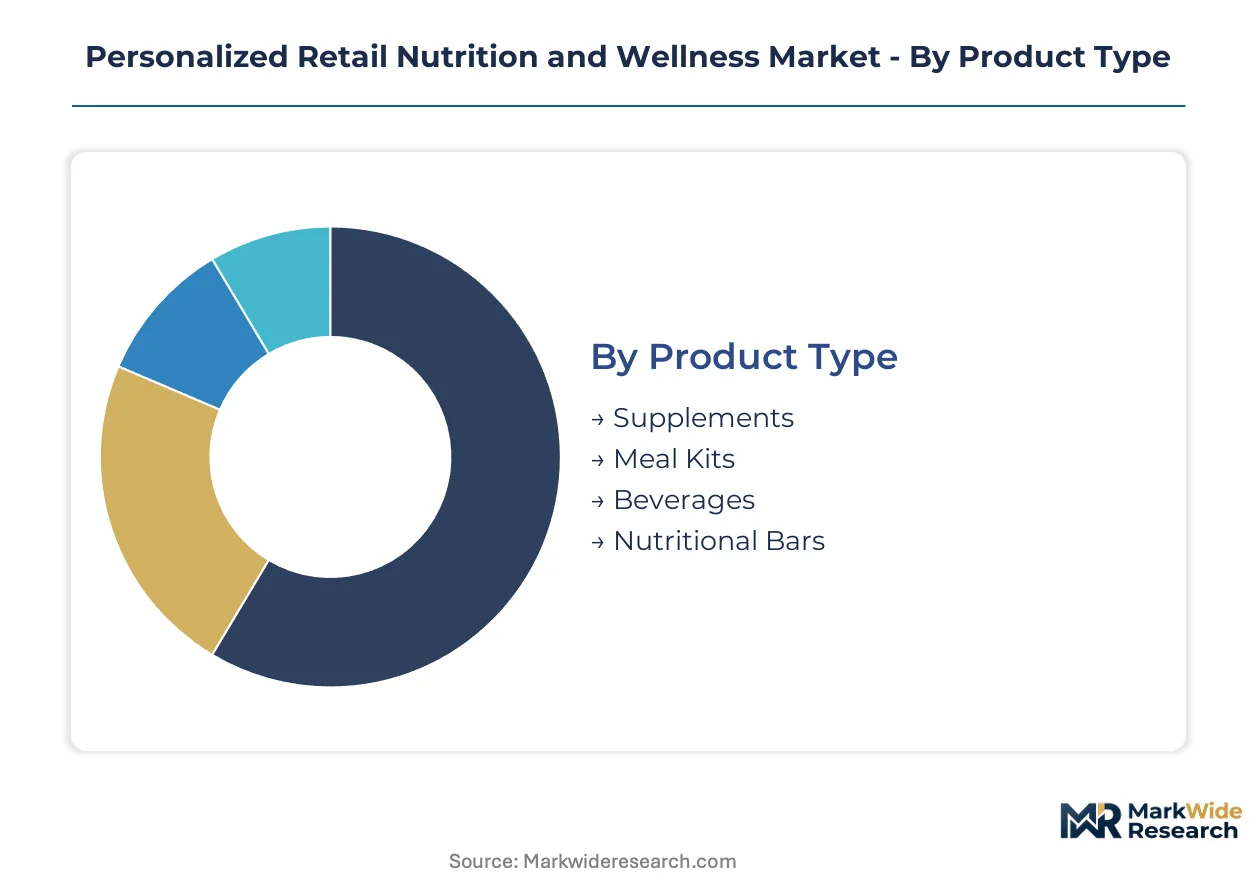
Personalized retail nutrition and wellness operates across four intersecting dimensions that determine how biometric data converts to recurring revenue. Product formulation, customer motivation, channel economics, and service architecture each carry distinct margin profiles and competitive barriers.
Product Type:
Supplements capture the deepest margin pools due to repeat-purchase velocity and proprietary formulation IP that resists commoditization.
- Supplements:Custom vitamin packs, probiotics, and nootropic stacks manufactured through small-batch compounding with strain-level specificity. Health enthusiasts in the United States drive subscription velocity through quarterly microbiome retesting protocols that trigger formula adjustments.
- Meal Kits:Algorithmically configured recipe boxes with pre-portioned ingredients matched to genetic metabolic profiles and continuous glucose monitoring data. Demand concentrates among diet-conscious individuals seeking execution support beyond pill-based interventions, climbing the fastest as consumers abandon static supplement regimens for guided culinary protocols.
- Beverages:Functional drinks with personalized micronutrient fortification and live-culture fermentation bases.
- Nutritional Bars:Macro-calibrated snack formats with biometric-validated ingredient ratios for athletic recovery or metabolic control.
Supplements hold installed capacity. Meal kits are rotating up the share rankings.
Customer Type:
Volume concentrates among consumers with established health optimization routines rather than reactive medical necessity.
- Health Enthusiasts:Early adopters of multi-omics testing who validate interventions through biometric feedback loops and pay premium subscriptions for strain-level gut-health customization. This segment expanding most quickly as DNA-based meal planning fragments loyalty from mass-market brands toward data-driven protocols.
- Diet-Conscious Individuals:Consumers managing weight, prediabetes, or food intolerances through continuous glucose monitoring integration and personalized macronutrient targeting.
- Athletes:Performance-focused buyers seeking recovery optimization through metabolomic-informed supplementation timing and composition.
- Casual Consumers:Price-sensitive entrants attracted by employer wellness mandates or introductory genetic testing bundles with limited retention economics.
Health enthusiasts dominate lifetime value calculations. Diet-conscious individuals are gaining share fastest among employer-sponsored programs.
Distribution Channel:
Customer acquisition economics diverge sharply between digital-native onboarding and physical consultation models.
- Online Retail:Direct-to-consumer platforms with algorithmic recommendation engines and subscription auto-replenishment triggered by biometric retesting. The United States concentration reflects HIPAA-compliant data portability between testing laboratories and nutrition platforms.
- Health Stores:Physical locations with in-body composition analyzers and credentialed staff consultation that command higher basket values through data-justified service fees.
- Supermarkets:Mass retail shelf presence for entry-tier personalized products with limited customization depth.
- Specialty Shops:Boutique channels in fitness clusters or medical adjacencies with practitioner validation networks.
Online retail owns subscriber acquisition efficiency. Health stores are rotating up the share rankings through consultation monetization.
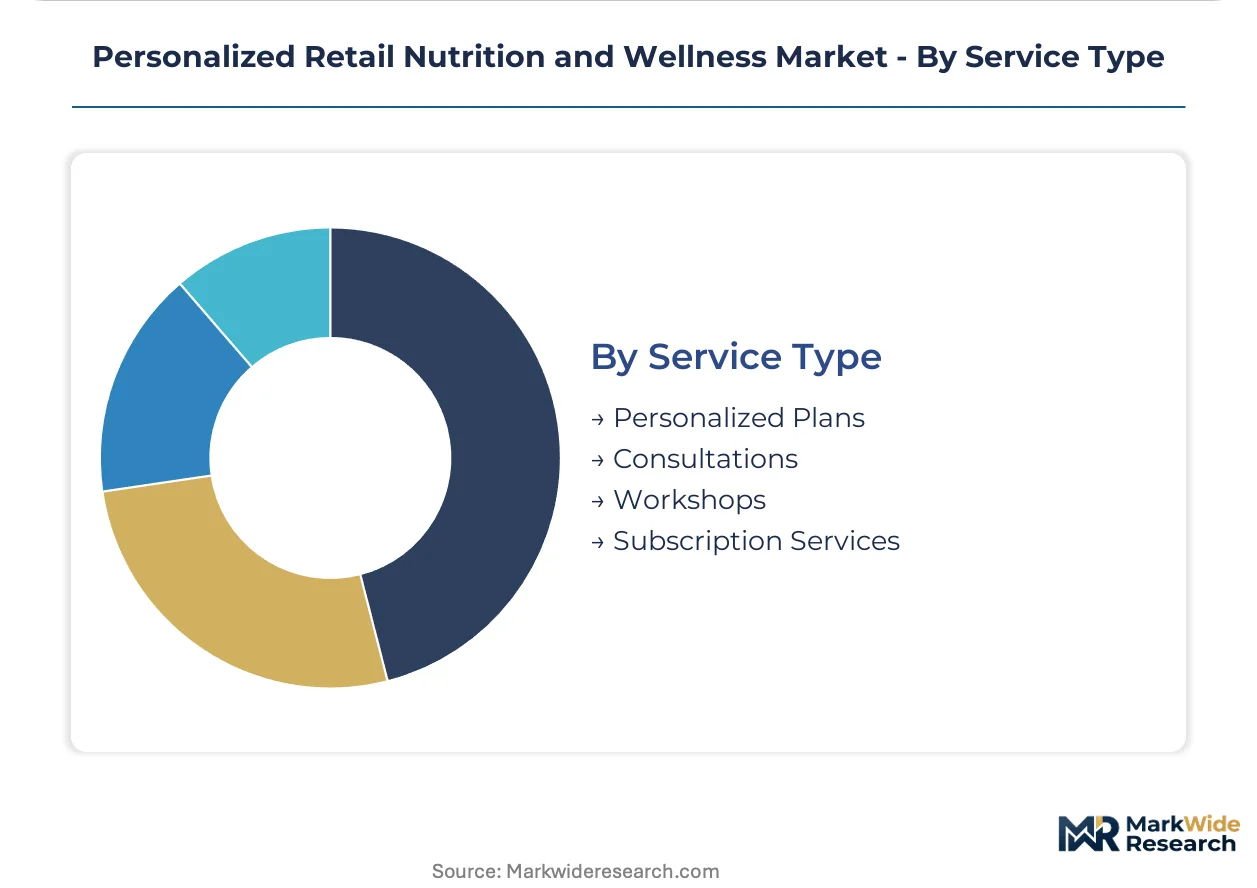
Service Type:
Recurring revenue architecture separates scalable digital delivery from high-touch professional relationships.
- Subscription Services:Automated product replenishment with iterative formula adjustments based on quarterly microbiome or metabolomic retesting. This segment carries the steepest expansion trajectory as consumers expect protocols to evolve with biometric feedback.
- Personalized Plans:Algorithm-generated dietary and supplement protocols configured from genetic, microbiome, and continuous glucose monitoring datasets.
- Consultations:Licensed practitioner channels controlling genetic-data interpretation standards and validating premium pricing through credentialed guidance.
- Workshops:Group education formats for employer wellness mandates or health system prevention programs with lower per-capita economics.
Subscription services hold installed capacity. Consultations are rotating up the share rankings as regulatory clarity on software-as-medical-device classification delays pure-play algorithmic models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows concentrate in the United States while Germany and Japan export formulation IP and diagnostic platforms. Trade balances favor service economies with strong data-protection frameworks that attract cross-border subscription revenue.
United States
HIPAA-compliant data portability between testing laboratories and nutrition platforms accelerates subscriber onboarding velocity. The FDA's evolving nutrigenetic claim guidance creates compliance preparation costs for direct-to-consumer brands. California's Bay Area hosts microbiome sequencing startups that supply algorithmic recommendation engines to national subscription services.
Germany
Licensed practitioner channels control genetic-data interpretation standards and validate premium pricing through credentialed guidance networks. The EU AI Act's proposed algorithmic transparency requirements create first-mover certification advantages for compliant platforms. Munich and Berlin clusters concentrate B2B health insurer partnerships that embed personalized nutrition into corporate benefits procurement.
United Kingdom
Post-Brexit data residency rules complicate cloud infrastructure for US-headquartered platforms serving British subscribers. The Medicines and Healthcare products Regulatory Agency scrutinizes software-as-medical-device classifications for algorithmic health recommendations. London's fintech-adjacent wellness sector attracts venture capital for subscription-model nutrition startups.
Japan
Metabolomic-informed supplementation timing commands premium pricing among aging demographics seeking preventive health optimization. The Pharmaceuticals and Medical Devices Agency maintains strict boundaries between food supplements and medical device claims. Tokyo-Osaka corridor manufacturing clusters produce strain-specific probiotic formulations for export across Asia-Pacific markets.
China
Domestic genetic testing platforms face cross-border data transfer restrictions that limit integration with international nutrition services. The National Medical Products Administration regulates health claim substantiation for DNA-based dietary recommendations. Shanghai's biotech parks incubate microbiome analytics startups serving state-backed hospital prevention programs.
Personalized Retail Nutrition and Wellness Market Vendor Landscape
Concentration sits with diversified nutrition conglomerates and specialized microbiome diagnostics platforms. Tier-one players combine captive ingredient sourcing with algorithmic recommendation capabilities. Three archetypes dominate: legacy supplement manufacturers pivoting toward subscription models, microbiome sequencing specialists monetizing through recurring testing protocols, and licensed practitioner networks controlling genetic-data interpretation standards. Competitive moves center on strategic partnerships with employer wellness programs and preemptive regulatory certification for algorithmic health recommendations.
Within the diagnostics-specialist tier, Viome Life Sciences exemplifies microbiome sequencing depth as a competitive moat, while Nutrigenomix occupies a position within licensed practitioner channel validation. Bayer AG anchors the pharmaceutical-conglomerate archetype with established regulatory affairs infrastructure that accelerates compliance navigation.
| Leading Market Players |
|---|
| Nature's Lab |
| Cargill, Incorporated |
| Nature's Bounty |
| Bayer AG |
| PlateJoy LLC |
| Viome Life Sciences, Inc. |
| Noom, Inc. |
| Nutrigenomix |
| DNAfit (Prenetics Global) |
| Others |
Supply Flow & Price Mechanics
Cold-chain capacity utilization rates above eighty percent in United States distribution hubs compress margin buffers for small-batch probiotic formulators while elevating price floors for live-culture meal kits. Scale advantages in ambient supplement manufacturing concentrate pricing power among diversified nutrition conglomerates with captive botanical extraction facilities.
Pricing Analysis
Health enthusiasts anchor subscription pricing power through quarterly microbiome retesting protocols that trigger formula adjustments. Three-tier pricing structure across premium, standard, and economy levels separates strain-level customized probiotics from generic shelf-stable alternatives. Cost compression in entry-tier supplements intensifies as employer wellness mandates expand procurement volume. Casual consumers exhibit highest price sensitivity, while athletes pay least attention to per-unit costs when metabolomic timing validation is bundled.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for strain-specific probiotic cultures sourced from Tokyo-Osaka manufacturing clusters. Traceable botanical extract supply concentrates in India, China, and select Mediterranean cultivation regions. Raw material dependencies include cold-chain live-culture fermentation bases, certified organic botanical substrates, and HIPAA-compliant genetic testing consumables. Single-source vulnerability in microbiome sequencing reagents threatens formulation continuity. Distribution runs through direct-to-consumer platforms with algorithmic auto-replenishment triggering quarterly shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription auto-replenishment with biometric-triggered formula adjustments expands recurring-revenue attachment faster than one-time supplement purchases. Service-layer monetization through licensed practitioner consultations deepens customer lifetime value beyond hardware-equivalent product margins.
For Market Incumbents: Consolidate microbiome sequencing capabilities through captive laboratory partnerships that reduce per-test cost structures. Lock in long-term supply agreements for traceable botanical extracts before harvest volatility intensifies. Bayer AG's regulatory affairs infrastructure offers a template for preemptive FDA software-as-medical-device certification that delays competitive entry.
For New Entrants and Emerging Players: Differentiate on continuous glucose monitoring integration that replaces marketing claims with real-time metabolic feedback loops. Target diet-conscious individuals in employer-sponsored wellness programs as the most penetrable segment with established procurement pipelines. Embed into HR benefits platforms through outcomes-based contracting that shares insurance premium reductions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among microbiome diagnostics platforms with quarterly retesting protocols that sustain subscription velocity. Five-to-ten year viability favors consolidated data architectures combining genomic, microbiome, and metabolomic datasets over point-solution vendors facing procurement consolidation. Monitor FDA enforcement clarity on nutrigenetic health claims as the critical inflection signal for marketing investment recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Sequencing Depth Expansion | Viome Life Sciences leverages gut-health analytics precision that generic probiotics cannot match. |
| Licensed Practitioner Channel Control | Nutrigenomix validates premium pricing through credentialed genetic-data interpretation standards in Germany. |
| Employer Wellness Program Embedding | Corporate benefits procurement pipelines reduce customer acquisition costs for biometric monitoring vendors. |
| Cold-Chain Logistics Infrastructure | Cargill's captive supply chains for traceable botanical extracts insulate against harvest volatility exposure. |
| Regulatory Pre-Certification Investment | FDA software-as-medical-device feedback accelerates product launch timelines for algorithmic recommendation engines. |
Methodological Framework
Operator-level perspectives from genetic testing laboratory directors, licensed nutrition practitioners, employer benefits procurement managers, and cold-chain logistics coordinators anchored the qualitative base. Primary interview findings combined with secondary validation from FDA nutrigenomic guidance documents, HIPAA compliance frameworks, EU AI Act proposal texts, and continuous glucose monitoring device regulatory filings. Bottom-up subscription revenue modeling triangulated against top-down personalized nutrition market sizing across product type, customer motivation, and channel economics dimensions.
Sensitivity analysis tested forecast outputs against variable adoption rates for DNA-based meal planning and microbiome retesting protocol penetration. Segmentation dimensions modeled include product formulation tier, customer health optimization maturity, distribution channel digital intensity, and service architecture recurrence structure. CAGRs derived from algorithmic projection of biometric monitoring device shipments, genetic testing kit volumes, and subscription auto-replenishment cohort retention curves across the analysis window. Employer wellness mandate expansion and EU AI Act certification timelines served as scenario-dependent inputs.
Material uncertainties — FDA software-as-medical-device classification delays, GDPR cross-border biometric data residency enforcement, and genetic counselor workforce scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory clarity timelines and HIPAA-compliant data portability continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Weight Management Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Yoga Market
Health and Wellness
GCC Weight Loss Market