
 Europe Weight Management Market | 2026-2036
Europe Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Weight Management Market Intelligence
Aftermarket service revenue from connected fitness devices is fragmenting as hardware margins compress and subscription models proliferate. Novo Nordisk A/S dominates the pharmaceutical intervention segment with its GLP-1 receptor agonist portfolio. Glanbia plc leverages its dairy-derived protein science to anchor the meal replacement category across Northern European markets.
Europe weight management encompasses clinically validated and consumer-oriented interventions designed to reduce adiposity, improve metabolic markers, and sustain behavioral modification through calibrated caloric deficit, physical activity prescription, and pharmacological or surgical adjuncts. The field integrates body composition analytics, macronutrient engineering, and digital adherence monitoring to deliver measurable health outcomes for individuals with overweight or obesity classifications. Meal replacements command the largest revenue share within product type segmentation due to their convenience positioning and clinical endorsement, while online retail channels are displacing traditional health stores as the primary fulfillment pathway for repeat-purchase supplement buyers. Behavioral therapy applications are expanding fastest within the professional service layer, driven by employer wellness mandates and national diabetes prevention frameworks.
The EU Medical Device Regulation and EFSA health claims framework govern product positioning and market access across member states, with national regulators such as Germany's BfArM and France's ANSM enforcing pharmacovigilance standards for prescription anti-obesity therapies. REACH compliance additionally constrains formulation chemistry for topical and ingestible products manufactured or distributed within the European Economic Area. Stakeholders must monitor reimbursement list revisions by statutory health insurers in Germany, France, and the Netherlands to anticipate which intervention categories will capture institutional procurement budgets.
Market Dynamics
GLP-1 receptor agonist adoption is compressing demand for traditional meal replacement and fitness hardware categories across European healthcare systems. Germany's statutory health insurance reimbursement expansion for physician-supervised obesity treatment is accelerating pharmaceutical intervention while constraining consumer wellness device procurement budgets.
Growth Catalysts
- EU Medical Device Regulation:MDR compliance mandates for connected fitness equipment are elevating safety documentation standards, filtering out marginal suppliers and consolidating procurement toward certified manufacturers with established quality management systems.
- Employer wellness mandates:National diabetes prevention frameworks in France and the Netherlands are institutionalizing behavioral therapy coverage, creating guaranteed revenue streams for digital health platforms serving corporate populations.
- Dairy-derived protein science:Advanced fractionation technologies are enabling clinical-grade meal replacement formulations with superior amino acid profiles, securing endorsement from hospital nutrition committees and statutory insurers.
Market Restraints
- REACH compliance costs:ECHA chemical safety documentation requirements for topical and ingestible products are inflating formulation development timelines and excluding smaller supplement manufacturers from the European Economic Area.
- Pharmaceutical supply concentration:Denmark-based GLP-1 production capacity constraints are creating allocation bottlenecks for German and French prescribing networks, delaying patient access to reimbursed obesity therapies.
- Hardware margin compression:Subscription model proliferation for connected fitness platforms is eroding upfront equipment profitability, forcing manufacturers to absorb customer acquisition costs over extended payback periods.
Strategic Opportunities
- Poland and Czech Republic:Private health insurance penetration is accelerating faster than statutory reimbursement expansion, creating premium-priced direct-pay markets for telemedicine-guided weight management programs.
- Behavioral therapy applications:Integration of cognitive behavioral therapy protocols with continuous glucose monitoring data is opening reimbursement pathways under national diabetes prevention frameworks in the Netherlands.
- EFSA health claims framework:Validated satiety and metabolic health claims are enabling clinical positioning for functional food ingredients, differentiating premium meal replacement products from commodity protein supplements.
Industry Challenges
- Pharmacovigilance expertise:Germany's BfArM and France's ANSM are intensifying post-market surveillance requirements for prescription anti-obesity therapies, creating talent scarcity for qualified safety data management professionals.
- Legacy system integration:Hospital nutrition departments are struggling to interface digital adherence monitoring platforms with existing electronic health record architectures, delaying deployment of integrated care pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Weight Management Market |
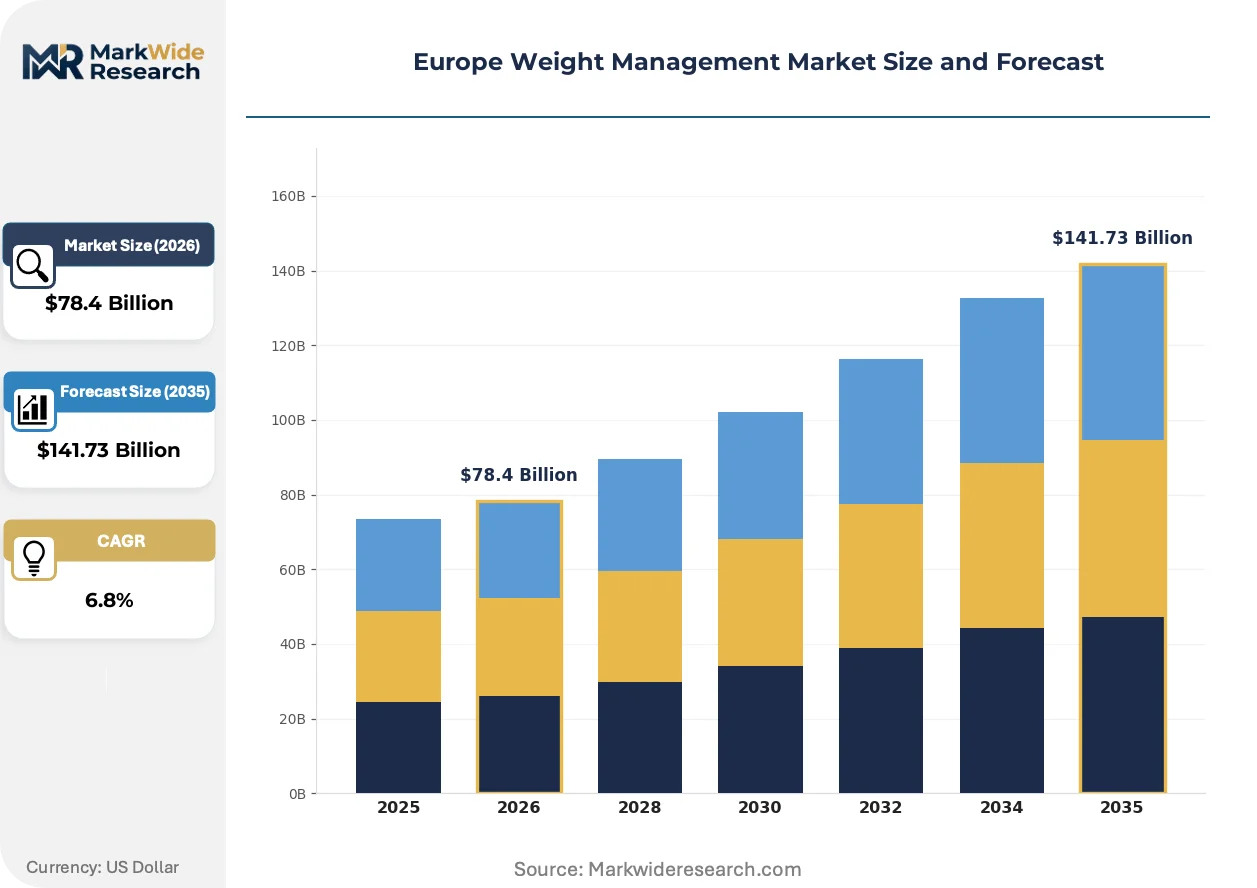
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weight Loss Supplements, Meal Replacements, Fitness Equipment, Weight Loss Programs Application: Behavioral Therapy, Dietary Management, Fitness Training, Nutritional Counseling Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Customer Type: Adults, Adolescents, Seniors, Fitness Enthusiasts |
| Companies Covered | Novo Nordisk A/S, Glanbia plc, Herbalife Nutrition, General Nutrition Centers, Amway Corp., Eli Lilly and Company, AstraZeneca, Nestlé S.A., The Hut Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Weight Management Market Strategic Shifts & Innovations
Continuous glucose monitoring integration with personalized nutrition algorithms is collapsing the boundary between medical device and consumer wellness categories. Regulatory frameworks and reimbursement policies are racing to catch up with this convergence.
Continuous glucose monitoring sensors paired with AI-driven macronutrient recommendations are collapsing the distinction between prescription diabetes management and consumer weight optimization. Dutch employer wellness programs and German statutory insurance pilot schemes are adopting these hybrid systems at accelerating rates. The technology is collapsing hardware margins for standalone fitness trackers while elevating data platform subscription values.
EFSA's evolving health claims substantiation requirements are tightening evidentiary standards for weight management product positioning across member states. Manufacturers must now generate human intervention studies for satiety and metabolic benefit claims, eliminating reliance on compositional arguments. Meal replacement and functional food categories face the steepest compliance burdens, with several legacy brands withdrawing unsupported claims from packaging.
Statutory insurer procurement is consolidating toward outcome-validated program providers, displacing open-access wellness subscriptions. Germany's DiGA fast-track approval pathway for digital health applications is channeling reimbursement toward platforms demonstrating HbA1c reduction in real-world evidence studies. This behavioral shift concentrates demand among clinically validated service models and marginalizes consumer-facing fitness applications lacking physician oversight integration.
Europe Weight Management Market Segmentation
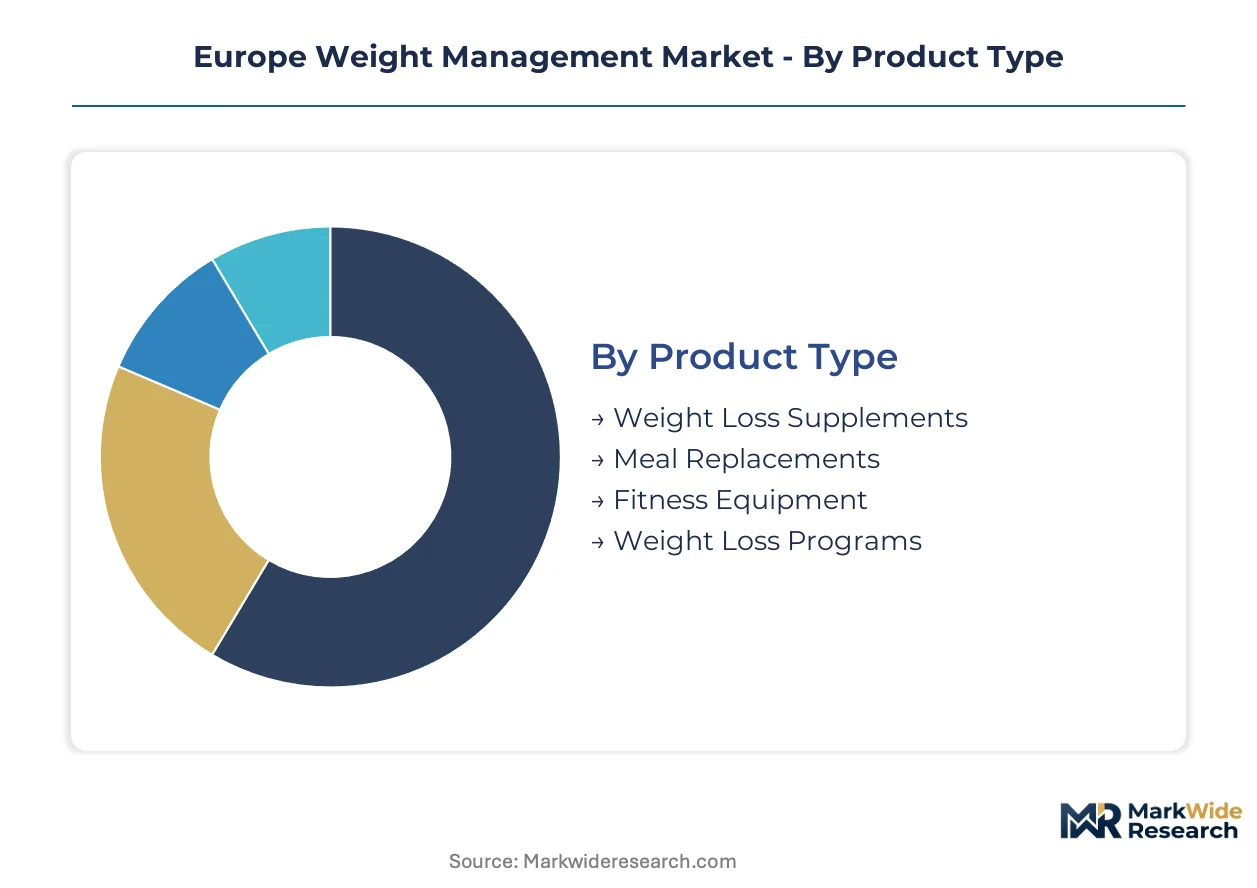
Segmentation in the Europe weight management market reveals how reimbursement policies, digital channel migration, and demographic health burdens reshape procurement patterns across member states. Understanding these divides exposes where statutory insurance budgets concentrate versus where direct-pay premiums sustain margin.
Product Type:
The use-case spectrum spans acute pharmaceutical intervention through sustained behavioral modification, with each product category serving distinct patient journeys and reimbursement pathways.
- Meal Replacements:Clinical-grade formulations leverage advanced dairy protein fractionation to deliver complete amino acid profiles validated by hospital nutrition committees. Demand concentrates in Germany where statutory health insurance reimbursement policies increasingly cover structured weight loss programs, though GLP-1 receptor agonist adoption is compressing growth trajectories.
- Fitness Equipment:Connected devices with continuous glucose monitoring integration are collapsing boundaries between medical device and consumer wellness categories. German and Dutch procurement budgets are shifting toward these hybrid systems while standalone hardware margins erode under subscription model proliferation.
- Weight Loss Supplements:EFSA health claims substantiation requirements are eliminating compositional arguments and forcing human intervention studies for satiety claims.
- Weight Loss Programs:Physician-supervised obesity treatment protocols are capturing statutory insurance reimbursement expansion across France and the Netherlands.
The dominant share belongs to meal replacements, while fitness equipment is closing the gap fastest through continuous monitoring integration.
Application:
Cost tier differentiation separates reimbursed clinical services from direct-pay wellness subscriptions, with employer mandates blurring the boundary.
- Behavioral Therapy:Cognitive behavioral therapy protocols integrated with continuous glucose monitoring data are opening reimbursement pathways under national diabetes prevention frameworks. Dutch employer wellness programs and German statutory insurance pilot schemes are adopting these platforms at accelerating rates.
- Dietary Management:AI-driven macronutrient recommendations paired with sensor data are elevating platform subscription values while collapsing margins for standalone tracking hardware.
- Fitness Training:Digital adherence monitoring platforms struggle to interface with hospital electronic health record architectures, delaying integrated care pathway deployment.
- Nutritional Counseling:Telemedicine-guided delivery is expanding fastest in Poland and Czech Republic where private health insurance penetration outpaces statutory reimbursement growth.
Behavioral therapy commands the premium tier through employer mandate coverage, while nutritional counseling expands most quickly via private insurance channels.
Distribution Channel:
Volume concentration tracks digital migration patterns, with repeat-purchase supplement buyers abandoning traditional health stores for platform-direct fulfillment.
- Online Retail:Subscription models for connected fitness platforms and meal replacement auto-delivery are displacing traditional health stores as the primary fulfillment pathway. E-commerce penetration is highest in Northern European markets with mature digital payment infrastructure.
- Pharmacies:GLP-1 receptor agonist distribution and prescription anti-obesity therapies are concentrating procurement through Germany's BfArM-supervised channels and France's ANSM-regulated networks.
- Supermarkets:Functional food positioning with EFSA-validated satiety claims is differentiating premium meal replacement products from commodity protein supplements.
- Health Stores:Legacy supplement retail is contracting as REACH compliance costs exclude smaller manufacturers from the European Economic Area.
Online retail has captured volume leadership, while pharmacies are climbing fastest on pharmaceutical intervention expansion.
Customer Type:
Maturity-based segmentation aligns with metabolic disease burden and reimbursement eligibility across European healthcare systems.
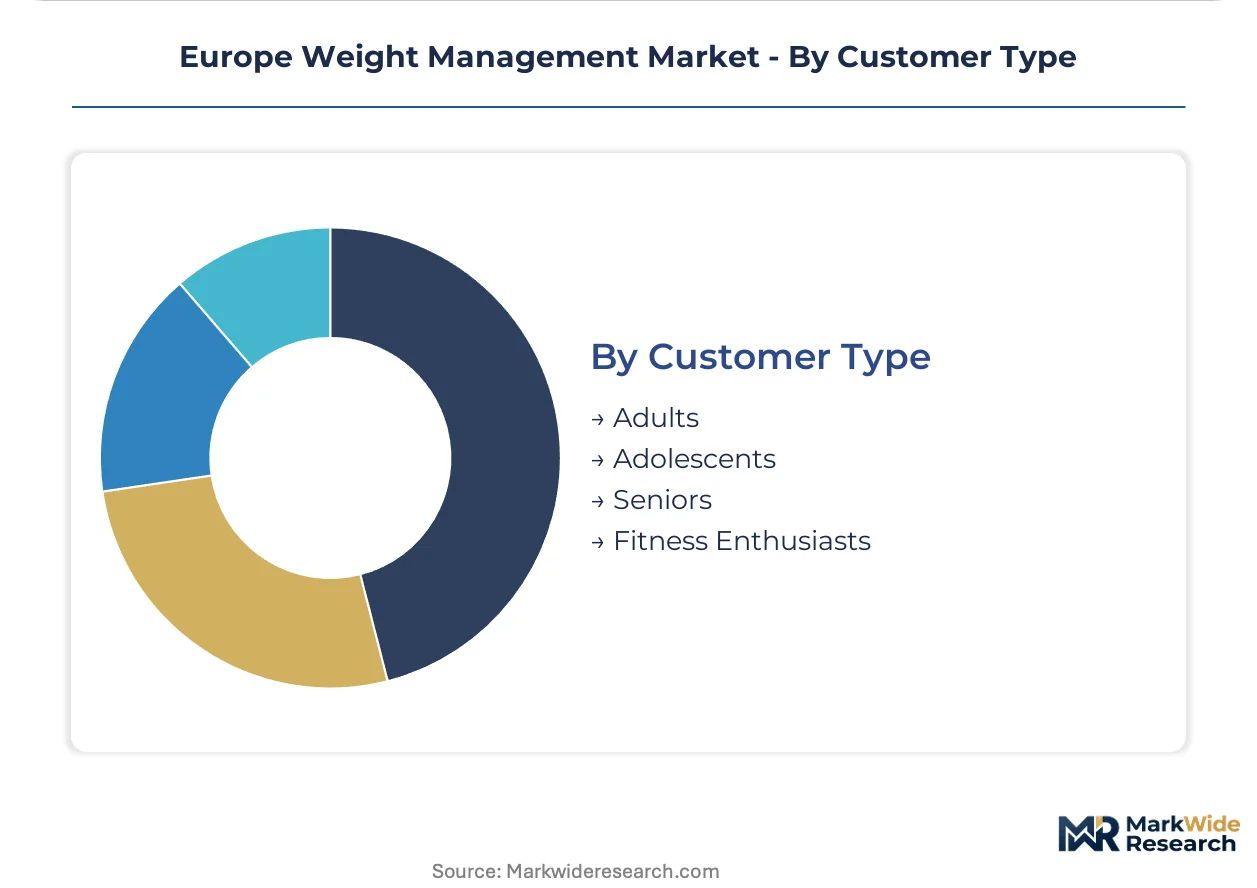
- Adults:Physician-supervised obesity treatment with pharmaceutical-grade appetite suppressants is gaining traction among adult patient populations seeking reimbursed interventions. Germany's statutory health insurance policies are accelerating this segment's institutional procurement.
- Seniors:Hospital nutrition committee endorsements for clinical-grade meal replacements are concentrating demand among polypharmacy populations with diabetes comorbidities.
- Fitness Enthusiasts:Connected fitness hardware adoption is fragmenting as subscription models proliferate and upfront equipment profitability erodes.
- Adolescents:Pediatric obesity protocols remain underdeveloped in statutory reimbursement frameworks across most member states.
Adults retain the dominant share through reimbursement expansion, while seniors are gaining share fastest on clinical validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity across European weight management markets diverges sharply between statutory reimbursement corridors and direct-pay private channels. German statutory health insurance absorbs substantial patient costs for physician-supervised interventions, while Polish and Czech consumers bear fuller out-of-pocket burdens for comparable services. This elasticity gap is reshaping where multinational suppliers deploy premium versus value-tier offerings.
Germany
Statutory health insurance reimbursement expansion for structured weight loss programs drives institutional procurement concentration. BfArM pharmacovigilance standards intensify post-market surveillance requirements for prescription anti-obesity therapies. The Cologne-Düsseldorf corridor anchors pharmaceutical distribution networks serving prescribing physicians across North Rhine-Westphalia.
France
ANSM-regulated channels concentrate GLP-1 receptor agonist distribution through hospital and retail pharmacy networks. National diabetes prevention frameworks institutionalize employer wellness mandates for behavioral therapy coverage. The Paris-Saclay cluster hosts digital health platform development integrating continuous glucose monitoring with cognitive behavioral protocols.
Netherlands
Employer wellness program adoption accelerates fastest among mid-sized enterprises seeking guaranteed reimbursement pathways. Integration of DiGA fast-track approval standards channels procurement toward platforms demonstrating HbA1c reduction in real-world evidence studies. The Eindhoven-Tilburg axis concentrates connected fitness hardware engineering talent.
Poland
Private health insurance penetration outpaces statutory reimbursement expansion, creating premium-priced direct-pay markets for telemedicine-guided programs. EFSA health claims substantiation requirements filter functional food positioning for meal replacement products. Warsaw anchors domestic distribution networks serving emerging private clinic chains.
United Kingdom
NHS procurement consolidation favors outcome-validated program providers over open-access wellness subscriptions. MHRA medical device regulations align with EU MDR standards for connected fitness equipment safety documentation. The Cambridge-Oxford corridor concentrates body composition analytics startups serving hospital nutrition committees.
Europe Weight Management Market Key Industry Players
Pharmaceutical-grade intervention specialists and dairy-derived nutrition science providers split the market into distinct capability domains. Consolidation pressures concentrate procurement toward manufacturers with established quality management systems and regulatory dossier depth. Three archetypes dominate: GLP-1 receptor agonist developers, clinical-grade meal replacement formulators, and digital adherence platform operators. Competitive maneuvering centers on strategic partnerships with statutory insurers and portfolio diversification into hybrid medical-consumer device categories.
Within the pharmaceutical intervention tier, Novo Nordisk A/S and Eli Lilly and Company occupy positions exemplifying receptor agonist development concentration. Glanbia plc anchors dairy-derived protein science capabilities for Northern European meal replacement markets. Among digital platform operators, The Hut Group represents the direct-to-consumer fulfillment archetype displacing traditional health store channels. These named entities illustrate how regulatory compliance depth and reimbursement pathway access determine sustainable market presence.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Glanbia plc |
| Herbalife Nutrition |
| General Nutrition Centers |
| Amway Corp. |
| Eli Lilly and Company |
| AstraZeneca |
| Nestlé S.A. |
| The Hut Group |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp freight corridor shapes cost dynamics across European weight management supply chains, concentrating pharmaceutical distribution through Germany's North Rhine-Westphalia while compressing logistics margins for meal replacement manufacturers serving price-sensitive Polish and Czech direct-pay markets. This corridor's container throughput costs differentiate premium clinical-grade formulations from commodity supplements downstream.
Pricing Analysis
Aftermarket service revenue from extended warranty and calibration contracts drives lifetime value for connected fitness hardware manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates DiGA-certified platforms with statutory reimbursement from direct-to-consumer wellness subscriptions. Pricing pressure stems from GLP-1 receptor agonist adoption compressing demand for traditional meal replacements. Statutory-insured adult patients exhibit lowest price sensitivity, while fitness enthusiasts in private-pay markets demonstrate highest elasticity.
Supply Chain Analysis
Supplier-financing through extended payment terms dominates procurement relationships between dairy protein fractionators and Northern European meal replacement formulators. Denmark anchors GLP-1 active pharmaceutical ingredient production, Ireland concentrates clinical-grade protein processing, and Netherlands hosts connected device engineering. Formulation chemistry draws from whey protein isolates, continuous glucose monitoring sensors, and cloud infrastructure. Single-source vulnerability in Danish peptide manufacturing creates allocation risk. Distribution runs through Germany's BfArM-supervised pharmacy networks and Netherlands employer wellness procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe weight management is approaching a platform-economics inflection where continuous glucose monitoring data interoperability between hospital EHR systems and consumer wellness applications determines reimbursement access. The DiGA fast-track pathway exemplifies this ecosystem shift toward clinically validated, integrated service models.
For Market Incumbents: Entrench statutory insurance relationships through backward integration into continuous glucose monitoring sensor manufacturing, securing component supply for hybrid medical-consumer devices. Deepen certification investment for EFSA-validated satiety claims to differentiate clinical-grade meal replacements from commodity protein supplements threatened by GLP-1 receptor agonist substitution. For New Entrants and Emerging Players: Build out telemedicine-guided weight management platforms targeting Poland and Czech Republic where private health insurance penetration outpaces statutory reimbursement growth. The employer wellness mandate segment in Netherlands offers most penetrable entry point through cognitive behavioral therapy protocol integration with existing diabetes prevention frameworks. For Investors and Strategic Acquirers: Digital adherence platform operators with demonstrated HbA1c reduction in real-world evidence studies represent the priority acquisition archetype for long-term viability across the 5-10 year reimbursement consolidation window. Monitor Germany's DiGA approval velocity as inflection indicator for platform-economics winner-take-most dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| DiGA Fast-Track Approval | Channels statutory reimbursement toward platforms demonstrating clinical outcomes in German pilot schemes. |
| Continuous Glucose Monitoring Integration | Collapses boundaries between prescription diabetes management and consumer weight optimization categories. |
| EFSA Health Claims Substantiation | Eliminates compositional arguments and forces human intervention studies for meal replacement positioning. |
| Backward Integration into Sensor Manufacturing | Secures component supply for hybrid devices facing hardware margin compression from subscription proliferation. |
| Employer Wellness Mandate Capture | Locks in guaranteed revenue streams through Netherlands and France national diabetes prevention frameworks. |
Research Approach
A standing panel of formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from EMA submissions, ClinicalTrials.gov, BfArM pharmacovigilance databases, and statutory insurer reimbursement list revisions. Bottom-up modeling of product-level shipments and top-down cross-check against national health expenditure data enabled triangulation.
Scenario-bracketing across regulatory approval velocity, GLP-1 supply allocation, and employer wellness mandate expansion framed the projection horizon. Segmentation dimensions modeled include product type, application, distribution channel, customer type, and national reimbursement framework cluster. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns, with inputs from continuous glucose monitoring device shipment data and meal replacement prescription volume trends.
Stress conditions across Danish API production capacity, REACH compliance cost inflation, and DiGA approval throughput were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about statutory insurance reimbursement expansion and EFSA claims substantiation timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Weight Management Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Yoga Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Europe Health and Wellness Market