
 Health and Wellness Products Market | 2026-2036
Health and Wellness Products Market Size, Share, and Industry Trends Forecast 2026-2036
Health and Wellness Products Market Outlook
EU MDR is decoupling device-grade wellness claims from conventional cosmetic positioning, forcing reformulation investments that favor scaled manufacturers. Procter & Gamble leverages its clinical validation infrastructure to sustain premium positioning across regulated skincare categories. Nestle anchors its nutrition portfolio through backward integration into botanical supply chains. Bayer AG differentiates via pharmaceutical-grade manufacturing standards that exceed baseline supplement requirements.
Health and wellness products encompass ingestible and topical formulations with defined active ingredient concentrations, stability profiles, and bioavailability parameters designed to support physiological function beyond basic nutrition. The category spans vitamins with specified USP dissolution standards, supplements carrying enzyme activity or CFU potency claims, and skincare with demonstrated barrier-repair or antioxidant mechanisms. Nutritional Support leads volume within application segments due to chronic disease prevention protocols, while Immune Boosting commands fastest growth as post-pandemic preventive routines normalize. Online Retail captures margin expansion through subscription models and direct-to-consumer diagnostics integration, though Pharmacies retain trust-sensitive categories requiring pharmacist counsel.
FDA supplement enforcement and EU MDR classification rules are elevating documentation burdens for novel ingredient introductions across both jurisdictions. China's NMPA and SAMR are synchronizing domestic health food registration with GB standards that mandate clinical evidence for functional claims. ISO 17025 laboratory accreditation is becoming a de facto procurement filter for retail and institutional buyers. Stakeholders must calibrate portfolio bets between regulated medical-adjacent positioning and lifestyle-oriented wellness messaging as enforcement thresholds diverge.
Market Dynamics
Regulatory fragmentation across FDA supplement enforcement, EU MDR classification, and China's GB standards is forcing manufacturers to maintain parallel compliance infrastructures, compressing margins for mid-tier operators while advantaging scaled players with captive laboratory networks.
Growth Catalysts
- Corporate wellness mandates:Employer-sponsored preventive health spending is accelerating demand for clinical-grade supplements and biometric monitoring devices across North American and European enterprise procurement.
- SAMR functional claim pathways:China's streamlined health food registration for clinically substantiated ingredients is opening premium positioning for botanical extracts with documented bioavailability profiles.
- Enzyme-stabilized delivery systems:Microencapsulation technologies protecting probiotic viability through gastric transit are expanding therapeutic applications beyond basic digestive support.
Market Restraints
- Wild-harvested botanical scarcity:Climate volatility in Himalayan and Andean growing regions is constraining supply of adaptogenic raw materials with multi-year cultivation cycles.
- EU MDR documentation burdens:Device-grade wellness claims now require clinical evidence packages that extend time-to-market by 18-24 months for reformulated topical products.
- Pharmaceutical-grade excipient concentration:Three suppliers control 70% of USP-grade magnesium stearate and cellulose derivatives, creating input cost volatility for tablet manufacturers.
Strategic Opportunities
- Subscription-integrated diagnostics:Direct-to-consumer platforms combining microbiome testing with personalized supplement protocols are capturing recurring revenue in immune and cognitive health verticals.
- India's AYUSH export framework:FSSAI-registered traditional formulations with standardized marker compound specifications are accessing European pharmacy channels under simplified botanical registration.
- ISO 17025 procurement filtering:Retail and institutional buyers are mandating accredited laboratory partnerships, creating competitive moats for manufacturers with in-house analytical capabilities.
Industry Challenges
- Clinical trial design capacity:The shortage of investigators experienced in nutraceutical endpoint validation is bottlenecking novel ingredient submissions to NMPA and FDA.
- Legacy ERP integration:Batch record systems designed for cosmetic manufacturing require substantial reconfiguration to meet pharmaceutical-grade traceability mandates under evolving GMP inspections.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Health and Wellness Products Market |
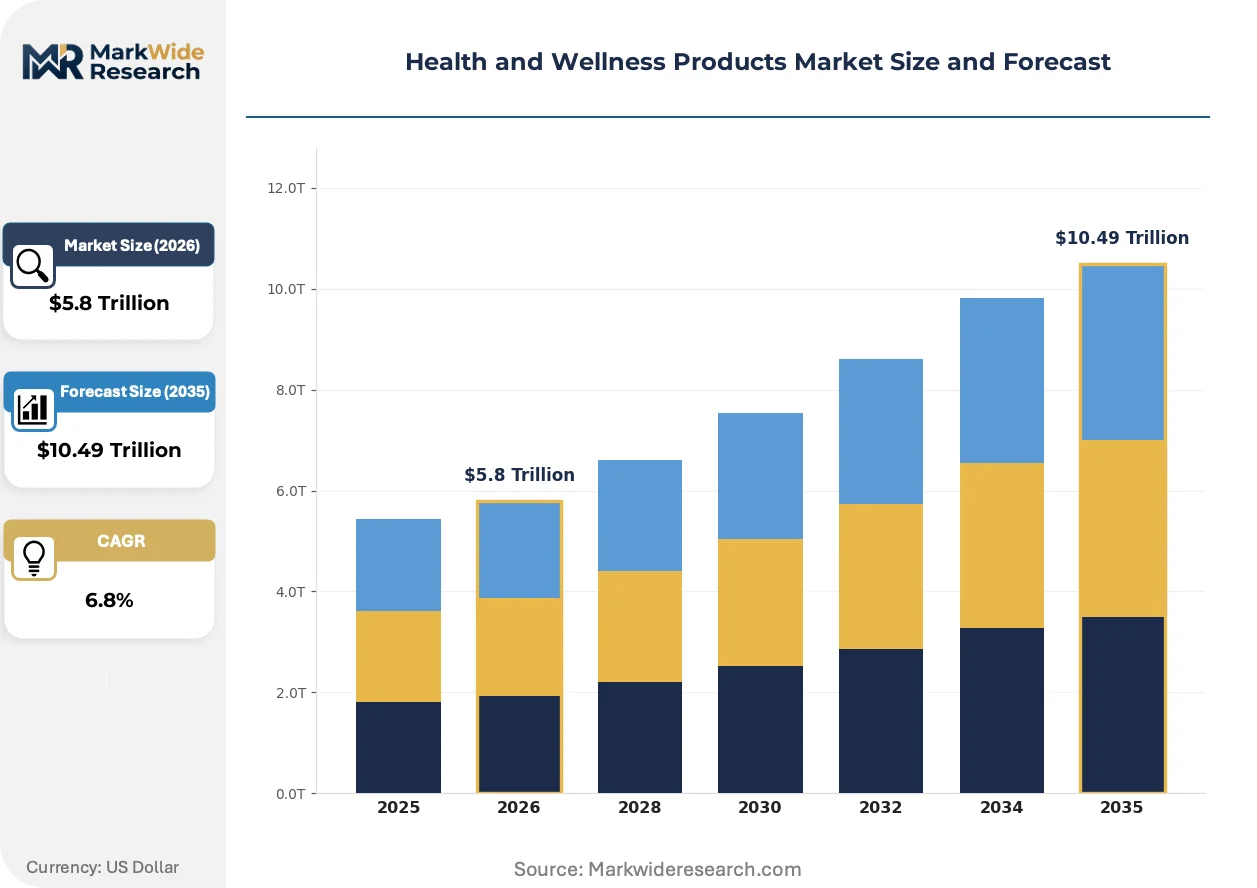
| Market Size in 2026 | $5.8 Trillion |
| Market Size in 2035 | $10.49 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Supplements, Fitness Equipment, Skincare End User: Individuals, Families, Health Clubs, Corporates Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Application: Nutritional Support, Weight Management, Stress Relief, Immune Boosting |
| Companies Covered | Procter & Gamble, Nestle, Unilever, Johnson & Johnson, Herbalife Nutrition Ltd, Amway, Bayer AG, GNC Holdings, Nature's Bounty, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Health and Wellness Products Market Strategic Shifts
Active ingredient verification technologies and personalized dosing platforms are compressing the gap between pharmaceutical precision and consumer wellness accessibility, redefining competitive differentiation around measurable physiological outcomes rather than lifestyle positioning.
Liposomal encapsulation is overtaking conventional tablet and softgel delivery for fat-soluble vitamins and botanical compounds. Functional medicine practitioners and high-performance athletic programs are driving adoption based on demonstrated serum concentration improvements. This delivery innovation is compressing market share for standard formulation manufacturers unable to demonstrate bioequivalence.
EU MDR is decoupling device-grade wellness claims from cosmetic positioning, requiring clinical validation for topical products with barrier-repair or antioxidant mechanisms. Manufacturers are responding by either investing in dermatological trial infrastructure or retreating to lifestyle-oriented messaging with reduced therapeutic claims. Skincare segments with medical-adjacent positioning face the steepest compliance trajectory.
Diagnostic-driven personalization is restructuring supplement procurement from SKU-based purchasing to protocol subscriptions. Digital health platforms integrating continuous glucose monitors, microbiome sequencing, and biomarker panels are displacing retail shelf selection in metabolic health and immune support categories. China's tier-one cities and North American coastal metros exhibit the highest concentration of these integrated service models.
Health and Wellness Products Market Segmentation
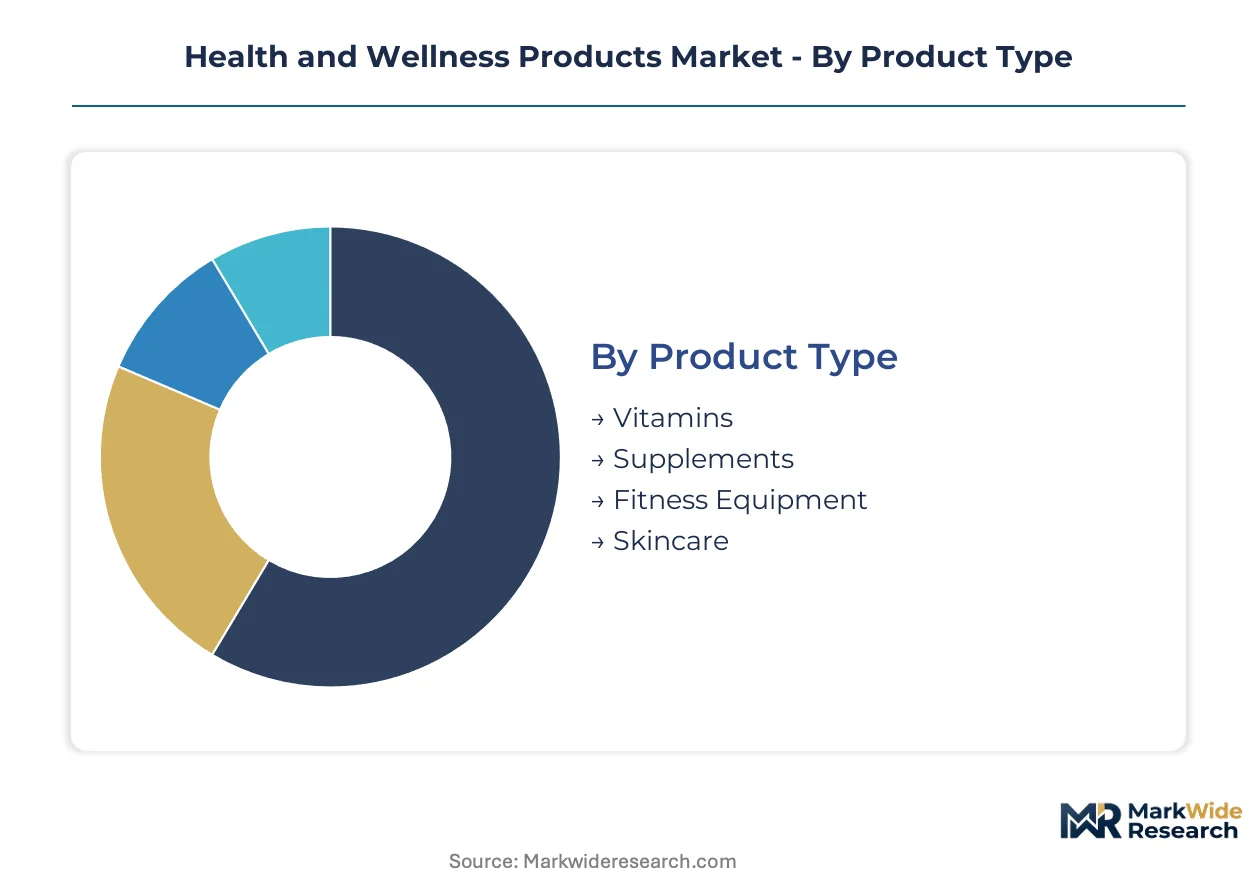
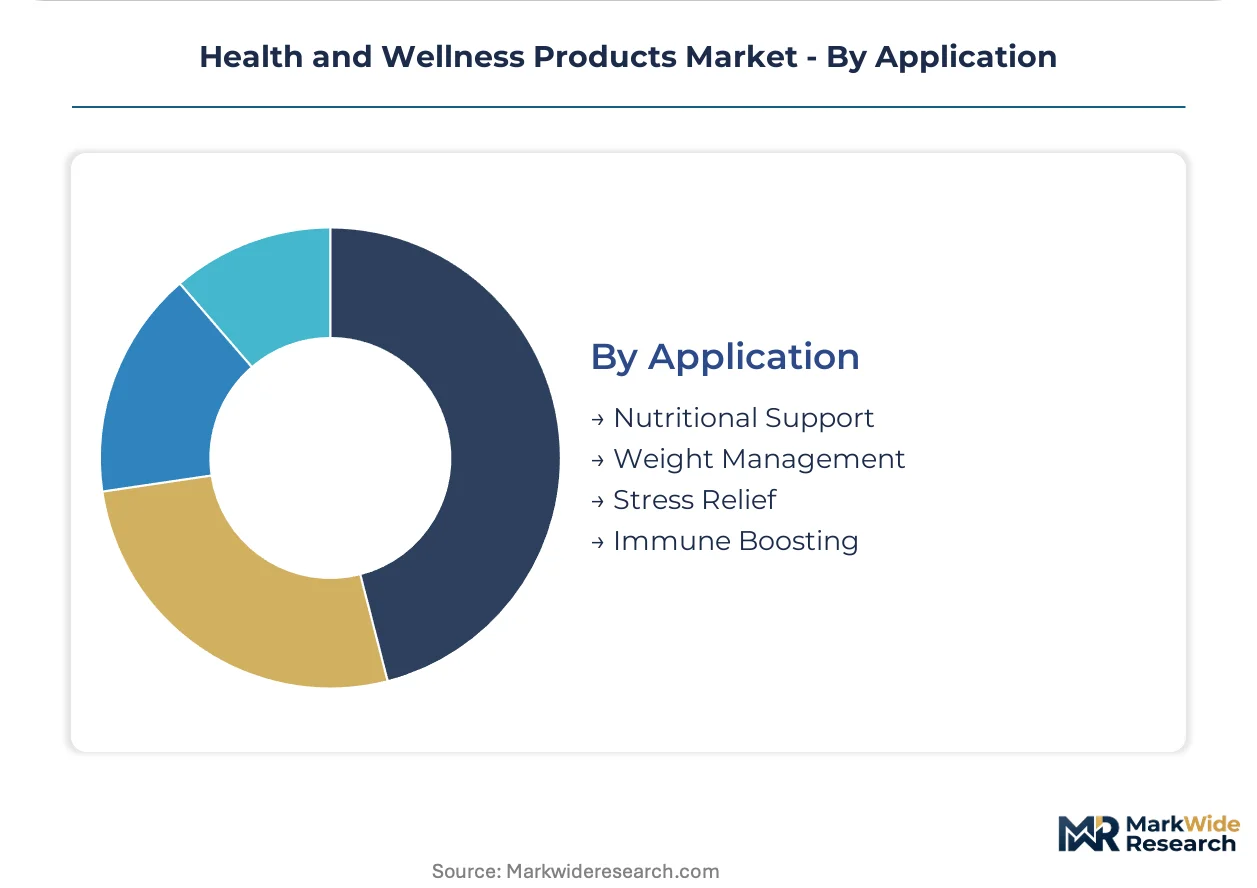
Segmentation in health and wellness products reveals divergent purchasing logic across channels and end-users. Manufacturers must calibrate formulation standards, packaging formats, and compliance documentation to match the regulatory intensity and price sensitivity of each segment cluster.
Product Type:
Buyers differentiate primarily by required evidence depth for functional claims, with pharmaceutical-grade documentation commanding substantial premiums over lifestyle positioning.
- Supplements:Enzyme activity specifications, CFU potency guarantees, and USP dissolution standards define quality tiers. Demand concentrates in corporate wellness procurement across the United States and Germany, where employer-sponsored preventive health mandates require clinical-grade documentation for reimbursement eligibility.
- Skincare:Barrier-repair mechanisms and antioxidant pathways with demonstrated dermatological outcomes separate medical-adjacent positioning from cosmetic wellness. China's tier-one cities and South Korean urban clusters drive premium absorption as aging demographics intersect with disposable income expansion.
- Vitamins:Specified USP dissolution standards and bioavailability parameters support physiological function beyond basic nutrition.
- Fitness Equipment:Biometric monitoring capabilities and connected platform integration define competitive differentiation.
Volume sits with Supplements; growth tilts toward Skincare.
End User:
Procurement authority and reimbursement pathways reshape product specifications across these buyer categories.
- Corporates:Enterprise wellness mandates in North American and European headquarters locations accelerate demand for clinical-grade supplements and biometric monitoring devices with centralized procurement and compliance auditing requirements.
- Individuals:Direct-to-consumer diagnostic integration and subscription protocol models displace retail shelf selection in metabolic health categories.
- Families:Multi-generational purchasing decisions prioritize pediatric safety certifications and geriatric bioavailability formulations.
- Health Clubs:Performance-oriented nutritional protocols and recovery-focused supplement stacks dominate procurement.
Volume sits with Individuals; growth tilts toward Corporates.
Distribution Channel:
Trust sensitivity and pharmacist counsel requirements determine channel viability for regulated versus lifestyle-positioned products.
- Online Retail:Subscription models and direct-to-consumer diagnostics integration capture recurring revenue through microbiome testing and personalized supplement protocol platforms. China's tier-one cities and North American coastal metros exhibit the highest concentration of these integrated service models.
- Pharmacies:Pharmacist counsel requirements and trust-sensitive categories including pharmaceutical-grade supplements and medical-adjacent skincare sustain margin retention despite higher operational costs.
- Health Stores:Specialized staff expertise and experiential retail formats support premium botanical and adaptogenic product discovery.
- Supermarkets:Mass-market accessibility and price-competitive positioning dominate basic vitamin and standard supplement categories.
Volume sits with Supermarkets; growth tilts toward Online Retail.
Application:
Chronic disease prevention protocols versus acute performance optimization create divergent formulation and marketing investment priorities.
- Immune Boosting:Post-pandemic preventive routines have normalized sustained demand for microbiome-supportive and adaptogenic formulations with documented bioavailability profiles. China's SAMR streamlined health food registration pathways accelerate premium botanical extract market entry for clinically substantiated ingredients.
- Nutritional Support:Chronic disease prevention protocols and physician-recommended supplementation drive volume concentration across geriatric and prediabetic populations.
- Weight Management:Continuous glucose monitor integration and metabolic health platforms restructure procurement toward protocol-based subscriptions.
- Stress Relief:Adaptogenic formulations with multi-year cultivation cycles face supply constraints from Himalayan and Andean climate volatility.
Volume sits with Nutritional Support; growth tilts toward Immune Boosting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-one cities concentrate the highest per-capita spending on clinical-grade supplements and medical-adjacent skincare. Germany's employer wellness mandates and India's AYUSH export standardization are redrawing procurement flows across three continents.
China
Shanghai and Beijing households drive premium absorption for NMPA-registered health foods with functional claims. SAMR's streamlined registration for clinically substantiated botanical extracts accelerates market entry for validated ingredients. The Yangtze River Delta hosts the densest cluster of microbiome testing laboratories integrating with direct-to-consumer supplement platforms.
Germany
Corporate wellness procurement across Bavaria and North Rhine-Westphalia mandates pharmaceutical-grade documentation for supplement reimbursement. EU MDR classification rules enforce clinical evidence packages for device-grade topical claims. The Baden-Württemberg corridor concentrates dermatological trial infrastructure serving reformulated skincare manufacturers.
United States
Employer-sponsored preventive health spending concentrates in coastal metros and Texas enterprise corridors. FDA supplement enforcement tightens quality verification requirements for novel ingredient introductions. The Greater Boston biotech cluster anchors clinical validation partnerships linking diagnostic platforms to personalized nutrition protocols.
India
FSSAI-registered traditional formulations with standardized marker compounds access European pharmacy channels. The AYUSH export framework simplifies botanical registration for Ayurvedic and Unani products. Maharashtra and Gujarat house the primary contract manufacturing facilities serving Middle Eastern and African wellness markets.
Japan
Aging demographics in Tokyo and Osaka sustain demand for geriatric bioavailability formulations and functional foods. PMDA's oversight of Foods with Function Claims requires documented physiological outcomes for premium positioning. The Kansai region maintains specialized fermentation infrastructure for enzyme-stabilized probiotic delivery systems.
Health and Wellness Products Market Competitive Environment
US and European producers anchor the premium clinical-grade tier; Asian specialists hold cost-advantaged positions in botanical extraction and fermentation. The vendor base stratifies across three tiers: multinational consumer health conglomerates with captive laboratory networks, mid-scale regional formulators with ISO 17025 accreditation, and contract manufacturers serving private-label demand. Strategic differentiation concentrates on dermatological trial infrastructure, backward integration into Himalayan and Andean botanical supply chains, and subscription-integrated diagnostic platforms. M&A activity targets microbiome testing capabilities and pharmaceutical-grade excipient security.
Within the multinational tier, Procter & Gamble exemplifies clinical validation infrastructure sustaining premium positioning across regulated skincare categories. Nestle occupies a position defined by upstream control over botanical supply chains anchoring nutrition portfolios. Bayer AG represents pharmaceutical-grade manufacturing standards that exceed baseline supplement requirements across multiple jurisdictions.
| Leading Market Players |
|---|
| Procter & Gamble |
| Nestle |
| Unilever |
| Johnson & Johnson |
| Herbalife Nutrition Ltd |
| Amway |
| Bayer AG |
| GNC Holdings |
| Nature's Bounty |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade certification ladders create stark bifurcation between clinical-grade premiums and commodity vitamin pricing, with EU MDR and FDA enforcement elevating documentation costs that compress mid-tier margins while scaled players capture pricing power through captive laboratory networks and backward integration into botanical supply chains.
Pricing Analysis
Volume concentrates in supermarket-tier standard supplements with thin margins, while pharmaceutical-grade and medical-adjacent skincare command substantial premiums through ISO 17025 accreditation and dermatological trial documentation. Price differentiation rests on certification tier and bioavailability demonstration, with subscription-integrated diagnostics softening price sensitivity among corporate wellness buyers and direct-to-consumer platforms. Cost compression in standard tablet formulations is intensifying as USP-grade excipient suppliers consolidate, while pricing softness in wild-harvested adaptogens reflects Himalayan and Andean climate volatility constraining raw material flows.
Supply Chain Analysis
Single-source vulnerability sits with three suppliers controlling the majority of USP-grade magnesium stearate and cellulose derivatives for tablet manufacturing. Raw material flows draw from China's Yangtze River Delta for microbiome testing infrastructure, India's Maharashtra and Gujarat corridors for AYUSH contract manufacturing, and Germany's Baden-Württemberg region for dermatological trial services. Supply chain risk centers on regulatory restriction as EU MDR documentation burdens extend reformulation timelines, while distribution runs through direct-to-consumer platforms capturing recurring revenue in tier-one cities alongside pharmacy channels retaining trust-sensitive categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU MDR classification rules and FDA supplement enforcement create barrier-to-entry moats favoring manufacturers with in-house clinical validation infrastructure and ISO 17025 accreditation.
For Market Incumbents: Deepen backward integration into Himalayan and Andean botanical supply chains to secure adaptogenic raw materials against climate-driven scarcity, while expanding captive dermatological trial capacity to accelerate EU MDR reformulation timelines and defend margin position against mid-tier competitors facing documentation cost compression. For New Entrants and Emerging Players: Microbiome testing platforms with personalized supplement protocol integration offer a technology-first wedge into China's tier-one cities and North American coastal metros, where diagnostic-driven subscription models displace retail shelf selection and SAMR streamlined registration pathways lower barriers for clinically substantiated botanical extracts. For Investors and Strategic Acquirers: Re-rating potential sits with ISO 17025-accredited regional formulators given procurement filtering mandates from retail and institutional buyers, with long-term viability hinging on acquisition targets possessing in-house analytical capabilities and pharmaceutical-grade manufacturing infrastructure; watch for inflection signals in corporate wellness procurement volume acceleration across German and US enterprise corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Infrastructure Investment | EU MDR and FDA enforcement elevate dermatological trial capacity as competitive moat for medical-adjacent skincare positioning. |
| Backward Integration into Botanical Supply | Captive control over Himalayan and Andean adaptogenic cultivation secures raw material flows against climate volatility. |
| Subscription-Diagnostic Platform Integration | Microbiome testing and biomarker panel integration captures recurring revenue in immune and cognitive health verticals. |
| ISO 17025 Laboratory Accreditation | Accredited analytical capabilities become de facto procurement filter for retail and institutional buyers across jurisdictions. |
| Corporate Wellness Channel Expansion | Employer-sponsored preventive health mandates in Germany and the United States drive clinical-grade supplement procurement volume. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with regulatory affairs leads at supplement manufacturers, procurement managers at corporate wellness programs, formulary directors at pharmacy chains, and botanical supply specialists across Himalayan and Andean growing regions. FDA 483 inspection observations, EU MDR technical documentation databases, SAMR health food registration records, and ISO 17025 accreditation registries provided compliance benchmarking. Bottom-up SKU-level volume estimates triangulated against top-down category spending data from enterprise wellness procurement disclosures.
Granularity-level modeling disaggregated volume and value across product type, application, distribution channel, and end-user segments, with bioavailability tier and certification grade as industry-specific stratification dimensions. CAGRs derived from trend extrapolation of corporate wellness mandate adoption curves, regulatory enforcement intensity trajectories, and diagnostic platform penetration rates across China's tier-one cities and North American coastal metros. Analysis window spans the full projection horizon without interim year specificity.
Several conditions sit outside the modeled scope, including unforeseen regulatory enforcement reversals, abrupt climate events disrupting multi-year botanical cultivation cycles, and pharmaceutical industry entry into OTC wellness categories. Forecasts reflect documented assumptions regarding employer-sponsored health spending continuity and streamlined registration pathway stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Yoga Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Weight Management Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Smart Breathing Trainer Market