
 Weight Management Market | 2026-2036
Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Management Market Intelligence
Registered dietitian availability is collapsing across rural health systems, creating a bottleneck that digital platforms exploit. Noom Inc. leverages behavioral psychology and AI coaching to bridge this gap, while Novo Nordisk AS anchors its position through GLP-1 receptor agonist supply chains that dominate pharmacological intervention. WW International Inc. competes by repositioning its community model toward clinical partnerships rather than pure consumer subscription.
Weight management encompasses calibrated nutritional interventions, metabolic monitoring, and behavioral modification protocols designed to achieve sustained energy balance. Formulations range from macronutrient-restricted meal replacements to peptide-based appetite suppressants, with delivery modes spanning pills, powders, bars, and ready-to-drink beverages. Dietary supplements and meal replacements occupy mature margin pools where brand trust determines repeat purchase, while weight loss apps capture the fastest expansion as smartphone penetration deepens and payer reimbursement for digital therapeutics broadens. Corporate wellness programs represent an underpenetrated customer type where annual contracts and outcomes-based pricing are displacing individual subscription models.
FDA oversees pharmaceutical obesity treatments through its Division of Metabolism and Endocrinology Products, while EMA's Committee for Medicinal Products for Human Use evaluates centralized marketing authorizations across EU member states. Both regulators now require cardiovascular outcome trials for novel anti-obesity drugs, extending development timelines and favoring incumbents with established safety databases. Stakeholders must monitor whether GLP-1 supply constraints ease before digital health platforms lose their current window to prove cost-effectiveness against pharmacotherapy.
Market Dynamics
GLP-1 receptor agonist supply chains currently dominate pharmacological weight management, reshaping competitive entry barriers as FDA cardiovascular outcome trial requirements extend development timelines for novel anti-obesity drugs.
Growth Catalysts
- Employer-Sponsored Wellness Spending:United States corporations are expanding structured weight management service procurement through annual contracts with outcomes-based pricing models.
- REACH Chemical Safety Standards:European Union regulatory clarity on metabolic monitoring device materials is accelerating market authorization timelines for connected health hardware.
- Smartphone Penetration Deepening:Mobile-first behavioral coaching platforms are capturing fastest expansion as payer reimbursement for digital therapeutics broadens across health systems.
Market Restraints
- Peptide API Supply Concentration:Active pharmaceutical ingredient manufacturing for GLP-1 agonists clusters among specialized biologics contractors in Denmark and Switzerland.
- Cardiovascular Outcome Trial Costs:FDA Division of Metabolism and Endocrinology Products mandates multi-year safety studies that favor incumbents with established databases.
- Registered Dietitian Availability Collapse:Rural health systems face acute talent shortages that constrain service delivery capacity outside metropolitan clusters.
Strategic Opportunities
- Corporate Wellness Underpenetration:Annual contracts with outcomes-based pricing are displacing individual subscription models among Fortune 500 employers.
- AI-Behavioral Psychology Convergence:Machine learning coaching layered with cognitive behavioral therapy protocols is opening reimbursement pathways through digital therapeutic classification.
- India Preventive Health Mandates:FSSAI nutritional labeling expansion and employer health insurance regulations are creating structured program demand in urban corporate centers.
Industry Challenges
- Cross-Functional Talent Scarcity:Integration of metabolic medicine, behavioral psychology, and software engineering expertise exceeds current workforce supply.
- Legacy EHR Integration Friction:Digital weight management platforms face interoperability barriers with hospital system electronic health record architectures.
- GLP-1 Supply Volatility:Manufacturing scale-up lags for injection devices and cold-chain distribution create patient access interruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Management Market |
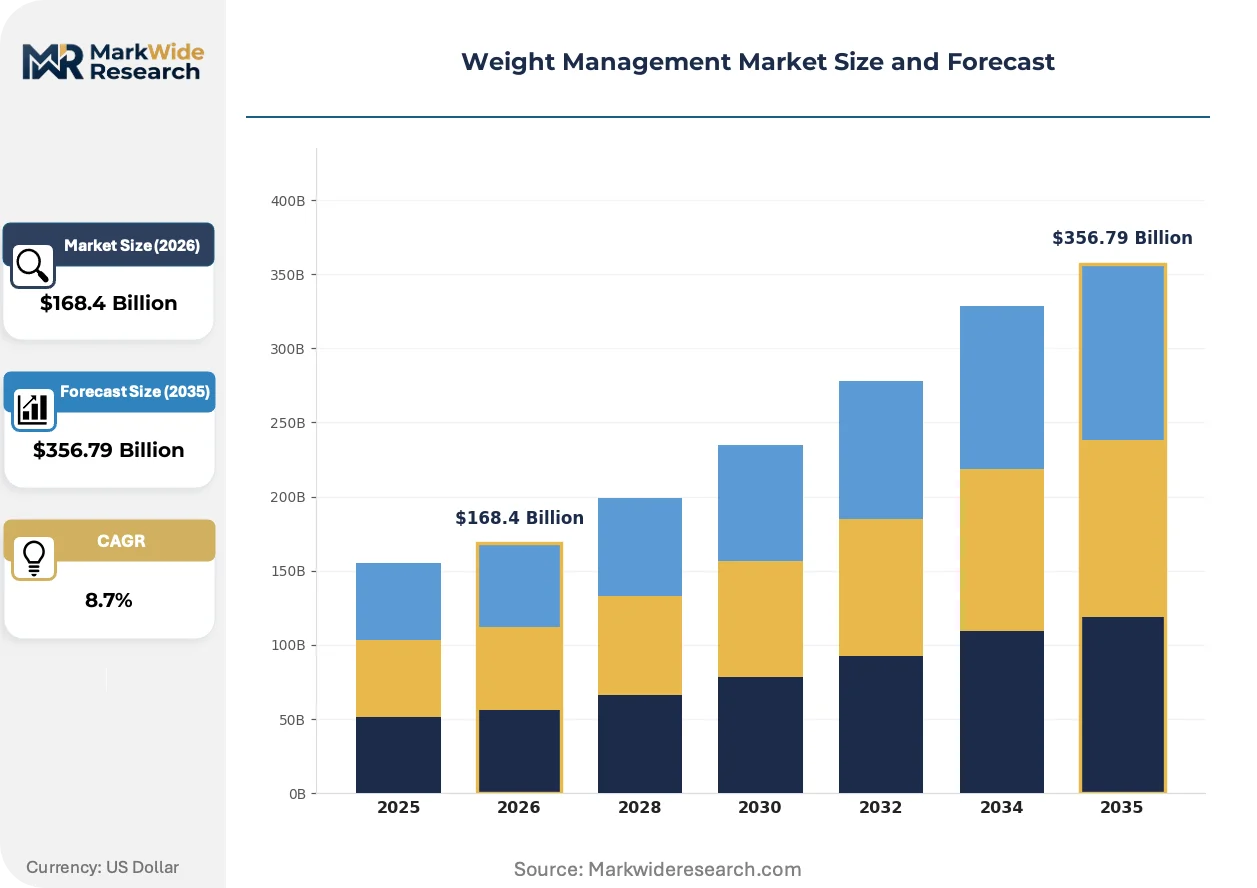
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $356.79 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacements, Low-Calorie Foods, Weight Loss Apps Customer Type: Individuals, Fitness Enthusiasts, Healthcare Providers, Corporate Wellness Programs Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies Delivery Mode: Pills, Powders, Bars, Ready-to-Drink Beverages |
| Companies Covered | Herbalife Nutrition Ltd., Nestlé Health Science, WW International Inc., Medifast Inc., Noom Inc., Nutrisystem Inc., Atkins Nutritionals Inc., Abbott Laboratories, Novo Nordisk AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Management Market Strategic Shifts & Innovations
Continuous glucose monitoring hardware is migrating from diabetes management into mainstream weight optimization, while regulatory frameworks on both sides of the Atlantic harden clinical evidence requirements for pharmacological entrants.
Peptide-based appetite suppressants are supplanting traditional macronutrient-restricted meal replacements as first-line clinical intervention. Endocrinology practices and employer health plans are adopting these formulations at accelerating velocity. This shift is compressing margin pools in mature supplement categories while expanding reimbursement complexity for pharmacy benefit managers.
EMA's Committee for Medicinal Products for Human Use now requires cardiovascular outcome trials for all novel anti-obesity drug applications across EU member states. This regulatory tightening extends development timelines by three to five years. Early-phase biotech developers are responding by prioritizing licensing partnerships with established GLP-1 safety databases over independent market entry.
Health system procurement teams are unbundling after-sales coaching from device and pharmaceutical purchases, instead contracting directly with digital therapeutic platforms for longitudinal patient support. This disintermediation compresses margins for integrated solution vendors. The pattern is most visible in United States metropolitan health systems where value-based care contracts dominate payer arrangements.
Weight Management Market Segmentation
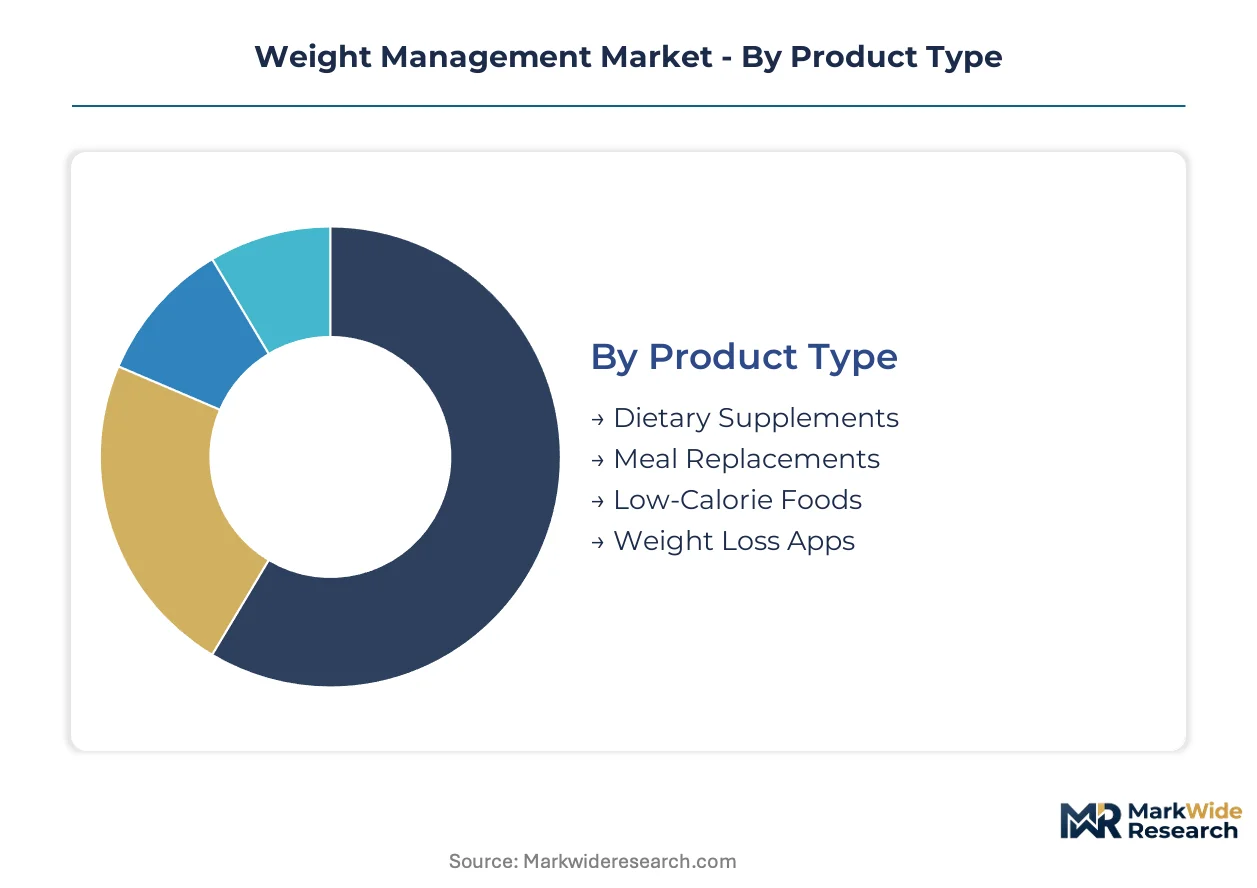
Weight management solutions fragment across product chemistry, customer procurement authority, and delivery infrastructure. Each segmentation axis carries distinct regulatory exposure and margin architecture that determines competitive positioning.
Product Type:
FDA and EMA cardiovascular outcome requirements create divergent compliance burdens across formulation categories.
- Meal Replacements:Macronutrient-calibrated formulations delivering controlled energy density through portion-engineered powders and liquids. Demand concentrates in United States corporate wellness contracts where outcomes-based pricing favors measurable caloric intervention. Supply chains source protein isolates from Midwest dairy processors and plant-based alternatives from Canadian pea protein facilities.
- Weight Loss Apps:Smartphone-native platforms integrating behavioral psychology protocols with metabolic data ingestion. United States health systems and self-insured employers drive procurement as digital therapeutic reimbursement codes expand. Machine learning coaching layers create defensible data moats against commodity hardware competitors.
- Dietary Supplements:Botanical and mineral formulations operating under DSHEA self-affirmation frameworks in the United States.
- Low-Calorie Foods:Reformulated packaged goods with reduced energy density targeting retail grocery channels.
Established volume favors meal replacements; emerging adoption favors weight loss apps.
Customer Type:
Procurement scale and contract duration separate enterprise purchasers from individual consumers.
- Corporate Wellness Programs:Fortune 500 employers contracting annual structured service agreements with outcomes-based pricing clauses. United States metropolitan health systems and self-insured corporations represent the deepest contract pipelines.
- Healthcare Providers:Endocrinology practices and integrated delivery networks prescribing pharmacological interventions alongside behavioral protocols. United States academic medical centers anchor clinical trial recruitment and GLP-1 agonist adoption curves.
- Individuals:Direct-to-consumer subscription purchasers sensitive to monthly churn and seasonal demand fluctuation.
- Fitness Enthusiasts:Performance-oriented consumers seeking body composition optimization through sport nutrition crossover products.
Contract value concentrates with corporate wellness programs; margin pressure concentrates with individual subscribers.
Distribution Channel:
Cold-chain and counseling requirements determine channel viability by product format.
- Pharmacies:GLP-1 agonist dispensing and prescription meal replacement fulfillment requiring pharmacist counseling infrastructure. United States retail pharmacy chains and hospital outpatient pharmacies capture the highest-value pharmacological transactions.
- Online Retail:Direct-to-consumer fulfillment of shelf-stable supplements and app-based service delivery bypassing physical inventory constraints.
- Supermarkets:Mass-market low-calorie packaged goods placement competing for shelf space against conventional CPG incumbents.
- Health Stores:Premium supplement positioning through specialized retail with trained staff consultation.
Prescription authorization favors pharmacies; customer acquisition efficiency favors online retail.
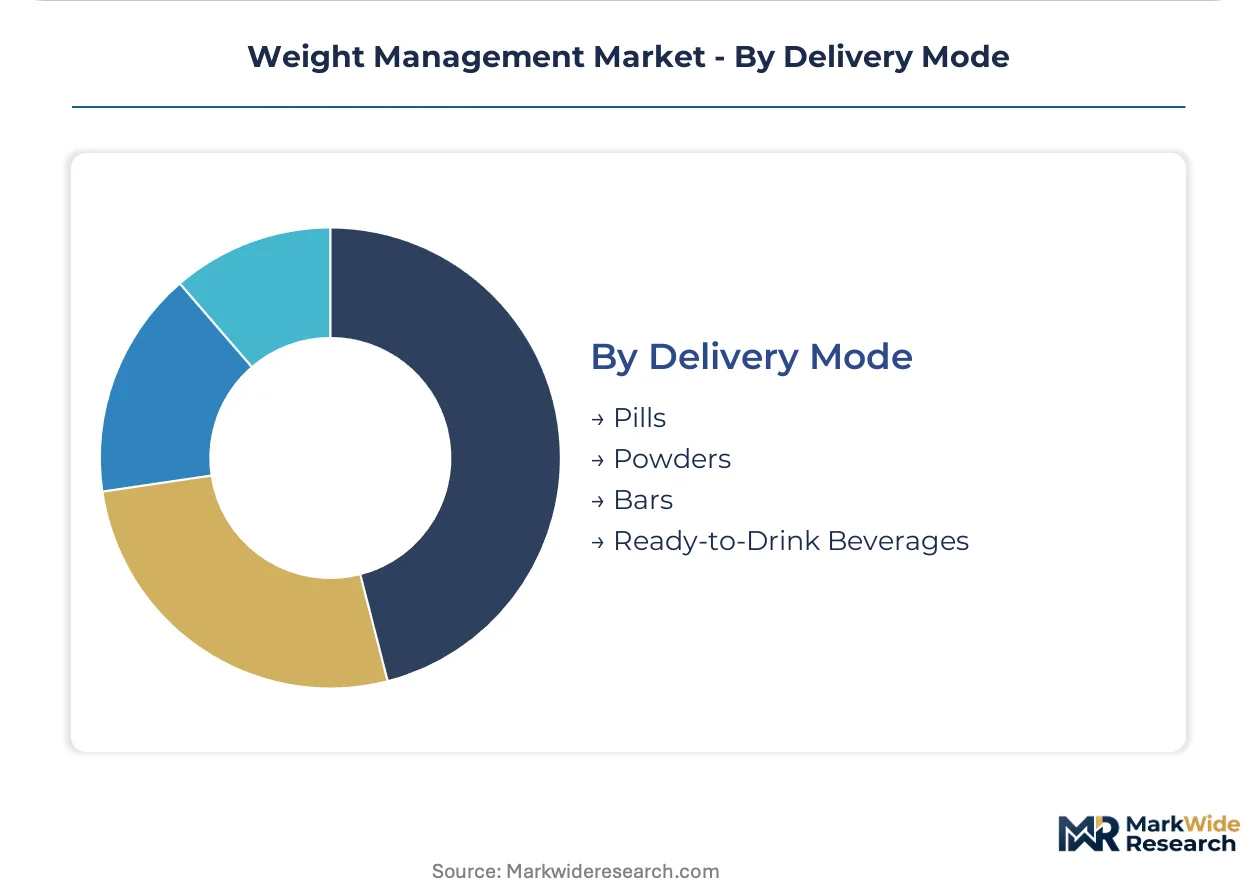
Delivery Mode:
Patient adherence and manufacturing complexity shape competitive concentration within each format.
- Pills:Oral solid dosage forms including peptide-based appetite suppressants and micronutrient complexes. FDA Division of Metabolism and Endocrinology Products oversight applies to novel anti-obesity drug entrants.
- Powders:Bulk macronutrient formulations enabling customizable dosing and flavor masking of functional ingredients.
- Bars:Shelf-stable meal replacement formats competing in convenience retail against conventional snack categories.
- Ready-to-Drink Beverages:Liquid meal replacements requiring aseptic processing and extended shelf-life engineering.
Clinical validation favors pills; consumption convenience favors ready-to-drink formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cardiovascular outcome requirements and employer-sponsored wellness spending anchor United States demand, while EMA regulatory tightening and GLP-1 manufacturing concentration shape European and Swiss market dynamics.
United States
Employer-sponsored wellness contracts and GLP-1 prescription volumes drive procurement concentration in metropolitan health systems. FDA Division of Metabolism and Endocrinology Products mandates multi-year cardiovascular safety studies that extend development timelines for novel entrants. Greater Boston and New York Metro anchor digital therapeutic platform development, with academic medical centers recruiting for outcomes-based pricing pilots.
Germany
Integrated delivery networks and statutory health insurance reimbursement frameworks sustain demand for structured weight management services. EMA Committee for Medicinal Products for Human Use requires centralized marketing authorizations with cardiovascular outcome trials for pharmacological interventions. Bavaria and North Rhine-Westphalia concentrate metabolic medicine expertise, with university hospitals in Munich and Cologne leading clinical adoption curves.
Switzerland
Specialized biologics contractors and peptide API manufacturing clusters attract pharmaceutical supply chain investment. Swissmedic oversight aligns with EMA standards while maintaining distinct national authorization pathways for metabolic monitoring devices. Basel and Zurich host concentrated GLP-1 agonist production infrastructure, with cold-chain distribution networks radiating across Alpine corridors.
India
Urban corporate centers and preventive health insurance regulations generate structured program demand among Fortune 500 subsidiaries. FSSAI nutritional labeling expansion and employer health insurance mandates reshape procurement specifications for meal replacement categories. Maharashtra and Karnataka concentrate digital health platform development, with Mumbai and Bangalore health tech clusters securing reimbursement pathway pilots.
United Kingdom
NHS integrated care systems and value-based procurement frameworks drive consolidation in behavioral coaching service contracts. MHRA post-Brexit regulatory autonomy maintains EMA-aligned cardiovascular trial requirements for novel anti-obesity pharmacology. London and Southeast England anchor health tech venture density, with academic medical centers in Cambridge and Oxford hosting digital therapeutic validation studies.
Weight Management Market Key Industry Players
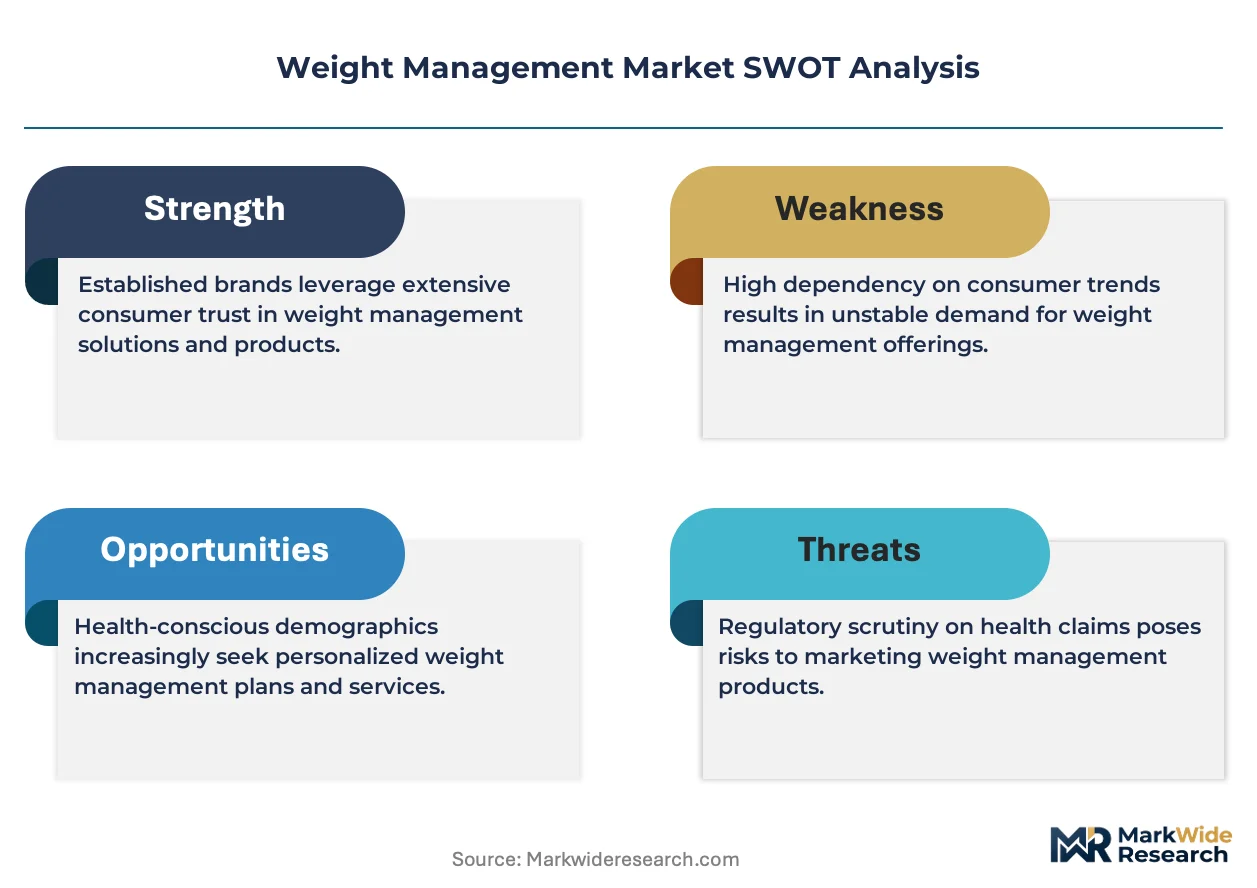
Technology leadership and cost leadership are held by different player archetypes, with GLP-1 manufacturers commanding pharmacological segments and digital platforms capturing behavioral intervention growth. The vendor base separates into three strategic tiers: pharmaceutical incumbents with established safety databases, AI-native coaching platforms with reimbursement pathway traction, and legacy meal replacement brands repositioning through clinical partnerships. Dominant competitive moves include strategic partnerships between digital platforms and employer benefit administrators, plus portfolio diversification from consumer subscription toward annual corporate contracts.
Within the pharmaceutical tier, Novo Nordisk AS and Abbott Laboratories exemplify divergent archetypes—Danish biologics specialization versus diversified health science conglomeration—while WW International Inc. occupies a transitional position between legacy community models and clinical partnership restructuring. Noom Inc. and Medifast Inc. represent contrasting digital-native versus traditional direct-to-consumer paths, with each anchoring distinct reimbursement and customer acquisition strategies. Herbalife Nutrition Ltd. and Nestlé Health Science illustrate multinational nutrition science positioning across emerging and developed market exposure profiles.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nestlé Health Science |
| WW International Inc. |
| Medifast Inc. |
| Noom Inc. |
| Nutrisystem Inc. |
| Atkins Nutritionals Inc. |
| Abbott Laboratories |
| Novo Nordisk AS |
| Others |
Cost & Logistics Intelligence
Peptide-based appetite suppressants displacing macronutrient-restricted meal replacements simultaneously concentrate API manufacturing in Denmark and Switzerland while compressing margin pools in mature supplement categories. This substitution dynamic reconfigures procurement power toward pharmaceutical incumbents with established cardiovascular safety databases.
Pricing Analysis
United States GLP-1 agonist pricing diverges sharply from European statutory reimbursement ceilings, with employer-sponsored wellness contracts in metropolitan health systems commanding premium positioning against individual direct-to-consumer subscriptions. Pricing stratifies across premium pharmacological interventions, standard digital therapeutic platforms, and economy meal replacement tiers, with brand trust and clinical validation serving as primary differentiation drivers. Cost compression in supplement categories intensifies as peptide formulations capture first-line clinical preference. Individual subscribers exhibit highest price sensitivity, while Fortune 500 corporate wellness programs demonstrate inelastic demand under outcomes-based contracting.
Supply Chain Analysis
Just-in-time inventory strategies dominate digital therapeutic platform delivery, while GLP-1 agonist manufacturers maintain strategic cold-chain stockpiles to buffer injection device volatility. Active pharmaceutical ingredient production clusters in Denmark and Switzerland, with fill-finish operations radiating through United States and German distribution hubs. Supply chains draw from specialized biologics contractors for peptide synthesis, Midwest dairy processors for protein isolates, and Canadian pea protein facilities for plant-based alternatives. Single-source vulnerability concentrates in Danish GLP-1 API manufacturing. Distribution runs through hospital outpatient pharmacies and retail pharmacy chains for prescription fulfillment, with direct-to-consumer online retail capturing shelf-stable supplement flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The weight management market is cycling through a pharmacological intervention upswing as GLP-1 receptor agonist adoption curves reshape competitive boundaries and procurement specifications across employer health plans.
For Market Incumbents: Fortify cardiovascular safety databases through continued post-market surveillance investment, as FDA Division of Metabolism and Endocrinology Products extends trial requirements for novel entrants. Secure backward integration into peptide API manufacturing through captive supply agreements with Danish and Swiss biologics contractors to defend against supply volatility. Deepen clinical partnership networks with United States academic medical centers to anchor outcomes-based pricing pilots. For New Entrants and Emerging Players: Differentiate on AI-behavioral psychology convergence by securing digital therapeutic classification through cognitive behavioral therapy protocol validation. Target rural health system penetration where registered dietitian availability collapse creates service delivery gaps. Pursue reimbursement pathway pilots with Indian urban corporate centers under FSSAI nutritional labeling expansion as the most penetrable geography. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital coaching platforms that have achieved payer reimbursement traction but require corporate wellness contract scale. Five-to-ten year viability hinges on demonstrating cost-effectiveness against pharmacotherapy before GLP-1 supply constraints ease. Monitor GLP-1 manufacturing scale-up velocity as the critical inflection signal for digital platform valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Cardiovascular outcome trials satisfy FDA and EMA requirements for novel anti-obesity pharmacology entrants. |
| Manufacturing Scale-Up | Peptide API capacity expansion in Denmark and Switzerland addresses injection device supply volatility. |
| Strategic Partnership | Digital platform alliances with Fortune 500 benefit administrators displace individual subscription models. |
| Regulatory Approval Pathway | Digital therapeutic classification through cognitive behavioral therapy protocols unlocks reimbursement codes. |
| Geographic Expansion | India urban corporate center entry leverages FSSAI mandates and employer health insurance regulations. |
Research Approach
The analysis maps pharmacological interventions, digital therapeutic platforms, and nutritional formulations, each validated through primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Secondary sources include FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up segment sizing triangulates against top-down market validation.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models treatment line, dosage form, patient population, and regional regulatory cluster dimensions. CAGRs derive from patient volume trajectories, pricing elasticity coefficients, and reimbursement pathway adoption curves.
Decision-makers should treat outputs as directional under assumptions of sustained GLP-1 supply constraint and employer wellness spending continuity; material deviation would warrant model refresh. Revision becomes warranted when peptide manufacturing scale-up crosses patient access interruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Smart Wellness Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Yoga Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market