
 Weight Management Products Market | 2026-2036
Weight Management Products Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Management Products Market Intelligence
Direct-to-consumer digital channels is rewriting how weight management products reach buyers, bypassing traditional pharmacy and retail gatekeepers. Herbalife Nutrition Ltd. leverages its independent distributor network to sustain engagement in emerging markets. Nestlé S.A. anchors its portfolio through functional foods that compete on clinical credibility. Abbott Laboratories differentiates via medical-grade meal replacements positioned for bariatric and diabetes protocols.
Weight management products encompass formulated consumables and devices engineered to alter energy balance, body composition, or metabolic rate through controlled caloric intake, macronutrient modulation, or physiological intervention. These products typically specify active ingredient concentrations, glycemic indices, or mechanical resistance parameters to ensure reproducible outcomes across patient and consumer populations. Dietary supplements occupy the largest revenue pool though meal replacements capture the fastest expansion as clinical protocols integrate structured nutrition into obesity treatment pathways. Functional foods concentrate margin in premium positioned entries while herbal products navigate stricter substantiation requirements across regulatory jurisdictions.
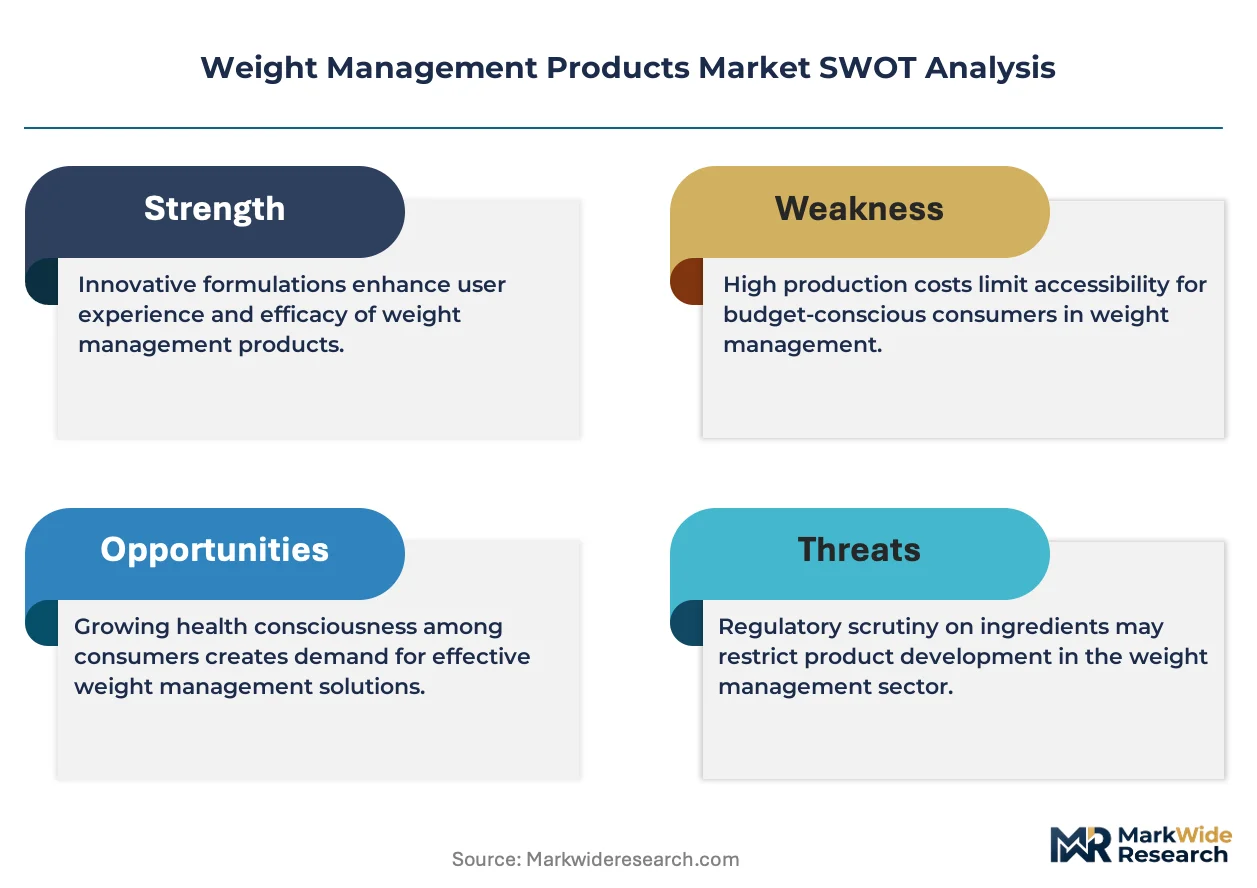
FDA nutrition labeling rules and EFSA health claims regulations force reformulation of appetite control and metabolism boost positioned products toward evidence-backed ingredient thresholds. The EU F-Gas Regulation and REACH frameworks additionally constrain excipient sourcing for certain delivery forms. Stakeholders must monitor how WHO obesity classification updates and national reimbursement policies for medical foods reshape the boundary between wellness consumer and clinical patient segments.
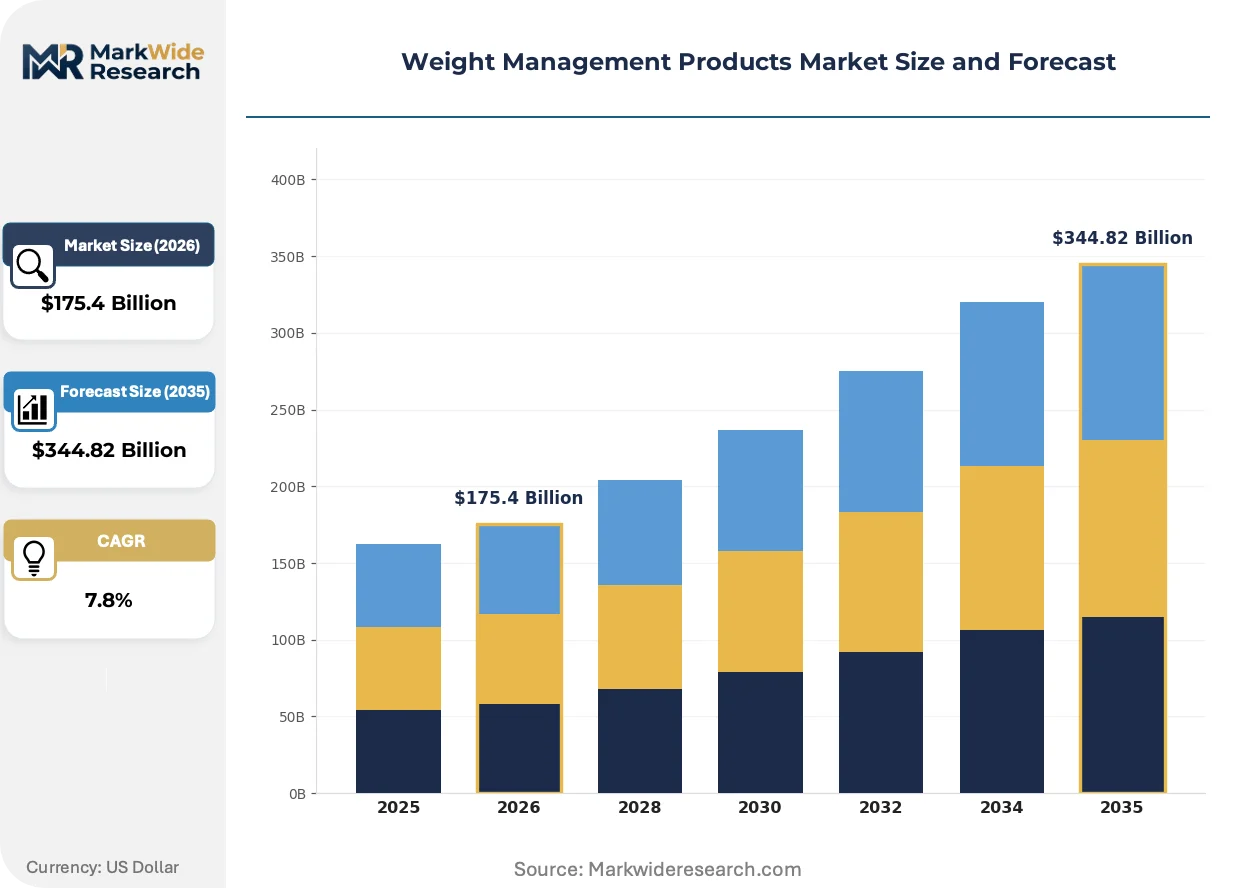
Market Dynamics
Direct-to-consumer digital channels are compressing traditional pharmacy and retail distribution layers, forcing reformulation investments that meet FDA and EFSA substantiation thresholds while enabling personalized nutrition protocols at scale.
Growth Catalysts
- Structured clinical protocols:Bariatric surgery programs and diabetes management pathways integrate medical-grade meal replacements as reimbursable interventions, expanding the addressable patient population beyond wellness consumers.
- FDA nutrition labeling modernization:Updated serving-size definitions and added-sugar disclosure requirements favor products with transparent macronutrient profiles, rewarding manufacturers with existing clean-label infrastructure.
- Germany:The country's statutory health insurance system increasingly covers prescription medical foods for obesity-related comorbidities, creating a reimbursed channel distinct from discretionary supplement purchases.
Market Restraints
- Protein input cost volatility:Whey and plant-protein concentrate prices fluctuate with dairy futures and agricultural commodity cycles, compressing gross margins for formulation-dependent SKUs.
- EFSA health claims substantiation:The 2015 Claims Regulation requires randomized controlled trials for appetite-control positioning, eliminating legacy marketing language and extending product development timelines.
- Supply concentration in excipient sourcing:Hydroxypropyl methylcellulose and modified starch suppliers cluster in China and India, exposing finished-goods manufacturers to tariff and logistics disruptions.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA's evolving medical food classification creates first-mover advantage for clinical-positioned entrants before reimbursement standardization matures.
- Continuous glucose monitor integration:Wearable metabolic data streams enable real-time personalized meal replacement dosing, converging hardware and consumable revenue models.
- Subscription direct-to-patient:Telehealth platforms bypass retail markup while capturing adherence data that supports payer contract negotiations for medical food coverage.
Industry Challenges
- Clinical-trial recruitment bottlenecks:Obesity protocol enrollment competes with GLP-1 pharmaceutical studies for investigator sites and patient pools, delaying EFSA-compliant claim substantiation.
- Legacy ERP integration:Track-and-trace requirements for FDA Food Safety Modernization Act compliance force mid-tier manufacturers to replace batch-record systems without disrupting just-in-time production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Management Products Market |
| Market Size in 2026 | $175.4 Billion |
| Market Size in 2035 | $344.82 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Functional Foods, Meal Replacements, Herbal Products, Medical Devices Form: Capsules, Powders, Liquids, Bars, Teas Application: Fat Reduction, Appetite Control, Metabolism Boost, Detoxification, Energy Enhancement End User: Gyms, Wellness Centers, Nutritionists, Personal Trainers, Fitness Enthusiasts |
| Companies Covered | Herbalife Nutrition Ltd., Nestlé S.A., Abbott Laboratories, Glanbia PLC, The Kellogg Company, WW International Inc., GNC Holdings, Inc., Atkins Nutritionals, Inc., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Management Products Market Strategic Shifts & Innovations
Biometric feedback loops and regulatory substantiation mandates are converging to separate evidence-backed formulations from legacy positioning, compressing the viable product development cycle while opening new reimbursement pathways.
Precision fermentation-derived proteins are hybridizing supply chains by replacing conventional dairy and soy isolates with identical amino acid profiles produced via microbial hosts. Sports nutrition and clinical meal replacement brands adopt these inputs to secure volume commitments independent of agricultural yield volatility. This technology is hybridizing cost structures, enabling price parity with commodity proteins while satisfying clean-label and allergen-free positioning simultaneously.
REACH authorization requirements for novel food-contact substances now extend to meal replacement packaging films containing active oxygen scavengers. Manufacturers reformulate barrier layers or absorb extended safety dossier costs to maintain shelf-life claims. Powder and ready-to-drink formats face divergent compliance timelines, with European launches delayed relative to US equivalents using GRAS-notified materials.
Employer-sponsored weight management benefits are consolidating purchasing authority through third-party administrators, displacing individual discretionary spending at retail. Large self-insured plans negotiate direct contracts with medical food suppliers for covered employee populations. This concentration is most visible in the United States, where Fortune 500 wellness program budgets now exceed traditional health club reimbursement allocations.
Weight Management Products Market Segmentation
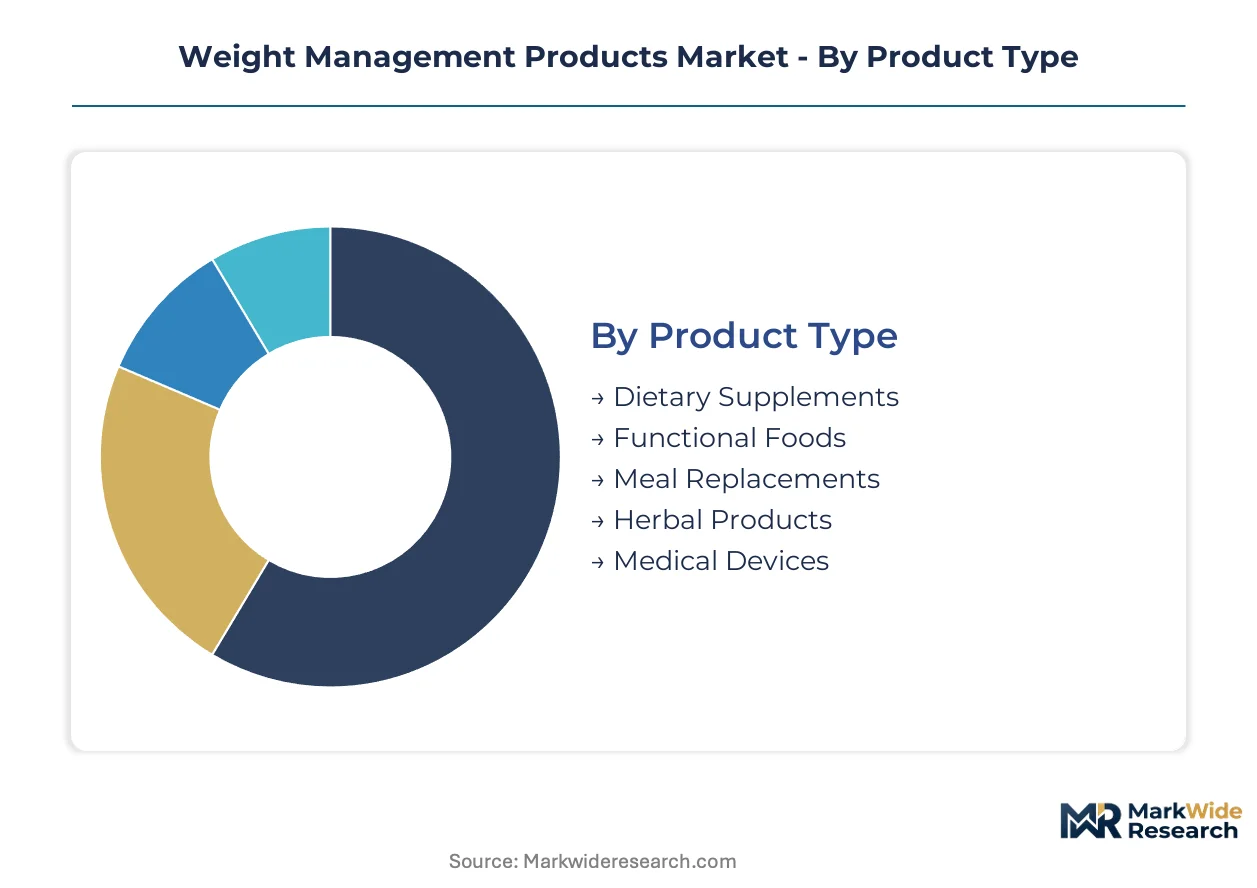
Segmentation in weight management products separates clinical-grade interventions from discretionary wellness purchases, with each category carrying distinct regulatory pathways and margin structures. Manufacturers must align formulation investments with the substantiation requirements and reimbursement eligibility of their target segments.
Product Type:
Cycle times vary sharply across this category, with medical devices requiring multi-year regulatory clearance while dietary supplements pivot formulations within months.
- Dietary Supplements:Formulated capsules, tablets, and softgels containing concentrated botanical extracts, vitamins, or minerals with specified active-ingredient thresholds. Demand concentrates in the United States where FDA DSHEA compliance costs favor established labelers with in-house analytical laboratories, though Amazon's supplement gating policies now absorb significant compliance overhead.
- Meal Replacements:Complete nutrition formulas delivering controlled macronutrient ratios with defined glycemic indices and micronutrient completeness per serving. Germany's statutory health insurance reimbursement for prescription medical foods accelerates patient adoption through pharmacy channels, diverging from discretionary sports-nutrition positioning elsewhere.
- Functional Foods:Fortified conventional foods with added bioactive compounds or modified macronutrient profiles.
- Herbal Products:Plant-derived preparations positioned for metabolic or appetite-modulating effects.
- Medical Devices:FDA-cleared or CE-marked apparatus for body composition analysis, gastric restriction, or metabolic monitoring.
Dietary supplements anchors the volume base while meal replacements gains share at the steepest rate.
Form:
Manufacturing asset intensity and shelf-stability requirements create divergent margin profiles across delivery formats.
- Powders:Bulk-form meal replacements and protein isolates requiring precise moisture control and oxygen-barrier packaging to maintain shelf-life claims. China's concentration in hydroxypropyl methylcellulose capsule shell supply exposes powder manufacturers to excipient cost volatility, driving backward integration into in-house blending facilities.
- Liquids:Ready-to-drink formulations with aseptic processing requirements and shortened distribution windows. Nestlé's clinical nutrition manufacturing footprint in Switzerland supports European hospital and pharmacy channels with cold-chain verified logistics, capturing premium positioning through stability data packages.
- Capsules:Encapsulated extracts and complexes with standardized dissolution profiles.
- Bars:Solid-form meal replacements with texture and mouthfeel engineering challenges.
- Teas:Infusion-based herbal preparations with traditional medicine positioning.
Powders dominate production volume while liquids commands the highest per-unit margin.
Application:
Clinical evidence requirements stratify segments, with metabolism boost facing the steepest EFSA substantiation barriers.
- Appetite Control:Formulations targeting satiety signaling through fiber matrices, protein loading, or botanical compounds with documented gastric emptying effects. GLP-1 pharmaceutical adoption in the United States compresses addressable market for non-prescription alternatives, forcing repositioning toward surgical prehabilitation and medication discontinuation support.
- Fat Reduction:Products modulating lipid metabolism or absorption through enzymatic inhibition or caloric deficit engineering. Brazil's ANVISA medical food classification evolution creates first-mover positioning for clinical-protocol entrants before reimbursement standardization matures.
- Metabolism Boost:Thermogenic and mitochondrial efficiency positioning with heavy substantiation burdens.
- Detoxification:Liver support and elimination pathway formulations with variable regulatory acceptance.
- Energy Enhancement:Caffeine and adaptogen-based formulations for physical performance support.
Fat reduction captures the largest revenue pool while appetite control faces the most intense competitive pressure from pharmaceutical alternatives.
End User:
Channel concentration shapes pricing power, with institutional purchasers consolidating volume through direct contracts.
- Gyms:High-traffic fitness facilities with captive member bases and supplement retail integration. Equinox and Life Time Fitness in the United States negotiate exclusive brand placements with revenue-sharing structures, displacing open retail competition within facility boundaries.
- Nutritionists:Licensed practitioners with prescribing authority for medical foods and structured meal protocols. Germany's dietitian network channels reimbursable prescriptions through statutory health insurance, creating a credential-gated distribution layer distinct from open retail.
- Wellness Centers:Holistic health facilities with integrated service and product offerings.
- Personal Trainers:Individual coaches with limited regulatory scope but high client influence.
- Fitness Enthusiasts:Self-directed consumers purchasing through direct-to-consumer digital channels.
Gyms and nutritionists together concentrate institutional purchasing power while fitness enthusiasts drives direct-to-consumer volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in weight management products diverges sharply between Germany's reimbursed pharmacy channel and the United States' discretionary direct-to-consumer market, creating a two-speed revenue architecture across developed economies.
United States
Employer-sponsored wellness programs and GLP-1 pharmaceutical adoption reshape demand for medical-grade meal replacements. FDA nutrition labeling modernization forces serving-size transparency that favors established clean-label manufacturers. The Boston-Cambridge corridor concentrates digital health startups integrating continuous glucose monitors with personalized nutrition protocols.
Germany
Statutory health insurance reimbursement for prescription medical foods expands the addressable patient population beyond wellness consumers. EFSA health claims substantiation requirements under the 2015 Claims Regulation eliminate legacy appetite-control marketing language. The Rhine-Ruhr metropolitan region anchors Nestlé's clinical nutrition manufacturing footprint serving hospital and pharmacy channels.
China
SAMR's evolving medical food classification and dual carbon goals reshape formulation standards and packaging sustainability requirements. E-commerce platform consolidation through Tmall and JD Health compresses traditional retail distribution layers. Yangtze River Delta manufacturing clusters dominate hydroxypropyl methylcellulose excipient production for capsule and powder formulations.
Brazil
ANVISA's developing medical food classification creates first-mover positioning for clinical-protocol entrants before reimbursement standardization matures. Rising obesity prevalence drives demand for structured nutrition interventions in employer health programs. São Paulo state's pharmaceutical manufacturing corridor attracts regional headquarters for multinational meal replacement brands.
India
FSSAI's tightening supplement quality standards and rising diabetes prevalence expand the clinical nutrition addressable market. Direct-to-consumer digital channels bypass traditional pharmacy gatekeepers in tier-1 cities. Maharashtra's Mumbai-Pune industrial belt concentrates contract manufacturing capacity for powder and liquid formulations serving domestic and export markets.
Weight Management Products Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying active ingredients and excipients to finished-goods formulators. The weight management products market exhibits consolidated leadership among multinational nutrition conglomerates with diversified portfolios spanning supplements, functional foods, and clinical nutrition. Three archetypes dominate: vertically integrated life-science conglomerates with medical-grade credibility, sports-nutrition specialists with direct-to-consumer digital infrastructure, and ingredient technology suppliers with precision fermentation capabilities. Competitive dynamics center on M&A activity to acquire biometric data platforms and capacity expansion in aseptic liquid manufacturing to serve hospital channels.
Within the life-science conglomerate tier, Herbalife Nutrition Ltd., Nestlé S.A., and Abbott Laboratories exemplify divergent strategic positioning. Herbalife's distributor-network model represents independent-channel engagement in emerging markets. Nestlé's Swiss-based S.A. structure anchors clinical credibility through functional food portfolios. Abbott's laboratory-derived corporate heritage occupies the medical-grade meal replacement segment serving bariatric and diabetes treatment protocols.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nestlé S.A. |
| Abbott Laboratories |
| Glanbia PLC |
| The Kellogg Company |
| WW International Inc. |
| GNC Holdings, Inc. |
| Atkins Nutritionals, Inc. |
| Koninklijke DSM N.V. |
| Others |
Cost & Logistics Intelligence
The Rotterdam-Antwerp pharmaceutical corridor channels excipient freight costs into finished-goods pricing, concentrating margin pressure on powder and capsule manufacturers while enabling premium differentiation for cold-chain liquid formulations through validated logistics infrastructure.
Pricing Analysis
The customization-premium spread separates configured-to-order medical food protocols from standard retail SKUs. Three-tier pricing structure across premium clinical-grade, standard wellness-positioned, and economy private-label levels dominates the market. Price differentiation rests on EFSA substantiation tier and volume scale, with institutional purchasers commanding contract discounts unavailable to direct-to-consumer buyers. Cost compression in the economy tier is intensifying because of whey protein concentrate volatility, while fitness enthusiasts show highest price sensitivity and hospital procurement committees demonstrate lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk assessment for hydroxypropyl methylcellulose and modified starch inputs. Geographic supply concentrates in China, India, and Germany for excipient sourcing, with Switzerland anchoring aseptic liquid manufacturing. Raw material dependencies center on whey isolates, plant protein concentrates, and oxygen-scavenger packaging films. Single-source vulnerability in HPMC capsule shell supply creates bottleneck exposure. Distribution runs through pharmacy channels in reimbursed markets and direct-to-consumer digital platforms in discretionary segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The weight management products market sits in early-cycle expansion as GLP-1 pharmaceutical adoption drives surgical prehabilitation and medication discontinuation support demand for structured nutrition protocols.
For Market Incumbents: Entrench medical-grade credibility through backward integration into precision fermentation protein supply and capacity expansion in Switzerland's aseptic manufacturing corridor. GLP-1 pharmaceutical competition threatens discretionary appetite-control positioning; defend through bariatric surgery program integration and statutory health insurance reimbursement contracts in Germany. For New Entrants and Emerging Players: Build out telehealth-integrated subscription models in Brazil before ANVISA reimbursement standardization matures, capturing first-mover positioning in employer-sponsored health programs. The most penetrable white space sits in continuous glucose monitor companion protocols, with personalized dosing algorithms as the go-to-market anchor. For Investors and Strategic Acquirers: Biometric data platform specialists with FDA-cleared software companions represent the highest-conviction acquisition archetype. Long-term viability over the five-to-ten year horizon hinges on convergence between hardware-enabled metabolic monitoring and consumable revenue models. Watch for employer wellness program budget reallocations from fitness reimbursements toward medical food coverage as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Integration | Microbial protein production secures volume commitments independent of agricultural yield cycles. |
| Continuous Glucose Monitor Partnership | Wearable metabolic data enables real-time personalized meal replacement dosing protocols. |
| Statutory Health Insurance Contracting | Germany's reimbursable pharmacy channel expands addressable patient population beyond wellness consumers. |
| Aseptic Liquid Capacity Expansion | Switzerland-based manufacturing captures premium positioning through cold-chain verified logistics. |
| Telehealth Platform Acquisition | Direct-to-patient channels bypass retail markup while capturing adherence data for payer negotiations. |
Research Approach
The analysis maps dietary supplements, meal replacements, functional foods, and medical devices, each validated through regulatory affairs directors, hospital procurement managers, distributor network leads, and clinical nutrition specialists. Primary interviews combined with secondary validation from FDA filings, EFSA health claims registers, statutory health insurance reimbursement databases, and customs trade records. Bottom-up SKU-level volume aggregation and top-down macroeconomic triangulation anchor the approach.
Assumptions held fixed include EFSA substantiation timelines and WHO obesity classification frameworks, while variables included GLP-1 pharmaceutical adoption curves and employer wellness program budget trajectories. Segmentation dimensions span product type, form, application, and end-user channel across the projection horizon. CAGRs derive from weighted average growth contributions by segment. Forecast inputs incorporate protein commodity futures and medical food reimbursement policy evolution.
Sensitivities concentrate around GLP-1 pharmaceutical substitution effects and REACH authorization delays for novel packaging materials. Forecasts reflect documented assumptions without forward guarantees. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Nutrition
South America Sports Drinks Market
Sports Nutrition
Weight Management Supplements Market
Sports Nutrition
Brazil Sports Nutrition Market
Sports Nutrition
Branched Chain Amino Acid Supplements Market
Sports Nutrition
Hydration Products Market
Sports Nutrition
GCC Sports Nutrition Market
Sports Nutrition
Sports Nutrition Market
Sports Nutrition
South America Sports Nutrition Market
Sports Nutrition
Europe Weight Management Supplement Market
Sports Nutrition
Hydroxymethylbutyrate Supplement Market
Sports Nutrition
ACF Supplements Market
Sports Nutrition
Global Ketone Supplements Market
Sports Nutrition
Europe Sports Nutrition Market
Sports Nutrition
Asia-Pacific Sports Nutrition Market
Sports Nutrition
Taurine Supplements Market
Sports Nutrition
Sports Nutrition Ingredients Market