
 GCC Weight Loss Market | 2026-2036
GCC Weight Loss Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Weight Loss Market Intelligence
SFDA's tightened supplement registration protocols is decoupling market access from simple import licensing, forcing entrants to establish local quality-assurance infrastructure. Glanbia PLC leverages its whey-protein vertical integration to sustain margin control across Gulf distribution channels. Herbalife Nutrition Ltd. anchors its regional presence through direct-selling networks that navigate Saudi Arabia's evolving commercial agency regulations.
GCC weight loss encompasses regulated nutritional interventions, physical conditioning apparatus, and behavior-modification protocols designed to reduce adiposity and improve metabolic markers. Formulation standards for meal-replacement products typically mandate minimum protein thresholds and micronutrient completeness to qualify for health claims. Dietary supplements dominate current revenue pools, while plant-based diet programs exhibit the fastest trajectory as Gulf consumers recalibrate protein sourcing away from conventional animal derivatives. Fitness equipment competes primarily on connected-device integration, with smart monitoring capabilities commanding premium positioning across Dubai and Riyadh retail channels.
SFDA and the UAE Ministry of Health and Prevention jointly enforce supplement labeling and advertising standards that restrict unsubstantiated efficacy claims. Dubai Municipality's food safety department extends this oversight to meal-replacement products sold through e-commerce platforms, creating a dual-track compliance environment. Stakeholders must monitor how Saudi Arabia's excise tax framework on sweetened beverages reshapes consumer caloric intake patterns and redirects spending toward structured weight management offerings.
Market Dynamics
The GCC weight loss sector faces structural pressure from the Saudi Food and Drug Authority's tightened supplement registration protocols, which now mandate local quality-assurance infrastructure and decouple market access from simple import licensing. This regulatory pivot elevates compliance costs for new entrants while rewarding incumbents with established Gulf distribution networks.
Growth Catalysts
- SFDA Registration Mandates:The tightened protocols force entrants to build local testing facilities, creating barriers that protect established players with Gulf infrastructure.
- Metropolitan Health Club Density:Riyadh, Jeddah, and Dubai concentrate disposable income and fitness penetration, anchoring demand for premium weight management solutions.
- Smart Device Integration:Connected fitness equipment with metabolic monitoring capabilities commands premium positioning across Dubai and Riyadh retail channels.
Market Restraints
- Whey Protein Input Volatility:Global dairy commodity swings compress margins for meal-replacement manufacturers dependent on imported protein isolates.
- Dual-Track Compliance Burden:SFDA and MOHAP labeling standards create overlapping audit requirements that extend product launch timelines.
- Plant-Based Substitution Threat:Accelerating consumer pivot from animal-derived proteins toward legume and algae alternatives destabilizes conventional formulation strategies.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:These markets lack the health club density and disposable income concentration of Riyadh and Dubai, offering first-mover expansion potential.
- E-Commerce Platform Integration:Dubai Municipality's extended oversight of meal-replacement sales through digital channels creates compliant direct-to-consumer pathways.
- Saudi Excise Tax Tailwind:Sweetened beverage taxation redirects consumer spending toward structured weight management offerings.
Industry Challenges
- Halal Certification Complexity:Multi-jurisdictional religious compliance requirements across Saudi Arabia, UAE, and neighboring states fragment product standardization.
- Local Quality-Assurance Talent Scarcity:SFDA-mandated infrastructure requires skilled Gulf-based regulatory affairs specialists that remain in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Weight Loss Market |
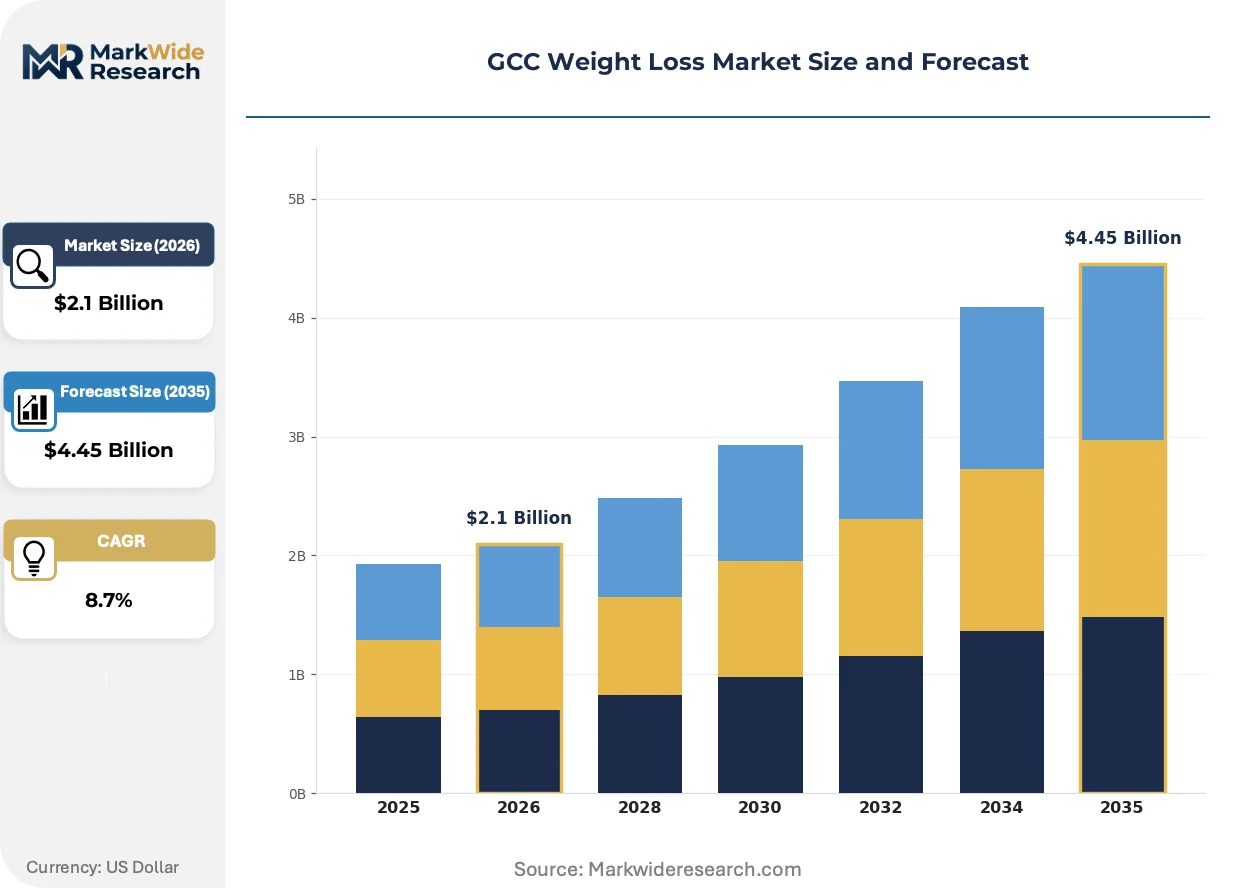
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacement, Fitness Equipment, Weight Loss Programs Delivery Mode: Online Sales, Retail Stores, Fitness Centers, Health Clinics Diet Type: Low-Carb, High-Protein, Plant-Based, Intermittent Fasting Consumer Demographic: Adults, Seniors, Teenagers, Pregnant Women |
| Companies Covered | Glanbia PLC, Ajinomoto Co. Inc., Herbalife Nutrition Ltd., Weight Watchers International, Nutrisystem, Nestle, Atkins Nutritionals, Amway Corp., GlaxoSmithKline PLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Weight Loss Market Strategic Shifts & Innovations
Connected metabolic monitoring is redrawing competitive boundaries in GCC weight management. Wearable integration and AI-driven personalization are compressing the gap between clinical intervention and consumer self-management.
Continuous glucose monitoring wearables are decentralizing metabolic feedback from clinical settings into daily consumer routines. Health-conscious professionals in Dubai and Riyadh are adopting these devices at accelerating rates. This shift is decentralizing dietitian authority toward algorithm-driven meal planning and real-time macronutrient adjustment.
MOHAP's tightened advertising standards for supplement efficacy claims are compressing marketing vocabulary across UAE digital channels. Manufacturers must now substantiate weight-loss assertions with clinical documentation. The meal-replacement segment is responding by reformulating around documented micronutrient completeness rather than aspirational lifestyle positioning.
Subscription-based coaching models are displacing one-time product purchases in Saudi Arabia's premium segment. Digital platforms bundle connected devices with remote dietitian access, unbundling traditional gym-based program delivery. This pattern is most visible among Riyadh's corporate wellness contracts, where employers seek measurable ROI on workforce health investments.
GCC Weight Loss Market Segmentation
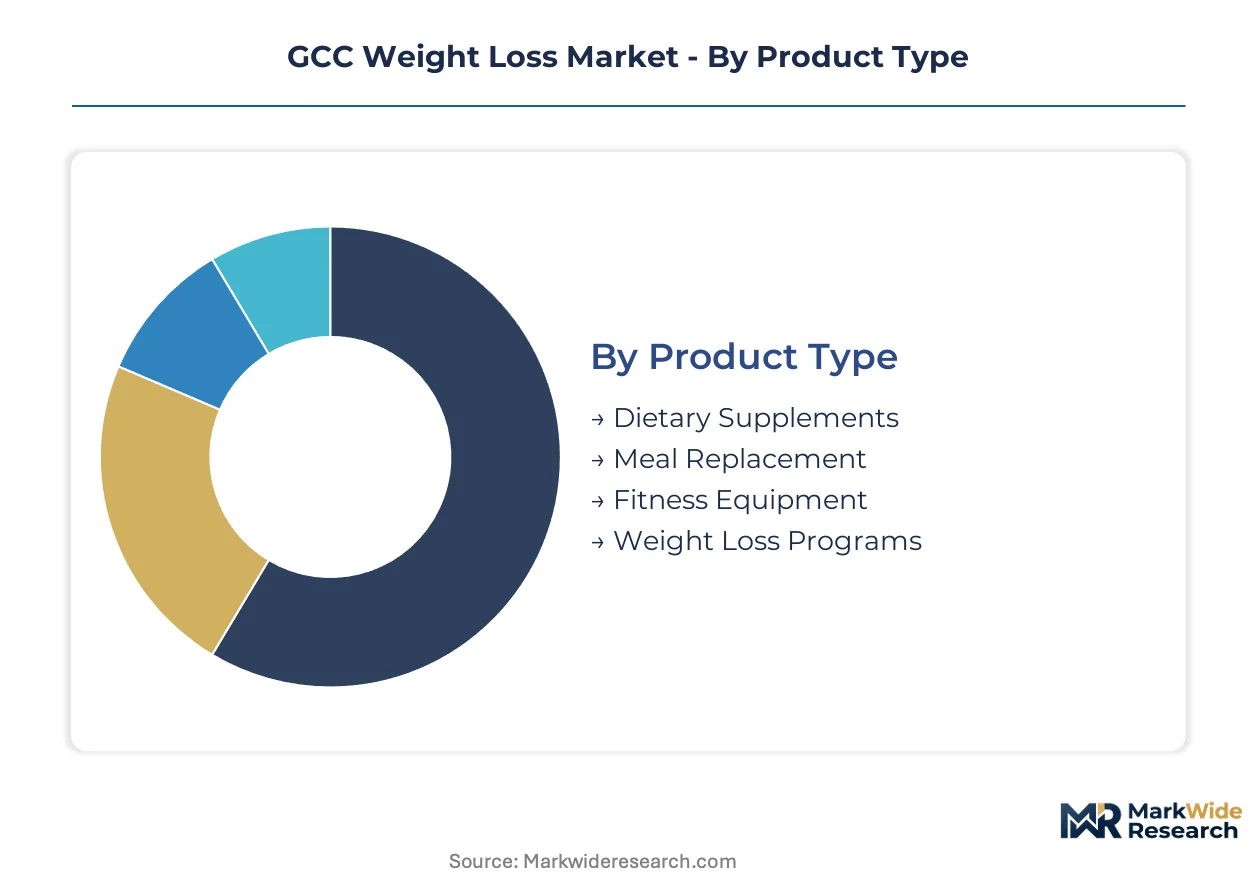
Segmentation in the GCC weight loss market reveals how purchasing power, regulatory exposure, and cultural preferences fragment demand across four critical dimensions. Each category exposes distinct margin profiles and compliance burdens that shape competitive positioning.
Product Type:
Purchasing behavior splits between consumable regimens requiring repeat transactions and durable hardware with extended replacement cycles.
- Dietary Supplements:Capsule, powder, and liquid formulations targeting metabolic acceleration and appetite modulation. Riyadh and Dubai health clubs drive premium positioning, though SFDA registration mandates now elevate compliance costs for new entrants.
- Meal Replacement:Pre-portioned shakes and bars delivering controlled caloric density with mandated protein thresholds. Corporate wellness contracts in Saudi Arabia anchor institutional demand as employers seek measurable workforce health ROI.
- Fitness Equipment:Connected devices with metabolic monitoring capabilities. Smart integration commands price premiums across Dubai retail channels.
- Weight Loss Programs:Structured behavioral protocols combining dietary guidance with coaching access. Subscription models displace one-time purchases in Saudi premium segments.
Volume sits with Dietary Supplements; growth tilts toward Meal Replacement as corporate procurement expands.
Delivery Mode:
Channel selection determines regulatory touchpoints and customer acquisition economics, with digital pathways now commanding disproportionate investment.
- Online Sales:Direct-to-consumer platforms and marketplace aggregators. Dubai Municipality's extended oversight of meal-replacement e-commerce creates compliant pathways that bypass traditional retail gatekeepers.
- Retail Stores:Pharmacy chains and hypermarket health aisles. Saudi Arabia's commercial agency regulations complicate foreign brand distribution.
- Fitness Centers:On-site product placement and bundled program sales. Metropolitan club density in Jeddah and Dubai concentrates this channel's revenue contribution.
- Health Clinics:Medically supervised weight management and prescription-adjacent protocols. MOHAP standards restrict unsubstantiated efficacy claims in UAE clinical settings.
Online Sales capture volume expansion; Health Clinics deliver margin protection through clinical credibility premiums.
Diet Type:
Nutritional philosophy alignment determines formulation requirements and ingredient sourcing strategies across protein substrates.
- Low-Carb:Ketogenic and reduced-glycemic protocols emphasizing fat oxidation. Saudi excise taxation on sweetened beverages redirects consumer preference toward carbohydrate restriction.
- High-Protein:Elevated amino acid intake targeting satiety and lean mass preservation. Whey protein input volatility from global dairy commodity swings compresses manufacturer margins.
- Plant-Based:Legume, algae, and alternative protein sourcing. Gulf consumers recalibrating away from animal derivatives drive the steepest expansion trajectory in this category.
- Intermittent Fasting:Time-restricted eating windows without caloric prescription. Digital coaching platforms facilitate adherence tracking among Riyadh professionals.
High-Protein dominates current revenue pools; Plant-Based gains share fastest as protein sourcing preferences shift.
Consumer Demographic:
Age and life-stage segmentation exposes divergent price sensitivity, health risk profiles, and regulatory safeguarding requirements.
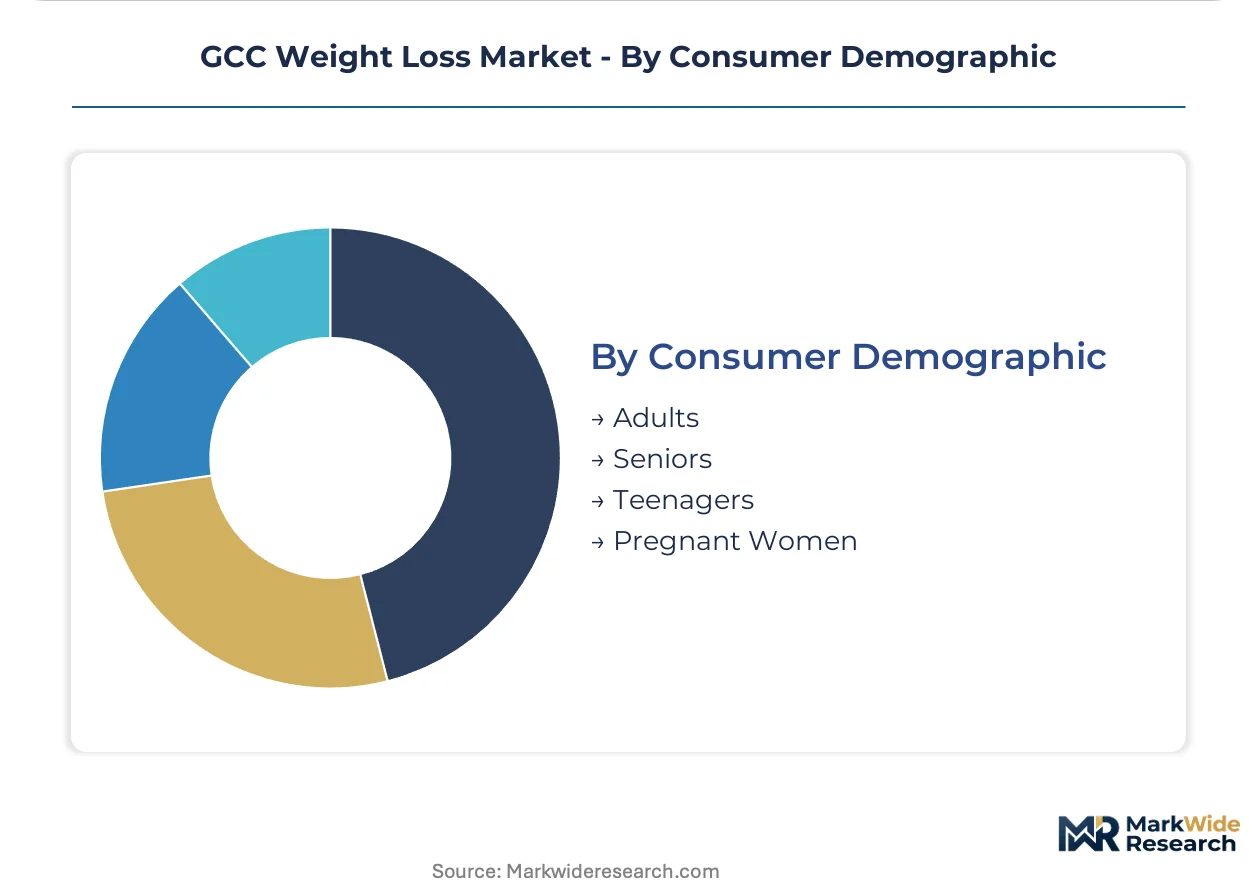
- Adults:Working-age population aged 18-64 with discretionary health spending. Obesity concentration among Saudi and UAE professionals intensifies demand for structured workplace interventions.
- Seniors:Population segments requiring sarcopenia prevention and metabolic maintenance. Medical supervision requirements elevate channel preference toward Health Clinics.
- Teenagers:Adolescent weight management with heightened regulatory scrutiny. SFDA and MOHAP labeling standards impose stricter substantiation for efficacy claims targeting minors.
- Pregnant Women:Pre- and post-natal weight protocols with specialized micronutrient requirements. Halal certification complexity fragments product standardization across Saudi Arabia and UAE jurisdictions.
Adults concentrate transaction volume; Seniors expand fastest as Gulf population aging accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City anchors concentrated health infrastructure investment along Saudi Arabia's western coast. This zone channels foreign direct investment into wellness manufacturing and distribution facilities serving Red Sea port access.
Saudi Arabia
Riyadh's corporate wellness procurement contracts drive institutional demand for structured weight management programs. SFDA registration mandates now require local quality-assurance infrastructure, elevating compliance costs for supplement entrants. Jeddah's health club density concentrates premium fitness equipment sales with connected metabolic monitoring capabilities.
United Arab Emirates
Dubai's disposable income concentration and fitness penetration anchor demand for premium meal-replacement products. MOHAP advertising standards restrict unsubstantiated efficacy claims across UAE digital channels, compressing marketing vocabulary. Abu Dhabi's medical tourism infrastructure attracts Gulf consumers seeking clinically supervised protocols.
Kuwait
Underpenetrated health club density relative to Riyadh and Dubai creates first-mover expansion potential for structured program providers. The country's national pharmaceutical regulator maintains supplement labeling standards aligned with GCC harmonization efforts. Kuwait City's emerging corporate wellness sector channels employer-sponsored weight management spending.
Bahrain
Financial services sector professionals generate concentrated demand for time-efficient dietary interventions. Bahrain's health ministry enforces halal certification requirements that fragment product standardization with neighboring jurisdictions. Manama's retail pharmacy chains serve as primary distribution gatekeepers for imported supplement brands.
Qatar
Expatriate professional populations with elevated obesity risk profiles intensify demand for English-language program delivery. Qatar's national health authority mandates pre-market notification for novel food products including meal replacements. Doha's sports infrastructure investment, including facilities from the 2022 World Cup, channels fitness equipment procurement.
GCC Weight Loss Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation, distribution, and coaching delivery vectors. The market structure rewards incumbents with established Gulf distribution networks and local regulatory affairs capabilities. Three archetypes dominate: multinational nutrition conglomerates with captive ingredient sourcing, direct-selling specialists leveraging personal network effects, and clinical-program operators anchoring medical credibility. Competitive moves concentrate on SFDA compliance infrastructure acquisition and subscription-based coaching platform development.
Among multinational nutrition conglomerates, Glanbia PLC and Nestle occupy positions exemplifying backward integration into protein sourcing and broad portfolio diversification across meal-replacement formats. Herbalife Nutrition Ltd. sits within the direct-selling specialist tier, representing network-based distribution architectures that navigate Saudi Arabia's evolving commercial agency regulations. These three anchors illustrate how divergent channel strategies—captive supply chains, personal selling networks, and clinical partnerships—partition the competitive landscape.
| Leading Market Players |
|---|
| Glanbia PLC |
| Ajinomoto Co. Inc. |
| Herbalife Nutrition Ltd. |
| Weight Watchers International |
| Nutrisystem |
| Nestle |
| Atkins Nutritionals |
| Amway Corp. |
| GlaxoSmithKline PLC |
| Others |
Cost & Logistics Intelligence
Global whey protein isolate futures and dairy commodity benchmarks cascade through GCC formulation costs, compressing margins for meal-replacement manufacturers while rewarding players with backward integration into protein sourcing. Price stratification across premium, standard, and economy tiers reflects divergent certification burdens and lead-time flexibility rather than intrinsic formulation differences.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to spot orders from Riyadh and Dubai health clubs, while contracted quarterly offtakes secure volume discounts. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-registered formulations with local quality-assurance infrastructure from import-dependent alternatives. Cost compression in the standard tier is intensifying because global dairy commodity swings transmit directly into whey protein input costs. Corporate wellness procurement teams in Saudi Arabia exhibit lowest price sensitivity, while independent health clubs in Bahrain and Kuwait drive hardest bargain negotiations.
Supply Chain Analysis
Dual-sourcing requirements from Saudi and UAE institutional buyers mandate qualified suppliers across both European dairy processors and North American protein isolate manufacturers. Geographic supply concentration centers on Ireland, New Zealand, and the United States for premium whey derivatives, with secondary qualification of Argentine and Australian alternatives for cost-sensitive tiers. Raw material dependencies rest on milk powder futures, hydrolyzed protein isolates, and specialized micronutrient premixes from Swiss and German suppliers. Single-source vulnerability from European dairy cooperative concentration presents structural risk during trade policy shifts. Distribution runs through Red Sea port consolidation at Jeddah and direct air freight into Dubai free zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in GCC weight management is becoming a vertical-integration race, with control over halal-certified protein sourcing and local SFDA testing infrastructure as the decisive upstream lever.
For Market Incumbents: Cement market position by acquiring distressed local quality-assurance facilities to meet SFDA registration mandates before capacity scarcity drives asset prices upward. Deepen captive supply of halal-certified whey protein through long-term offtake agreements with New Zealand and Irish processors, insulating margin structure from dairy commodity volatility that threatens import-dependent competitors. For New Entrants and Emerging Players: Fitness center chains in Kuwait and Bahrain present the most penetrable channel anchor, as these markets lack the established direct-selling networks that dominate Saudi Arabia and UAE. Digital-native subscription coaching platforms targeting Riyadh corporate wellness contracts offer white-space entry with lower regulatory exposure than supplement formulation. Prioritize partnership with Dubai Municipality-compliant e-commerce enablers to bypass traditional retail gatekeeper margins. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with existing Gulf regulatory affairs capabilities and halal certification expertise. Long-term viability hinges on consolidation plays that aggregate SFDA-registered local infrastructure across fragmented supplement portfolios. Watch for Saudi excise tax expansion into additional sugar categories as the inflection signal redirecting consumer spending toward structured weight management subscriptions.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Compliance Infrastructure Acquisition | Local testing facilities decouple market access from import licensing delays and protect margin structure. |
| Halal Certification Vertical Integration | In-house religious compliance teams reduce multi-jurisdictional fragmentation across Saudi Arabia and UAE. |
| Corporate Wellness Subscription Platforms | Riyadh employer contracts seek measurable ROI on workforce health investments through bundled coaching. |
| Connected Device Ecosystem Development | Smart metabolic monitoring capabilities command premium positioning across Dubai and Riyadh retail channels. |
| Plant-Based Protein Sourcing Diversification | Legume and algae alternatives address accelerating Gulf consumer pivot from animal-derived formulations. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with SFDA regulatory affairs consultants, health club procurement directors, corporate wellness benefits managers, and Dubai Municipality food safety officers. SFDA supplement registration databases, MOHAP advertising enforcement notices, GCC customs import classifications, and health club membership statistics provided validation triangulation. Bottom-up segment sizing and top-down macroeconomic reconciliation ensured cross-check integrity across the analysis window.
Data-stream reconciliation merged volume trajectories from equipment import manifests with value indicators from retail channel audits and corporate contract disclosures. Segmentation modeling captured product type, delivery mode, diet philosophy, and consumer demographic dimensions alongside regulatory compliance tier as an industry-specific stratifier. CAGRs were derived from curve-fitting across historical trajectory and policy-impact scenario weighting, with Saudi excise tax elasticity and SFDA registration velocity as key forecast inputs.
Caveats apply where SFDA regulatory stringency revisions or Gulf dairy commodity price spikes could materially shift the outlook. Forecasts embed assumptions regarding sustained metropolitan health club expansion and corporate wellness adoption velocity. Deviation in Saudi excise tax scope expansion timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Yoga Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Weight Control Products Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Weight Management Market
Health and Wellness
Europe Weight Management Market