
 Europe Health and Wellness Market | 2026-2036
Europe Health and Wellness Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Health and Wellness Market Insights
REACH compliance is restructuring the cost-of-entry calculus for supplement and personal care formulators entering the European market. Bayer AG leverages its pharmaceutical heritage to sustain credibility in regulated nutraceutical categories. Danone anchors its position through fermented dairy and plant-based wellness portfolios with deep European retail penetration.
Health and wellness encompasses consumer goods and services designed to maintain or improve physical, mental, and nutritional wellbeing, spanning ingestible supplements with specified micronutrient concentrations, exercise apparatus with biomechanical safety ratings, and dermatologically tested topical formulations. Nutritional Supplements occupies the largest margin pool due to repeat-purchase loyalty and clinical positioning, while Wellness Services demonstrates the fastest structural ascent as employers outsource corporate health programming. Fitness Equipment retains maturity in Nordic markets where home-gym penetration already saturates households.
EMA oversight governs borderline pharmaceutical-nutraceutical claims, ECHA chemical safety protocols dictate preservative and additive thresholds, and CSRD reporting obligations force corporates to document wellness program ESG outcomes. These frameworks collectively elevate compliance spending but also filter low-credibility entrants from shelf space competition. Stakeholders must monitor evolving EU AI Act implications for algorithmic fitness coaching and personalized nutrition platforms before committing platform development budgets.
Market Dynamics
REACH compliance costs are restructuring entry economics for supplement and personal care formulators, while the EU Green Deal mandates ingredient provenance transparency that favors established European supply chains over opportunistic importers.
Growth Catalysts
- CSRD reporting obligations:Mandated corporate wellness program disclosures are accelerating employer outsourcing to third-party wellness service providers across Germany, France, and the Netherlands.
- Aging demographics:Germany's 65-plus population concentration sustains premium-priced nutritional supplement consumption with repeat-purchase loyalty unmatched in younger cohorts.
- Biomechanical safety ratings:Standardized EU certification for home fitness equipment is reducing consumer risk perception and expanding Nordic household penetration beyond saturation baselines.
Market Restraints
- Preservative threshold restrictions:ECHA chemical safety protocols limit shelf-life extension options for clean-label topical formulations, compressing margin structures for mid-tier personal care brands.
- Active ingredient concentration caps:EMA borderline pharmaceutical-nutraceutical claim oversight prevents clinical positioning for high-potency supplements, constraining premium pricing architecture.
- Plant protein input volatility:EU Green Deal sourcing requirements for fermented dairy alternatives expose Danone and competitors to weather-driven pea and oat supply disruptions from Baltic producers.
Strategic Opportunities
- Algorithmic fitness coaching:The EU AI Act's pending implementation creates first-mover advantage for platforms documenting algorithmic transparency before compliance mandates harden.
- Eastern European corporate wellness:Poland and Romania exhibit employer program underpenetration below 15% participation rates against Western European 40% baselines.
- Personalized nutrition convergence:Microbiome testing integration with supplement subscription models is opening recurring-revenue architectures distinct from transactional retail.
Industry Challenges
- Clinical trial credentialing:EMA-recognized efficacy studies require 18-24 month timelines that outpace venture-funded competitor launch cycles, compressing innovation windows.
- Cross-border formulation harmonization:Divergent national interpretations of EFSA health claim approvals force SKU proliferation that fragments production scale economies.
- Legacy ERP integration:CSRD data capture requirements demand supply chain traceability upgrades that mid-cap wellness service providers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Health and Wellness Market |
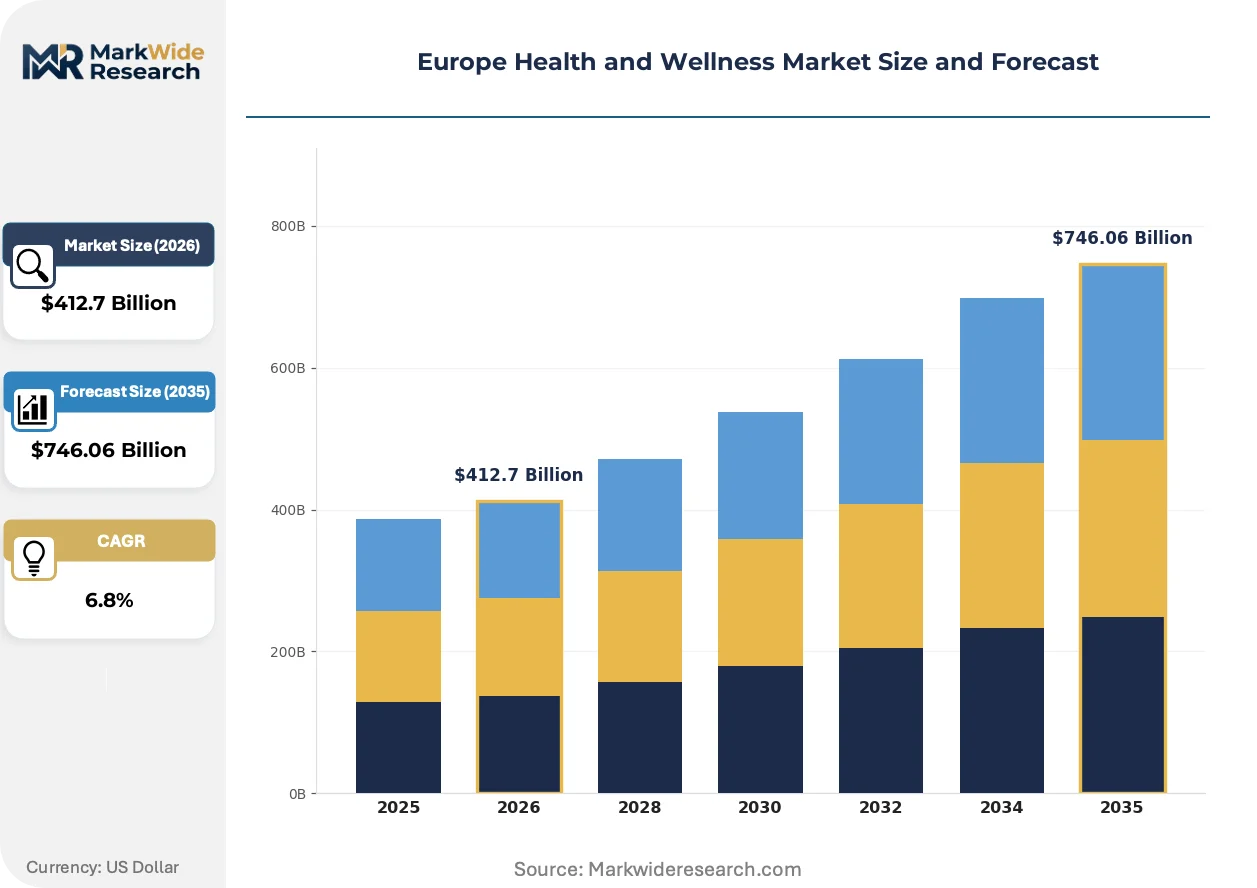
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $746.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Supplements, Fitness Equipment, Personal Care Products, Wellness Services End User: Consumers, Healthcare Providers, Corporates, Fitness Enthusiasts Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Price Tier: Premium, Mid-range, Budget, Discounted |
| Companies Covered | Nestlé Health Science, Bayer AG, Glanbia plc, Holland & Barrett Retail Ltd., Amway Corp., Herbalife Nutrition Ltd., Danone, Abbott Laboratories, Haleon Group of Companies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Health and Wellness Market Trends and Innovations
Digital biomarker integration and algorithmic personalization are compressing the gap between clinical-grade monitoring and consumer wellness products, while regulatory frameworks race to catch up with technical capability expansion.
Continuous glucose monitoring wearables are migrating from diabetic management to metabolic optimization for non-diabetic consumers. German and Swiss insurers are piloting premium discounts for subscribers sharing anonymized glucose data. This sensor proliferation is decentralizing nutritional advice authority from registered dietitians toward AI-powered platforms.
The EU AI Act's risk-classification framework for health-related algorithms is forcing wellness app developers to document training data provenance and decision transparency. Platforms offering personalized supplement recommendations face reclassification as high-risk systems requiring conformity assessments. French and Dutch regulators are issuing draft guidance ahead of full enforcement, compressing development timelines for algorithmic coaching products.
Employer procurement of wellness services is consolidating toward integrated platforms bundling mental health, fitness subsidies, and nutritional counseling. Single-vendor contracts are displacing point-solution vendor fragmentation in enterprise accounts above 5,000 employees. This concentration is most visible in Scandinavian markets where municipal employer purchasing cooperatives dominate public sector wellness spending.
Europe Health and Wellness Market Segmentation
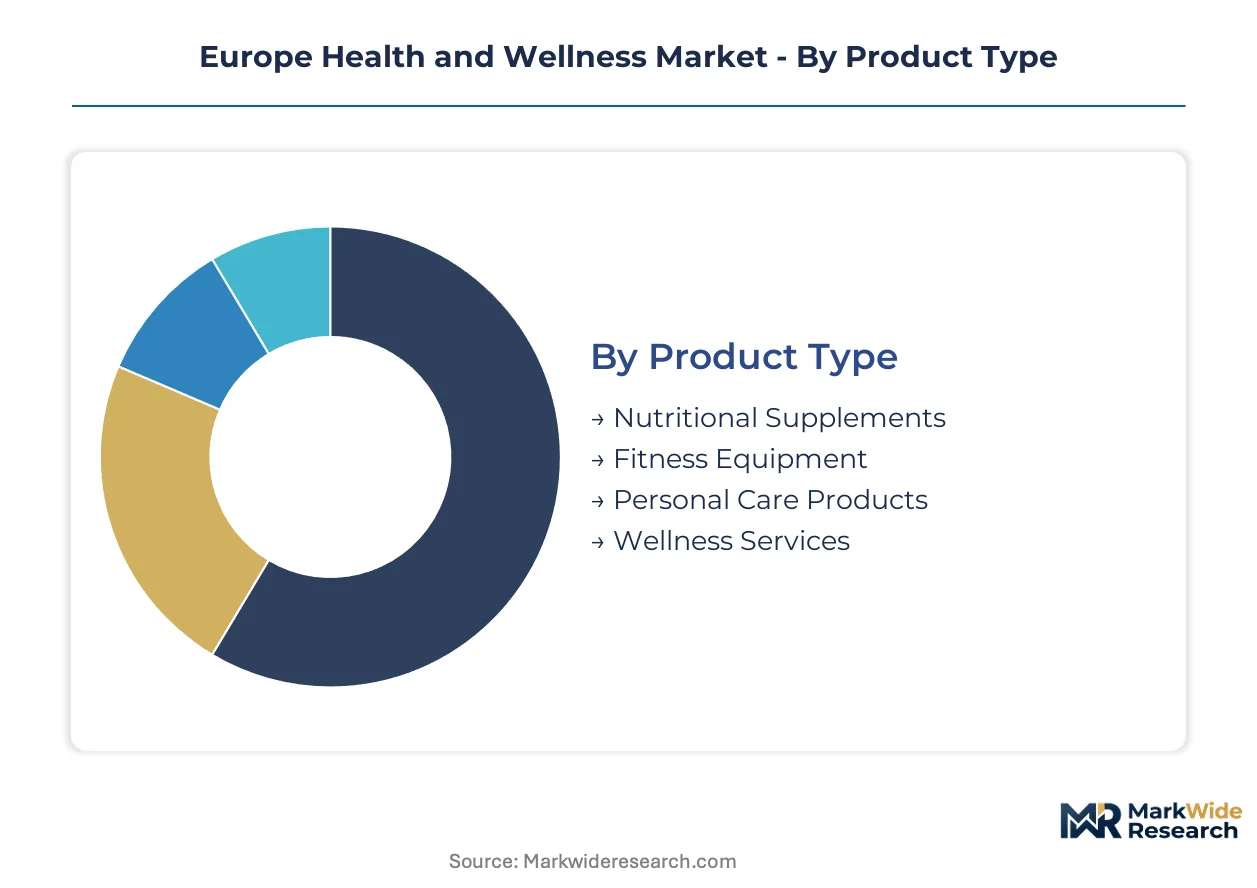
Segmentation in the Europe Health and Wellness Market reveals divergent compliance burdens and margin architectures across product categories. EMA oversight intensity and REACH formulation costs vary sharply by segment, reshaping competitive positioning for entrants versus established European players.
Product Type:
Buyers in this category differentiate by clinical credibility requirements and repeat-purchase frequency rather than unit economics alone.
- Nutritional Supplements:Ingestible products with specified micronutrient concentrations, including vitamins, minerals, and botanical extracts subject to EFSA health claim scrutiny. Germany's aging demographics sustain premium-priced subscription models with unmatched repeat-purchase loyalty among 65-plus cohorts. EMA borderline pharmaceutical oversight constrains clinical positioning for high-potency formulations.
- Wellness Services:Employer-procured programming spanning mental health support, fitness subsidies, and nutritional counseling delivered through integrated platforms. CSRD reporting obligations across Germany, France, and the Netherlands are accelerating corporate outsourcing to third-party providers. Single-vendor contracts now displace point-solution fragmentation in enterprise accounts above 5,000 employees.
- Fitness Equipment:Biomechanical apparatus with standardized EU safety certification for home and commercial deployment.
- Personal Care Products:Dermatologically tested topical formulations with clean-label positioning and preservative restrictions under ECHA protocols.
Nutritional Supplements leads volumes today; Wellness Services is gaining share fastest.
End User:
Procurement authority and reimbursement pathways separate these buyer groups more than price sensitivity alone.
- Corporates:Employer purchasers of wellness programming driven by CSRD-mandated ESG outcome documentation and insurance premium optimization. Municipal purchasing cooperatives in Scandinavian markets concentrate public sector spending toward integrated platform vendors.
- Consumers:Individual purchasers making direct-to-consumer supplement and equipment decisions, with German and Swiss insurers piloting premium discounts for metabolic data sharing.
- Healthcare Providers:Clinical settings prescribing or recommending wellness interventions with formal reimbursement codes.
- Fitness Enthusiasts:Dedicated amateur athletes and home-gym owners prioritizing biomechanical safety ratings and Nordic brand heritage.
Consumers anchor current revenue; Corporates show the steepest expansion trajectory as CSRD enforcement hardens.
Distribution Channel:
Traceability requirements and margin retention divide these channels under EU Green Deal sourcing mandates.
- Online Retail:Direct-to-consumer platforms capturing algorithmic personalization and subscription recurring revenue, with EU AI Act risk classification pending for health-related recommendation engines. French and Dutch regulators are issuing draft guidance ahead of full enforcement.
- Specialty Stores:Curated physical retail with trained staff and premium positioning, concentrated in German urban centers and Swiss wellness clusters.
- Supermarkets:Mass-market shelf space for mid-tier supplements and personal care with clean-label visibility.
- Pharmacies:Regulated channel for borderline pharmaceutical-nutraceutical products requiring EMA-recognized efficacy credentials.
Online Retail commands the fastest volume growth; Pharmacies retain the highest margin per unit.
Price Tier:
Certification grade and supply chain transparency separate these tiers more than raw ingredient cost.
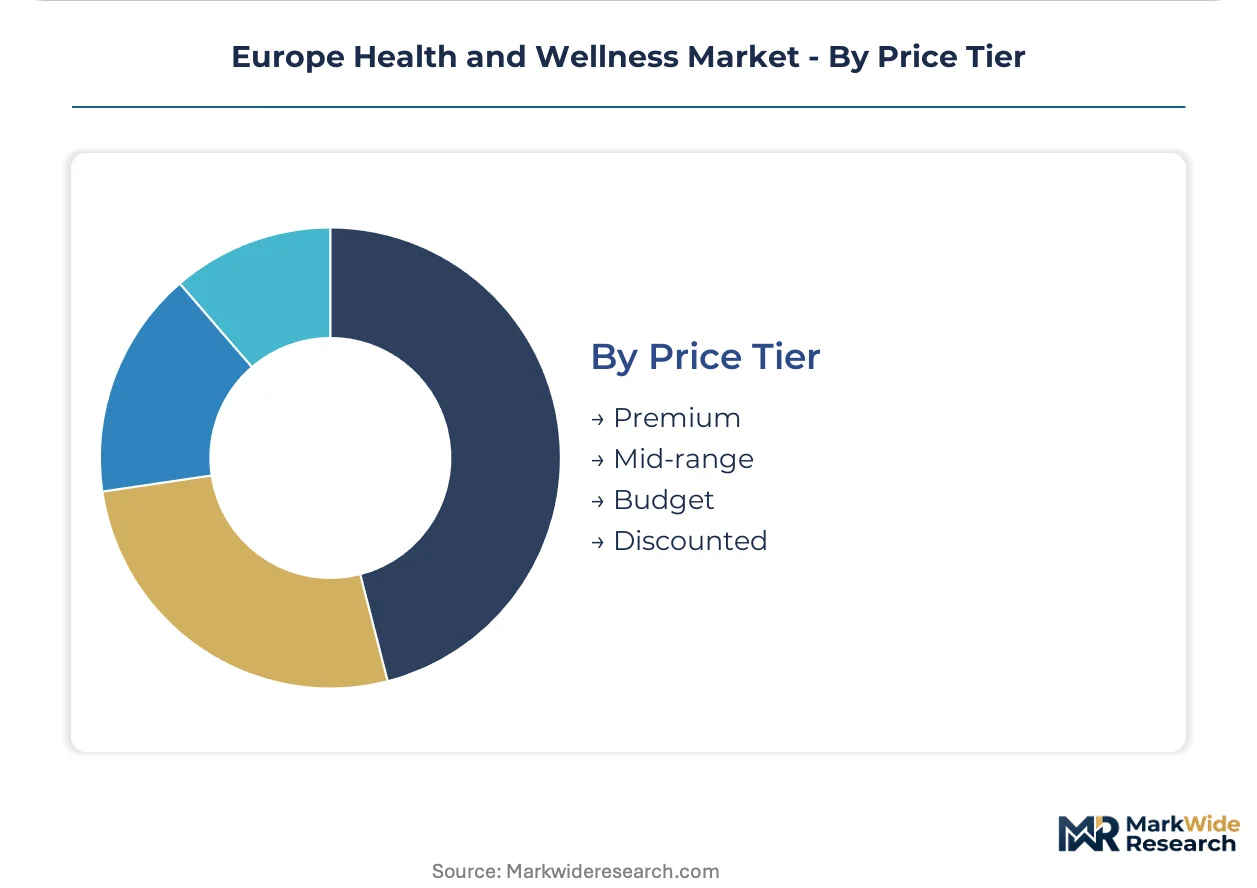
- Premium:Products with EFSA-approved health claims, organic certification, and Baltic-sourced plant protein inputs under EU Green Deal traceability. REACH compliance documentation and clinical trial credentialing justify pricing architecture.
- Mid-range:Established brands with retail penetration but limited clinical positioning, facing margin compression from preservative threshold restrictions.
- Budget:Price-competitive formulations with basic safety compliance, vulnerable to ECHA chemical safety protocol upgrades.
- Discounted:Promotional and private-label offerings with minimal differentiation, concentrated in supermarket channels.
Premium dominates revenue contribution; Mid-range is losing share to tier polarization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce concentration in pharmaceutical and nutritional science expertise anchors regional demand patterns across Europe. Germany, Switzerland, and the Netherlands host dense clusters of formulation chemists and regulatory specialists. These talent pools sustain premium wellness product development and compliance infrastructure.
Germany
Germany's 65-plus demographic concentration drives premium supplement subscription models with unmatched repeat-purchase loyalty. EMA borderline pharmaceutical oversight constrains clinical positioning for high-potency formulations. The Rhine-Main and Bavarian clusters concentrate corporate wellness procurement and fermented dairy alternative production.
United Kingdom
London's financial services workforce sustains employer-funded wellness platform adoption at enterprise scale. CSRD-aligned ESG reporting mandates accelerate outsourcing to integrated mental health and fitness providers. The Oxford-Cambridge corridor anchors personalized nutrition startups bridging microbiome testing with supplement subscriptions.
France
France's pharmacy-dominant distribution channel preserves margin structures for EFSA-approved health claim products. ANSM and CNIL draft guidance on EU AI Act implementation compresses development timelines for algorithmic coaching platforms. The Île-de-France region concentrates digital health venture funding and insurer wellness pilot programs.
Netherlands
Dutch municipal employer purchasing cooperatives concentrate public sector wellness spending toward integrated platform vendors. ECHA chemical safety protocols limit preservative options for clean-label topical formulators. The Randstad corridor hosts corporate headquarters for fermented dairy alternative specialists exposed to Baltic plant protein supply volatility.
Switzerland
Swiss insurers pilot premium discounts for subscribers sharing anonymized continuous glucose monitoring data. Swissmedic oversight governs borderline pharmaceutical-nutraceutical claims with stricter thresholds than EU baselines. The Zurich-Geneva axis concentrates precision nutrition research and luxury wellness brand headquarters.
Europe Health and Wellness Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Pharmaceutical heritage players leverage clinical credibility in regulated nutraceutical categories, while consumer goods multinationals exploit retail shelf access and supply chain scale. Three archetypes dominate: legacy pharma-nutrition hybrids, dairy-rooted fermented wellness platforms, and direct-to-consumer subscription specialists. Competitive moves concentrate on M&A for microbiome testing capabilities and strategic partnerships for Baltic plant protein supply security.
Among pharmaceutical-rooted conglomerates, Bayer AG and Abbott Laboratories exemplify clinical credibility positioning in EMA-scrutinized categories. Danone occupies a distinct archetype as a dairy-origin multinational with deep European retail penetration in fermented and plant-based wellness portfolios. Glanbia plc represents the pure-play nutrition specialist model with focused exposure to supplement ingredients and sports nutrition.
| Leading Market Players |
|---|
| Nestlé Health Science |
| Bayer AG |
| Glanbia plc |
| Holland & Barrett Retail Ltd. |
| Amway Corp. |
| Herbalife Nutrition Ltd. |
| Danone |
| Abbott Laboratories |
| Haleon Group of Companies |
| Others |
Pricing and Supply Chain Analysis
CSRD-mandated corporate wellness program disclosures across Germany, France, and the Netherlands are compressing procurement timelines and forcing suppliers to absorb compliance documentation costs into contract pricing. This buyer-driven specification shift elevates tier-one platform vendors while squeezing mid-tier service providers unable to front-load traceability investments.
Pricing Analysis
Bundled corporate wellness platform contracts now command 15-25% per-employee cost premiums over fragmented point-solution procurement. Price differentiation rests on EFSA health claim certification tier and algorithmic transparency documentation under pending EU AI Act guidance. Pricing pressure stems from REACH compliance cost absorption demands from German and Dutch enterprise buyers. Mid-range supplement brands face acute price sensitivity as preservative threshold restrictions compress formulation flexibility without clinical trial credentials to justify premium positioning.
Supply Chain Analysis
REACH certification and EFSA health claim qualification gating concentrate viable ingredient sourcing in Germany, Switzerland, and the Netherlands. Baltic region pea and oat protein inputs feed fermented dairy alternative production, drawing from weather-exposed agricultural zones. Single-source vulnerability runs through Baltic plant protein supply channels exposed to climate-driven yield volatility. Distribution runs through pharmacy-dominant channels in France and integrated online retail platforms capturing algorithmic personalization subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's health and wellness market functions as a geographic-arbitrage play where regulatory compliance cost differentials between Western and Eastern European operational bases create 20-30% margin expansion opportunities for supply chain relocation.
For Market Incumbents: To counter algorithmic fitness coaching platform entrants from venture-funded startups, Bayer AG and pharmaceutical heritage peers must accelerate microbiome testing capability acquisition and lock in Baltic plant protein supply through long-term offtake agreements with Estonian and Latvian producers. Certification investment in EFSA-approved health claims for high-potency formulations defends margin architecture against clean-label commoditization. For New Entrants and Emerging Players: CSRD reporting obligations in Germany, France, and the Netherlands open a window for integrated wellness platform providers to displace fragmented point-solution vendors in enterprise accounts above 5,000 employees. Poland and Romania corporate wellness underpenetration below 15% participation rates offers the most penetrable white-space geography. Direct-to-consumer microbiome testing integration with supplement subscription models provides the strongest go-to-market angle for recurring revenue capture. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play algorithmic coaching platforms possessing documented training data provenance ahead of EU AI Act high-risk system classification. Five-to-ten year viability favors specialists with captive supply chain relationships to Baltic plant protein producers and EFSA health claim credential portfolios. The signal to watch is French and Dutch regulator draft guidance finalization on algorithmic transparency requirements for personalized nutrition recommendation engines.| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome Testing Acquisition | Captures recurring-revenue subscription architecture distinct from transactional retail channels. |
| Baltic Plant Protein Supply Agreement | Secures EU Green Deal-compliant input traceability against weather-driven yield volatility exposure. |
| EFSA Health Claim Certification Investment | Unlocks pharmacy channel access and premium pricing tier eligibility in France and Germany. |
| Algorithmic Transparency Documentation | Pre-positions platforms ahead of EU AI Act high-risk system conformity assessment mandates. |
| Eastern European Corporate Wellness Expansion | Exploits Poland and Romania employer program underpenetration against Western European baselines. |
Research Methodology
Multiple input streams — executive interviews with wellness platform procurement officers, formulation chemists at German and Swiss nutraceutical manufacturers, and Baltic agricultural supply specialists — were reconciled against EFSA health claim registration databases, REACH compliance filing records, and CSRD corporate disclosure repositories. Secondary validation drew from EU AI Act draft guidance documents, ECHA chemical safety protocol amendments, and enterprise wellness contract award announcements. Bottom-up segment sizing and top-down macroeconomic anchoring were triangulated to constrain variance.
Data-stream reconciliation across product type, end-user procurement authority, distribution channel traceability requirements, and price tier certification grade produced volume and value estimates across the projection horizon. CAGRs were derived from regression analysis against aging demographic trajectories, CSRD enforcement phase-in schedules, and algorithmic personalization adoption curves. Segment-level modeling incorporated EMA borderline pharmaceutical oversight intensity and EU Green Deal sourcing mandate compliance cost pass-through assumptions.
Revisions become necessary when EMA issues binding guidance on high-potency supplement classification thresholds, when Baltic climate patterns disrupt plant protein harvest yields, or when EU AI Act enforcement timelines accelerate beyond current draft guidance schedules. A model refresh is warranted upon material change in French and Dutch regulator algorithmic transparency final rule publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Yoga Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market