
 North America Fitness Rings Market | 2026-2036
North America Fitness Rings Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fitness Rings Market Analytics
Canadian sensor module production is expanding as North American manufacturers seek to reduce dependence on Asian component suppliers. Oura Health leverages its Finnish-North American operational base to sustain premium positioning in sleep analytics. Movano Health differentiates through medical-grade glucose monitoring integration. RingConn competes aggressively on price while occupying direct-to-consumer channels.
Fitness rings are titanium, ceramic, or silicone-encased wearable devices embedding photoplethysmography sensors, accelerometers, and temperature monitors to track heart rate variability, sleep architecture, and activity metrics. Smart rings lead the product type landscape due to multifunction sensor fusion, while health monitoring rings capture concentrated margin pools from chronic disease management applications. Titanium dominates the material segment for durability-conscious athletes, whereas silicone variants penetrate the casual user base through lower price points.
FDA regulates pulse oximetry and electrocardiogram functionality as Class II medical devices, compelling manufacturers to navigate 510(k) premarket notification pathways. FCC governs Bluetooth and NFC radio emissions, shaping connectivity architecture decisions for cross-border Canadian and US sales. Health Canada and the FDA's parallel review pilot for digital health devices is streamlining market access. Stakeholders must monitor evolving HIPAA compliance obligations as employers integrate ring-generated biometric data into group health plans.
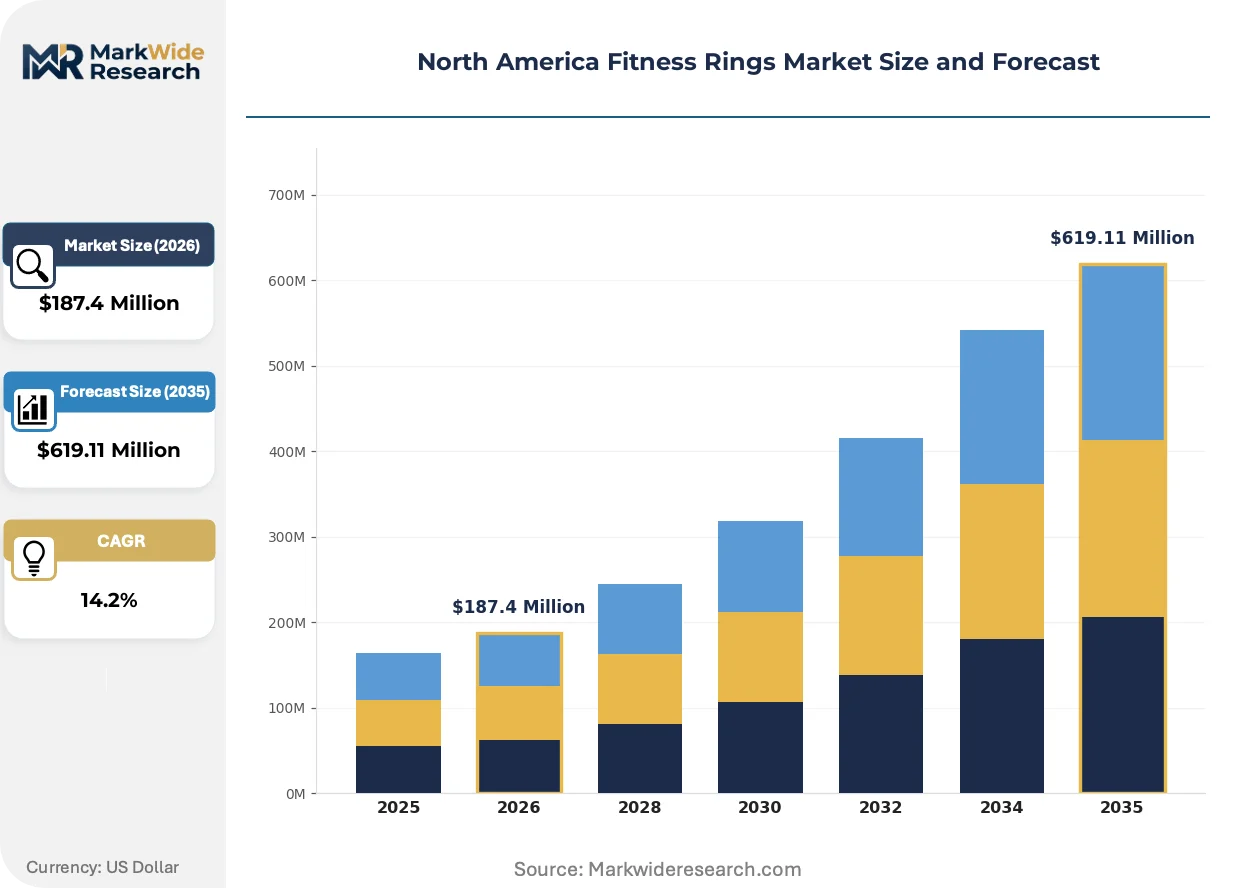
Market Dynamics
FDA's parallel review pilot with Health Canada is compressing 510(k) clearance timelines for pulse oximetry-enabled rings, while corporate wellness procurement concentrates demand in California and Ontario tech corridors.
Growth Catalysts
- Corporate Wellness Procurement:United States employers are embedding fitness rings into group health plans as biometric screening tools. HIPAA compliance frameworks now accommodate wearable-generated data streams.
- 510(k) Pathway Streamlining:FDA's digital health pre-certification program is accelerating market access for sleep staging algorithms. Health Canada participation reduces duplicate testing burdens.
- Photoplethysmography Sensor Maturation:Multi-wavelength PPG modules achieve clinical-grade accuracy at consumer price points. Titanium-encased designs penetrate durability-sensitive athletic segments.
Market Restraints
- Asian Component Dependence:North American manufacturers rely on concentrated Asian suppliers for MEMS accelerometers and optical sensor arrays. Geopolitical friction elevates inventory carrying costs.
- Class II Device Friction:FDA's 510(k) requirements for pulse oximetry functionality impose documentation burdens that stretch development budgets. Smaller entrants face capital constraints.
- Smartwatch Substitution:Apple Watch and Garmin devices capture overlapping health-monitoring use cases with established brand equity. Ring form factor limits display and interaction capabilities.
Strategic Opportunities
- Chronic Disease Management Integration:United States Medicare Advantage plans are reimbursing remote patient monitoring devices. Fitness rings with medical-grade glucose correlation unlock B2B2C channels.
- Canadian Manufacturing Reshoring:Ontario and Quebec sensor module facilities offer tariff-advantaged supply chains for US market access. Federal procurement incentives favor domestic content.
- Sleep Architecture Monetization:Employer-sponsored sleep coaching programs generate recurring revenue streams. Oura Health's subscription model demonstrates pricing power in wellness-adjacent services.
Industry Challenges
- Algorithm Validation Talent Scarcity:Machine learning engineers with FDA submission experience command premium compensation. Universities produce insufficient graduates with dual biostatistics-regulatory expertise.
- HIPAA Technical Safeguards Complexity:Employer-integrated ring data triggers business associate agreement obligations. Encryption standards for biometric transmission exceed consumer electronics norms.
- Cross-Border Certification Synchronization:FCC Part 15 and ISED Canada radio emission testing requires duplicate lab work. Bluetooth Low Energy certification timelines delay synchronized product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fitness Rings Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Rings, Health Monitoring Rings, Sports Rings, Connected Rings Material: Silicone, Titanium, Stainless Steel, Ceramic End User: Athletes, Fitness Enthusiasts, Health-conscious Individuals, Casual Users Connectivity: Bluetooth, Wi-Fi, NFC, Cellular |
| Companies Covered | Oura Health, Movano Health, Ultrahuman Healthcare, Fitbit, Samsung Electronics, RingConn, Motiv, Mclear, Circular, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fitness Rings Market Evolving Landscape
Multi-sensor fusion architectures are redefining competitive differentiation in North American fitness rings, with medical-grade accuracy claims now table stakes for premium positioning.
Photoplethysmography is consolidating as the dominant biosensing modality for continuous heart rate and blood oxygen monitoring. United States-based athletes and quantified-self enthusiasts are adopting titanium-encased multi-wavelength PPG rings at accelerating rates. This technology is consolidating market share around vendors with proprietary signal processing algorithms, compressing margins for hardware-only competitors.
Health Canada's Medical Devices Directorate is harmonizing software-as-a-medical-device classification with FDA's 510(k) framework. Canadian and United States manufacturers now submit parallel premarket notifications for sleep staging and arrhythmia detection features. Chronic disease management rings targeting Medicare Advantage reimbursement face accelerated compliance timelines under this bilateral alignment.
Direct-to-consumer subscription bundling is displacing one-time hardware transactions as the dominant revenue model. California's Bay Area tech employers are purchasing annual Oura Health memberships alongside bulk device procurement. This shift concentrates customer lifetime value in software and coaching services rather than sensor hardware margins.
North America Fitness Rings Market Segmentation
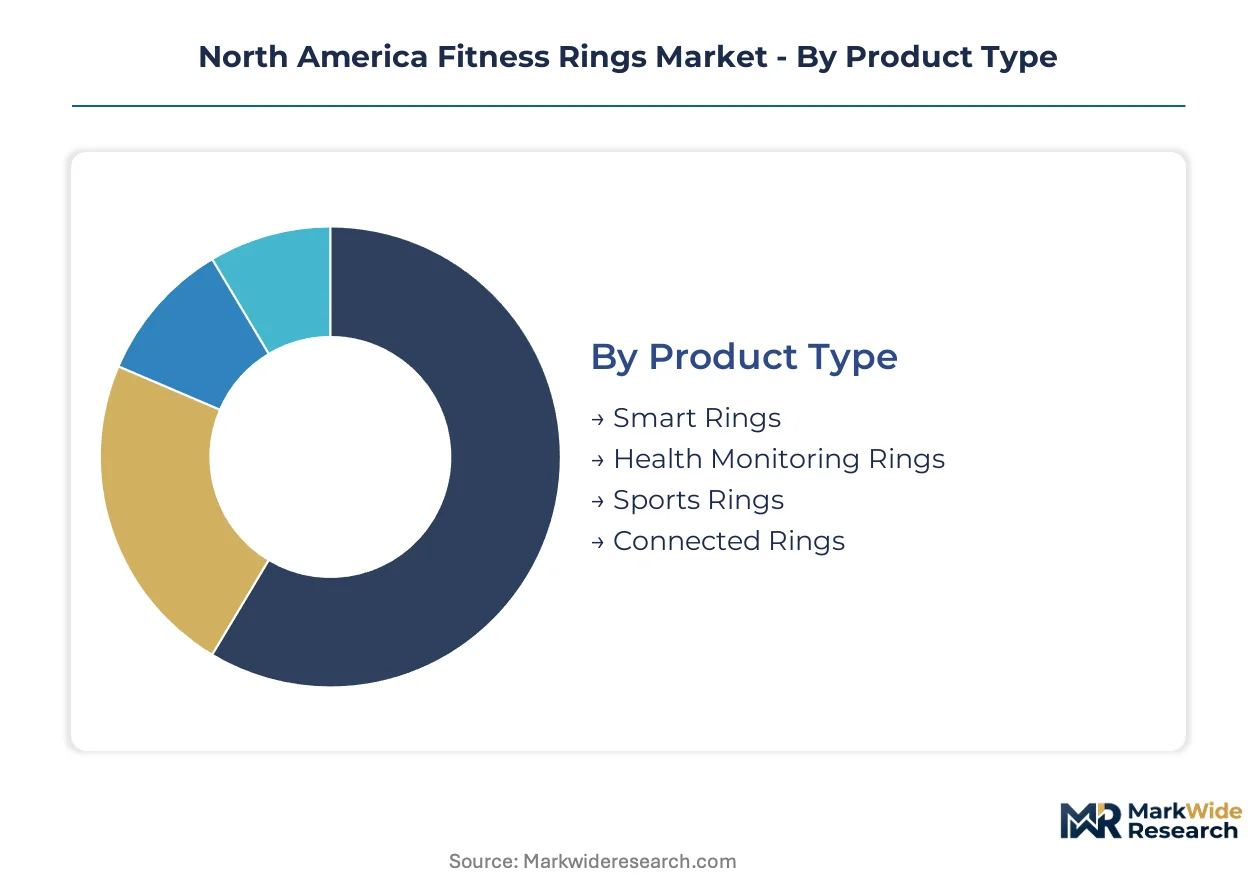
Fitness ring segmentation in North America reflects divergent regulatory pathways and pricing architectures. FDA Class II clearance requirements split the market between wellness-adjacent consumer devices and reimbursable medical monitors.
Product Type:
FDA 510(k) obligations vary sharply across this category, with pulse oximetry-enabled segments facing Class II documentation burdens that wellness-only variants bypass entirely.
- Smart Rings:Multi-sensor fusion devices embedding photoplethysmography, accelerometry, and temperature monitoring in titanium or ceramic housings. California's Bay Area tech employers are procuring these in bulk for corporate wellness programs, driving concentrated B2B demand despite HIPAA compliance overhead.
- Health Monitoring Rings:Medical-grade form factors targeting chronic disease management with arrhythmia detection and sleep staging algorithms. Medicare Advantage reimbursement eligibility in the United States is unlocking B2B2C distribution through payer networks, though FDA premarket notification timelines stretch 12-18 months.
- Sports Rings:Durability-optimized titanium designs for quantified-self athletes requiring impact resistance and extended battery life.
- Connected Rings:NFC-enabled variants prioritizing contactless payment and access control over biometric depth.
Leading the category by volume: Smart Rings. Growing fastest: Health Monitoring Rings.
Material:
Cost tier architecture separates premium medical-grade finishes from mass-market elastomer alternatives, with manufacturing location determining tariff exposure under USMCA rules.
- Titanium:Aerospace-grade Ti-6Al-4V alloys dominate durability-sensitive athletic and clinical segments. Ontario-based CNC machining facilities are capturing reshoring demand from US manufacturers seeking supply chain de-risking.
- Silicone:Medical-grade elastomers penetrate price-sensitive casual user bases through sub-premium direct-to-consumer channels. Injection molding concentrates in Shenzhen-dependent supply chains, elevating inventory carrying costs amid geopolitical friction.
- Stainless Steel:316L surgical steel variants occupy mid-tier positioning with corrosion resistance for humid climates.
- Ceramic:Zirconia-based housings offer scratch resistance and hypoallergenic properties for dermatologically sensitive users.
Titanium commands the premium tier by margin. Silicone dominates unit volume.
End User:
Customer type stratification mirrors reimbursement eligibility and employer subsidy availability across United States and Canadian markets.
- Health-conscious Individuals:Self-directed quantified-self adopters purchasing premium titanium devices with subscription sleep coaching services. The Greater Toronto Area's health-tech startup ecosystem generates concentrated early-adopter demand for clinical-grade accuracy claims.
- Athletes:Durability-focused competitive and recreational users requiring impact-rated titanium housings and multi-sport algorithm libraries. NCAA and professional team procurement is emerging as a volume channel.
- Fitness Enthusiasts:Gym-centric users prioritizing activity tracking over medical-grade validation.
- Casual Users:Price-driven entrants seeking basic step and sleep metrics in silicone form factors.
Health-conscious Individuals generate the highest customer lifetime value. Athletes are expanding most quickly.
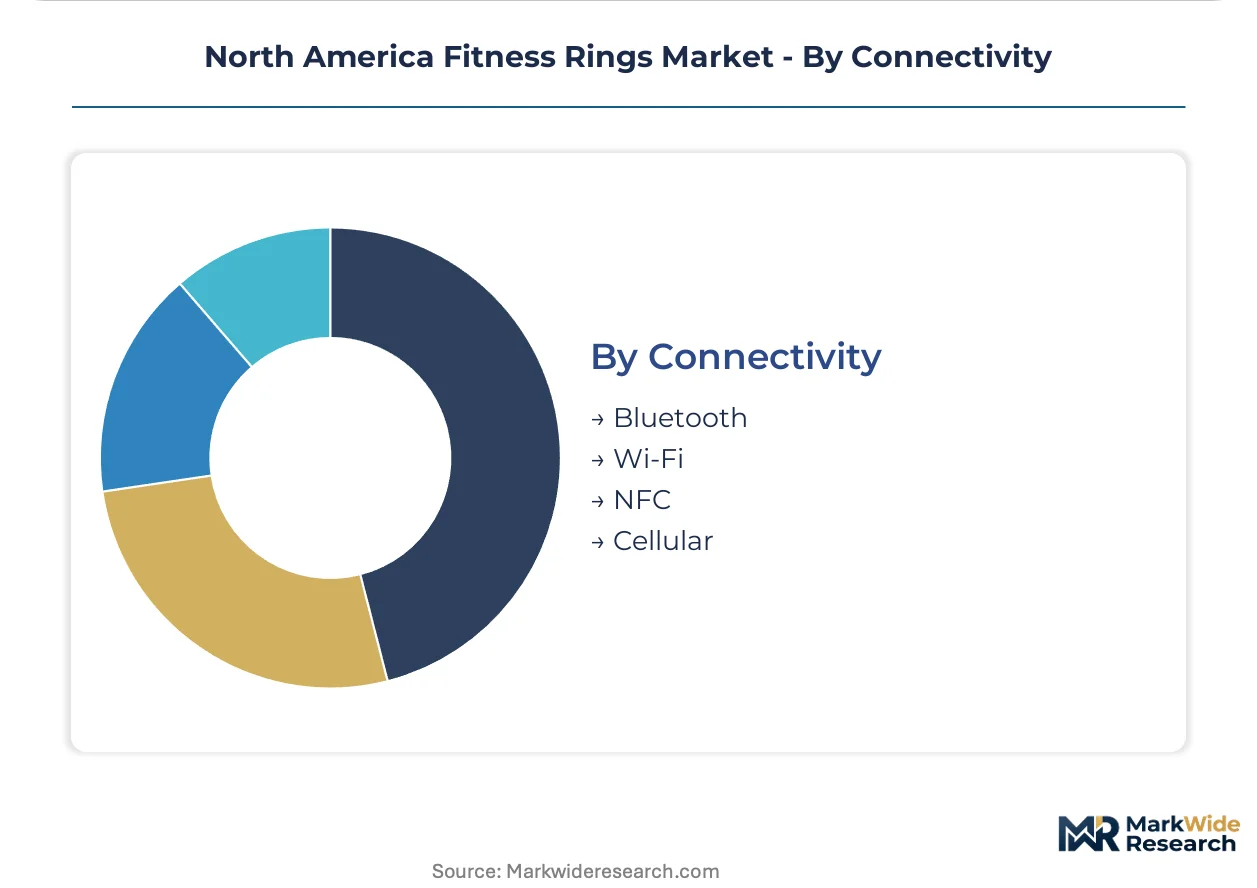
Connectivity:
Radio emission certification requirements split this category between FCC Part 15 simplicity and cellular module complexity with associated carrier certification burdens.
- Bluetooth:Low Energy 5.0 modules dominate with minimal FCC compliance overhead and sub-10mW power draw enabling multi-day battery life. Cross-border US-Canadian sales require parallel ISED Canada testing, compressing synchronized launch timelines.
- NFC:13.56MHz contactless payment and access control integration requires payment network certification (Visa, Mastercard, Amex) beyond baseline FCC emission compliance.
- Wi-Fi:2.4GHz and 5GHz variants enable cloud synchronization without smartphone tethering but impose steeper power budgets.
- Cellular:LTE-M and NB-IoT modules for standalone remote patient monitoring applications trigger PTCRB and carrier-specific certification requirements.
Bluetooth leads by installed base. Cellular is gaining share fastest in chronic disease management deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's sensor module foundries anchor North American supply chain restructuring as manufacturers seek tariff-advantaged production corridors. The regional landscape fragments across three national jurisdictions with divergent regulatory harmonization timelines and employer-sponsored procurement intensity.
United States
California's Bay Area tech employers are procuring fitness rings in bulk for corporate wellness programs, driving concentrated B2B demand despite HIPAA compliance overhead. FDA's 510(k) premarket notification pathways for pulse oximetry-enabled devices stretch development timelines to 12-18 months. Greater Boston's health-tech cluster is emerging as a secondary demand center for clinical-grade sleep analytics.
Canada
Ontario and Quebec sensor module facilities are capturing reshoring demand from US manufacturers seeking supply chain de-risking under USMCA rules. Health Canada's parallel review pilot with FDA is compressing dual certification timelines for sleep staging algorithms. The Greater Toronto Area's health-tech startup ecosystem generates concentrated early-adopter demand for medical-grade accuracy claims.
Mexico
Baja California's electronics assembly corridors are attracting North American fitness ring manufacturers seeking proximity to US distribution networks. Mexico's national medical device regulator requires alignment with FDA Class II standards for pulse oximetry imports. Mexico City Metro's corporate sector is piloting employer-sponsored wellness programs with wearable biometric screening tools.
North America Fitness Rings Market Competitive Landscape
Global majors compete with regional champions across certification depth and reimbursement eligibility. The vendor base stratifies into three tiers: medical-grade specialists pursuing FDA 510(k) clearances, wellness-adjacent consumer brands, and price-aggressive direct-to-consumer entrants. Strategic archetypes include sleep analytics specialists, chronic disease management integrators, and durability-focused athletic variants. Dominant competitive moves encompass Canadian manufacturing reshoring for tariff advantage and subscription bundling to capture recurring revenue streams.
Among Nordic-originated specialists, Oura Health exemplifies the premium sleep analytics archetype through its Finnish-North American operational base. Movano Health occupies a position within the medical-grade glucose monitoring integration tier. RingConn sits within the price-aggressive direct-to-consumer vector, competing through lower price points and digital-native distribution channels.
| Leading Market Players |
|---|
| Oura Health |
| Movano Health |
| Ultrahuman Healthcare |
| Fitbit |
| Samsung Electronics |
| RingConn |
| Motiv |
| Mclear |
| Circular |
| Others |
Value Network & Pricing Analysis
Photoplethysmography sensor module miniaturization is collapsing unit economics for titanium-encased devices while simultaneously dispersing manufacturing capacity from Shenzhen-dependent clusters toward tariff-advantaged North American facilities. This dual shift compresses hardware margins at the economy tier while elevating pricing power for clinical-grade variants with FDA 510(k) clearance.
Pricing Analysis
Extended warranty and sleep coaching subscription bundles now separate premium Oura Health positioning from unbundled hardware-only competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA certification status and titanium versus silicone material grade. Cost compression in silicone variants is intensifying because RingConn's direct-to-consumer aggression forces margin sacrifice. Casual users in the sub-premium segment exhibit highest price sensitivity, whereas Medicare Advantage-integrated health monitoring rings face inelastic demand from chronic disease management programs.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale corporate wellness procurement from California Bay Area tech employers, while distributor networks serve fragmented health-conscious individual demand. Component sourcing draws from Taiwan for MEMS accelerometers, South Korea for optical sensor arrays, and Ontario for reshoring-tariff-advantaged titanium machining. Single-source vulnerability concentrates in Shenzhen-dependent silicone injection molding for economy-tier housings. Distribution runs through medical device distributors for FDA-cleared health monitoring rings and Amazon-direct for wellness-adjacent consumer variants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into sensor module fabrication and algorithm development capabilities is becoming the defining competitive race, with Ontario and Quebec facilities offering the most credible near-term captive supply option for US market access.
For Market Incumbents: Acquire FDA regulatory submission expertise and Health Canada parallel review capabilities to compress dual-certification timelines. Build captive titanium CNC machining capacity in Ontario to neutralize USMCA tariff exposure. Smartwatch substitution from Apple and Garmin represents the core threat requiring defensive certification depth.
For New Entrants and Emerging Players: FDA's digital health pre-certification program in the United States opens a window for streamlined 510(k) pathway navigation by algorithm-native startups. Target Medicare Advantage reimbursement-eligible health monitoring rings as the most penetrable white space. Pursue B2B2C distribution through payer networks rather than saturated direct-to-consumer channels.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by smartwatch incumbents seeking ring-form-factor biometric depth. Long-term viability favors vertically integrated players with captive Ontario sensor supply and proprietary sleep staging algorithms. Watch for Health Canada-FDA harmonization completion as inflection signal for accelerated M&A timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses 12-18 month clearance timelines for pulse oximetry-enabled rings through pre-certification program participation. |
| Ontario Manufacturing Reshoring | Captures tariff-advantaged USMCA supply chains for titanium sensor module assembly. |
| Subscription Service Bundling | Shifts revenue mix from one-time hardware margins to recurring sleep coaching and wellness analytics. |
| Medicare Advantage Reimbursement Strategy | Unlocks B2B2C distribution through payer networks for chronic disease management applications. |
| Health Canada Parallel Review Participation | Reduces duplicate testing burdens for synchronized US-Canadian product launches. |
Research Methodology
Independent corroboration across primary interviews with wearable device engineering leads, FDA regulatory affairs specialists, corporate wellness procurement managers, and Medicare Advantage plan directors underwrites the qualitative findings. Secondary validation draws from FDA 510(k) premarket notification databases, Health Canada medical device licenses, CMS Medicare Advantage reimbursement filings, and USMCA tariff schedule documentation. Bottom-up unit demand modeling triangulates against top-down corporate wellness spend allocation estimates.
Historical reference periods spanning pre-pandemic baseline through recent corporate wellness procurement acceleration anchor the projection horizon. The analytical framework segments by product type, material grade, end user archetype, and connectivity protocol across the modeling period. CAGRs derive from fitted growth curves incorporating photoplethysmography sensor cost decline trajectories and FDA clearance timeline compression assumptions. Medicare Advantage reimbursement expansion and Health Canada-FDA harmonization progress serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for non-invasive glucose monitoring correlation would alter the outlook. Forecasts reflect documented assumptions regarding corporate wellness penetration rates and regulatory harmonization timelines. Algorithm validation talent scarcity and geopolitical friction in Asian component supply represent specific stress factors requiring periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fitness Equipment
Global Jumping Rope Market
Fitness Equipment
Belt Trainers Market
Fitness Equipment
US Fitness Rings Market
Fitness Equipment
Europe Fitness Rings Market
Fitness Equipment
Mexico Outdoor Fitness Equipment Market
Fitness Equipment
Recumbent Stationary Bikes Market
Fitness Equipment
Lung Exercise Machine Market
Fitness Equipment
Weight Training Benches Market
Fitness Equipment
Latin America Fitness Ring Market
Fitness Equipment
Smart Scales Market
Fitness Equipment
GCC Fitness Ring Market
Fitness Equipment
Gymnastic Springboard Market
Fitness Equipment
Gym Fitness Accessories Market
Fitness Equipment
Functional Fitness Equipment Market
Fitness Equipment
Exercise Band Market
Fitness Equipment
China Outdoor Fitness Equipment Market