
 Weight Loss and Weight Management Market | 2026-2036
Weight Loss and Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Loss and Weight Management Market Intelligence
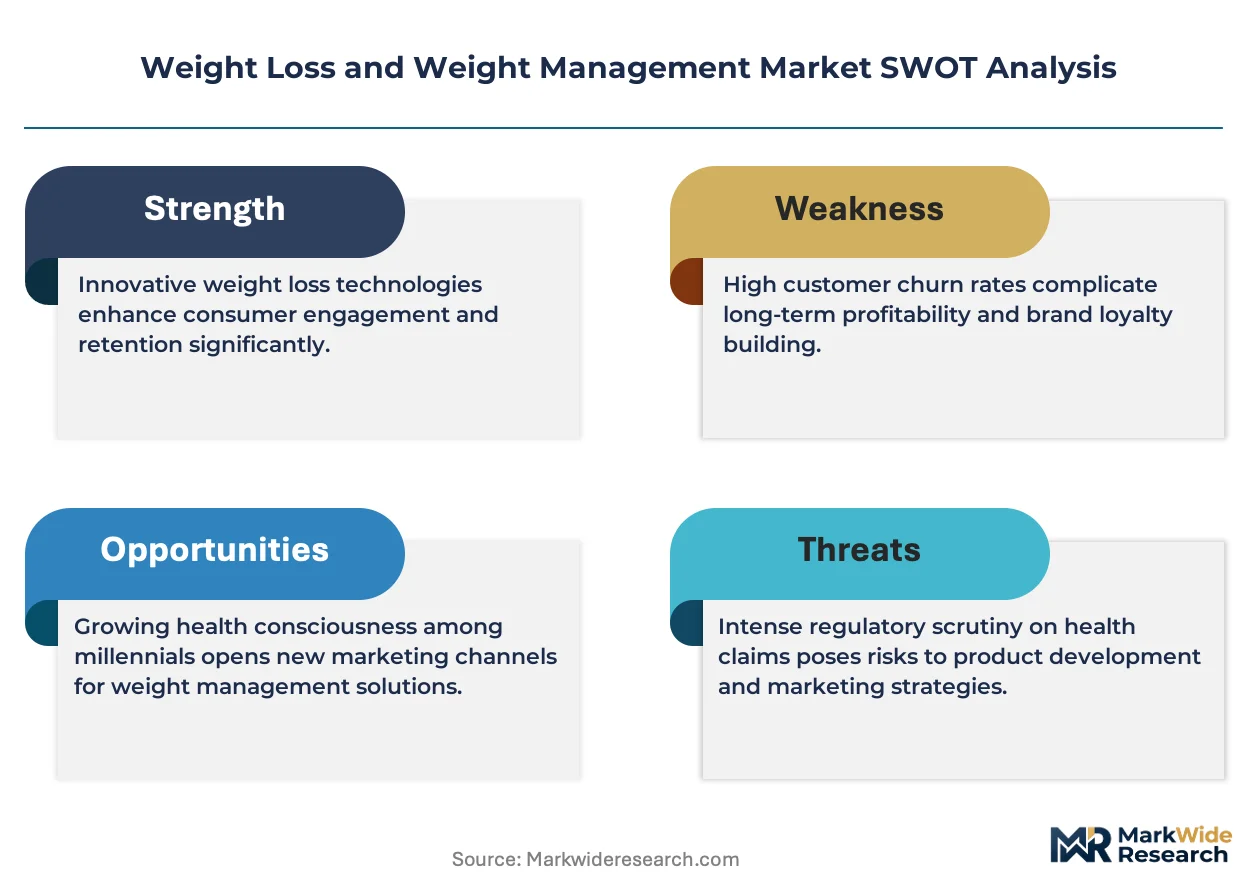
Subscription-based financing and asset-light platform models are reshaping competitive dynamics in weight management services. Novo Nordisk leverages its manufacturing scale to anchor supply of peptide-based therapies. WW International Inc. sustains member retention through behavioral economics tools. Noom Inc. differentiates via AI-driven meal logging and psychology-based coaching protocols.
Weight loss and weight management encompasses pharmacological interventions, nutritional formulations, digital behavior-modification platforms, and supervised clinical programs designed to reduce adiposity and maintain metabolic health through caloric deficit, macronutrient modulation, or appetite suppression. Dietary supplements occupy mature margin pools with established brand loyalty, while fitness apps represent the fastest-expanding segment driven by smartphone penetration and wearable integration. Meal replacements compete on convenience and protein fortification standards.
FDA oversees prescription drug approvals and labeling claims for anti-obesity medications, while EMA regulates market access across European jurisdictions through centralized assessment procedures. The Federal Trade Commission monitors advertising substantiation for over-the-counter supplements and digital health promises. Stakeholders must track evolving reimbursement decisions by CMS and national health technology assessment bodies that determine patient access and commercial viability of integrated care models.
Market Dynamics
GLP-1 receptor agonist manufacturing capacity constraints are redrawing competitive boundaries between pharmaceutical incumbents and contract peptide producers, compressing timelines for market entry while elevating raw material sourcing as a strategic priority.
Growth Catalysts
- FDA accelerated approval pathways:Compressed clinical trial requirements for obesity therapeutics are shortening development cycles and expanding eligible patient populations through streamlined efficacy demonstrations.
- Employer-sponsored wellness programs:Large US corporations are integrating prescription weight management into health benefit structures, creating institutional demand channels that bypass traditional retail pharmacy distribution.
- Continuous glucose monitoring integration:Wearable biosensor data streams are enabling real-time metabolic feedback loops that reinforce behavioral adherence and sustain long-term patient engagement.
Market Restraints
- Peptide API supply concentration:Active pharmaceutical ingredient production for GLP-1 analogs clusters among a limited set of European and Asian contract manufacturers, creating single-source vulnerabilities.
- Cold chain distribution requirements:Temperature-sensitive biologic therapies demand specialized logistics infrastructure that elevates per-dose fulfillment costs and limits rural pharmacy participation.
- Reimbursement uncertainty:CMS coverage determinations for anti-obesity medications remain inconsistent across Medicare Advantage plans, fragmenting patient access and distorting prescriber behavior.
Strategic Opportunities
- Behavioral economics platform integration:Digital health applications incorporating loss aversion framing and social accountability mechanisms are capturing employer contract opportunities previously held by traditional wellness vendors.
- Compounded pharmacy alternatives:FDA enforcement discretion around 503A compounding facilities is creating parallel supply channels for semaglutide formulations during branded product shortages.
- Metabolic health monitoring convergence:Integration of prescription therapy data with consumer wearable ecosystems is opening subscription revenue models that bridge clinical and lifestyle intervention boundaries.
Industry Challenges
- Peptide synthesis workforce scarcity:Specialized chemists capable of solid-phase peptide manufacturing command premium compensation, constraining capacity expansion at contract development organizations.
- Multi-jurisdictional labeling harmonization:Divergent FDA and EMA requirements for cardiovascular outcome claims complicate global launch strategies and extend regulatory affairs timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Loss and Weight Management Market |
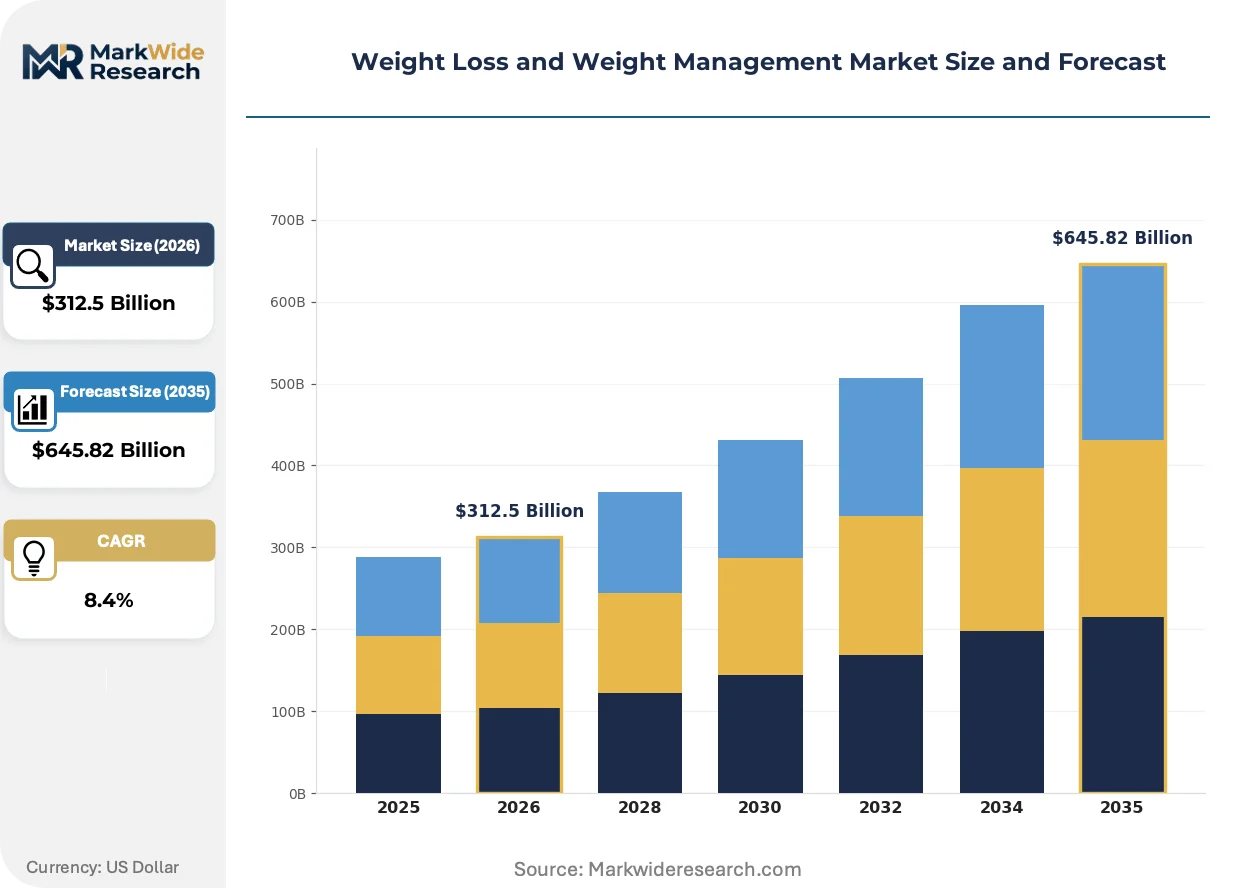
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $645.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacements, Weight Loss Programs, Fitness Apps Application: Home, Commercial, Clinical, Virtual Coaching Customer Type: Adults, Teenagers, Seniors, Health Enthusiasts Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Herbalife Nutrition Ltd., Nestlé Health Science, WW International Inc., Medifast Inc., Noom Inc., Novo Nordisk, Eli Lilly, Glanbia plc, USANA Health Sciences Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Loss and Weight Management Market Strategic Shifts & Innovations
Artificial intelligence is penetrating every layer of weight management service delivery, from predictive meal planning algorithms to computer-vision portion estimation, compressing the cost structure of personalized coaching while elevating data privacy as a competitive differentiator.
Dual-hormone receptor agonists targeting GLP-1 and GIP pathways simultaneously are rendering obsolete single-mechanism peptide therapies in prescriber preference hierarchies. Endocrinology practices in the United States are adopting these next-generation formulations at rates exceeding prior product transitions. The shift is compressing commercial viability windows for first-generation agents and forcing portfolio restructuring among manufacturers with concentrated single-mechanism exposure.
EMA's centralized assessment procedures for anti-obesity medications are tightening evidentiary standards for cardiovascular safety claims, extending pre-market evaluation timelines relative to FDA pathways. European health technology assessment bodies are incorporating quality-adjusted life year thresholds that exceed US cost-effectiveness benchmarks. Manufacturers are responding with outcome-based pricing proposals and indication-specific value dossiers tailored to national reimbursement committees.
Direct-to-consumer telehealth platforms are displacing traditional primary care gatekeeping for obesity medication initiation, particularly among commercially insured populations under age 45. These virtual channels aggregate demand through social media acquisition funnels and bypass geographic constraints on specialist availability. The phenomenon is most visible in suburban and exurban US markets where endocrinology practice density remains insufficient to serve diagnosed prevalence.
Weight Loss and Weight Management Market Segmentation
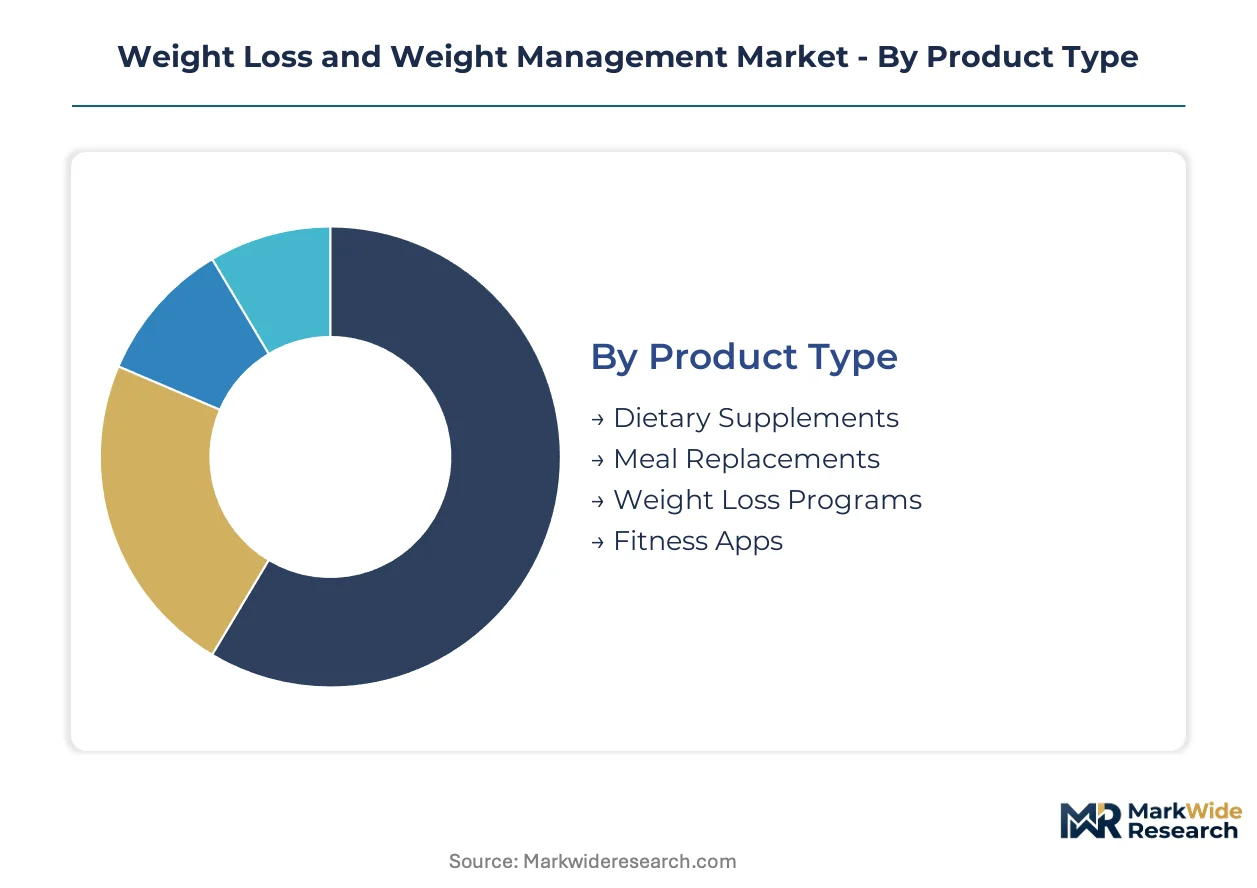
Segmentation in weight management reveals distinct service intensity profiles across product categories. Subscription-based digital platforms demand continuous engagement engineering, while pharmaceutical interventions require specialized cold-chain logistics and prescriber education support.
Product Type:
After-sales service intensity varies dramatically across product categories, with peptide-based pharmaceuticals requiring injection training and adverse event monitoring, while digital platforms depend on behavioral coaching retention.
- Dietary Supplements:Over-the-counter formulations span thermogenics, fiber blends, and micronutrient complexes with varying bioavailability claims. Demand clusters among health enthusiasts in the United States seeking non-prescription metabolic support, though FTC substantiation requirements constrain advertising claims.
- Meal Replacements:Powder and ready-to-drink formulations compete on protein fortification standards and glycemic index specifications. Commercial weight loss centers and employer wellness programs in suburban US markets drive institutional procurement, with convenience positioning capturing time-constrained professionals.
- Weight Loss Programs:Supervised clinical protocols combine caloric restriction with behavioral modification curricula.
- Fitness Apps:Smartphone-based platforms integrate wearable biosensor data for real-time metabolic feedback.
Dietary supplements hold the largest share; momentum sits with fitness apps.
Application:
Cost tier stratification separates premium clinical interventions from mass-market digital solutions, with reimbursement eligibility determining effective pricing floors.
- Home:Self-directed interventions encompass portion-controlled meal delivery, connected fitness equipment, and telehealth prescription services. Demand concentrates among commercially insured adults under 45 in the United States, where direct-to-consumer platforms bypass primary care gatekeeping.
- Commercial:Workplace wellness programs and fitness center affiliations provide institutional access channels. Large US corporations integrate GLP-1 therapies into health benefit structures, creating contracted demand pools independent of retail pharmacy distribution.
- Clinical:Endocrinology practices and obesity medicine specialists oversee pharmacological interventions.
- Virtual Coaching:AI-augmented behavioral platforms deliver psychology-based adherence protocols.
Home applications dominate volume; virtual coaching climbs the fastest.
Customer Type:
Volume concentration among adults masks margin differentiation across life-stage segments with distinct adherence challenges and reimbursement profiles.
- Adults:Working-age populations between 25 and 55 represent the core addressable market for employer-sponsored programs and direct-to-consumer platforms. Medicare Advantage coverage expansion for anti-obesity medications is reshaping access for pre-retirement cohorts in the United States.
- Seniors:Adults over 65 present comorbidity complexity that elevates clinical supervision requirements. CMS coverage determinations for weight management therapies remain inconsistent across plan administrators, fragmenting prescriber behavior.
- Teenagers:Pediatric obesity protocols face stricter FDA evidentiary standards for pharmacological approval.
- Health Enthusiasts:Prevention-focused consumers drive premium supplement and wearable subscription demand.
Adults command the largest share; seniors represent the steepest expansion trajectory as Medicare coverage evolves.
Distribution Channel:
Supply concentration in peptide API manufacturing is redrawing channel economics, with specialty pharmacy networks capturing high-value biologic dispensing.
- Online Retail:Direct-to-consumer platforms aggregate demand through social media acquisition funnels, bypassing geographic constraints on specialist availability. Telehealth-integrated prescription services in the United States are displacing traditional primary care gatekeeping for obesity medication initiation.
- Pharmacies:Cold-chain distribution requirements for GLP-1 receptor agonists favor specialty pharmacy networks with temperature-controlled logistics infrastructure. Rural pharmacy participation remains limited by per-dose fulfillment cost structures.
- Supermarkets:Mass retail channels capture meal replacement and supplement volume through placement economics.
- Health Stores:Premium positioning and staff consultation support higher-margin supplement sales.
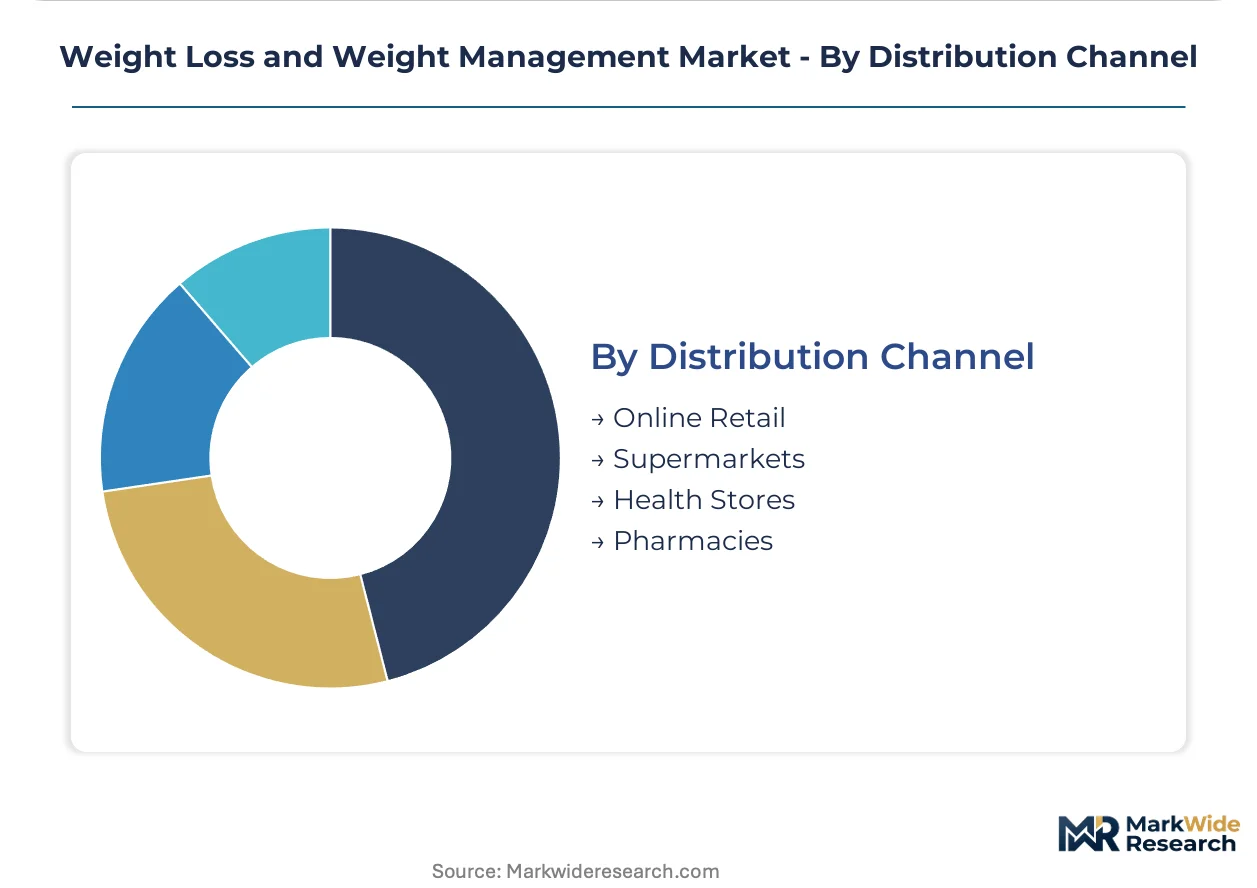
Online retail holds the largest share; pharmacies gain share fastest on biologic dispensing concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer-sponsored wellness subsidies and Medicare reimbursement expansion are redrawing patient access maps across major economies. Regulatory acceleration pathways in the United States and Europe compress development timelines while Asian markets build peptide manufacturing capacity.
United States
Commercial insurance integration of GLP-1 therapies and direct-to-consumer telehealth platforms drive institutional demand. FDA accelerated approval pathways compress clinical trial requirements for obesity medications. The Boston-Cambridge corridor anchors endocrinology research concentration with specialized obesity medicine practices adopting next-generation dual-hormone formulations.
Germany
EMA centralized assessment procedures and statutory health insurance reimbursement negotiations shape market entry strategies. The Federal Joint Committee (G-BA) evaluates cost-effectiveness through quality-adjusted life year thresholds exceeding US benchmarks. The Rhine-Main biopharma cluster hosts contract peptide manufacturers expanding solid-phase synthesis capacity for GLP-1 analog production.
China
NMPA priority review pathways for innovative biologics and expanding private health insurance coverage create dual-track access. The National Healthcare Security Administration negotiates volume-based procurement for metabolic therapies. The Yangtze River Delta biotech corridor concentrates domestic GLP-1 receptor agonist development with Shanghai-based firms advancing biosimilar pipelines.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning frameworks determine formulary placement for weight management interventions. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit regulatory pathways with FDA convergence initiatives. The Oxford-Cambridge-London golden triangle anchors obesity research translation with academic medical centers piloting integrated digital-therapeutic models.
Japan
PMDA sakigake designation system and Ministry of Health, Labour and Welfare reimbursement pricing surveys compress launch timelines for novel anti-obesity agents. The Chuikyo central social insurance medical council evaluates cost-effectiveness against domestic reference prices. The Kansai pharmaceutical manufacturing belt hosts peptide API producers serving regional demand for incretin-based therapies.
Weight Loss and Weight Management Market Key Industry Players
On the supply side, the industry is bifurcating between capital-intensive biologic manufacturers and asset-light digital platform operators. Pharmaceutical incumbents leverage manufacturing scale and cold-chain infrastructure to anchor peptide therapy distribution. Digital health providers compete through behavioral economics tools and AI-driven engagement protocols. Dominant competitive moves include vertical integration into API sourcing and strategic partnerships bridging clinical prescription channels with consumer wellness ecosystems.
Within the pharmaceutical tier, Novo Nordisk and Eli Lilly exemplify the manufacturing-scale archetype with European and US origins respectively. WW International Inc. occupies a position representing the behavioral platform segment with subscription-based retention engineering. Noom Inc. sits within the AI-augmented coaching archetype, anchoring the telehealth-integrated prescription initiation channel that bypasses traditional primary care gatekeeping.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nestlé Health Science |
| WW International Inc. |
| Medifast Inc. |
| Noom Inc. |
| Novo Nordisk |
| Eli Lilly |
| Glanbia plc |
| USANA Health Sciences Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in European peptide API manufacturing is elevating raw material premiums and compressing margin structures across GLP-1 therapy tiers, forcing pharmaceutical buyers into long-term offtake commitments while digital platform operators exploit fixed-cost software economics to capture price-sensitive segments.
Pricing Analysis
Certification level (FDA-grade vs. 503A compounding) creates the primary spread between branded and alternative supply channels. Subscription-based digital platforms deploy SaaS-tiered pricing anchored to engagement depth, while peptide therapies command per-unit transactional premiums reflecting cold-chain logistics and prescriber education bundling. Price differentiation intensifies as employer-sponsored programs negotiate volume discounts that squeeze retail pharmacy margins. Medicare Advantage beneficiaries exhibit highest price sensitivity due to fragmented prior-authorization requirements, while commercially insured populations under 45 show lowest sensitivity through telehealth-integrated direct access.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing conversations for GLP-1 precursor chemicals. Active pharmaceutical ingredient production concentrates in Denmark, China, and South Korea, drawing from specialized amino acid feedstocks and solid-phase synthesis equipment. Single-source vulnerability pervades European contract manufacturing organizations with limited peptide synthesis workforce depth. Distribution runs through specialty pharmacy networks with temperature-controlled infrastructure, bypassing mass retail channels for biologic fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across reimbursement models and patient access channels is generating niche opportunities for differentiated positioning, as Medicare coverage expansion and employer wellness integration create parallel demand pools with divergent purchasing protocols.
For Market Incumbents: Entrench manufacturing-scale advantages through captive supply of peptide API capacity in the Rhine-Main biopharma cluster, while reinforcing prescriber education infrastructure against telehealth platform displacement. Dual-hormone receptor agonist portfolio transitions represent the critical R&D lever to render single-mechanism therapies obsolete. Cold-chain distribution partnerships with specialty pharmacy networks anchor channel control against direct-to-consumer encroachment.
For New Entrants and Emerging Players: Rural and exurban United States markets present the most penetrable geography for virtual coaching platforms, where endocrinology practice density fails to serve diagnosed prevalence. Behavioral economics toolkits targeting employer wellness contracts offer the strongest go-to-market angle, bypassing traditional primary care gatekeeping through social media acquisition funnels. AI-augmented meal logging with psychology-based adherence protocols captures white-space between pharmaceutical intervention and self-directed digital tools.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-based digital health platforms with integrated wearable data streams, offering superior cash-flow quality relative to transactional pharmaceutical dispensing. Long-term viability across the analysis window favors asset-light operators with employer contract concentration and AI-driven engagement engineering. The signal to watch is CMS coverage determination consistency across Medicare Advantage plan administrators as inflection indicator for pharmaceutical tier access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Peptide API capacity expansion in European contract manufacturing organizations anchors supply security for GLP-1 agonist portfolios. |
| Regulatory Approval Pathway | FDA accelerated approval designation compresses clinical trial timelines and expands eligible patient populations for obesity therapeutics. |
| Platform Integration | Wearable biosensor data convergence with prescription therapy records enables subscription revenue models bridging clinical and lifestyle boundaries. |
| Strategic Partnership | Employer wellness program contracts create institutional demand channels independent of retail pharmacy distribution economics. |
| Pipeline Diversification | Dual-hormone GLP-1/GIP receptor agonist development renders single-mechanism peptide therapies commercially obsolete. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with endocrinology practice administrators, pharmacy benefit managers, employer wellness program directors, and contract manufacturing organization executives. Secondary validation drew from FDA filings, EMA centralized assessment procedures, CMS coverage determination databases, and ClinicalTrials.gov protocol registries. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored segmentation-level estimates.
Calibration against historical launch trajectories of anti-obesity medications and digital health platform subscription curves informed projection mechanics across the analysis window. Segmentation dimensions encompassed product type, application setting, customer life-stage, and distribution channel, with regional regulatory clusters and reimbursement eligibility tiers as cross-cutting variables. CAGRs derived from logistic diffusion curves for pharmacological adoption and exponential smoothing for digital engagement metrics, with peptide API capacity expansion timelines and CMS policy evolution as key forecast inputs.
Practitioners should monitor FDA enforcement discretion around 503A compounding facilities and EMA cardiovascular safety evidentiary tightening for early signals of supply channel disruption or launch timeline extension. Forecasts reflect documented assumptions regarding Medicare Advantage coverage expansion velocity and employer wellness program integration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Weight Management Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Yoga Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Weight Control Products Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market