
 GCC Weight Management Market | 2026-2036
GCC Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Weight Management Market Intelligence
Hospital procurement consolidation across the Gulf Cooperation Council is pivoting toward long-term supply contracts with vetted nutrition providers. Herbalife International leverages its direct-selling infrastructure to sustain distributor loyalty in Saudi Arabia and the UAE. Abbott Nutrition anchors its regional position through specialized metabolic formulas distributed via hospital formularies. GlaxoSmithKline competes in the retail pharmacy channel with science-backed supplement positioning.
GCC weight management encompasses clinically supervised and consumer-directed interventions targeting energy balance modification through caloric restriction, macronutrient manipulation, behavioral coaching, and pharmacological or surgical adjuncts, with formulations typically specifying protein content per serving, glycemic index classification, and micronutrient fortification levels to meet Gulf-specific dietary patterns. Dietary supplements occupy the largest product type share due to lower price points and minimal clinical infrastructure requirements, while meal replacements command premium margins among bariatric surgery pre-operative protocols. Fitness enthusiasts represent the fastest-growing end user segment as gym culture proliferates in Dubai, Riyadh, and Doha, though adults with diagnosed metabolic syndrome still generate the majority of prescription-directed revenue.
The Saudi Food and Drug Authority, UAE Ministry of Health and Prevention, and Kuwait's Public Authority for Food and Nutrition shape market access through mandatory supplement registration, health claim substantiation requirements, and periodic facility inspections that favor established multinationals with dedicated regulatory affairs teams. The Gulf Standardization Organization harmonizes labeling and safety testing protocols across member states, reducing but not eliminating cross-border compliance friction. Stakeholders must monitor evolving reimbursement policies for medical nutrition therapy as Gulf health systems shift toward preventive care models and value-based provider contracts.
Market Dynamics
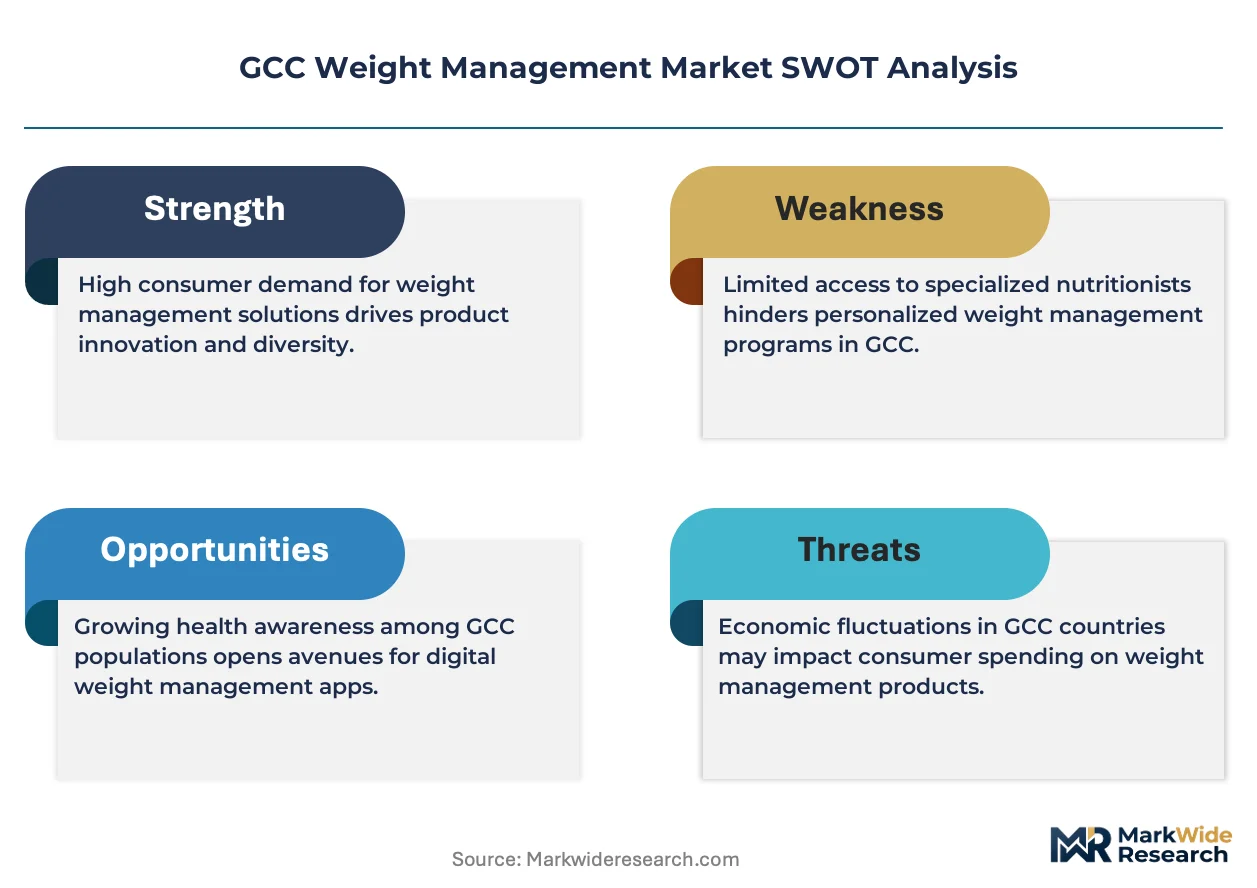
Hospital procurement consolidation across Saudi Arabia, the UAE, and Kuwait is compressing vendor margins while elevating compliance requirements for nutrition suppliers serving institutional buyers.
Growth Catalysts
- SFDA Registration Mandates:The Saudi Food and Drug Authority's tightened supplement protocols are filtering out informal competitors and formalizing demand channels for compliant manufacturers.
- Bariatric Surgery Pre-Operative Protocols:Hospital networks in Riyadh and Jeddah are standardizing meal replacement regimens, creating recurring institutional contracts for specialized metabolic formulas.
- Kuwait's Preventive Care Pivot:The Ministry of Health's metabolic syndrome screening programs are expanding prescription-directed nutrition access beyond traditional retail pharmacy channels.
Market Restraints
- Import Dependency for Whey Protein Isolates:GCC manufacturers rely on European and North American dairy processors, exposing margins to currency volatility and shipping cost spikes.
- MOHAP Health Claim Substantiation:The UAE Ministry of Health and Prevention requires clinical trial data for weight loss assertions, extending product launch timelines by 18-24 months for novel ingredients.
- Herbal Supplement Substitution:Traditional Arabic medicine practitioners in Oman and Bahrain continue recommending black seed oil and fenugreek preparations for appetite management, limiting penetration of standardized formulations.
Strategic Opportunities
- Qatar's Fitness Infrastructure Buildout:Lusail Sports Arena and Education City athletic complexes are creating concentrated demand for sports nutrition among expatriate professionals and national athletes.
- Telehealth-Integrated Coaching:Dubai Health Authority's virtual care licensing framework enables synchronous dietitian consultations bundled with subscription meal plans, bypassing retail pharmacy intermediaries.
- Gulf Standardization Organization Harmonization:Cross-border label recognition protocols are reducing duplicate testing costs for manufacturers distributing across multiple member states simultaneously.
Industry Challenges
- Halal Certification Complexity:Divergent standards between Emirates Authority for Standardization and Metrology and Saudi Standards, Metrology and Quality Organization create redundant facility audits for multi-market suppliers.
- Refrigerated Last-Mile Gaps:Meal replacement shakes requiring cold chain integrity face spoilage risks in summer months across secondary cities like Al Ain and Khobar where logistics infrastructure remains underdeveloped.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Weight Management Market |
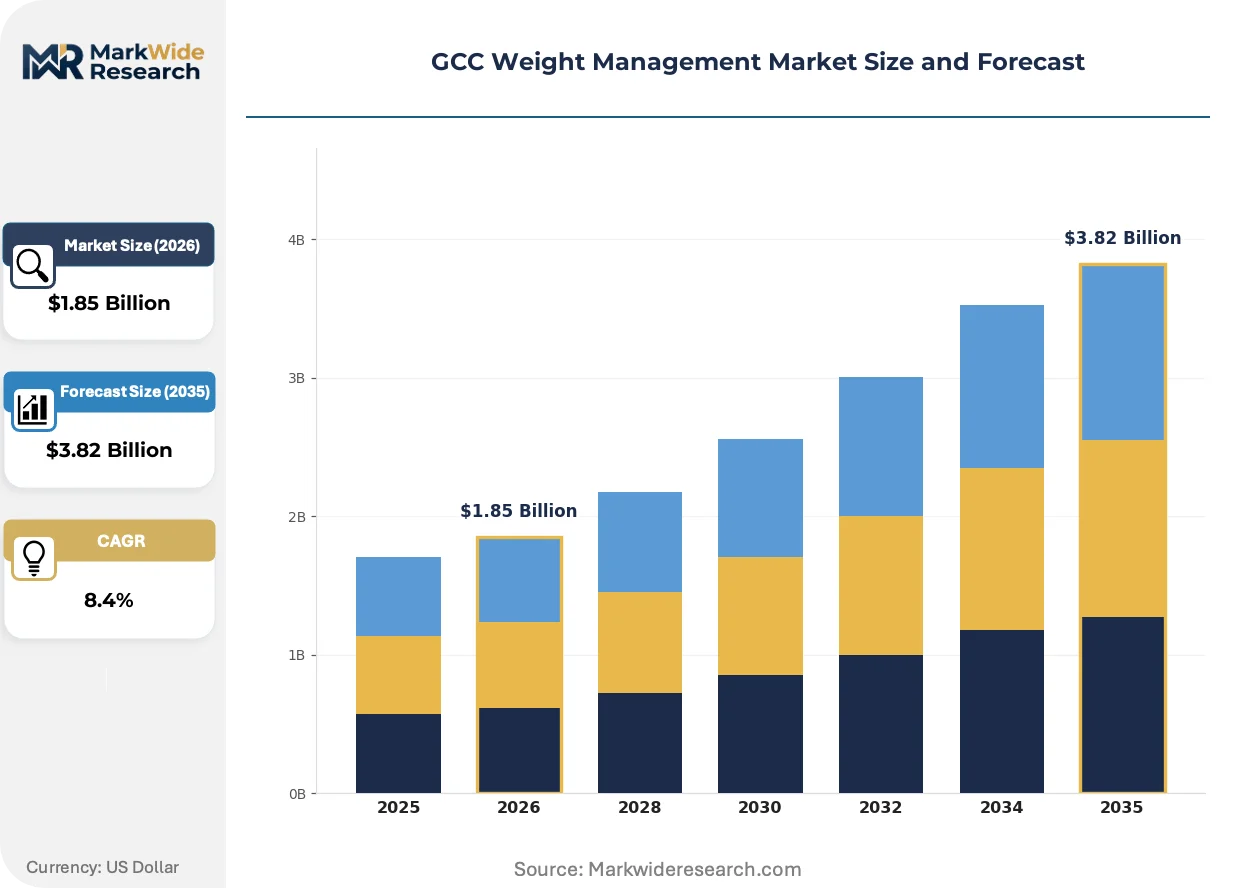
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Meal Replacements, Low-Calorie Foods, Weight Loss Programs End User: Adults, Children, Fitness Enthusiasts, Healthcare Professionals Distribution Channel: Online Retail, Pharmacies, Supermarkets, Health Stores Service Type: Consultation Services, Coaching, Fitness Classes, Nutritional Counseling |
| Companies Covered | GlaxoSmithKline, Medifast, Herbalife International, Nutrisystem, Weight Watchers International, Nestle, Atkins Nutritionals, Glanbia Nutritionals, Abbott Nutrition, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Weight Management Market Strategic Shifts & Innovations
Digital health integration and personalized nutrition algorithms are displacing one-size-fits-all product positioning across Gulf wellness programs. Manufacturers are recalibrating R&D spending toward biomarker-responsive formulations.
Continuous glucose monitoring wearables is converging with subscription-based meal planning platforms in Dubai and Riyadh. Endocrinology clinics are prescribing CGM-enabled diet protocols to pre-diabetic patients. This hardware-software pairing is compressing demand for generic low-calorie products while elevating precision-formulation premiums.
The UAE Ministry of Health and Prevention's 2023 health claim substantiation circular now requires peer-reviewed evidence for weight management assertions on supplement labels. Manufacturers are reformulating portfolios to remove borderline ingredients or commissioning local clinical trials. Retail pharmacy buyers in Abu Dhabi and Sharjah are prioritizing SKUs with pre-cleared MOHAP registrations to reduce liability exposure.
Bundled service contracts are displacing standalone product sales in Saudi hospital networks. Bariatric surgery centers in Jeddah and Dammam now specify multi-month nutrition support packages incorporating pre-op meal replacements, post-op micronutrient monitoring, and dietitian teleconsultations. This procurement evolution favors vendors with integrated care platforms over pure-play formula suppliers.
GCC Weight Management Market Segmentation
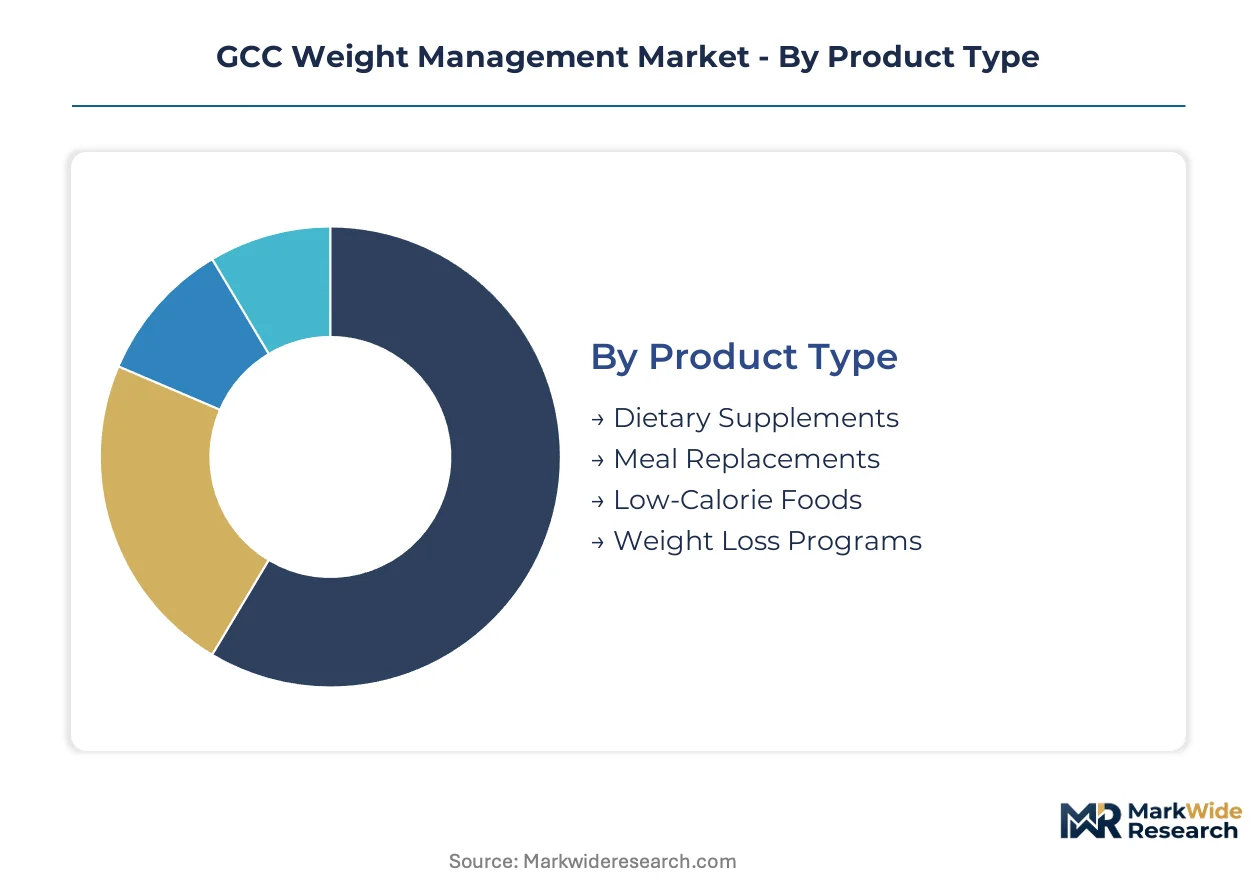
Segmentation in the GCC weight management market reveals distinct procurement pathways between institutional buyers and consumer-directed channels. Product formulations, service delivery modes, and distribution infrastructure vary sharply across these divides, shaping vendor positioning and margin structures.
Product Type:
Standalone formulations dominate retail pharmacy and direct-to-consumer channels, while embedded meal replacement protocols integrate into hospital bariatric programs.
- Dietary Supplements:Capsule and tablet formulations specifying protein content per serving, micronutrient fortification levels, and glycemic index classification. Demand concentrates in Saudi retail pharmacies where SFDA registration mandates filter informal competitors; lower price points sustain volume against compliance cost pressures.
- Meal Replacements:Specialized metabolic formulas distributed via hospital formularies for pre-operative bariatric protocols. Riyadh and Jeddah hospital networks standardize these regimens, creating recurring institutional contracts with premium margin structures.
- Low-Calorie Foods:Portion-controlled prepared meals targeting calorie restriction without clinical supervision.
- Weight Loss Programs:Structured multi-week interventions combining behavioral coaching with product bundles.
Volume placements concentrate in Dietary Supplements; the faster expansion belongs to Meal Replacements.
End User:
Customer archetypes span diagnosed metabolic conditions requiring clinical oversight through self-directed fitness optimization, with procurement authority shifting accordingly.
- Fitness Enthusiasts:Gym-affiliated consumers pursuing macronutrient manipulation for body composition goals. Dubai, Riyadh, and Doha gym culture proliferation drives demand; this segment climbs fastest as athletic facility investment accelerates across the Gulf.
- Adults:Broader demographic encompassing diagnosed metabolic syndrome patients and general wellness seekers. Majority of prescription-directed revenue originates here through endocrinology clinic referrals in Saudi Arabia and the UAE.
- Children:Pediatric obesity interventions requiring family-centered behavioral coaching protocols.
- Healthcare Professionals:Institutional purchasers procuring on behalf of hospital networks and clinic systems.
Revenue gravity sits with Adults; Fitness Enthusiasts capture the steepest expansion trajectory.
Distribution Channel:
Channel selection determines regulatory exposure, with pharmacy and hospital pathways requiring MOHAP or SFDA clearance versus lighter-touch online frameworks.
- Pharmacies:Brick-and-mortar retail with trained staff consultation. Abu Dhabi and Sharjah buyers prioritize SKUs with pre-cleared MOHAP registrations to reduce liability exposure; health claim substantiation requirements extend launch timelines.
- Online Retail:Direct-to-consumer platforms bypassing traditional intermediaries. Dubai Health Authority's virtual care licensing enables synchronous dietitian consultations bundled with subscription meal plans.
- Supermarkets:Mass-market shelf placement for low-calorie packaged foods.
- Health Stores:Specialty retailers emphasizing premium positioning and ingredient transparency.
Transaction volume flows through Pharmacies; Online Retail gains share fastest as telehealth integration matures.
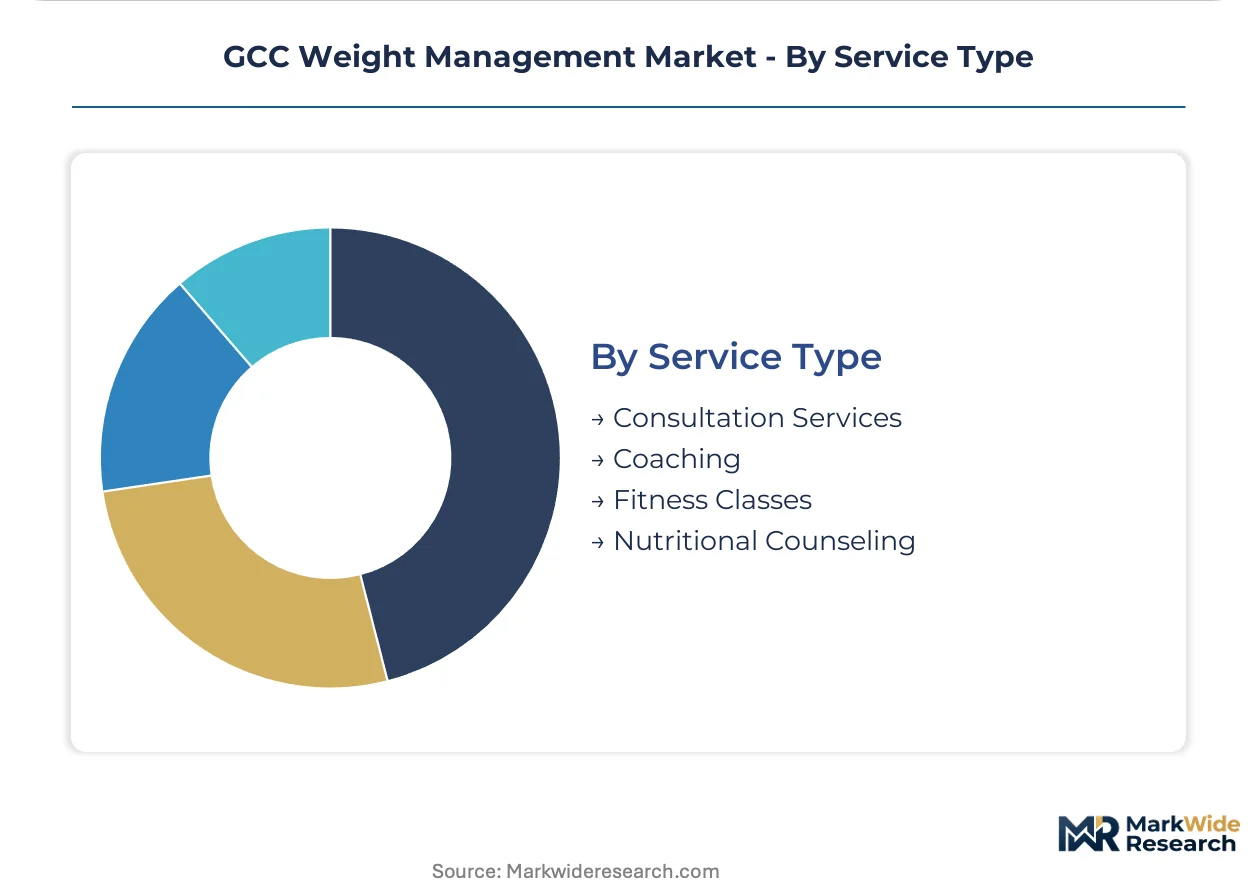
Service Type:
Service delivery modes range from one-time clinical encounters through ongoing subscription relationships, with technology integration reshaping traditional face-to-face models.
- Consultation Services:Initial clinical assessments and personalized protocol design. Kuwait's Ministry of Health metabolic syndrome screening programs expand prescription-directed access beyond retail channels.
- Nutritional Counseling:Ongoing dietitian oversight with biomarker monitoring. CGM-enabled protocols in Dubai and Riyadh endocrinology clinics compress demand for generic low-calorie products.
- Coaching:Behavioral support emphasizing adherence and lifestyle modification.
- Fitness Classes:Group exercise programming bundled with nutrition guidance.
Service revenue concentrates in Consultation Services; Nutritional Counseling demonstrates the fastest uptake as precision monitoring hardware proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most heavily in Saudi Arabia, where government wellness initiatives and rising obesity intervention spending outpace other Gulf states. Hospital and clinic networks across the region are expanding bariatric and metabolic health programs, creating concentrated demand from institutional buyers in specific metropolitan clusters.
Saudi Arabia
Riyadh and Jeddah hospital networks standardize pre-operative meal replacement regimens, creating recurring institutional contracts for specialized metabolic formulas. The Saudi Food and Drug Authority has tightened nutritional labeling requirements and supplement registration protocols, elevating compliance costs for new entrants. Jeddah's bariatric surgery centers now specify multi-month nutrition support packages incorporating teleconsultations.
United Arab Emirates
Dubai's gym culture proliferation drives demand among fitness enthusiasts pursuing macronutrient manipulation for body composition goals. The UAE Ministry of Health and Prevention requires clinical trial data for weight loss assertions, extending product launch timelines by 18-24 months for novel ingredients. Abu Dhabi and Sharjah retail pharmacy buyers prioritize SKUs with pre-cleared MOHAP registrations to reduce liability exposure.
Kuwait
The Ministry of Health's metabolic syndrome screening programs are expanding prescription-directed nutrition access beyond traditional retail pharmacy channels. Kuwait's preventive care pivot creates institutional procurement pathways for clinically supervised interventions. Metabolic health clinics in Kuwait City are bundling CGM-enabled protocols with subscription meal planning services.
Qatar
Lusail Sports Arena and Education City athletic complexes generate concentrated demand for sports nutrition among expatriate professionals and national athletes. The Dubai Health Authority's virtual care licensing framework enables synchronous dietitian consultations bundled with subscription meal plans, bypassing retail pharmacy intermediaries. Doha's fitness infrastructure buildout supports the fastest-growing end user segment regionally.
Oman and Bahrain
Traditional Arabic medicine practitioners continue recommending black seed oil and fenugreek preparations for appetite management, limiting penetration of standardized formulations. The Gulf Standardization Organization harmonizes labeling and safety testing protocols across member states, reducing but not eliminating cross-border compliance friction. Secondary cities face refrigerated last-mile gaps where meal replacement shakes requiring cold chain integrity encounter spoilage risks.
GCC Weight Management Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue telehealth-integrated coaching and precision-formulation niches. The vendor base spans multinational nutrition conglomerates with dedicated regulatory affairs teams, direct-selling networks sustaining distributor loyalty, and specialized metabolic formula suppliers anchored in hospital formularies. Three archetypes dominate: institutional formulary incumbents, retail pharmacy science-backed positioners, and direct-to-consumer subscription platforms. Competitive moves concentrate on long-term supply contract consolidation and bundled service contracts displacing standalone product sales.
Within the institutional formulary tier, Abbott Nutrition and GlaxoSmithKline exemplify divergent channel strategies. Abbott Nutrition anchors regional position through specialized metabolic formulas distributed via hospital formularies, while GlaxoSmithKline competes in the retail pharmacy channel with science-backed supplement positioning. Herbalife International represents the direct-selling archetype, leveraging infrastructure to sustain distributor loyalty in Saudi Arabia and the UAE. These three occupy positions reflecting distinct regulatory exposure profiles and procurement authority relationships across Gulf markets.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Medifast |
| Herbalife International |
| Nutrisystem |
| Weight Watchers International |
| Nestle |
| Atkins Nutritionals |
| Glanbia Nutritionals |
| Abbott Nutrition |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between SFDA-registered hospital formulary products and unregistered retail supplements manifests in both margin structures and sourcing complexity across Saudi Arabia and the UAE. Premium metabolic formulas command institutional pricing power through bundled multi-month nutrition support packages, while commodity dietary supplements face compression from direct-to-consumer subscription platforms bypassing traditional pharmacy markups.
Pricing Analysis
Volume placements concentrate in dietary supplements at lower price points, while meal replacement protocols capture premium margins through institutional contracting. Three-tier pricing structure across premium metabolic formulas, standard retail supplements, and economy direct-to-consumer brands reflects divergent compliance investment levels. Pricing pressure stems from telehealth-integrated coaching platforms compressing traditional pharmacy channel margins. Fitness enthusiasts demonstrate highest price sensitivity, whereas hospital procurement committees prioritize pre-cleared MOHAP registrations over unit cost.
Supply Chain Analysis
Freight cost volatility for temperature-sensitive meal replacements exposes margin fragility during Gulf summer months when cold chain integrity degrades across secondary cities. Manufacturing concentration in Saudi Arabia and the UAE for formulated products contrasts with raw material dependency on European and North American whey protein isolates. Supply chain risk centers on single-source vulnerability for specialized metabolic ingredients subject to currency fluctuation. Distribution runs through hospital formularies and retail pharmacy networks with divergent compliance requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in SFDA-registered manufacturing capacity prop pricing power for compliant producers, creating durable margin structures for established institutional suppliers.
For Market Incumbents: Anchor regional position through long-term hospital supply contracts incorporating teleconsultation bundles, defending against direct-to-consumer subscription platforms. Deepen backward integration into cold chain logistics to mitigate summer spoilage risks in secondary Gulf cities. Prioritize Emirates Authority for Standardization and Metrology certification investment to reduce redundant facility audits across multi-market distribution. For New Entrants and Emerging Players: Begin with Qatar's fitness infrastructure buildout targeting expatriate professionals at Lusail Sports Arena and Education City complexes, the most penetrable geography for sports nutrition white space. Exploit telehealth licensing frameworks in Dubai to launch synchronous dietitian consultation platforms bundled with subscription meal plans, bypassing established pharmacy intermediaries. For Investors and Strategic Acquirers: Re-rating potential sits with telehealth-integrated nutrition platforms given Dubai Health Authority's virtual care licensing catalyst and bundled service contract displacement of standalone product sales. Long-term viability favors acquisition targets with hospital formulary anchoring and regulatory affairs infrastructure spanning multiple Gulf jurisdictions. Monitor SFDA registration backlog clearance rates as inflection indicator for formalized demand channel expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Platform Integration | Dubai Health Authority licensing enables synchronous dietitian consultations bypassing retail pharmacy intermediaries. |
| Hospital Formulary Partnership | Riyadh and Jeddah bariatric centers standardize multi-month nutrition support packages with embedded teleconsultations. |
| SFDA Registration Investment | Saudi Food and Drug Authority compliance filters informal competitors and formalizes demand channels for registered manufacturers. |
| Cold Chain Infrastructure Expansion | Refrigerated last-mile capabilities in Al Ain and Khobar reduce meal replacement spoilage risks during summer months. |
| CGM-Enabled Protocol Development | Continuous glucose monitoring convergence with subscription platforms elevates precision-formulation premiums in Dubai endocrinology clinics. |
Research Approach
Independent corroboration across hospital procurement managers, regulatory affairs directors at multinational nutrition firms, SFDA compliance specialists, and retail pharmacy category buyers underwrites the qualitative findings. Primary fieldwork combined structured interviews with institutional formulary committees and bariatric surgery center administrators with secondary validation through SFDA registration databases, MOHAP health claim circulars, and Gulf Standardization Organization harmonization protocols. Bottom-up demand modeling from hospital network expansion plans and top-down macroeconomic indicators from Gulf health ministry budget allocations were triangulated for cross-verification.
Rate-of-change decomposition across product type, end user archetype, distribution channel, and service delivery mode segments informed the analytical framework over the projection horizon. CAGRs were derived from segment-specific growth drivers including bariatric surgery volume trends, fitness facility investment pipelines, and telehealth licensing expansion trajectories. Modeled inputs incorporated metabolic syndrome screening program scale-ups in Kuwait and Qatar's sports infrastructure buildout timelines alongside reimbursement policy evolution for medical nutrition therapy.
Underlying measurement precision varies by segment; hospital formulary and institutional procurement pathways carry tighter precision than direct-to-consumer subscription platforms where customer churn assumptions introduce variability. Forecasts reflect documented assumptions regarding regulatory harmonization progress and cold chain infrastructure development timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Smart Wellness Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Weight Management Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Yoga Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Sports and Fitness Biohacking Market