
 Sports and Fitness Biohacking Market | 2026-2036
Sports and Fitness Biohacking Market Size, Share, and Industry Trends Forecast 2026-2036
Sports and Fitness Biohacking Market Analytics
ISO 13485 certification for medical device quality management is redrawing competitive boundaries in wearable biohacking hardware. Apple leverages its silicon design capabilities to sustain tight integration between biometric sensors and AI analytics pipelines. Dexcom anchors its position through specialized glucose monitoring ecosystems that extend into athletic performance optimization. Whoop competes on subscription-based recovery analytics, differentiating through HRV-derived strain metrics that dominate professional team procurement cycles.
Sports and fitness biohacking encompasses the deliberate modification of human physiology through technology-mediated interventions, combining real-time biometric capture from photoplethysmography and accelerometer arrays with algorithmic feedback loops to optimize training load, recovery velocity, and neuromuscular adaptation. Its commercial purpose centers on quantified performance enhancement for competitive athletes and serious fitness practitioners seeking measurable physiological returns on training investment. Wearable tech commands the largest revenue pool due to recurring data subscription attach rates, while recovery devices represent the fastest-expanding segment as cryotherapy and pneumatic compression systems penetrate collegiate and semi-professional athletic programs. Nutraceutical supplements occupy mature distribution channels with compressed margins, whereas smart gym equipment concentrates margin capture among AI-enabled form-correction platforms.
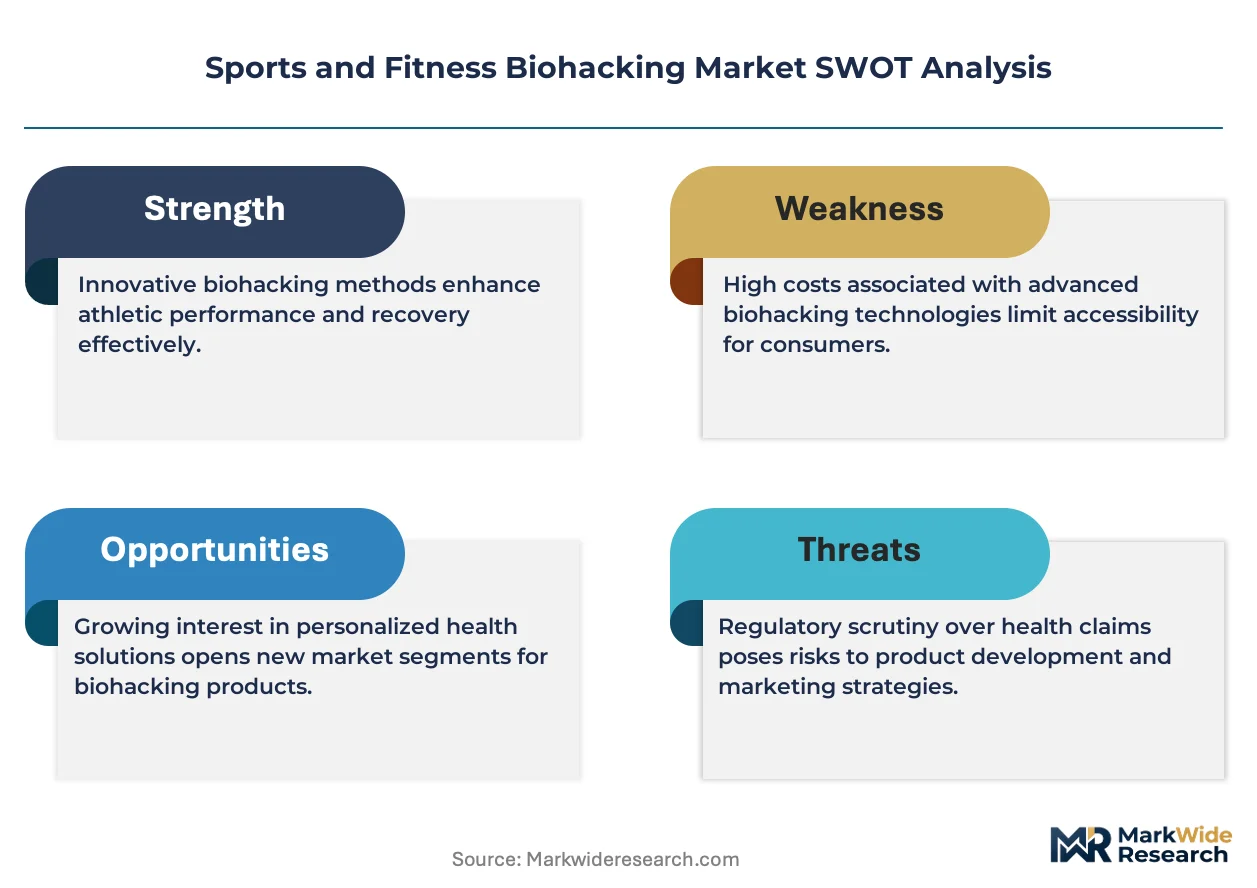
FDA clearance pathways for software-as-medical-device functions create compliance bottlenecks that filter market entrants in the United States, while the EU AI Act imposes risk-classification burdens on algorithmic health recommendations in Europe. HIPAA data handling requirements constrain how US-based platforms aggregate and monetize biometric datasets from employer-sponsored wellness programs. Stakeholders must monitor regulatory divergence between jurisdictions where wearable data transitions from wellness claims to diagnostic functions, as this boundary shift determines reimbursement eligibility and channel access for emerging biohacking platforms.
Market Dynamics
ISO 13485 certification requirements are compressing vendor margins while elevating compliance costs for wearable biohacking hardware entrants, filtering smaller players from professional team procurement channels.
Growth Catalysts
- Collegiate Athletic Investment:NCAA Division I programs in the United States now mandate athlete monitoring systems, creating institutional procurement pipelines for recovery devices and biometric wearables that extend into alumni-funded training facilities.
- FDA Software-as-Medical-Device Pathway:The agency's evolving framework for algorithmic health recommendations is clarifying reimbursement eligibility for diagnostic-grade wearables, accelerating enterprise wellness program adoption.
- Photoplethysmography Miniaturization:Advances in optical sensor integration enable continuous SpO2 and heart rate variability capture from form factors compatible with competitive sports equipment.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundries dominate custom ASIC production for low-power biometric processing, exposing hardware vendors to single-source risk during capacity constraints.
- EU AI Act Risk Classification:Algorithmic health recommendation functions face heightened compliance burdens in Europe, extending product launch timelines by 12-18 months for predictive analytics features.
- Substitute Modalities:Manual recovery protocols and conventional physical therapy retain cost advantages in price-sensitive amateur athletic segments, limiting addressable market expansion.
Strategic Opportunities
- Military and Tactical Fitness:Defense procurement channels in Australia and the United Kingdom are piloting stress-resilience monitoring systems derived from elite athletic protocols, opening adjacent demand verticals.
- Neurostimulation-Recovery Convergence:Integration of transcutaneous electrical nerve stimulation with pneumatic compression systems creates differentiated premium offerings for post-surgical rehabilitation markets.
- Employer Wellness Mandates:Post-pandemic workforce health initiatives in Germany and the Netherlands are subsidizing wearable subscriptions, converting individual fitness expenditure into corporate benefit expenditure.
Industry Challenges
- Biomedical Engineering Talent Scarcity:The intersection of signal processing, exercise physiology, and regulatory affairs commands premium compensation, constraining R&D velocity for mid-tier vendors.
- HIPAA Data Architecture Complexity:Employer-sponsored wellness platforms face architectural redesign costs to segregate diagnostic-grade data flows from general fitness tracking, delaying monetization of aggregated biometric datasets.
- Interoperability Certification Delays:Continua Health Alliance and IEEE 11073 standards compliance testing creates bottlenecks for devices seeking integration with electronic health record systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports and Fitness Biohacking Market |
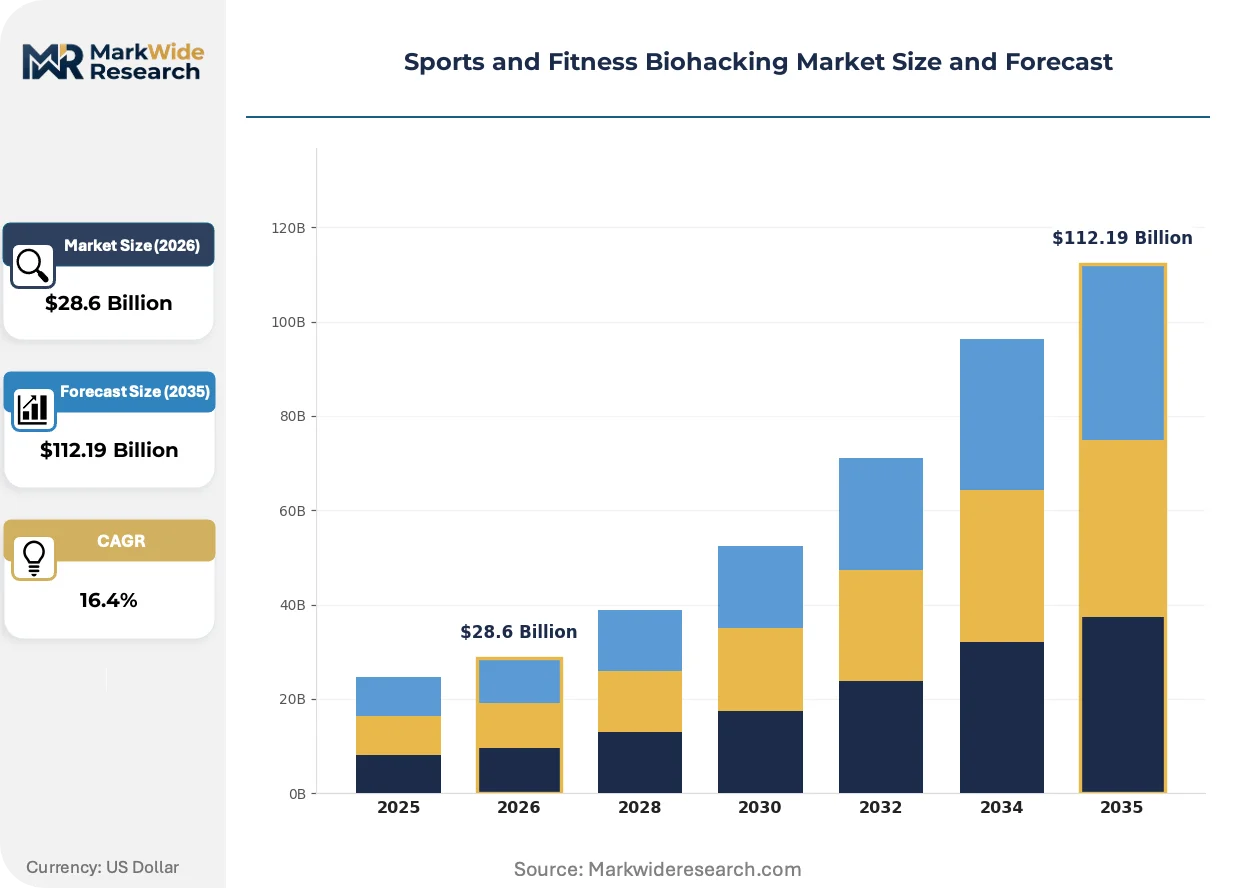
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $112.19 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Tech, Nutraceutical Supplements, Smart Gym Equipment, Recovery Devices Application: Performance Enhancement, Muscle Recovery, Stress Reduction, Sleep Improvement End User: Athletes, Fitness Enthusiasts, Health Coaches, Rehabilitation Specialists Technology: Biometric Sensors, AI Analytics, Neurostimulation, Cryotherapy |
| Companies Covered | Altos Labs, Samsung, Apple, Bulletproof 360, Dexcom, Whoop, Abbott, Function Health, Oura Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports and Fitness Biohacking Market Evolving Landscape
Algorithmic personalization is displacing one-size-fits-all training protocols across competitive athletics, with machine learning models now dictating load management decisions previously reserved for human coaching staff.
Continuous glucose monitoring technology is bifurcating athletic nutrition strategy. Elite endurance athletes in cycling and marathon disciplines adopt real-time glycemic feedback to modulate fueling timing. Professional team nutrition departments integrate CGM-derived metabolic profiles with training periodization. This capability compression is eroding the competitive moat of specialized sports dietetics consultancies.
The EU AI Act's risk-based classification system is reshaping product development roadmaps for algorithmic coaching platforms. High-risk health recommendation functions trigger conformity assessment requirements that extend certification timelines. Vendors targeting European professional sports markets are bifurcating feature sets, deploying simplified wellness-tier algorithms in EU jurisdictions while reserving diagnostic-grade analytics for US deployments under FDA enforcement discretion.
Subscription unbundling is fragmenting buyer relationships in team procurement. Athletic departments increasingly separate hardware acquisition from data analytics contracts, treating sensors as capital expenditure and algorithms as operating expenditure. This pattern is most pronounced in United States collegiate programs, where procurement officers negotiate multi-year platform agreements independent of device refresh cycles, compressing vendor lifetime value per account.
Sports and Fitness Biohacking Market Segmentation
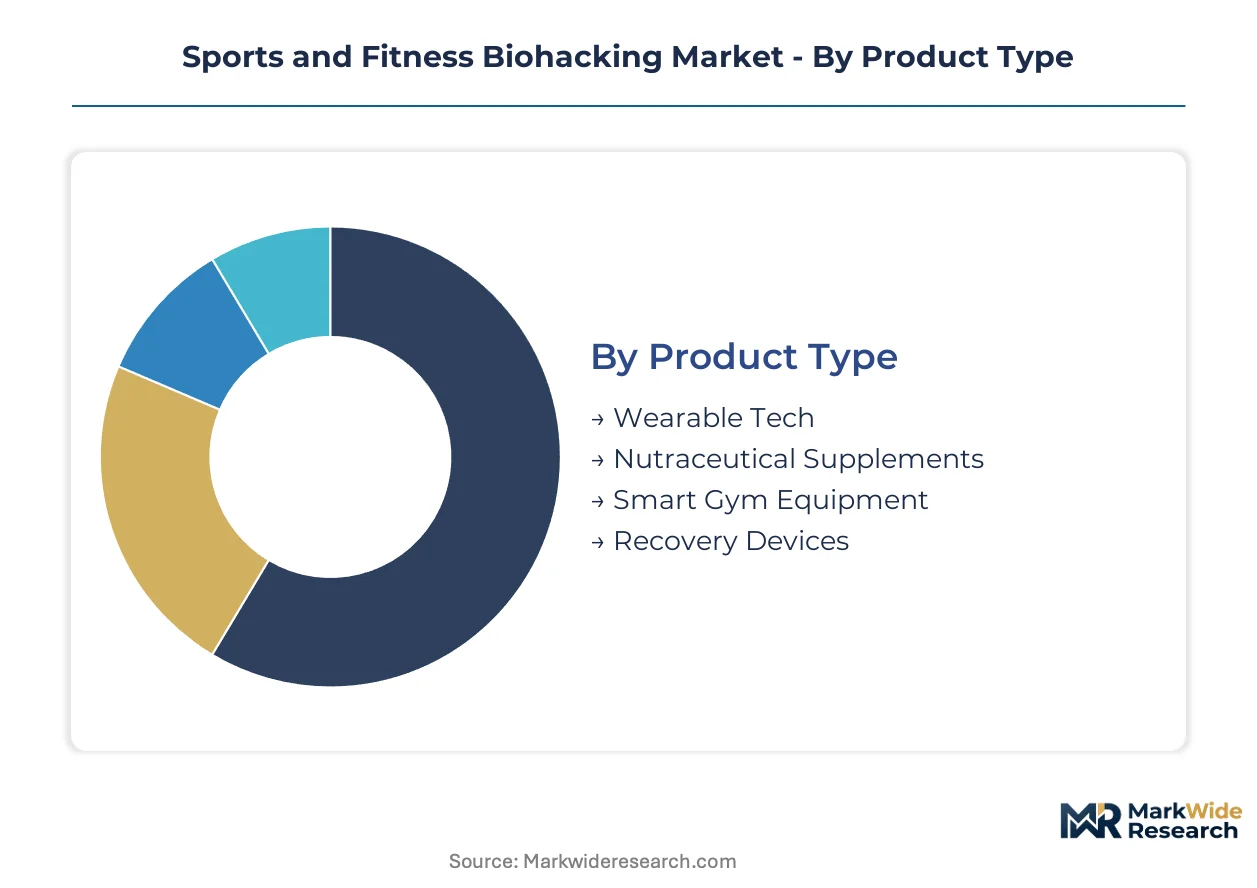
Product differentiation in sports and fitness biohacking follows distinct procurement patterns across amateur, collegiate, and professional athletic tiers. Each segment category reflects divergent margin structures, regulatory exposure, and customer lifetime value profiles that reshape vendor go-to-market strategies.
Product Type:
Wearable tech and recovery devices concentrate demand in the United States collegiate athletic system, while nutraceutical supplements distribute through mature retail channels with compressed pricing power.
- Wearable Tech:Photoplethysmography-enabled devices with continuous HRV and SpO2 monitoring dominate professional team procurement through subscription-anchored revenue models. NCAA Division I programs in the United States now mandate athlete monitoring systems, institutionalizing hardware refresh cycles and data platform contracts.
- Recovery Devices:Pneumatic compression systems and cryotherapy hardware penetrate semi-professional and collegiate facilities as post-training protocol standardization accelerates. Australian defense procurement channels pilot stress-resilience monitoring systems derived from elite athletic protocols, opening adjacent demand verticals for recovery-integrated platforms.
- Nutraceutical Supplements:Branched-chain amino acids, adaptogens, and nootropic stacks distribute through Amazon and direct-to-consumer channels with minimal regulatory friction.
- Smart Gym Equipment:AI-enabled form-correction platforms capture margin through software subscriptions attached to hardware sales in private training facilities.
Wearable tech holds the largest share; momentum sits with recovery devices.
Application:
Cost tier stratification separates diagnostic-grade performance optimization from consumer wellness claims, with reimbursement eligibility determining enterprise adoption velocity.
- Performance Enhancement:Real-time biometric feedback for load management and training periodization commands premium pricing in professional cycling and marathon disciplines. Continuous glucose monitoring technology enables fueling timing optimization that erodes traditional sports dietetics consultancies.
- Muscle Recovery:Algorithmic compression protocols and neurostimulation integration address post-surgical rehabilitation markets with clinical-grade positioning. Transcutaneous electrical nerve stimulation converges with pneumatic systems to create differentiated premium offerings.
- Stress Reduction:HRV-guided breathing interventions and vagus nerve stimulation target corporate wellness programs in Germany and the Netherlands.
- Sleep Improvement:Temperature-regulating wearables and circadian rhythm trackers address recovery velocity optimization for shift-working tactical personnel.
Performance enhancement commands premium pricing; sleep improvement is climbing the fastest as recovery science permeates amateur athletic segments.
End User:
Customer type determines contract structure, with institutional procurement favoring capital-expenditure hardware separation from operating-expenditure analytics subscriptions.
- Athletes:Professional and collegiate competitors drive demand for diagnostic-grade wearables with FDA-cleared algorithms. Subscription unbundling fragments buyer relationships as athletic departments negotiate multi-year platform agreements independent of device refresh cycles.
- Rehabilitation Specialists:Physical therapy clinics integrate pneumatic compression and neurostimulation for post-operative protocols. HIPAA data architecture complexity constrains how US-based platforms aggregate biometric datasets from employer-sponsored wellness programs.
- Fitness Enthusiasts:Amateur practitioners purchase consumer-tier wearables through retail channels with wellness-tier algorithm limitations.
- Health Coaches:Independent practitioners leverage aggregated biometric dashboards to justify client retention and outcome-based pricing.
Athletes generate the highest revenue per account; rehabilitation specialists are gaining share fastest as clinical-channel penetration deepens.
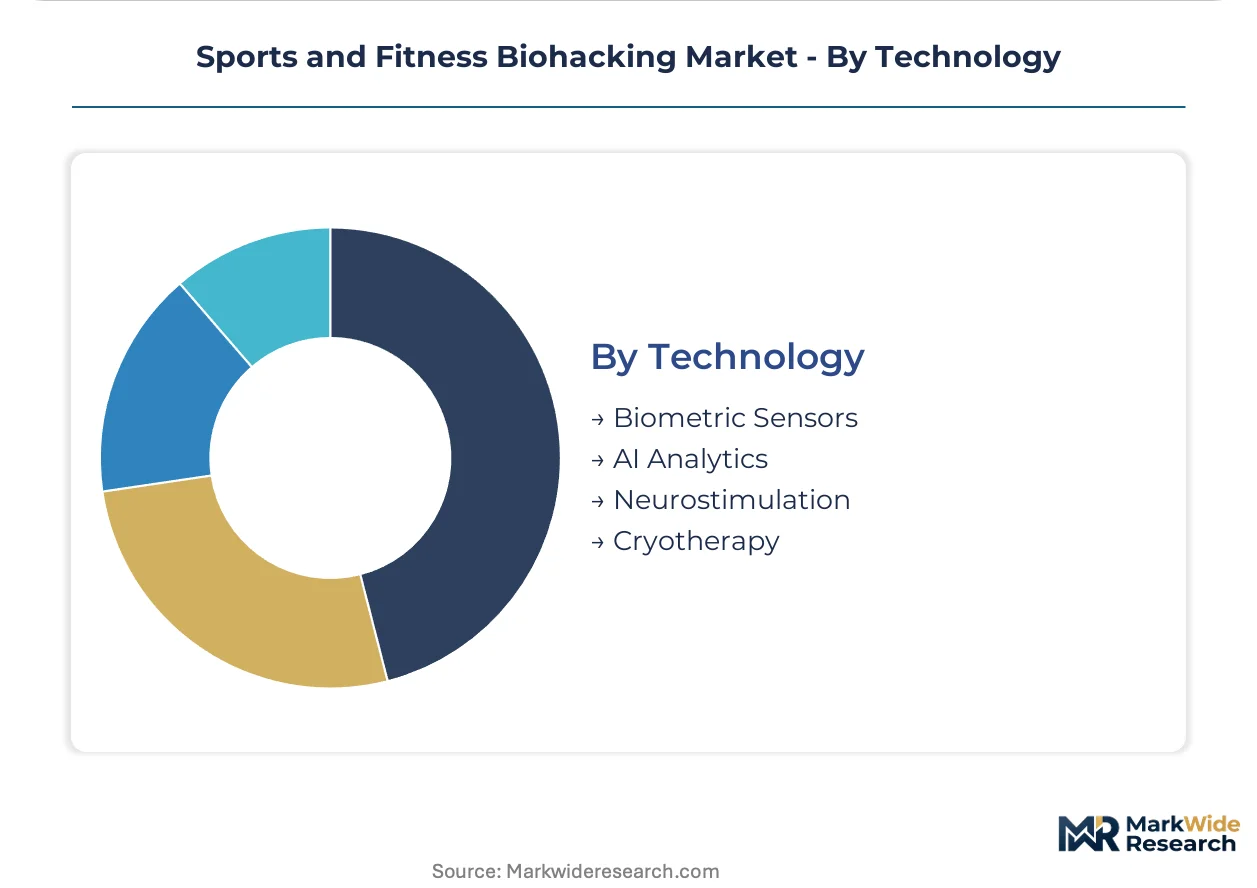
Technology:
Supply concentration in Taiwan-based foundries for custom ASIC production exposes hardware vendors to single-source risk during capacity constraints.
- Biometric Sensors:Photoplethysmography miniaturization enables continuous capture from form factors compatible with competitive sports equipment. Optical sensor integration advances from Apple and Dexcom sustain tight hardware-software integration pipelines.
- AI Analytics:Machine learning models now dictate load management decisions previously reserved for human coaching staff. EU AI Act risk classification extends certification timelines by 12-18 months for predictive analytics features in European markets.
- Neurostimulation:Transcutaneous electrical nerve stimulation and transcranial direct current stimulation address neuromuscular adaptation and pain management.
- Cryotherapy:Whole-body and localized cold exposure systems penetrate collegiate athletic programs as recovery protocol standardization advances.
Biometric sensors anchor revenue concentration; AI analytics faces the steepest regulatory divergence between US FDA pathways and EU AI Act compliance burdens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA clearance pathways for diagnostic-grade wearables accelerate enterprise adoption in the United States, while employer wellness mandates in Germany and the Netherlands convert individual fitness expenditure into corporate benefit programs. Defense procurement channels in Australia and the United Kingdom pilot stress-resilience monitoring systems derived from elite athletic protocols.
United States
NCAA Division I programs mandate athlete monitoring systems, creating institutional procurement pipelines for recovery devices and biometric wearables. HIPAA data handling requirements constrain how platforms aggregate and monetize biometric datasets from employer-sponsored wellness programs. Greater Boston anchors development of AI-enabled coaching platforms, while Austin and San Francisco concentrate venture-backed wearable startups.
Germany
Post-pandemic workforce health initiatives subsidize wearable subscriptions, converting individual fitness expenditure into corporate benefit expenditure. The EU AI Act imposes risk-classification burdens on algorithmic health recommendations, extending product launch timelines for predictive analytics features. Munich and Berlin concentrate digital health incubators developing HRV-guided stress reduction platforms for corporate wellness deployment.
United Kingdom
Defense procurement channels pilot stress-resilience monitoring systems derived from elite athletic protocols, opening adjacent demand verticals for recovery-integrated platforms. MHRA alignment with FDA breakthrough device pathways accelerates clearance for diagnostic-grade wearables. London anchors sports technology venture capital, while Manchester concentrates rehabilitation specialist clinics integrating pneumatic compression systems.
Australia
Defense procurement channels pilot stress-resilience monitoring systems for tactical fitness applications, extending elite athletic protocols into military verticals. TGA regulatory frameworks for software-as-medical-device functions create compliance bottlenecks that filter market entrants. Melbourne and Sydney concentrate sports science research institutions driving photoplethysmography miniaturization advances.
Netherlands
Employer wellness mandates subsidize wearable subscriptions, converting individual fitness expenditure into corporate benefit expenditure. GDPR compliance requirements constrain biometric data aggregation from employer-sponsored wellness programs. Eindhoven anchors semiconductor design capabilities for low-power biometric processing ASICs.
Sports and Fitness Biohacking Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and data platform maturity. The vendor base stratifies between vertically integrated technology conglomerates, specialized biometric sensor developers, and subscription-native analytics platforms. Three archetypes dominate: silicon-integrated ecosystem builders, medical-grade sensor specialists, and recovery-focused hardware-software bundles. Competitive moves concentrate on ISO 13485 certification acquisition and multi-year platform agreements with collegiate athletic departments.
Within the medical-grade sensor tier, Dexcom and Abbott exemplify specialized glucose monitoring ecosystems that extend into athletic performance optimization. Among subscription-native analytics platforms, Whoop occupies a position representing HRV-derived strain metrics that dominate professional team procurement cycles. Apple sits within the silicon-integrated ecosystem builder archetype, leveraging in-house chip design to sustain tight hardware-software integration pipelines. These three anchors illustrate how certification depth, data platform stickiness, and vertical integration separate competitive tiers in professional and collegiate procurement channels.
| Leading Market Players |
|---|
| Altos Labs |
| Samsung |
| Apple |
| Bulletproof 360 |
| Dexcom |
| Whoop |
| Abbott |
| Function Health |
| Oura Health |
| Others |
Value Network & Pricing Analysis
Foundry-scale economies in Taiwan-based ASIC production for low-power biometric processing concentrate supply-side leverage among vertically integrated wearable vendors, compressing price floors for mid-tier hardware entrants while elevating margins for ecosystem builders with captive silicon design.
Pricing Analysis
Certification level creates the primary spread between wellness-tier consumer devices and diagnostic-grade professional hardware. Three-tier pricing structure across premium, standard, and economy levels segments by FDA clearance status, ISO 13485 compliance, and algorithmic sophistication. Cost compression in the standard tier intensifies because collegiate athletic procurement officers unbundle hardware from analytics subscriptions, treating sensors as capital expenditure. Amateur fitness enthusiasts exhibit highest price sensitivity, while professional team procurement favors long-term platform agreements with minimal per-unit cost scrutiny.
Supply Chain Analysis
Taiwan Strait transit exposure concentrates single-source risk for photoplethysmography sensor ASICs that power continuous HRV monitoring. Hardware vendors draw from South Korean memory components, Chinese lithium-polymer cells, and Japanese optical sensor substrates. Tariff exposure on Chinese-manufactured compression therapy housings threatens margin stability for recovery device specialists. Distribution runs through direct-to-consumer channels for amateur segments and GPO-negotiated contracts for institutional athletic departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data subscription attach rates expand faster than hardware refresh cycles across collegiate and professional procurement channels, converting one-time device sales into recurring platform revenue that sustains customer lifetime value through multi-year analytics contracts.
For Market Incumbents: Secure ISO 13485 certification depth to filter mid-tier competitors from NCAA Division I procurement pipelines, and deepen backward integration into custom ASIC design to reduce Taiwan foundry dependency. Subscription unbundling by athletic department procurement officers threatens hardware margin capture, making algorithmic platform stickiness the priority defensive lever. For New Entrants and Emerging Players: Anchor in Australian and United Kingdom defense procurement channels piloting stress-resilience monitoring systems, where regulatory pathways remain less congested than FDA-cleared professional sports markets. Employer wellness mandates in Germany and the Netherlands represent the most penetrable demand vertical, with corporate benefit expenditure converting individual fitness purchases into subsidized enterprise subscriptions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors medical-grade sensor specialists with FDA-cleared algorithms and established collegiate athletic relationships over consumer wellness hardware vendors facing margin compression. Long-term viability hinges on regulatory moat durability and data platform switching costs. Watch for EU AI Act enforcement discretion shifts that bifurcate product roadmaps between diagnostic-grade US deployments and wellness-tier European offerings.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acquisition | FDA-cleared vendors filter mid-tier competitors from NCAA Division I procurement pipelines. |
| Data Platform Integration | Algorithmic subscription stickiness offsets hardware margin erosion from procurement unbundling. |
| Defense Channel Expansion | Australian and UK military pilots extend elite athletic protocols into adjacent tactical fitness verticals. |
| ASIC Design Backward Integration | In-house silicon development reduces Taiwan foundry dependency and sustains hardware-software integration. |
| EU AI Act Compliance Bifurcation | Separate wellness-tier and diagnostic-grade feature sets manage European certification timeline risk. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR conformity assessments, collegiate athletic procurement databases, and GPO contract records. Interviews with biomedical engineers, athletic department procurement officers, regulatory affairs specialists, and sports science researchers inform demand-side segmentation. SEC filings from listed wearable vendors and venture financing disclosures from private analytics platforms provide supply-side validation. Bottom-up device shipment estimates and top-down subscription revenue analysis triangulate market sizing.
Segmentation dimensions modeled include product type, application, end user, and technology across the analysis window. CAGRs derive from regression analysis of historical procurement patterns and regulatory pathway velocity. Forecast inputs incorporate NCAA mandate expansion timelines, EU AI Act risk classification implementation, and photoplethysmography miniaturization curves from optical sensor foundry roadmaps.
Material uncertainties — FDA software-as-medical-device pathway evolution, Taiwan semiconductor capacity constraints, and EU AI Act enforcement discretion shifts — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as collegiate procurement unbundling patterns and defense channel pilot outcomes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Weight Management Market
Health and Wellness
Personalized Retail Nutrition and Wellness Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Yoga Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Asia Pacific Weight Management Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
UAE Weight Loss Market