
 UAE Smart Lighting Market | 2026-2036
UAE Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Smart Lighting Market Intelligence
Multi-source procurement for LED controllers and sensor modules is decoupling from traditional single-vendor building automation contracts. Signify Holding dominates the professional channel through its Interact platform, while Schneider Electric anchors large infrastructure bids with integrated power management architectures. Global Light & Power LLC competes aggressively in municipal streetlight retrofit tenders across the northern emirates.
Smart lighting denotes networked luminaire systems incorporating solid-state emitters, occupancy sensors, and wireless control protocols to enable automated dimming, spectral tuning, and energy telemetry. LED-based installations command the installed base due to luminous efficacy exceeding 150 lm/W and compatibility with digital drivers. Wi-Fi and Zigbee connectivity segments are expanding fastest as hospitality operators in Dubai prioritize guest-room personalization and facility managers demand interoperable mesh topologies.
MOHAP enforces electrical safety and energy performance standards for connected fixtures deployed in healthcare and public buildings, while ESMA's UAE Energy Label program mandates minimum efficacy thresholds that accelerate LED displacement of legacy HID sources. Stakeholders must monitor Matter protocol certification timelines and evolving federal green building codes to avoid stranded technology commitments in long-duration infrastructure contracts.
Market Dynamics
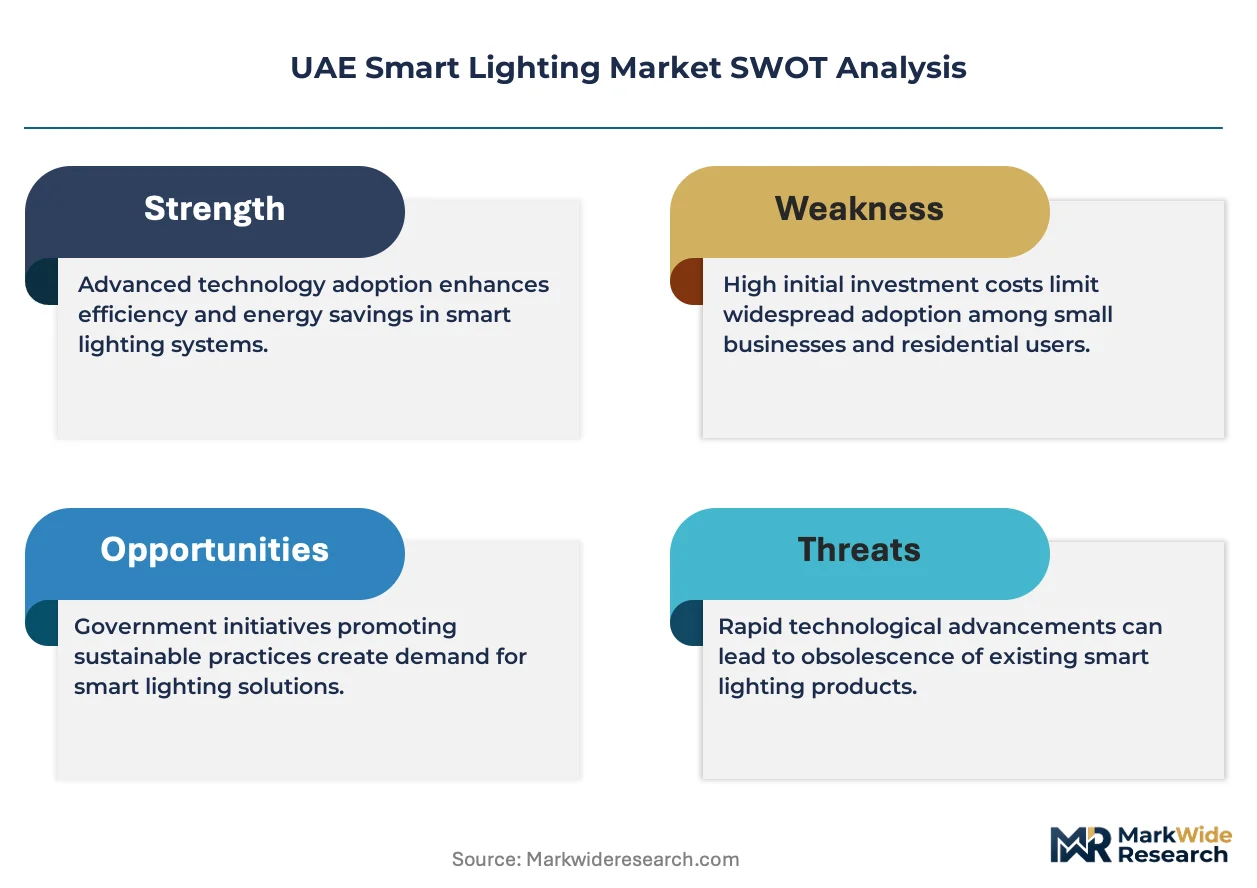
Matter protocol certification timelines and MOHAP efficiency mandates are decoupling procurement decisions from legacy single-vendor building automation contracts, forcing facility managers toward interoperable mesh topologies and multi-source controller strategies.
Growth Catalysts
- MOHAP Efficiency Mandates:Healthcare and public building regulations enforce minimum efficacy thresholds that accelerate LED displacement of legacy HID sources across Dubai and Abu Dhabi.
- Hospitality Personalization Demand:Guest-room spectral tuning and automated dimming requirements in Dubai's luxury hotel sector pull Wi-Fi and Zigbee connectivity into premium retrofit specifications.
- Saadiyat Island Development Pipeline:Cultural district construction timelines concentrate demand for connected luminaire systems with embedded occupancy sensors and energy telemetry.
Market Restraints
- Controller Supply Concentration:Digital driver and sensor module sourcing concentrates among East Asian semiconductor fabricators, exposing procurement to shipping lane volatility.
- Retrofit Capex Compression:Municipal streetlight tenders across northern emirates prioritize lowest-first-cost bids over lifecycle energy savings, constraining premium connected fixture penetration.
- Legacy HID Infrastructure Lock-in:Existing high-pressure sodium installations in industrial zones carry sunk wiring investments that delay full-network replacement cycles.
Strategic Opportunities
- Sharjah Smart City Expansion:Underpenetrated emirate-level infrastructure programs present first-mover positioning for interoperable platform providers outside Dubai-Abu Dhabi concentration.
- Healthcare Human-Centric Lighting:MOHAP-regulated patient recovery environments create specification pull for circadian-rhythm-tuned spectral systems in hospital new-builds.
- Matter Protocol Convergence:Cross-ecosystem interoperability certification enables single-app control architectures that reduce facility management training overhead.
Industry Challenges
- Mesh Network Commissioning Expertise Gap:Shortage of certified technicians for Zigbee and Thread topology optimization delays project handover timelines in hospitality rollouts.
- ESMA Certification Pipeline Bottlenecks:UAE Energy Label testing queue lengths extend product launch windows for imported LED driver assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Smart Lighting Market |
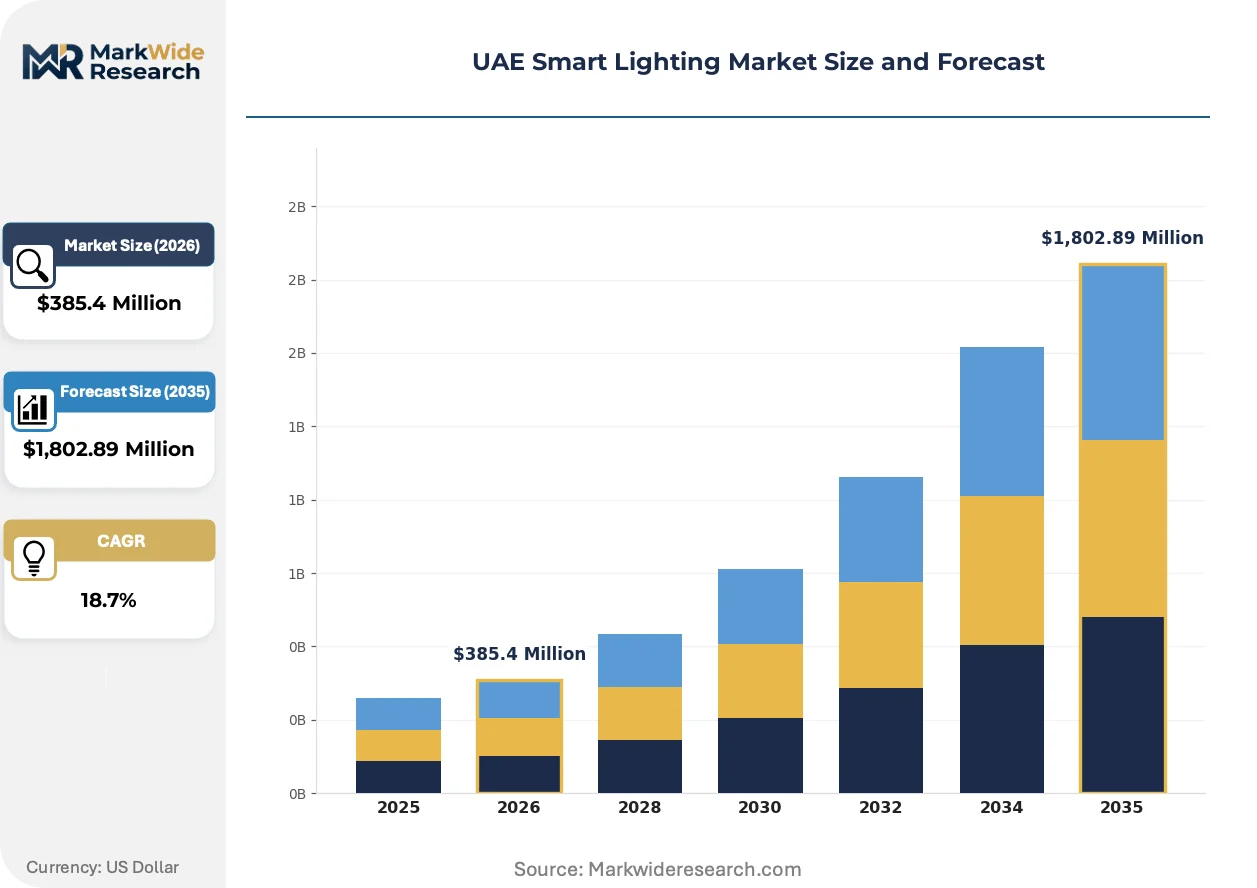
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,802.89 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, Fluorescent, HID Technology: Wi-Fi, Zigbee, Bluetooth, Powerline Communication End User: Residential, Commercial, Industrial, Municipal Installation: Indoor, Outdoor, Smart Cities, Smart Homes |
| Companies Covered | Honeywell International Inc., General Electric Company, Schneider Electric, Trans Light Electricals, Eaton Corporation, Signify Holding, OSRAM Light AG, Global Light & Power LLC, Philips Lighting N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Smart Lighting Market Strategic Shifts & Innovations
Wireless control protocols and solid-state driver architectures are compressing the traditional separation between luminaire hardware and building management software, enabling real-time energy telemetry to reshape facility operations.
Li-Fi visible light communication is converging with LED downlight form factors to embed high-bandwidth data transmission within existing illumination infrastructure. Dubai International Airport and select luxury hospitality operators are piloting guest Wi-Fi offload through ceiling-mounted luminaires. This convergence is compressing the distinction between lighting and IT infrastructure procurement categories.
MOHAP's 2023 technical guidelines for electrical safety in healthcare-connected fixtures mandate isolation-rated drivers and encrypted wireless commissioning protocols. The industrial consequence elevates compliance costs for imported assemblies while creating preference for pre-certified platform ecosystems. Dubai's hospital new-build pipeline shows strongest response, with specifications increasingly requiring documented cybersecurity attestations alongside photometric performance.
Facility managers in Abu Dhabi's commercial towers are unbundling long-term maintenance contracts from initial equipment supply, shifting toward performance-based service agreements with uptime guarantees. This displaces traditional lump-sum procurement through engineering consultants. The pattern is most visible in Grade A office stock on Al Maryah Island and Reem Island developments.
UAE Smart Lighting Market Segmentation
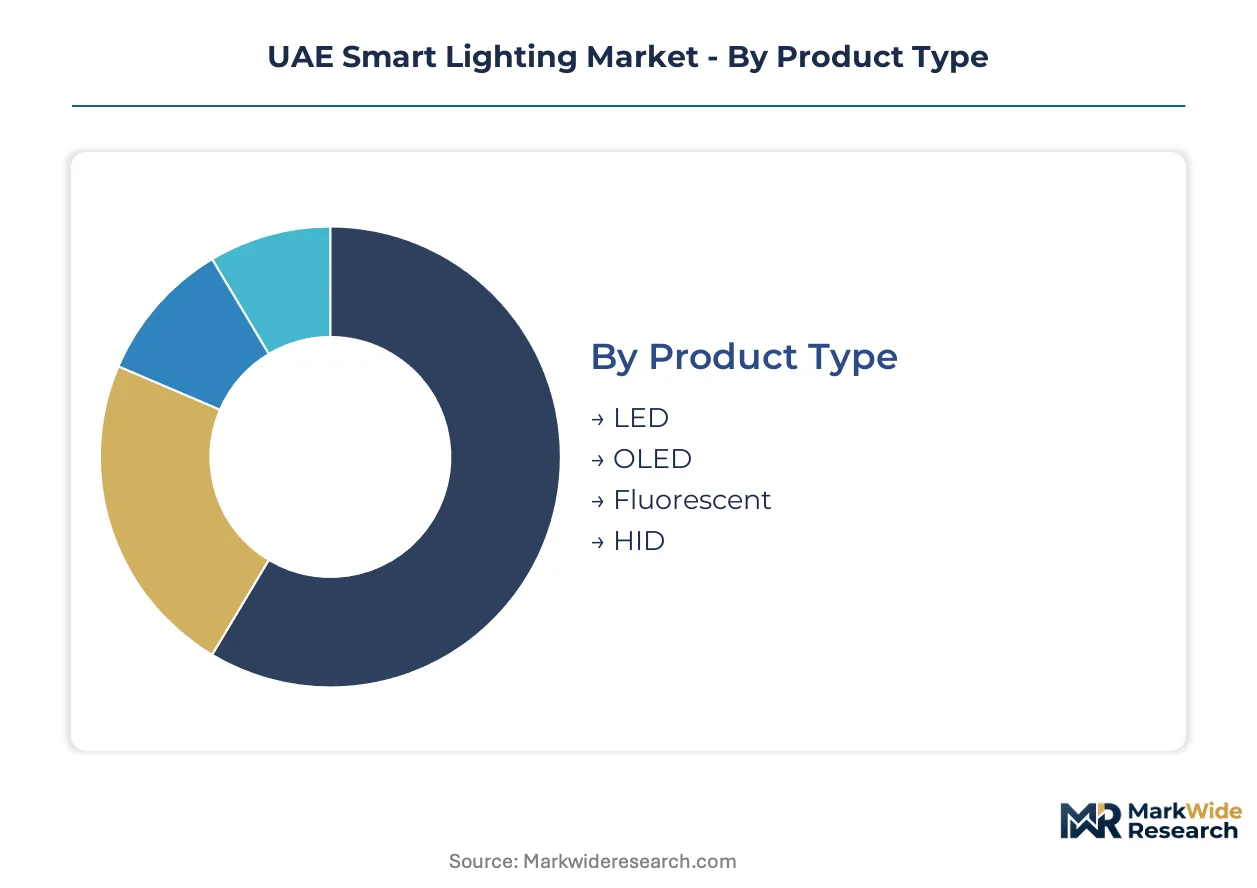
Procurement patterns in the UAE diver sharply across application contexts, with hospitality operators prioritizing guest-room personalization while municipal buyers face capex compression. Technology choices cluster around interoperability mandates and existing building automation investments.
Product Type:
Cost tier separates specification-grade installations from commodity retrofit replacements across Dubai and Abu Dhabi project pipelines.
- LED:Solid-state emitters delivering luminous efficacy above 150 lm/W with digital driver compatibility. Demand concentrates in Saadiyat Island cultural district developments where MOHAP efficiency mandates enforce minimum thresholds and energy telemetry integration.
- OLED:Thin-film organic emitters enabling uniform surface illumination without point-source glare. Hospitality operators on Al Maryah Island specify OLED panels for premium guest-room ambient layers where spectral tuning supports circadian programming.
- Fluorescent:Legacy linear installations persisting in northern emirate municipal facilities with constrained maintenance budgets.
- HID:High-pressure sodium and metal halide sources retained in industrial zones with sunk wiring infrastructure delaying full-network replacement cycles.
Volume sits with LED; growth tilts toward OLED.
Technology:
Customer type determines protocol selection, with facility managers demanding interoperable mesh topologies and residential developers favoring single-app ecosystems.
- Wi-Fi:IP-native connectivity leveraging existing enterprise infrastructure for direct cloud integration. Commercial towers on Reem Island deploy Wi-Fi backbones to unify lighting controls with HVAC and access management under single-dashboard operations.
- Zigbee:Low-power mesh protocol enabling extended device counts without network congestion. Luxury hospitality retrofits across Dubai prioritize Zigbee for guest-room personalization where battery-powered sensors reduce wiring disruption.
- Bluetooth:Beacon-enabled commissioning and proximity-based control for small-scale residential deployments.
- Powerline Communication:Carrier-current signaling over existing electrical conductors in heritage building retrofits where wireless penetration faces structural interference.
Deployment scale favors Wi-Fi; expansion velocity clusters around Zigbee.
End User:
Application maturity shapes procurement sophistication, with healthcare and hospitality leading specification complexity while industrial buyers lag on connected fixture adoption.
- Commercial:Grade A office stock and retail environments driving performance-based service agreements with uptime guarantees. Al Maryah Island developments unbundle maintenance contracts from equipment supply, shifting procurement toward outcome-based arrangements.
- Municipal:Streetlight retrofit tenders across Sharjah and northern emirates constrained by lowest-first-cost bidding criteria that suppress premium connected fixture penetration.
- Residential:Smart home integration demand concentrated in Dubai's high-end villa developments.
- Industrial:Warehouse and manufacturing facilities with legacy HID lock-in delaying network replacement cycles.
Revenue concentrates in Commercial; steepest expansion trajectory appears in Municipal as federal efficiency mandates tighten.
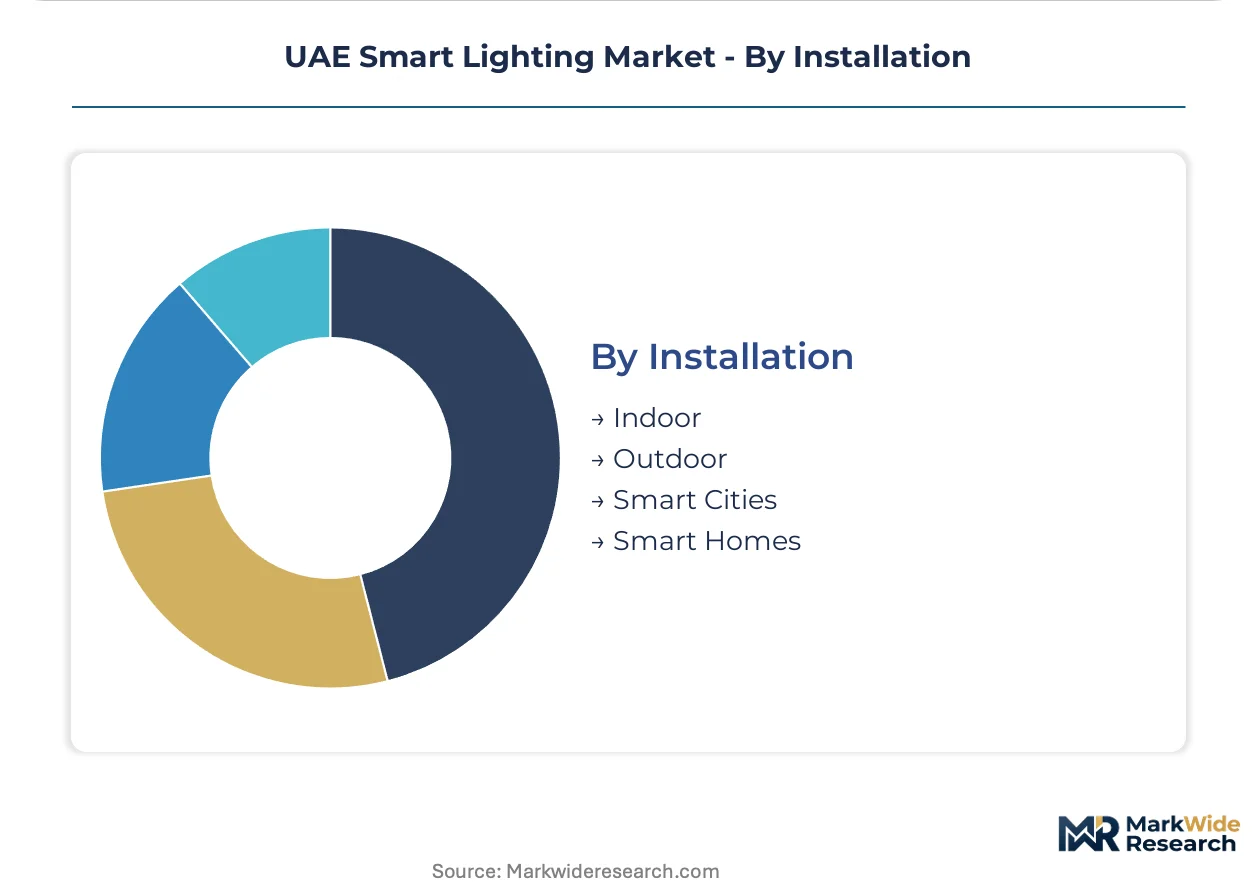
Installation:
Geography within the UAE determines infrastructure readiness, with Dubai's smart city districts commanding fully networked deployments and emerging emirates requiring staged retrofit approaches.
- Smart Cities:Integrated urban platforms embedding occupancy sensors and energy telemetry within streetlight and public building networks. Dubai's smart city districts concentrate demand for connected luminaire systems with real-time operational visibility.
- Indoor:Guest-room and workspace applications where spectral tuning and automated dimming respond to occupancy patterns and daylight harvesting algorithms.
- Outdoor:Façade and landscape illumination facing harsh thermal cycling and sand abrasion specifications.
- Smart Homes:Residential automation with Matter protocol convergence enabling cross-ecosystem interoperability.
Project pipeline depth favors Smart Cities; technology refresh cycles run fastest in Indoor hospitality specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in East Asia supply the digital drivers and sensor modules anchoring UAE procurement networks. Dubai and Abu Dhabi concentrate specification-grade demand through smart city mandates and hospitality developments. Federal efficiency regulations cascade procurement sophistication across all seven emirates.
Dubai
Saadiyat Island cultural district construction drives specification-grade connected luminaire procurement with embedded occupancy sensors. MOHAP efficiency mandates enforce minimum efficacy thresholds for healthcare-connected fixtures in new hospital builds. Downtown smart city districts concentrate demand for fully networked streetlight deployments with real-time operational visibility.
Abu Dhabi
Al Maryah Island Grade A office stock unbundles maintenance contracts from equipment supply toward performance-based service agreements. ESMA's UAE Energy Label program accelerates LED displacement of legacy HID sources across public building retrofits. Reem Island developments deploy Wi-Fi backbones to unify lighting controls with HVAC under single-dashboard operations.
Sharjah
Underpenetrated emirate-level infrastructure programs present first-mover positioning for interoperable platform providers outside Dubai-Abu Dhabi concentration. Federal green building code evolution tightens procurement criteria for municipal streetlight tenders. Industrial zones retain legacy high-pressure sodium installations with sunk wiring investments delaying full-network replacement cycles.
Northern Emirates
Ras Al Khaimah and Fujairah municipal streetlight retrofit tenders prioritize lowest-first-cost bidding criteria over lifecycle energy savings. Constrained maintenance budgets sustain legacy fluorescent linear installations in government facilities. Heritage building retrofits deploy powerline communication over existing electrical conductors where wireless penetration faces structural interference.
UAE Smart Lighting Market Key Industry Players
Global majors compete with regional champions across platform interoperability and project financing capabilities. Signify Holding and Schneider Electric anchor the professional channel through integrated control architectures, while Global Light & Power LLC competes aggressively in municipal infrastructure bids. The vendor base separates into three archetypes: platform-integrated multinationals, power-management specialists, and regional retrofit contractors. Dominant competitive moves include Matter protocol certification races and performance-based service contract unbundling from equipment supply.
Among platform-integrated multinationals, Signify Holding and Schneider Electric occupy positions anchoring large infrastructure bids with interoperable ecosystems. Global Light & Power LLC represents the regional contractor archetype competing in price-sensitive municipal tenders across underpenetrated emirates. Honeywell International Inc. and General Electric Company sit within the diversified industrial conglomerate tier leveraging existing building automation relationships. These named entities exemplify how competitive positioning fragments across specification complexity versus cost compression vectors.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| General Electric Company |
| Schneider Electric |
| Trans Light Electricals |
| Eaton Corporation |
| Signify Holding |
| OSRAM Light AG |
| Global Light & Power LLC |
| Philips Lighting N.V. |
| Others |
Cost & Logistics Intelligence
Sovereign-backed infrastructure developers and family-owned electrical contractors anchor procurement networks across the UAE, concentrating pricing power among platform-integrated multinationals while fragmenting margins for regional retrofit specialists competing on municipal tenders.
Pricing Analysis
Warranty bundling and long-term maintenance contracts separate premium-tier offerings from commodity procurement in municipal streetlight tenders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ESMA's UAE Energy Label program and MOHAP technical guidelines. Pricing pressure stems from lowest-first-cost bidding criteria in northern emirate municipal tenders, compressing margins for connected fixture suppliers. Municipal buyers exhibit highest price sensitivity; hospitality operators on Saadiyat Island and Al Maryah Island demonstrate lowest sensitivity due to specification-grade requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Signify Holding and Schneider Electric for integrated control architectures, while regional distributors serve fragmented contractor demand across underpenetrated emirates. Semiconductor fabrication clusters in Taiwan, South Korea, and China supply digital drivers and sensor modules. Rare earth phosphors, gallium nitride substrates, and silicon carbide wafers constitute critical input dependencies. Single-source vulnerability concentrates in East Asian controller sourcing, exposing procurement to shipping lane volatility. Distribution runs through authorized dealer networks for professional-grade installations and open-market procurement for commodity retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE Smart Lighting Market functions as a cost-of-compliance arena where MOHAP efficiency mandates and Matter protocol certification timelines erect barrier-to-entry moats favoring pre-certified platform ecosystems over import-assemblers.
For Market Incumbents: Acquire certified commissioning expertise to address the mesh network technician shortage delaying hospitality project handovers. Deepen backward integration into digital driver sourcing to mitigate East Asian semiconductor supply concentration. Fortify platform interoperability through Matter protocol certification races against Schneider Electric's integrated power management architectures.
For New Entrants and Emerging Players: Capture first-mover positioning in Sharjah's underpenetrated smart city infrastructure programs outside Dubai-Abu Dhabi concentration. Target municipal streetlight retrofit tenders across Ras Al Khaimah and Fujairah where lowest-first-cost criteria currently suppress premium connected fixture penetration. Deploy powerline communication solutions for heritage building retrofits where wireless penetration faces structural interference.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional retrofit contractors with established municipal relationships in northern emirates during federal green building code tightening. Long-term viability hinges on Matter protocol convergence enabling cross-ecosystem interoperability that reduces facility management training overhead. Monitor ESMA certification pipeline queue lengths as inflection indicator for imported LED driver assembly market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-ecosystem interoperability reduces facility management training overhead for hospitality operators. |
| Performance-Based Service Agreements | Uptime guarantees unbundle maintenance from equipment supply in Al Maryah Island Grade A offices. |
| Healthcare Human-Centric Lighting | Circadian-rhythm-tuned spectral systems meet MOHAP technical guidelines for patient recovery environments. |
| Li-Fi Infrastructure Convergence | Visible light communication embeds high-bandwidth data transmission within Dubai International Airport luminaires. |
| Sharjah Smart City Expansion | Underpenetrated emirate-level programs present positioning for interoperable platform providers. |
Research Approach
Independent corroboration across facility management directors, electrical engineering consultants, and municipal procurement officers underwrites the qualitative findings. Primary fieldwork engaged lighting controls specialists, hospitality technology managers, and smart city infrastructure planners across Dubai, Abu Dhabi, and Sharjah. Secondary validation drew from ESMA regulatory filings, MOHAP technical guideline releases, and federal green building code documentation. Bottom-up demand modeling triangulated against top-down infrastructure spend projections across the analysis window.
Rate-of-change decomposition segmented volume and value trajectories by product type, connectivity protocol, end-user application, and installation context. The analytical framework modeled LED displacement dynamics, wireless protocol adoption curves, and service contract unbundling patterns throughout the forecast period. CAGRs derived from infrastructure pipeline tracking, efficiency mandate compliance timelines, and hospitality development occupancy forecasts. Matter protocol certification velocity and ESMA testing queue durations served as industry-specific forecast inputs.
The model holds under stable federal regulatory enforcement and sustained smart city infrastructure commitment; deviation in semiconductor supply availability or shipping lane disruption would shift procurement timelines. Forecasts reflect documented assumptions regarding MOHAP mandate expansion and Matter ecosystem convergence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Ambient Lighting Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Bulb Market
Lighting
Battery Operated Lights Market
Lighting
Human Centric Lighting Market
Lighting
OLED Lightening Panels Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
UV Lamps Market
Lighting
Solar Rope Light Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
North America Smart Lighting Market
Lighting
Residential Lighting Fixtures Market
Lighting
Asia-Pacific Lighting Control Market
Lighting
Intelligent Lighting Controls Market
Lighting
COB Photo Light Market
Lighting
Smart Industrial Illumination Market