
 OLED Lightening Panels Market | 2026-2036
OLED Lightening Panels Market Size, Share, and Industry Trends Forecast 2026-2036
OLED Lightening Panels Market Analytics
Phosphorescent emitter materials are repositioning cost structures across the OLED lightening panel supply chain, reducing reliance on iridium-heavy architectures. LG Display leverages vertical integration into vapor deposition equipment to sustain wafer-scale throughput advantages. OLEDWorks anchors its competitive stance through specialized R&D intensity in flexible substrate bonding. Konica Minolta competes via proprietary thin-film encapsulation that extends operational lifespans in humid environments.
OLED lightening panels are solid-state luminaires employing organic electroluminescent compounds deposited between conductive electrodes on glass or polymer substrates, emitting diffuse surface light without secondary optics. These panels serve commercial and architectural applications requiring uniform luminance, minimal heat emission, and design-integrated form factors below 2mm thickness. Panel-format products dominate current revenue pools due to established ceiling-grid compatibility, while flexible technology segments capture the fastest expansion as curved architectural envelopes and automotive interior surfaces demand conformable illumination. Transparent variants occupy emerging niche positions where daylight harvesting and see-through display integration justify premium positioning.
EPA Energy Star certification and the EU Ecodesign Directive shape product efficiency benchmarks and market access requirements for luminaire manufacturers. Japan's METI sets domestic efficiency targets that influence emitter material selection and driver circuit design across Asian supply chains. Stakeholders must monitor divergence between regional efficiency test protocols and emerging circular-economy material-recovery mandates that could alter substrate and encapsulation choices.
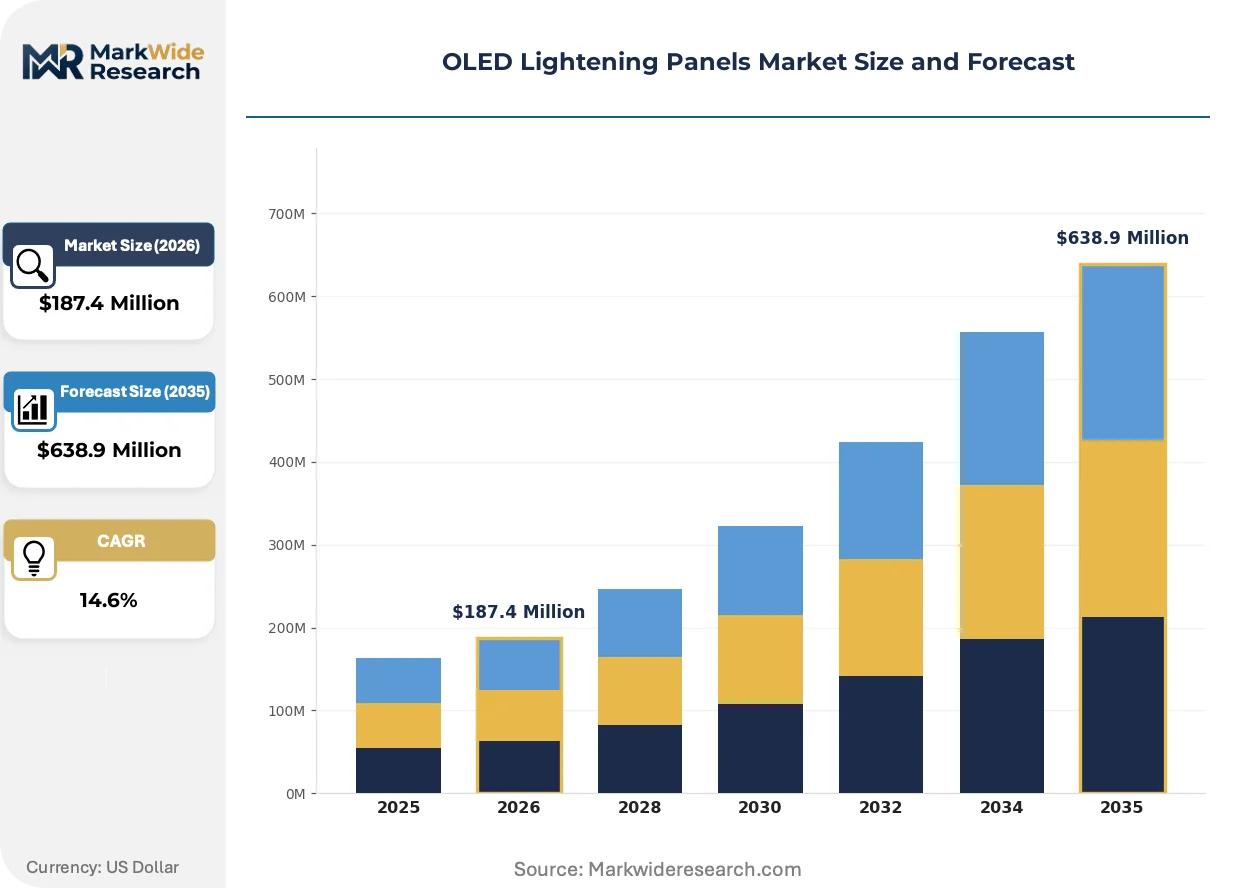
Market Dynamics
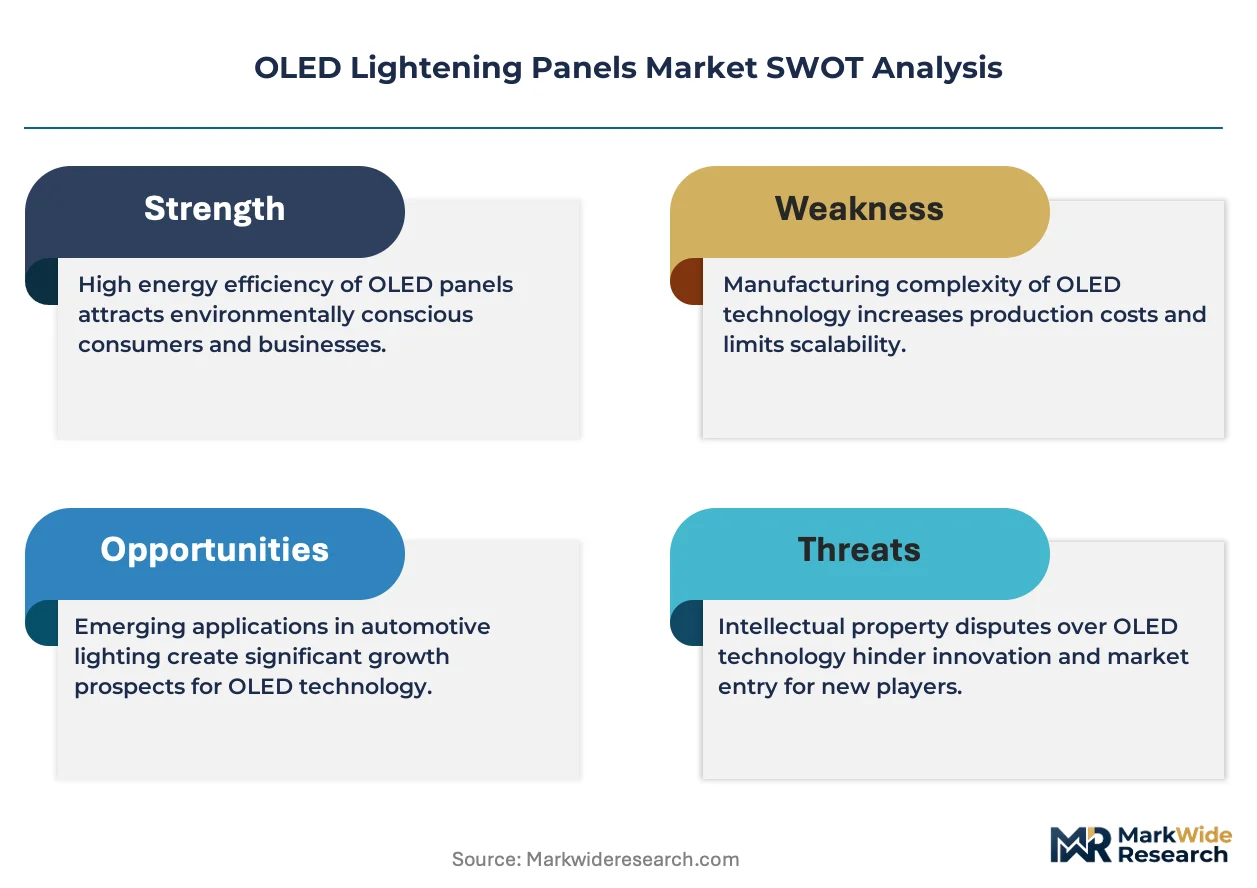
The EU Green Deal's building efficiency mandates are compressing replacement cycles for conventional fluorescent and LED edge-lit systems across commercial interiors, forcing specification shifts toward surface-emitting organic luminaires.
Growth Catalysts
- EU Ecodesign Directive:The directive mandates minimum efficacy thresholds for commercial luminaires, disqualifying legacy fluorescent troffers from new construction and major renovation projects across Germany, France, and the Netherlands.
- Architectural lighting designers:Design studios in hospitality and corporate sectors specify OLED panels for glare-free illumination in wellness-focused interiors, prioritizing visual comfort metrics over raw lumen output.
- Phosphorescent emitter materials:These compounds reduce iridium loading in organic stacks, lowering bill-of-materials costs and enabling price parity with premium LED edge-lit alternatives in mid-market specifications.
Market Restraints
- Iridium price volatility:The platinum-group metal anchors phosphorescent dopant chemistry; supply concentration in South African and Russian mining operations creates input cost instability for emitter material suppliers.
- Vapor deposition equipment scarcity:Canon Tokki's near-monopoly on large-area organic vapor phase deposition systems creates capacity bottlenecks for panel manufacturers scaling beyond pilot volumes.
- LED retrofits:Existing LED edge-lit installations with 50,000-hour rated lifespans delay replacement demand in cost-constrained municipal and educational facilities.
Strategic Opportunities
- Automotive interior surfaces:Curved dashboard and ceiling applications demand conformable illumination; flexible OLED substrates enable seamless integration with molded polymer trim components.
- Japan's METI efficiency targets:Domestic incentives for solid-state lighting with sub-2mm form factors accelerate emitter material qualification programs for humid-environment automotive specifications.
- Transparent daylight harvesting:See-through panel variants integrate with building management systems for automated glare control, commanding premium positioning in net-zero commercial developments.
Industry Challenges
- Thin-film encapsulation expertise:The barrier layer deposition process requires atomic-layer precision; talent scarcity in vacuum coating engineering extends product qualification timelines.
- EPA Energy Star certification timelines:Luminaire manufacturers face 8-14 month approval cycles for diffuse surface-emitting products, compressing revenue recognition for new panel introductions.
- Legacy ceiling-grid incompatibility:Standard T-bar systems require mechanical adapters for sub-2mm panels, adding installation labor costs that erode total-cost-of-ownership advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OLED Lightening Panels Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Modules, Components, Systems Technology: Active Matrix, Passive Matrix, Flexible, Transparent End User: Commercial Spaces, Residential Areas, Automotive Applications, Healthcare Facilities Installation: Ceiling Mounted, Wall Mounted, Free-standing, Integrated |
| Companies Covered | LG Display, OLEDWorks, Sumitomo Chemical, Lumiotec, Kaneka, Osram, NEC Lighting, Konica Minolta, Signify, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OLED Lightening Panels Market Evolving Landscape
Emitter material chemistry and deposition architecture are converging to reshape cost structures and application boundaries for organic luminaires. Three developments are restructuring competitive positioning.
Phosphorescent TADF (thermally activated delayed fluorescence) emitter systems are electrifying efficiency benchmarks in commercial panels. These materials harvest triplet excitons without iridium centers, enabling 90+ lm/W efficacy in surface-emitting formats. Architectural lighting designers in German corporate interiors specify TADF-based panels for LEED Platinum certifications. The technology is electrifying mid-market penetration by collapsing the premium over LED alternatives.
REACH substance restrictions are forcing reformulation of organic charge-transport layers. The regulation's candidate list expansion threatens legacy aromatic amine compounds used in hole-injection stacks. Panel manufacturers serving EU commercial markets accelerate alternative material qualification with emitter suppliers. Germany's KBA automotive lighting standards are tightening parallel substance restrictions, creating dual-compliance pressure for flexible automotive panel developers.
Specification authority is migrating from electrical contractors to lighting design consultants. Large hospitality and workplace projects now route panel selection through independent design studios rather than traditional distributor channels. This disintermediation compresses price transparency and accelerates preference for brand-recognized organic luminaire suppliers. The shift is most visible in Netherlands and Denmark commercial developments, where design-build contracts consolidate procurement decisions under architectural firms.
OLED Lightening Panels Market Segmentation
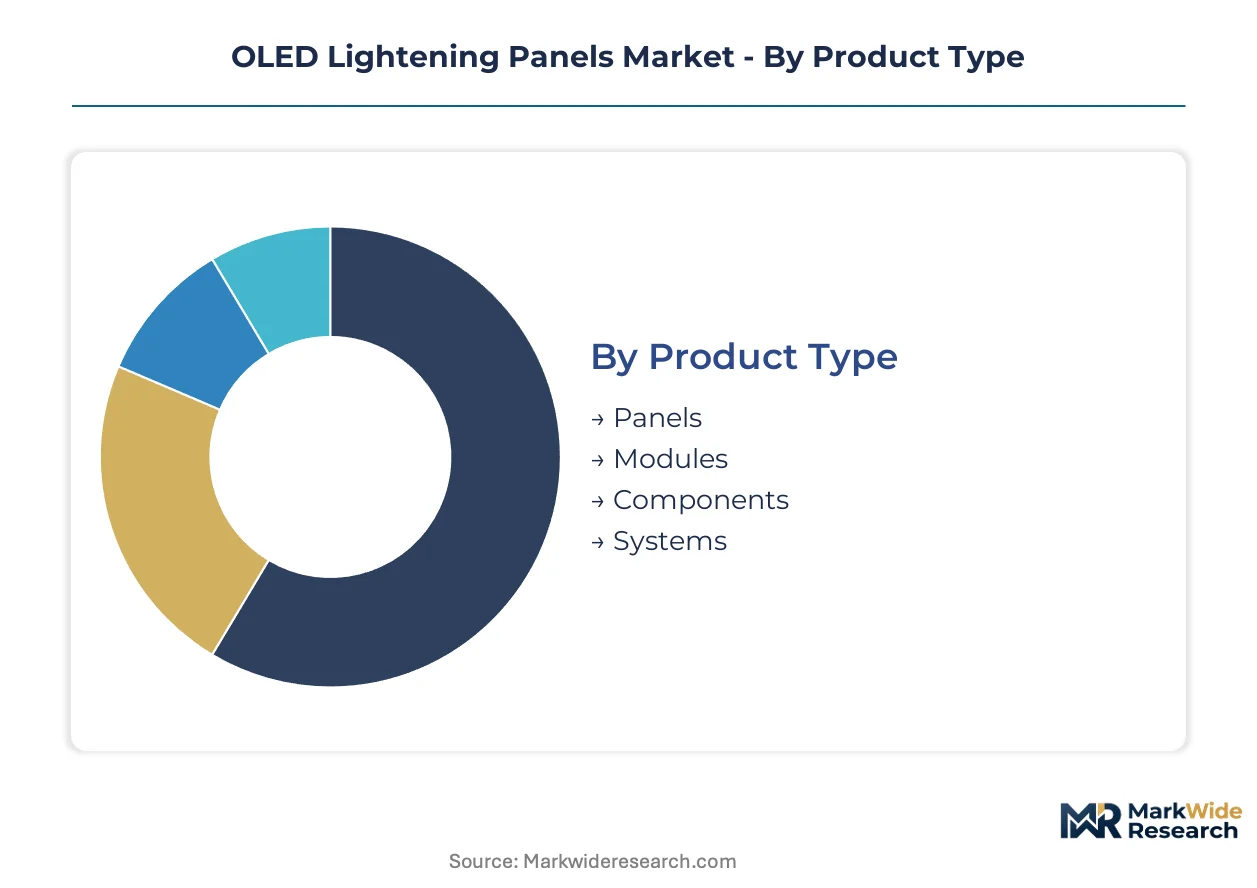
OLED lighting panels serve heterogeneous application environments where form factor, control architecture, and mounting constraints dictate procurement patterns. Segmentation reveals how specification authority migrates across product categories and installation contexts, reshaping vendor go-to-market requirements.
Product Type:
Replacement cycles for legacy fluorescent and LED edge-lit systems vary dramatically by product format, with integrated systems commanding longer evaluation periods than drop-in panel substitutes.
- Panels:Surface-emitting tiles in 600x600mm and custom formats dominate commercial retrofit specifications. German municipal programs and Dutch corporate interiors drive specification volume for glare-free ceiling-grid replacements.
- Modules:Sub-assemblies with integrated drivers and thermal management suit luminaire OEMs seeking design flexibility. Japanese automotive suppliers qualify modular formats for curved interior applications under METI efficiency guidelines.
- Components:Bare emitter substrates and driver electronics serve specialized integrators building custom architectural installations.
- Systems:Complete luminaire assemblies with building management integration target net-zero commercial developments requiring daylight harvesting coordination.
Panels sit at the top of the volume ranking, with Modules climbing the fastest as automotive and hospitality sectors demand application-specific configurations.
Technology:
Cost structures stratify sharply across deposition architectures, with vapor deposition equipment scarcity favoring manufacturers with captive process technology or established equipment partnerships.
- Active Matrix:Thin-film transistor backplanes enable pixel-level dimming control for tunable white and circadian lighting applications. Healthcare facilities in France and Germany specify active matrix panels for patient room environments requiring precise intensity modulation.
- Flexible:Polyimide and metal-foil substrates permit bending radii below 10mm for automotive dashboard and ceiling contours. Japan's humid-environment automotive standards accelerate qualification programs for flexible encapsulation systems.
- Passive Matrix:Simpler row-column addressing suits cost-constrained architectural accent lighting with uniform output requirements.
- Transparent:Partially transmissive emitters integrate with glazing systems for see-through display and daylight modulation functions in premium commercial facades.
Active Matrix holds the dominant revenue share, while Flexible formats gain share fastest as curved surface applications multiply across transportation and hospitality sectors.
End User:
Procurement sophistication diverges across customer types, with automotive and healthcare buyers imposing qualification protocols that extend vendor onboarding timelines versus commercial real estate specifications.
- Commercial Spaces:Corporate headquarters, hospitality venues, and retail environments prioritize visual comfort metrics and design integration. Netherlands and Denmark design-build contracts consolidate panel selection under architectural lighting consultants rather than electrical distributors.
- Automotive Applications:Tier-1 suppliers and OEM interior divisions demand conformable illumination for molded trim integration. Germany's KBA automotive lighting standards impose parallel substance restrictions alongside EU REACH compliance for flexible panel developers.
- Residential Areas:High-end residential specifications follow commercial design trends with extended lead times and custom form factor requirements.
- Healthcare Facilities:Patient room and surgical lighting applications require flicker-free operation and circadian tuning capabilities with stringent electromagnetic compatibility certification.
Commercial Spaces anchor current demand volumes, with Automotive Applications expanding most quickly as interior surface illumination becomes standard in electric vehicle platforms.
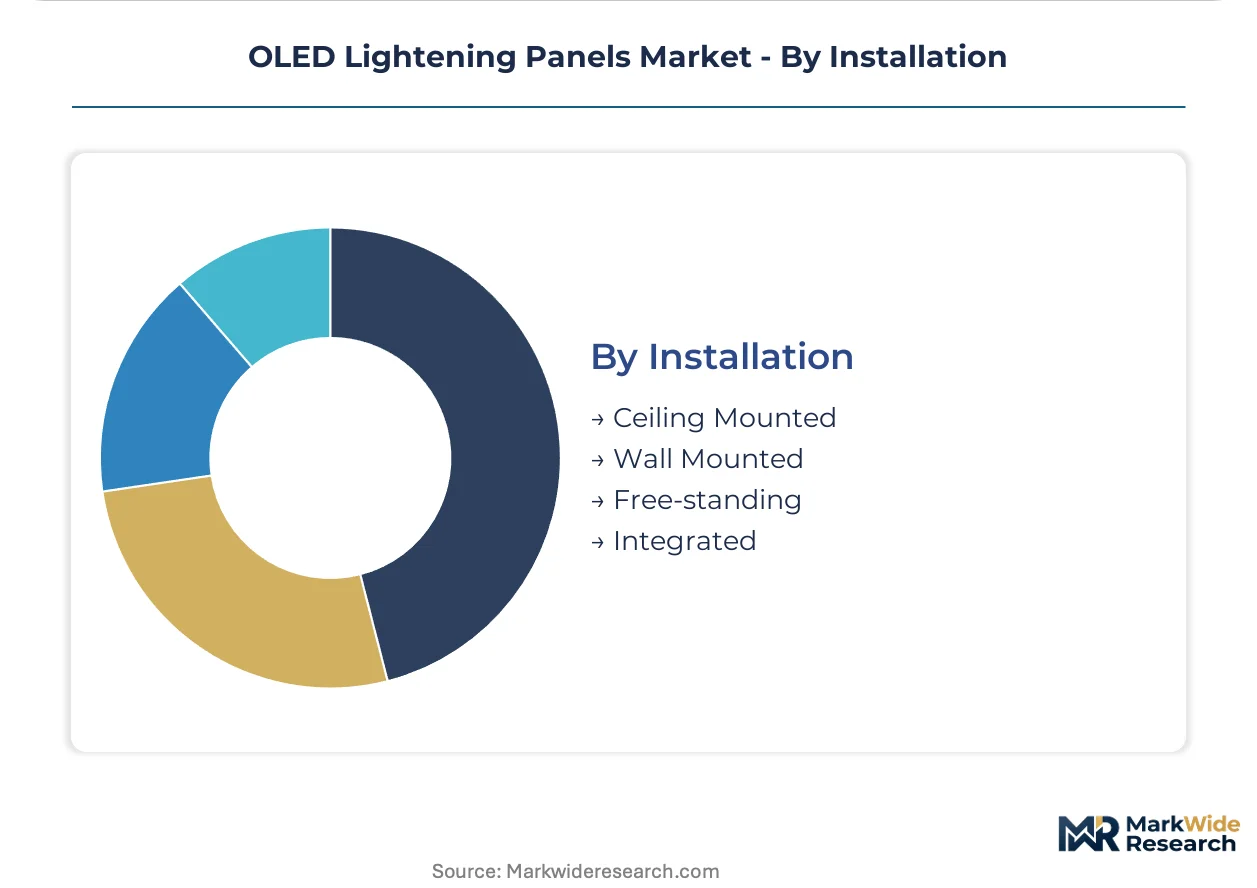
Installation:
Mounting methodology determines labor cost burdens and compatibility with existing building infrastructure, creating divergent total-cost-of-ownership profiles across installation categories.
- Ceiling Mounted:T-bar grid and surface-mount configurations dominate commercial retrofit volumes. Standard ceiling systems require mechanical adapters for sub-2mm panels, adding installation labor that erodes cost advantages in some specifications.
- Integrated:Direct bonding to architectural surfaces and furniture elements enables sub-millimeter profile lighting in millwork and custom interiors. German corporate wellness-focused interiors specify integrated panels for seamless ceiling and wall continuity.
- Wall Mounted:Vertical surface applications serve accent and task lighting functions in hospitality and workplace environments.
- Free-standing:Portable luminaire formats address temporary and flexible workspace configurations with minimal installation requirements.
Ceiling Mounted retains the largest installed base, with Integrated formats gaining traction fastest as architectural envelope design treats illumination as a surface material rather than applied fixture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal retrofit programs and design-conscious corporate interiors anchor regional specification rates for organic luminaires. The analysis examines five countries where building efficiency mandates and automotive integration demands concentrate market development.
Germany
Municipal retrofit programs in Berlin and Hamburg drive specification volume for glare-free ceiling-grid replacements. The EU Ecodesign Directive disqualifies legacy fluorescent troffers from new construction projects, accelerating organic luminaire adoption. Bavaria's automotive suppliers qualify flexible panel formats for curved interior applications under KBA lighting standards.
Japan
Automotive interior surface applications dominate qualification activity for conformable illumination systems. METI efficiency targets for solid-state lighting with sub-2mm form factors accelerate emitter material programs. Nagoya's Tier-1 supplier cluster integrates molded polymer trim components with flexible organic substrates.
United States
Healthcare facilities specify flicker-free panels for patient room circadian lighting applications. EPA Energy Star certification timelines extend product approval cycles to 8-14 months for diffuse surface-emitting formats. Greater Boston's hospital construction pipeline prioritizes visual comfort metrics in wellness-focused interiors.
Netherlands
Design-build contracts consolidate panel procurement under architectural lighting consultants rather than electrical distributors. The EU Green Deal's building efficiency mandates compress replacement cycles for conventional LED edge-lit systems. Amsterdam corporate developments specify transparent variants for daylight harvesting in net-zero commercial facades.
South Korea
Display technology cross-over drives captive supply advantages in vapor deposition equipment and emitter material integration. Domestic efficiency protocols influence driver circuit design across Asian supply chains. Seoul's electronics manufacturing cluster leverages wafer-scale throughput capabilities for panel-format production scaling.
OLED Lightening Panels Market Competitive Landscape
Backward integration into vapor deposition equipment dominates the current landscape as manufacturers secure capacity amid Canon Tokki's near-monopoly on large-area organic vapor phase deposition systems. The vendor base stratifies across three tiers: integrated display-to-lighting conglomerates with captive substrate and encapsulation capabilities; specialized organic luminaire developers focused on architectural and automotive qualification; and materials suppliers controlling phosphorescent emitter chemistry. Capacity expansion and strategic partnerships represent the dominant competitive moves, with equipment access agreements and joint development programs for flexible automotive specifications gaining priority.
Among Asia-Pacific-based conglomerates, LG Display and Sumitomo Chemical occupy positions anchored in display technology cross-over and materials chemistry control respectively. OLEDWorks exemplifies the specialized developer archetype, with its organizational structure reflecting R&D-intensive focus on substrate bonding and encapsulation expertise. These three entities represent distinct strategic postures: upstream equipment and materials control, midstream panel manufacturing scale, and downstream application-specific qualification intensity.
| Leading Market Players |
|---|
| LG Display |
| OLEDWorks |
| Sumitomo Chemical |
| Lumiotec |
| Kaneka |
| Osram |
| NEC Lighting |
| Konica Minolta |
| Signify |
| Others |
Value Network & Pricing Analysis
Iridium loading in phosphorescent emitter stacks anchors cost structures from South African mining operations through finished panel tiers. The metal's price volatility propagates downstream, forcing tiered pricing separation between premium TADF-based architectural specifications and cost-constrained passive matrix alternatives.
Pricing Analysis
Input-cost pass-through from iridium-heavy phosphorescent dopants drives three-tier pricing structure across premium, standard, and economy levels. Premium active matrix panels with METI-certified efficiency ratings command price separation from economy passive matrix formats used in accent lighting. Cost compression in mid-market specifications intensifies as TADF materials reduce iridium dependency. Municipal retrofit programs in Germany exhibit highest price sensitivity, while Dutch design-build contracts prioritize visual comfort metrics over unit economics.
Supply Chain Analysis
Freight costs for vapor deposition equipment from Japan amplify landed costs for panel manufacturers outside East Asia. Supply concentrates in South Korea, Japan, and Germany, with Seoul's electronics cluster feeding wafer-scale throughput and Nagoya's Tier-1 automotive suppliers qualifying flexible substrates. The supply chain draws from iridium mining in South Africa, phosphorescent emitter production in Japan, and glass substrate fabrication in Germany. Single-source vulnerability around Canon Tokki's organic vapor phase deposition systems creates capacity bottlenecks. Distribution runs through luminaire OEMs and architectural lighting consultants rather than traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as building efficiency mandates across the EU Green Deal force replacement cycles in commercial interiors. Regulatory tailwinds provide demand visibility that offsets technology transition risks.
For Market Incumbents: Anticipate margin compression from LED retrofit delays in cost-constrained educational facilities by deepening captive supply of vapor deposition capacity. Secure equipment access agreements with Canon Tokki or alternative deposition technology providers before qualification timelines extend. Invest in TADF emitter material partnerships to collapse premium-over-LED positioning in mid-market specifications.
For New Entrants and Emerging Players: The gap between premium flexible automotive panels and economy ceiling-grid replacements offers white-space targeting. Penetrate modular formats for Japanese automotive suppliers seeking curved interior integration under humid-environment standards. Pursue design-build channel relationships in Netherlands and Denmark where architectural consultants consolidated procurement authority.
For Investors and Strategic Acquirers: Consolidation pressure builds where thin-film encapsulation expertise concentrates among specialized developers. Long-term viability hinges on backward integration into emitter material chemistry or captive equipment access. Target acquisition profiles favor R&D-intensive substrate bonding specialists with automotive qualification pipelines. Watch for inflection when EPA Energy Star certification timelines compress below eight months, signaling regulatory pathway maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Equipment Access Partnership | Canon Tokki deposition system agreements secure wafer-scale throughput for German automotive specifications. |
| TADF Material Qualification | Phosphorescent emitter reformulation collapses iridium cost exposure in EU Ecodesign-compliant panels. |
| Flexible Substrate Scale-Up | Polyimide bonding expertise enables curved dashboard integration for Japan METI automotive targets. |
| Design-Build Channel Development | Architectural consultant relationships bypass electrical distributor price transparency in Netherlands contracts. |
| Transparent Panel Certification | Daylight harvesting integration commands premium positioning in Amsterdam net-zero commercial facades. |
Research Methodology
Direct dialogue with emitter material chemists, vapor deposition equipment engineers, architectural lighting consultants, and automotive Tier-1 procurement managers grounded qualitative findings. Secondary validation drew from EU Ecodesign Directive filings, METI efficiency standard publications, EPA Energy Star certification databases, and SEC disclosures from display technology conglomerates. Bottom-up panel shipment estimates triangulated against top-down building retrofit spending projections across Germany, Japan, and the Netherlands.
Segment-level value outputs across the projection horizon reflect modeled adoption curves for active matrix, flexible, passive matrix, and transparent technologies. The analytical framework incorporated form factor constraints, installation methodology labor costs, and regional regulatory compliance tiers. CAGRs derived from replacement cycle compression under EU Green Deal mandates and automotive interior surface illumination penetration. Forecast inputs included iridium price volatility scenarios and Canon Tokki equipment delivery lead time assumptions.
The model assumes a particular technology adoption path; alternative pathways for TADF emitter commercialization would alter the outlook. Forecasts reflect assumptions around EU Ecodesign Directive enforcement consistency and automotive qualification timeline stability. A model refresh is warranted upon material change in EPA Energy Star certification processing durations or South African iridium supply disruptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Vintage Bulb Market
Lighting
Lighting Control Components Market
Lighting
Europe Lighting Control Systems Market
Lighting
Lighting Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Global Lamps Market
Lighting
North America Outdoor Lighting Market
Lighting
Xenon Lights Market
Lighting
UAE Smart Lighting Market
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Lamps and Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Xenon Flashlamps Market
Lighting
High Bay Lighting Market
Lighting
Bacteriological Light Market
Lighting
Programmable Stage Lighting Market