
 Eye-Illuminating Gadgets Market | 2026-2036
Eye-Illuminating Gadgets Market Size, Share, and Industry Trends Forecast 2026-2036
Eye-Illuminating Gadgets Market Analytics
Silicone polymers is consolidating around LED arrays in premium eye-illuminating devices, displacing rigid plastic housings that previously dominated mid-tier SKUs. Koninklijke Philips N.V. leverages its medical-grade manufacturing infrastructure to anchor professional-tier distribution across European optometry channels. YA-MAN Ltd specializes in compact form-factor engineering for at-home consumers in East Asian markets. Panasonic Corporation sustains component sourcing advantages through captive semiconductor relationships in Japan.
Eye-illuminating gadgets are wearable or stationary devices that emit calibrated visible-spectrum or near-infrared light, typically operating at wavelengths between 480 nm and 850 nm, designed to modulate retinal photoreceptor response, melatonin suppression, or periorbital microcirculation. Light therapy devices command the largest installed base among product types, reflecting established clinical protocols for seasonal affective disorder and sleep-phase disorders. Smart contact lenses represent the fastest-expanding segment, though margin pools currently concentrate in LED glasses where Bluetooth-enabled prescription integration commands premium positioning. Energy harvesting technology remains nascent but attracts disproportionate R&D allocation as manufacturers seek to eliminate charging friction in all-day wearables.
FDA 510(k) pathways govern therapeutic claims for light-emitting devices sold into US healthcare channels, while the EU Medical Device Regulation imposes notified-body oversight on products marketed for vision enhancement or clinical outcomes. Japan's PMDA maintains distinct pharmaceutical-adjacent classification for contact-lens formats incorporating active illumination, creating dual compliance burdens for cross-border launches. Stakeholders must monitor evolving electromagnetic-exposure thresholds from IEC and WHO technical committees, as these standards will determine market-access eligibility for next-generation high-output devices before commercial scale.
Market Dynamics
Silicone polymer integration into LED array housings is compressing production timelines and enabling rapid form-factor iteration across wearable eye-tech categories. This materials transition eliminates tooling costs associated with rigid plastic injection molding, allowing manufacturers to test multiple industrial designs within single product cycles.
Growth Catalysts
- Remote Worker Circadian Health Protocols:Employer-sponsored wellness programs in the United States now subsidize light-therapy hardware for home office setups, creating institutional procurement channels.
- FDA 510(k) Clearance Precedents:Established regulatory pathways for seasonal affective disorder claims reduce commercialization uncertainty for therapeutic device entrants.
- Near-Infrared Wavelength Expansion:Clinical validation of 850 nm protocols for periorbital microcirculation is opening new indication categories beyond melatonin modulation.
Market Restraints
- Semiconductor Supply Concentration:Captive LED die production in Japanese and South Korean fabs creates allocation bottlenecks for mid-tier device manufacturers without long-term supply agreements.
- EU Medical Device Regulation Compliance Burden:Notified-body oversight requirements for vision-enhancement claims extend time-to-market by 14-22 months compared to wellness-classification routes.
- Pharmaceutical Adjacency Classification:Japan's PMDA treats illuminated contact lenses as pharmaceutical-device hybrids, imposing dual filing requirements that deter cross-border launches.
Strategic Opportunities
- German Optometry Channel Integration:Professional-tier distribution through European eye-care practices commands premium positioning unavailable through direct-to-consumer routes.
- Energy Harvesting Convergence:Integration of photovoltaic and thermoelectric harvesting into frame architectures eliminates charging friction for all-day wearable formats.
- Bluetooth-Enabled Prescription Integration:Smart glasses combining corrective lenses with calibrated light therapy address the myopia-management segment in East Asian markets.
Industry Challenges
- Photobiological Safety Certification Delays:IEC 62471 testing backlog at accredited laboratories extends pre-market validation timelines for high-output devices.
- Retinal Photoreceptor Response Variability:Individual melanopsin sensitivity differences complicate dosing standardization and create liability exposure for therapeutic claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Eye-Illuminating Gadgets Market |
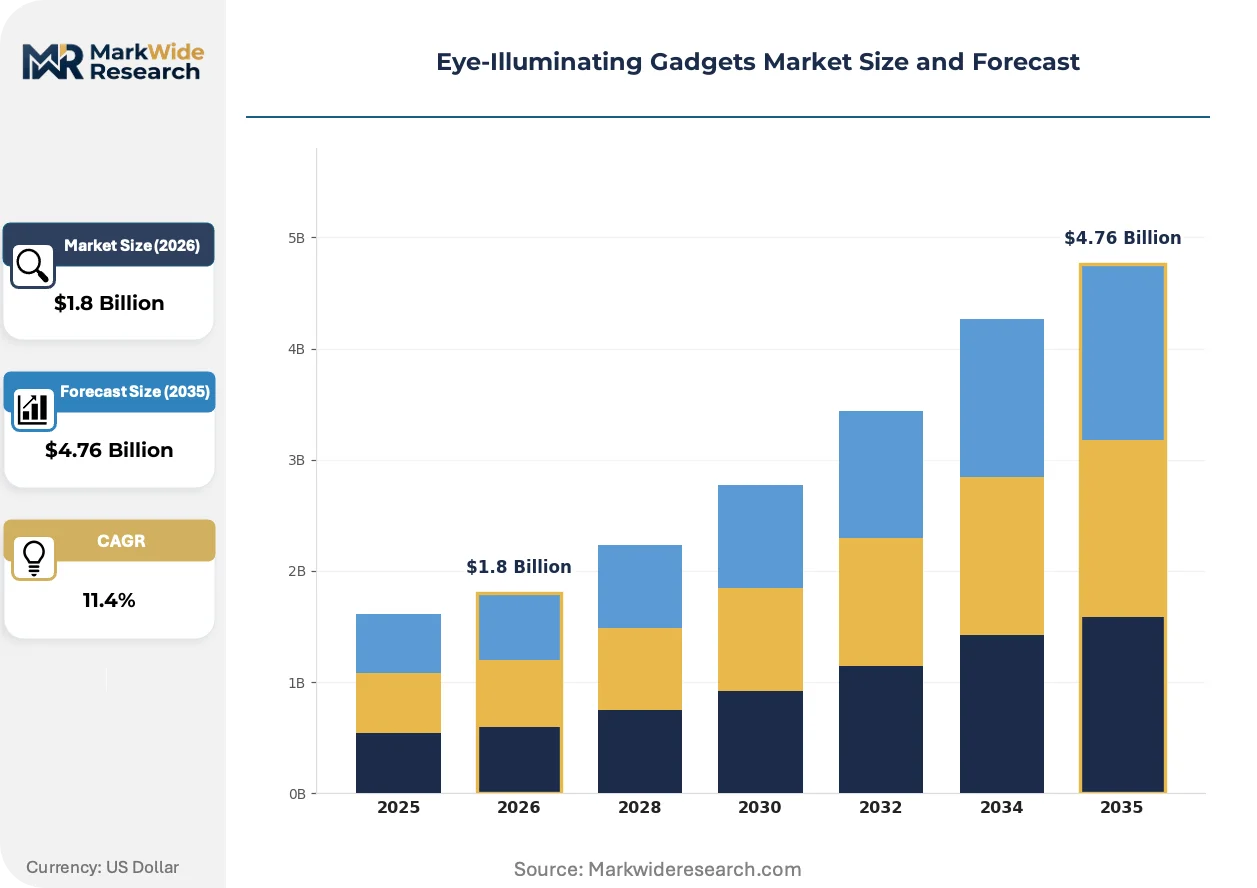
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Glasses, Light Therapy Devices, Smart Contact Lenses, Visual Display Units Application: Vision Enhancement, Mood Lighting, Sleep Aid, Therapeutic Use User Type: Consumers, Eye Care Professionals, Healthcare Providers, Retailers Technology: Bluetooth Connectivity, Augmented Reality, Wearable Tech, Energy Harvesting |
| Companies Covered | FOREO, Panasonic Corporation, Lumenis Ltd, Home Skinovations Ltd, Koninklijke Philips N.V., Iluminage Beauty Inc, Carol Cole Company, YA-MAN Ltd, TRIA Beauty Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Eye-Illuminating Gadgets Market Evolving Landscape
Active illumination hardware is fragmenting into specialized form factors optimized for discrete use cases rather than converging on universal wearable platforms. This specialization is compressing product development cycles and enabling targeted clinical validation strategies.
Micro-LED array architecture is modularizing across premium eye-illuminating devices, replacing monolithic LED packages with addressable pixel matrices. Sleep-clinic procurement teams in the United States are specifying modular platforms for programmable circadian protocols. This modularity is enabling software-defined wavelength tuning that compresses hardware refresh cycles from 36 months to 12-18 months.
The EU Medical Device Regulation's 2021 recast is forcing therapeutic claim substantiation through clinical outcome studies rather than predicate-device equivalence. Manufacturers targeting vision-enhancement indications must now compile post-market surveillance data from notified-body jurisdictions. German and French entrants are responding by segregating wellness-classification SKUs from clinical-tier product lines to preserve commercialization velocity.
Remote workers in South Korea and the United States are consolidating device purchases through employer wellness stipends rather than individual retail channels. Enterprise procurement teams are unbundling hardware from subscription-based light-therapy coaching services. This channel shift is most visible in technology sector employers with distributed workforces, where facilities budgets now cover home-office ergonomic and wellness equipment.
Eye-Illuminating Gadgets Market Segmentation
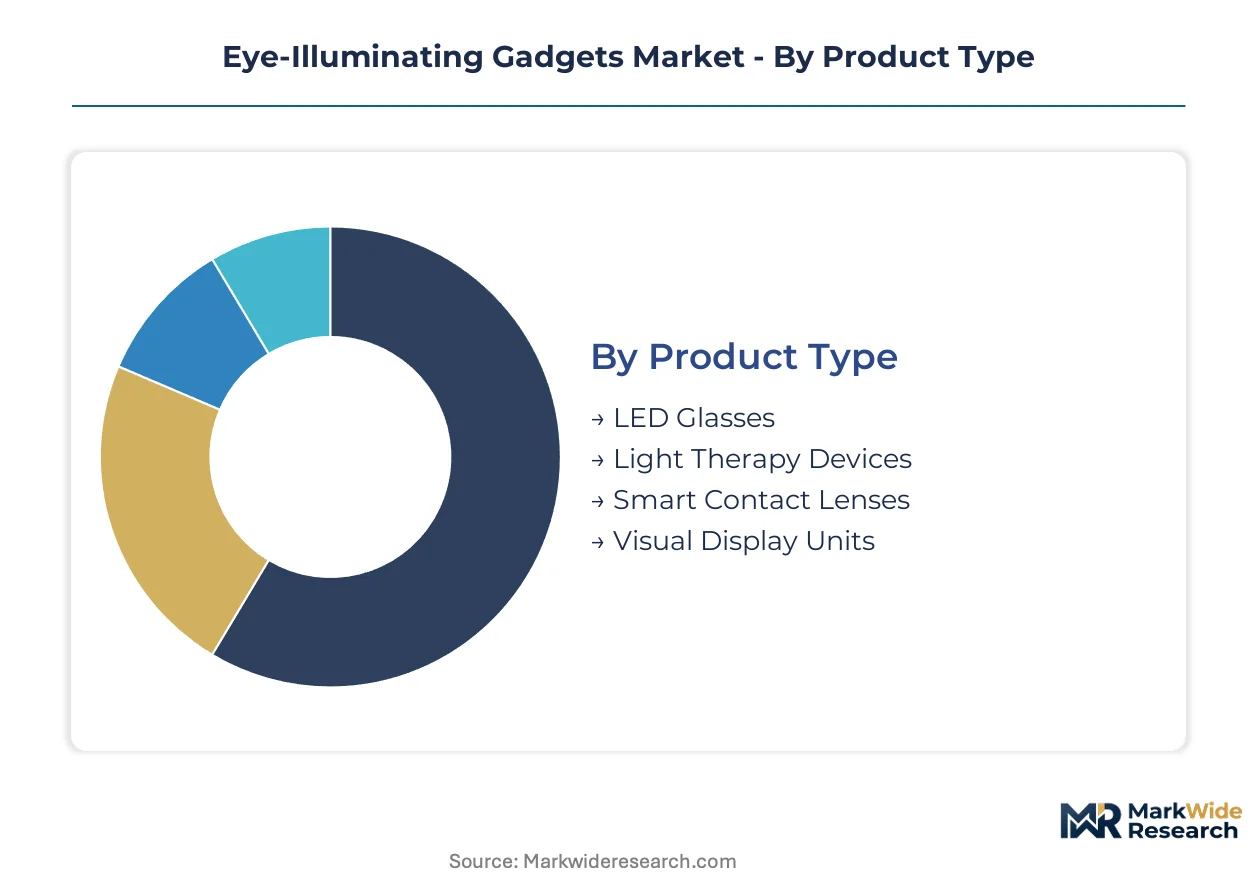
Segmentation in eye-illuminating gadgets reflects divergent buyer priorities across therapeutic claims, wellness positioning, and technical sophistication. Purchase decisions split between institutional procurement channels and direct-to-consumer retail, with regulatory classification determining accessible market segments.
Product Type:
Buyers differentiate primarily by intended use environment—clinical settings demand certified therapeutic hardware while home users prioritize portability and aesthetic integration.
- LED Glasses:Wearable frames incorporating calibrated LED arrays typically operating between 480-850 nm wavelengths. Demand concentrates among remote workers in the United States seeking circadian rhythm modulation for home office environments, driven by employer wellness stipend programs.
- Light Therapy Devices:Stationary units designed for prescribed exposure protocols with established clinical validation for seasonal affective disorder. German optometry practices anchor professional-tier procurement, with notified-body oversight under EU Medical Device Regulation creating premium positioning unavailable in wellness-classified alternatives.
- Smart Contact Lenses:Miniaturized active illumination systems with pharmaceutical-adjacent classification in Japan.
- Visual Display Units:Screen-integrated ambient lighting systems for workstation environments.
Light therapy devices lead volumes today; smart contact lenses are gaining share fastest.
Application:
Application segmentation tracks reimbursement pathways and regulatory scrutiny intensity, with therapeutic claims requiring clinical substantiation that wellness positioning avoids.
- Therapeutic Use:FDA 510(k) cleared indications for sleep-phase disorders and seasonal affective disorder with standardized dosing protocols. United States sleep clinics specify programmable circadian hardware, with procurement teams demanding modular micro-LED platforms for wavelength customization.
- Vision Enhancement:Claims for contrast sensitivity and visual acuity improvement requiring notified-body oversight under EU MDR recast. French and German manufacturers now segregate clinical-tier SKUs from wellness lines to preserve commercialization velocity amid stricter equivalence requirements.
- Sleep Aid:Melatonin suppression and circadian entrainment for consumer wellness markets.
- Mood Lighting:Ambient illumination without clinical outcome claims.
Therapeutic use commands the largest installed base; vision enhancement shows steepest expansion trajectory.
User Type:
User segmentation reflects channel structure divergence between institutional procurement with volume pricing and fragmented retail with premium positioning.
- Healthcare Providers:Hospital systems and specialty clinics purchasing through group purchasing organizations with outcome-based specification requirements. South Korean healthcare networks are consolidating procurement for illuminated contact lens trials, though PMDA dual filing requirements deter cross-border launch participation.
- Eye Care Professionals:Independent optometry and ophthalmology practices with professional-tier margin expectations. German practices command premium positioning through in-clinic fitting services unavailable through direct-to-consumer channels.
- Consumers:Individual purchasers through retail and e-commerce channels.
- Retailers:Merchandising intermediaries with private-label development capabilities.
Healthcare providers dominate current procurement volumes; eye care professionals are expanding fastest.
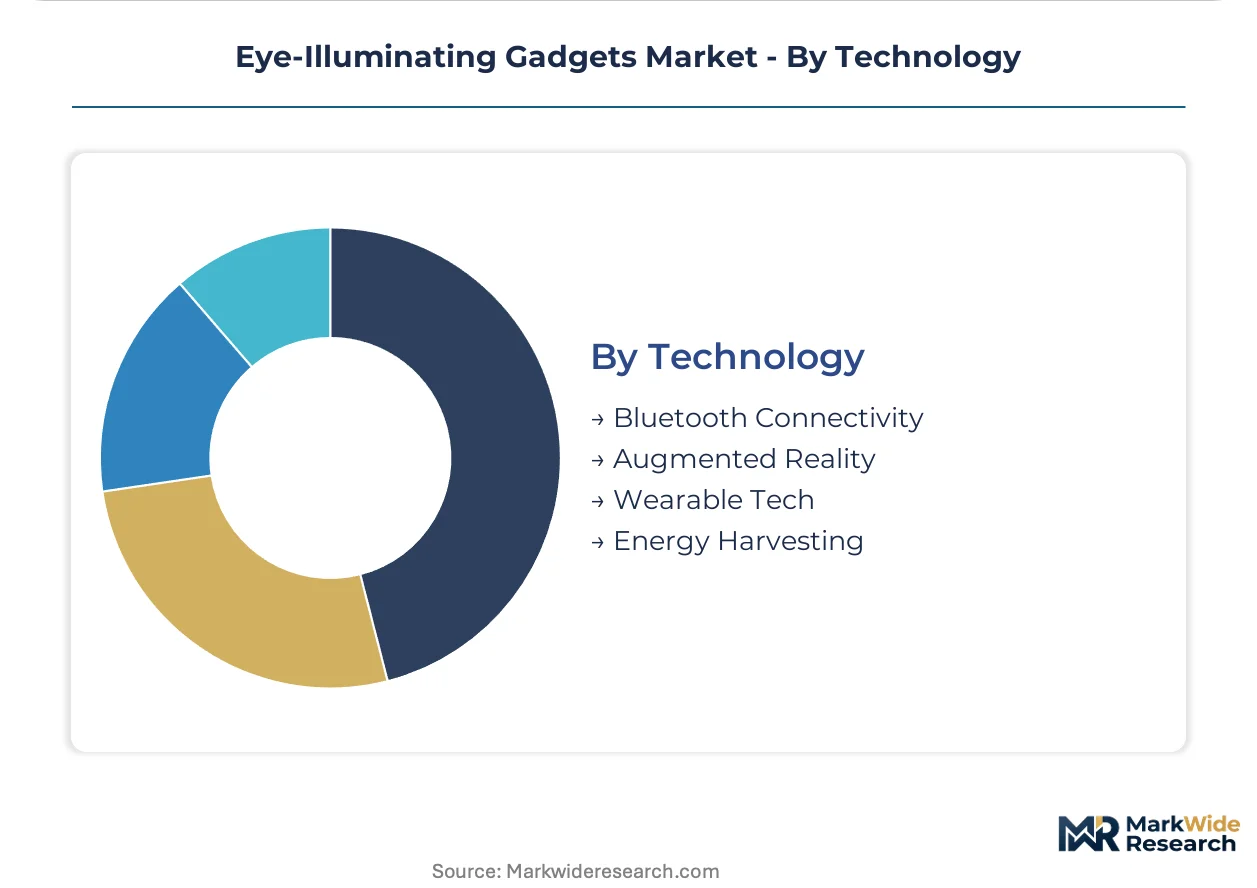
Technology:
Technology segmentation tracks integration complexity and power architecture, with connectivity and energy autonomy representing divergent R&D allocation priorities.
- Energy Harvesting:Photovoltaic and thermoelectric systems eliminating charging friction in all-day wearable formats. Japanese manufacturers leverage captive semiconductor relationships to prototype frame-integrated harvesting, though commercial scale awaits efficiency breakthroughs.
- Bluetooth Connectivity:Wireless prescription integration and protocol customization for myopia management. East Asian markets specify corrective lens compatibility with calibrated light therapy, addressing pediatric myopia prevalence through programmable dosing.
- Augmented Reality:Overlay display integration with illumination systems.
- Wearable Tech:General-purpose biometric and environmental sensing integration.
Bluetooth connectivity leads current shipments; energy harvesting is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's Seoul Capital Area anchors production capacity for LED die fabrication and micro-LED array assembly, with Samsung and LG Display subsidiaries supplying component ecosystems across wearable eye-tech categories.
United States
Employer wellness stipends from technology sector distributed workforces drive procurement of circadian rhythm devices for home office setups. FDA 510(k) clearance pathways for seasonal affective disorder claims reduce commercialization uncertainty for therapeutic hardware entrants. Boston-area sleep medicine clinics specify programmable micro-LED platforms for institutional procurement.
Germany
Independent optometry practices command premium positioning for professional-tier light therapy distribution unavailable through direct-to-consumer channels. EU Medical Device Regulation notified-body oversight extends time-to-market for vision-enhancement claims by 14-22 months. Munich and Stuttgart industrial clusters concentrate medical-grade manufacturing infrastructure for LED array housings.
Japan
PMDA pharmaceutical-adjacent classification for illuminated contact lenses imposes dual filing requirements that deter cross-border launch participation. Captive semiconductor relationships through domestic fabs create allocation advantages for component sourcing. Osaka-Kobe manufacturing corridor specializes in compact form-factor engineering for at-home consumer devices.
South Korea
Healthcare networks consolidate procurement for illuminated contact lens trials despite regulatory export friction. MFDS maintains distinct electromagnetic-exposure thresholds for high-output wearable devices. Suwon and Pangyo technology corridors host R&D facilities for energy harvesting integration into frame architectures.
Eye-Illuminating Gadgets Market Competitive Landscape
Global majors compete with regional champions across regulatory clearance capabilities and optometry channel access. The vendor base organizes into three tiers: medical-grade manufacturers with FDA 510(k) portfolios, wellness-classification specialists with rapid DTC iteration cycles, and component-integrated OEMs leveraging captive semiconductor supply. Two strategic archetypes dominate: European optometry-anchored professional-tier suppliers and East Asian compact-form-factor engineers. Competitive moves concentrate on M&A for regulatory asset accumulation and strategic partnerships for energy harvesting technology licensing.
Among diversified electronics conglomerates, Panasonic Corporation and Koninklijke Philips N.V. occupy positions spanning medical-grade manufacturing infrastructure and professional distribution channels. YA-MAN Ltd exemplifies the compact-form-factor engineering archetype targeting at-home consumers. These three companies represent contrasting geographic and strategic positioning within the competitive set, with Japanese and Dutch entities anchoring professional-tier markets and Japanese specialists driving East Asian wellness-classification segments.
| Leading Market Players |
|---|
| FOREO |
| Panasonic Corporation |
| Lumenis Ltd |
| Home Skinovations Ltd |
| Koninklijke Philips N.V. |
| Iluminage Beauty Inc |
| Carol Cole Company |
| YA-MAN Ltd |
| TRIA Beauty Inc |
| Others |
Value Network & Pricing Analysis
Silicone polymer spot prices in East Asian commodity markets cascade through LED array housing costs, compressing margin pools for mid-tier manufacturers while premium-tier suppliers with captive polymer compounding capabilities maintain pricing power through certification-grade differentiation.
Pricing Analysis
Input-cost pass-through from semiconductor die pricing runs through three distinct hardware tiers. Pricing stratifies across FDA 510(k) cleared clinical devices, notified-body certified professional units, and wellness-classified consumer SKUs. Cost compression in mid-tier LED glasses is intensifying because Japanese and South Korean fabs ration die allocation to non-captive buyers. Employer wellness stipend recipients in the United States show lowest price sensitivity; uninsured direct-to-consumer purchasers in European markets exhibit highest elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke fulfillment for finished devices. Component manufacturing concentrates in Japan, South Korea, and Taiwan for LED die fabrication and micro-LED array assembly. Finished device assembly draws from silicone polymer feedstock in Germany and China, plus precision optics from Japan. Single-source vulnerability sits with gallium nitride wafer supply from Japanese fabs. Distribution runs through optometry channel wholesalers in Europe and direct-to-consumer logistics platforms in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Medical Device Regulation compliance costs in Germany exceed wellness-classification routes in the United States by a factor that justifies segregated product lines.
For Market Incumbents: Extend regulatory asset portfolios through parallel FDA 510(k) and EU MDR filings to capture both clinical and wellness channels. Deepen captive semiconductor relationships with Japanese fabs to secure die allocation against mid-tier competitors. Channel control through German optometry practices remains the priority defensive lever against direct-to-consumer entrants. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest friction entry path. Wellness-classified sleep aid devices for remote workers in the United States represent the most penetrable white space. Bluetooth-enabled prescription integration for East Asian myopia management offers a second beachhead. Employer wellness stipend procurement teams respond to bundled hardware-plus-coaching service models. For Investors and Strategic Acquirers: Asymmetric upside sits with compact-form-factor engineering specialists holding East Asian distribution relationships. Long-term viability hinges on energy harvesting technology maturation for all-day wearable formats. Acquisition targets should demonstrate clinical validation partnerships with Boston-area sleep medicine institutions. The signal to watch is IEC 62471 testing backlog resolution at accredited laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Reduces commercialization uncertainty for seasonal affective disorder therapeutic claims in United States channels. |
| EU MDR Notified-Body Certification | Enables premium positioning through German optometry practices unavailable to wellness-classified competitors. |
| Energy Harvesting Technology Licensing | Eliminates charging friction for all-day wearable formats in Japanese and South Korean consumer markets. |
| Bluetooth Prescription Integration | Addresses pediatric myopia prevalence through programmable dosing protocols in East Asian markets. |
| Employer Wellness Channel Partnership | Captures institutional procurement budgets from technology sector distributed workforces in the United States. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and sleep clinic procurement teams informed demand-side assumptions. Secondary sources include FDA 510(k) filings, EU MDR notified-body documentation, hospital procurement databases, and customs records for LED die trade flows. Bottom-up unit economics and top-down macroeconomic triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window separates volume growth from pricing dynamics and mix shifts. Segmentation dimensions modeled include product type, application claim tier, user channel, and technology integration level. CAGRs derive from installed base turnover rates and replacement cycle compression. Forecast inputs incorporate semiconductor fab capacity expansion schedules and regulatory clearance timeline distributions.
The model assumes a particular technology adoption path; alternative pathways for energy harvesting efficiency breakthroughs would alter the outlook. Forecasts reflect documented assumptions regarding FDA review queue durations and EU MDR notified-body capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Solar Outdoor LED Lighting Market
Lighting
Global Stadium Lighting Market
Lighting
Global Headlight Control Module Market
Lighting
Photocell Market
Lighting
UAE Smart Lighting Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Directional Luminaire Market
Lighting
US Indoor LED Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Architectural Lighting Market
Lighting
Human Centric Lighting Market
Lighting
Bacteriological Light Market
Lighting
Digital Light Processing Technology Market
Lighting
Miniature Bulbs Market
Lighting
Global Machine Vision Lighting Market