
 North America Smart Lighting Market | 2026-2036
North America Smart Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Smart Lighting Market Intelligence
Buyer concentration among large commercial real estate portfolios is hardening as institutional property managers consolidate vendor relationships across multi-site footprints. Signify North America leverages its Interact platform to anchor long-term service contracts with facility management conglomerates. Acuity Brands Lighting sustains R&D intensity in tunable-white systems for healthcare and education verticals. Lutron Electronics dominates the luxury residential channel through dealer-exclusive distribution.
North America Smart Lighting comprises networked luminaire systems integrating sensors, controllers, and software protocols to enable automated dimming, daylight harvesting, and occupancy-responsive illumination. These systems typically operate on 0-10V, DALI, or wireless mesh architectures and serve primarily to reduce commercial building energy consumption while generating operational data streams. Wireless technology segments led by Zigbee and Bluetooth mesh are capturing retrofit installations where conduit replacement proves cost-prohibitive. LED product types occupy the dominant hardware share while organic LED remains confined to architectural accent applications with narrow volume scale.
The US Department of Energy's appliance standards program and California Title 24 building codes collectively mandate minimum efficacy thresholds and control requirements for new construction and major renovations. The FCC regulates radio-frequency emissions from wireless lighting control devices, while Canada's NRCan administers comparable energy performance labeling. Stakeholders must monitor evolving interoperability standards between proprietary ecosystems and Matter-protocol compatibility as procurement committees increasingly prioritize vendor-agnostic platform architecture.
Market Dynamics
Institutional procurement consolidation across multi-site commercial real estate portfolios is compressing vendor ecosystems and anchoring long-term platform contracts, reshaping competitive positioning in North America smart lighting.
Growth Catalysts
- US Inflation Reduction Act:Tax credits for energy-efficient building retrofits accelerate capital deployment into sensor-integrated luminaire upgrades across Class A office and industrial facilities.
- California Title 24 building codes:Mandatory daylight harvesting and occupancy-responsive control requirements in new construction and major renovations drive specification of networked lighting systems.
- Texas metropolitan clusters:Rapid commercial development in Dallas-Fort Worth and Houston corridors concentrates demand for wireless mesh architectures where conduit replacement costs deter wired alternatives.
Market Restraints
- Semiconductor input volatility:Zigbee and Bluetooth mesh chipsets face supply concentration risk from East Asian foundry capacity constraints, inflating controller unit costs.
- Legacy DALI infrastructure:Existing 0-10V and proprietary wired installations in aging commercial stock create technical lock-in that slows full-network retrofits.
- Interoperability friction:Proprietary ecosystem silos between major platform vendors fragment procurement committees seeking vendor-agnostic architecture.
Strategic Opportunities
- Healthcare tunable-white applications:Circadian lighting protocols for patient recovery rooms and surgical suites represent underpenetrated specification channels with premium pricing tolerance.
- Matter protocol convergence:Cross-platform standardization between Zigbee, Bluetooth mesh, and Wi-Fi control layers enables single-vendor procurement with multi-brand hardware flexibility.
- Canadian federal energy labeling:NRCan performance standards create regulatory tailwind for LED control system exports from US manufacturing bases.
Industry Challenges
- Controls integration talent scarcity:Facility engineering teams lack expertise in commissioning networked sensor arrays and software protocol configuration.
- Legacy electrical contractor capacity:Traditional trade installers face skill gaps in wireless commissioning and cloud-based platform administration.
- Multi-vendor warranty complexity:Luminaire, sensor, and software component warranties from different suppliers create service accountability fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Smart Lighting Market |
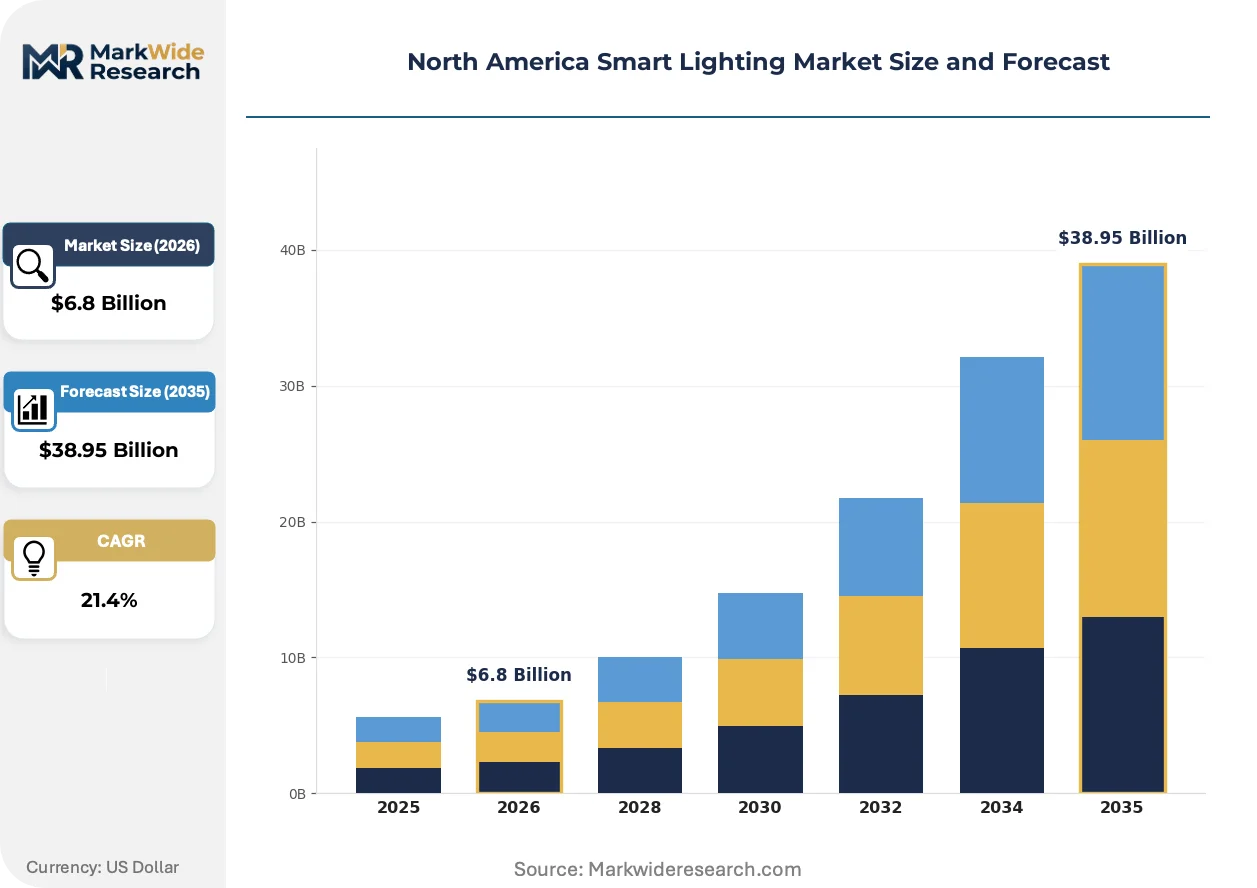
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Incandescent, Organic LED Application: Residential, Commercial, Industrial, Outdoor Technology: Wired, Wireless, Bluetooth, Zigbee End User: Households, Retailers, Offices, Factories |
| Companies Covered | Signify North America, Acuity Brands Lighting, Lutron Electronics, Philips Lighting Holding, Honeywell International, Eaton, OSRAM, Legrand, Cree, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Smart Lighting Market Strategic Shifts & Innovations
Wireless mesh control architectures are displacing wired alternatives across retrofit-heavy building stock, while regulatory mandates and procurement model evolution reshape vendor relationships and technology roadmaps.
Bluetooth mesh technology is expanding into commercial retrofit installations where conduit replacement proves cost-prohibitive. Large multi-site property managers specify Bluetooth mesh for its self-healing network topology and smartphone-based commissioning tools. This expansion is compressing deployment timelines from weeks to days and enabling phased upgrade strategies that preserve capital expenditure flexibility.
The US Department of Energy's appliance standards program tightens minimum efficacy thresholds for luminaires sold into commercial applications. Manufacturers must redesign optical systems and driver electronics to maintain compliance, raising engineering costs for mid-tier suppliers. New construction specifications in California and Washington state now preemptively exceed federal minima, forcing national product line harmonization around stricter performance tiers.
Facility management conglomerates now bundle lighting control procurement into multi-year energy service agreements rather than capital purchase cycles. This unbundling of hardware ownership from operational outcome shifts vendor relationships toward performance-guarantee contracts with penalty clauses for energy savings shortfalls. The model concentrates most visibly in Texas and Florida markets where property management outsourcing penetration exceeds national averages.
North America Smart Lighting Market Segmentation
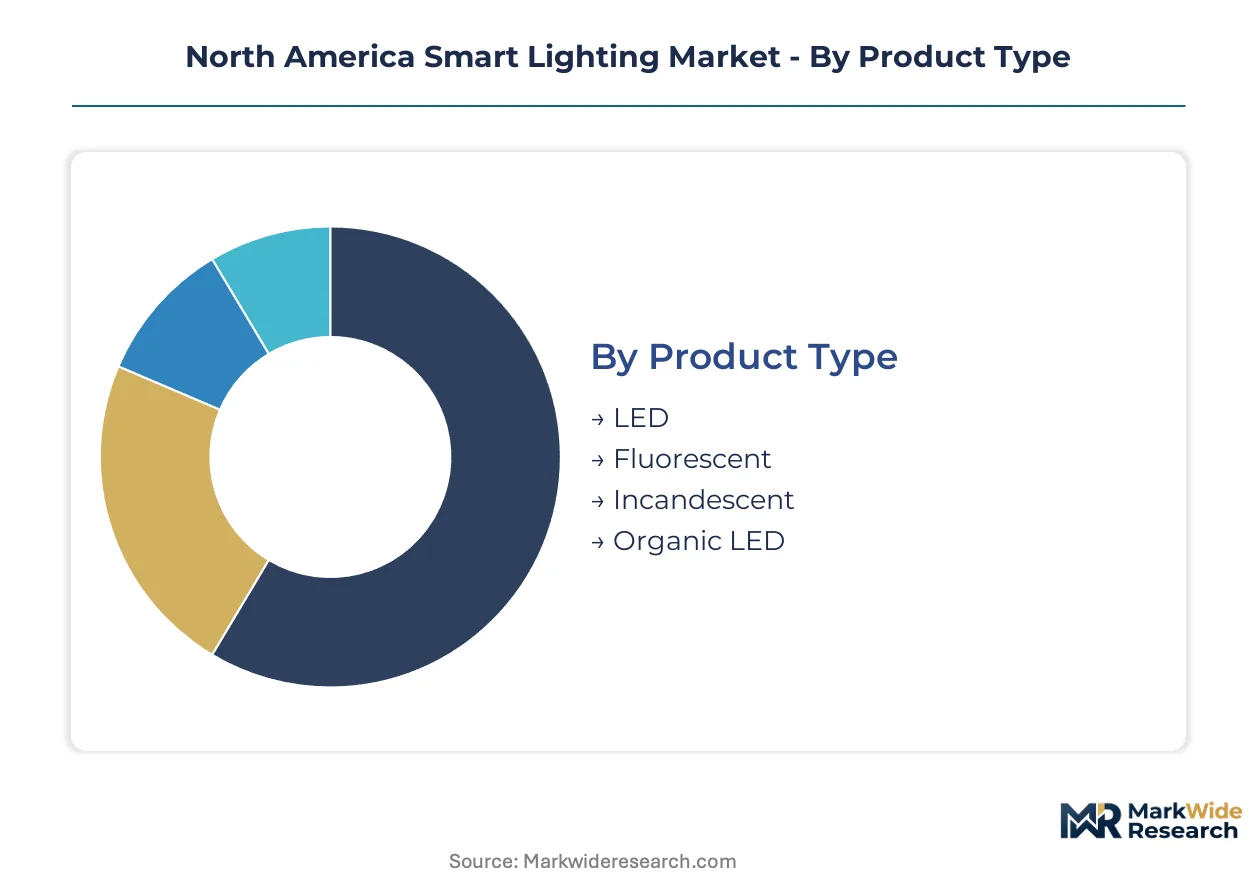
Segmentation in North America Smart Lighting reveals how procurement committees balance retrofit economics against native connectivity requirements. Hardware categories diverge sharply between embedded sensor platforms and standalone luminaire replacements.
Product Type:
Standalone luminaires dominate retrofit channels while embedded systems anchor new construction specifications.
- LED:Solid-state emitters with efficacy thresholds mandated by US DOE appliance standards and California Title 24. Demand concentrates in Texas metropolitan clusters where rapid commercial development favors wireless mesh retrofits over conduit replacement. The US Inflation Reduction Act tax credits accelerate capital deployment into LED upgrades across Class A office portfolios.
- Organic LED:Thin-film electroluminescent panels delivering architectural accent illumination with surface-mount flexibility. Specification concentrates in California's tech corridor for high-end commercial lobbies and healthcare reception areas where form factor outweighs unit economics. Narrow volume scale limits manufacturing scale effects.
- Fluorescent:Legacy tube formats with magnetic or electronic ballast dependence, now restricted by federal minimum efficacy standards.
- Incandescent:Thermal filament technology largely phased from commercial specifications by energy code mandates.
LED leads volumes today; Organic LED is gaining share fastest in premium architectural channels.
Application:
Cost tier stratification separates capital-intensive new construction from operational-budget retrofit deployments.
- Commercial:Office, hospitality, and institutional facilities requiring networked daylight harvesting and occupancy-responsive controls. Procurement concentrates among institutional property managers consolidating multi-site vendor relationships. The US Inflation Reduction Act incentivizes sensor-integrated luminaire upgrades across Class A office and industrial facilities.
- Outdoor:Streetscape, parking structure, and facade illumination with photocell and motion-sensor integration. Demand clusters in Texas metropolitan development corridors where municipal infrastructure expansion outpaces wired infrastructure capacity.
- Residential:Single-family and multi-family dwelling units with dealer-exclusive distribution channels dominating luxury segments.
- Industrial:High-bay manufacturing and warehousing facilities requiring robust fixture housing and extreme-temperature driver performance.
Commercial applications anchor revenue concentration; Outdoor segments show steepest expansion trajectory in municipal infrastructure cycles.
Technology:
Customer type divides between facility management conglomerates seeking long-term platform contracts and independent property owners prioritizing capital flexibility.
- Wireless:Mesh architectures including Zigbee and Bluetooth protocols enabling retrofit without conduit replacement. Large multi-site property managers specify wireless for self-healing network topology and smartphone-based commissioning. Bluetooth mesh compresses deployment timelines from weeks to days in Texas and Florida markets.
- Zigbee:Low-power IEEE 802.15.4 protocol with proven interoperability in commercial building automation stacks. Procurement committees prioritize Zigbee for vendor-agnostic platform architecture despite proprietary ecosystem friction.
- Wired:0-10V analog and DALI digital architectures requiring conduit infrastructure, dominant in new construction.
- Bluetooth:Native smartphone commissioning and direct device-to-device mesh formation without dedicated gateway hardware.
Wireless systems dominate retrofit volumes; Zigbee maintains strongest specification share in multi-vendor environments.
End User:
Supply concentration among semiconductor foundries shapes controller availability across end-user categories.
- Offices:Corporate and institutional workplace facilities with circadian lighting protocols and tunable-white specifications. Demand concentrates in healthcare and education verticals where Acuity Brands sustains R&D intensity. Facility management conglomerates bundle procurement into multi-year energy service agreements.
- Factories:Manufacturing operations requiring high-bay industrial fixtures with extreme ambient temperature tolerance and vibration resistance. Texas industrial development corridors concentrate demand for robust wireless mesh alternatives to wired infrastructure.
- Households:Residential consumers accessing smart lighting through dealer-exclusive luxury channels or mass-market retail.
- Retailers:Merchandise display and customer experience lighting with color-tuning for product presentation.
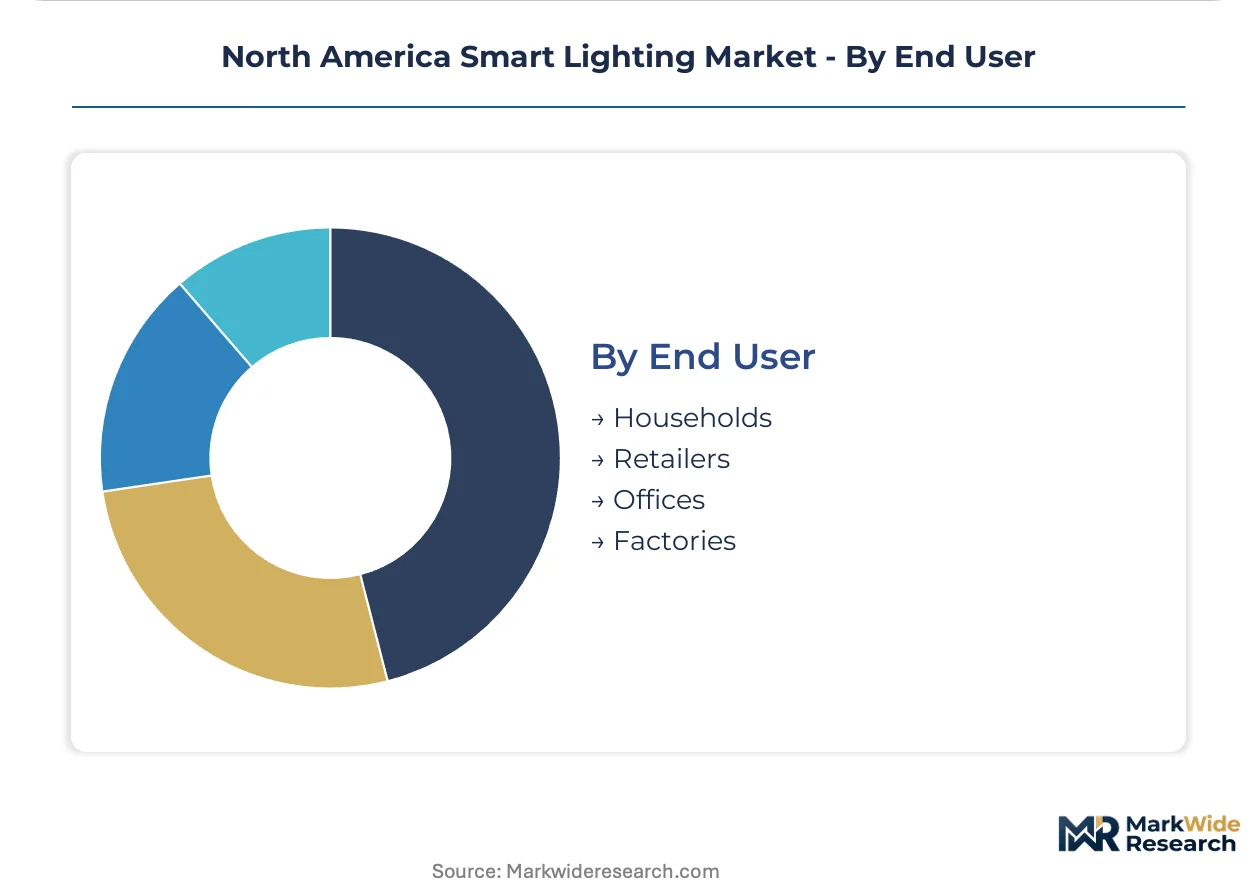
Offices generate the largest project scale; Factories show fastest adoption acceleration in industrial development zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrical engineering talent clusters in California's Bay Area and Texas's metropolitan corridors anchor smart lighting system design and commissioning expertise across the continent.
United States
Class A office portfolios in Dallas-Fort Worth and Houston drive wireless mesh retrofits where conduit replacement costs deter wired alternatives. The US Inflation Reduction Act channels tax credits into sensor-integrated luminaire upgrades across commercial and industrial facilities. California's Title 24 building codes mandate daylight harvesting controls in new construction throughout the tech corridor from San Francisco to San Jose.
Canada
Energy service companies in Toronto and Vancouver bundle lighting control procurement into multi-year performance contracts with penalty clauses for savings shortfalls. Natural Resources Canada administers energy performance labeling standards that create regulatory tailwind for LED control system imports. Montreal's commercial development pipeline concentrates demand for tunable-white specifications in healthcare and education verticals.
Mexico
Manufacturing facilities in Nuevo León and Baja California require high-bay industrial fixtures with extreme temperature tolerance for automotive and electronics assembly operations. The country's federal energy efficiency standards for commercial buildings remain less stringent than US Title 24 equivalents. Mexico City metropolitan area development concentrates specification activity for networked lighting in hospitality and retail channels.
North America Smart Lighting Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered vendor ecosystems, with procurement consolidation among institutional property managers compressing relationship structures. The market exhibits moderate concentration at the platform level while fragmenting across hardware component suppliers. Three archetypes dominate: integrated platform vendors anchoring long-term service contracts, luminaire specialists with embedded sensor capabilities, and controls-software pure-plays. Competitive moves center on strategic partnerships for interoperability certification and backward integration into semiconductor sourcing.
Among North American platform vendors, Signify North America and Acuity Brands Lighting exemplify the integrated archetype, while Lutron Electronics occupies a position within premium residential and commercial controls specialization. These three entities represent contrasting approaches to channel structure—direct facility management relationships versus dealer-exclusive distribution versus specification-driven project engineering.
| Leading Market Players |
|---|
| Signify North America |
| Acuity Brands Lighting |
| Lutron Electronics |
| Philips Lighting Holding |
| Honeywell International |
| Eaton |
| OSRAM |
| Legrand |
| Cree |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up facility management conglomerates now dominate procurement volume, compressing vendor ecosystems into multi-year platform contracts that reshape both supply allocation discipline and pricing leverage across the North American smart lighting value chain.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across the market. Hardware ownership unbundled from operational outcome concentrates in Texas and Florida energy service agreements with penalty clauses for savings shortfalls. Price differentiation hinges on certification tier—UL-listed versus Title 24 pre-certified systems—and after-sales commissioning support. Cost compression in mid-tier LED driver electronics intensifies as East Asian foundry capacity constraints inflate Zigbee chipset costs. Institutional property managers show lowest price sensitivity, while independent commercial owners prioritize capital flexibility.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act reshape sourcing toward North American LED driver assembly and final luminaire integration. Semiconductor inputs draw from Taiwan, South Korea, and China, with Zigbee and Bluetooth mesh chipsets facing single-source vulnerability from concentrated East Asian foundry capacity. Optical components and aluminum heat sinks feed from Mexico and domestic US extrusion facilities. Distribution runs through electrical contractor channels and direct facility management procurement desks, with wireless retrofit SKUs bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with California Title 24 and US Inflation Reduction Act mandates structurally expanding specification volume beyond organic construction cycles.
For Market Incumbents: Anchor long-term service contracts through Interact-style platform ecosystems that lock in facility management conglomerates across multi-site footprints. Defend against Bluetooth mesh pure-plays by deepening backward integration into semiconductor sourcing and commissioning talent pools. Prioritize Matter protocol certification investment to neutralize proprietary ecosystem fragmentation. For New Entrants and Emerging Players: Begin with healthcare tunable-white specifications in Montreal and Vancouver corridors where circadian lighting protocols command premium pricing tolerance and incumbent R&D intensity has not fully penetrated. Target municipal outdoor infrastructure in Texas metropolitan clusters where wireless mesh retrofits outpace wired alternatives. Pursue dealer-exclusive distribution in luxury residential channels as the fastest path to margin protection. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier luminaire specialists lacking embedded sensor capabilities and cloud platform integration. Five-to-ten-year viability favors vendors with captive commissioning expertise and multi-year energy service agreement books. Watch for Matter protocol adoption velocity as the inflection signal separating platform winners from hardware commoditization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Matter protocol certification enables single-vendor procurement with multi-brand hardware flexibility across Zigbee and Bluetooth mesh ecosystems. |
| Backward Integration | Captive sourcing of Zigbee chipsets insulates controller unit costs from Taiwan foundry capacity constraints and supply volatility. |
| Healthcare Vertical Expansion | Tunable-white specifications for patient recovery rooms unlock premium pricing channels with underpenetrated specification penetration. |
| Energy Service Agreement Structuring | Multi-year performance contracts with penalty clauses shift revenue from capital cycles to recurring operational outcomes in Texas and Florida. |
| Commissioning Talent Acquisition | Controls integration expertise scarcity creates competitive moat through captive facility engineering capabilities and faster deployment timelines. |
Research Approach
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining structured interviews with facility management procurement directors, electrical contractor operations heads, lighting controls integration specialists, and commercial real estate portfolio managers. Secondary validation draws from US Department of Energy appliance standard filings, California Energy Commission Title 24 documentation, Natural Resources Canada performance labeling databases, and FCC equipment authorization records. Bottom-up project pipeline tracking triangulates against top-down construction spending forecasts.
Granularity-level modeling disaggregates volume and value across product type, application, technology protocol, and end-user vertical throughout the projection horizon. Wireless versus wired architecture splits, retrofit versus new construction deployment patterns, and bundled service contract penetration inform segment-level CAGRs. Regulatory mandate implementation timelines and semiconductor supply availability function as key forecast sensitivity inputs.
Several conditions sit outside the modeled scope, including potential repeal or modification of US Inflation Reduction Act provisions, trade policy shifts affecting Mexico-US component flows, and breakthrough organic LED manufacturing cost reductions. Forecasts reflect documented assumptions around continued Title 24 stringency and Matter protocol adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Smart Street Lighting Systems Market
Lighting
Global Commercial Lighting Market
Lighting
Solar Lights Market
Lighting
Lighting Product Market
Lighting
Circadian Lighting Market
Lighting
North America Street Lighting Market
Lighting
Intelligent Lighting Market
Lighting
Malaysia LED Lighting Controllers Market
Lighting
Solar Spotlights Market
Lighting
Smart Lamp Market
Lighting
Global Work Lights Market
Lighting
Directional Luminaire Market
Lighting
Solid-State Lighting Source Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Explosion Proof Lighting Market
Lighting
Ambient Lighting Market