
 Intelligent Lighting Controls Market | 2026-2036
Intelligent Lighting Controls Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Lighting Controls Market Intelligence
China is tilting toward domestic production of intelligent lighting modules, with Shenzhen and Dongguan clusters expanding LED driver and sensor assembly capacity. Signify Holding leverages its vertical integration in LED sourcing and control software to sustain margin advantages across European commercial projects. Acuity Brands anchors its position through deep specification relationships with North American electrical contractors and architects. Lutron Electronics differentiates via proprietary wireless protocols that reduce commissioning complexity in high-end residential and hospitality deployments.
Intelligent lighting controls encompass networked hardware and software systems that modulate artificial illumination based on occupancy detection, daylight availability, time schedules, or user commands, typically operating through 0-10V, DALI, or wireless protocols at 2.4 GHz frequency bands. These systems reduce commercial building energy consumption by 30-50% compared to conventional switching while enabling circadian lighting programs that align artificial spectra with human photobiological needs. Lighting control systems command the largest value pool due to integration complexity and recurring software licensing revenue, while motion sensors represent the fastest-expanding product category as code mandates spread beyond commercial into residential and outdoor applications. KNX technology dominates European specification channels where interoperability certification creates switching costs, whereas Wi-Fi and Zigbee compete aggressively in consumer-facing smart home segments where installation simplicity overrides protocol sophistication.
The EU Green Deal and F-Gas Regulation shape product design requirements across European markets, while the US Department of Energy enforces efficacy standards through EPA and state-level stretch codes that effectively mandate sensor-based controls in new construction. China's GB standards and MIIT guidelines establish domestic interoperability requirements that favor locally certified control platforms. India's BIS and CEA building codes are beginning to incorporate mandatory daylight harvesting provisions in commercial structures above specified floor areas. Stakeholders must monitor regulatory divergence between wireless certification regimes and emerging cybersecurity mandates for connected building infrastructure, as compliance fragmentation threatens to partition what hardware platforms can deploy across jurisdictions without redesign.
Market Dynamics
Networked lighting infrastructure is consolidating around software-defined control platforms that compress commissioning timelines and displace standalone hardware controllers. The shift from proprietary protocols toward open API architectures is redrawing competitive boundaries between fixture manufacturers, sensor suppliers, and building automation integrators.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany, France, and Italy now require sensor-based controls in commercial renovations above specified energy thresholds, pulling daylight harvesting systems into existing building stock.
- Occupancy analytics convergence:Workplace experience platforms are integrating lighting control data with space utilization metrics, creating bundled procurement decisions that favor networked over standalone systems.
- Shenzhen-Dongguan manufacturing clusters:China's concentrated LED driver and wireless module production is compressing hardware costs and accelerating product refresh cycles for export markets.
Market Restraints
- Semiconductor input volatility:MCU and RF chip supply concentration in Taiwan creates inventory risk for control module assemblers during foundry allocation cycles.
- KNX certification friction:European interoperability requirements impose 12-18 month approval timelines that disadvantage new entrants against established specification holders.
- Wi-Fi/Zigbee substitution pressure:Consumer-grade mesh protocols are capturing residential and light commercial segments where installation simplicity overrides DALI sophistication.
Strategic Opportunities
- India daylight harvesting mandates:BIS and CEA codes are beginning to incorporate automatic dimming provisions in commercial structures above 2,000 square meters.
- Circadian lighting programs:Healthcare and education verticals are specifying tunable white systems that align artificial spectra with human photobiological needs.
- Utility demand response integration:Grid-edge programs in California and Texas are creating revenue streams for networked lighting as dispatchable load assets.
Industry Challenges
- Commissioning labor scarcity:Qualified lighting control programmers command premium wages that inflate total installed costs for complex DALI-2 networks.
- Cybersecurity certification fragmentation:Diverging wireless security mandates across FCC, ETSI, and MIIT regimes force hardware redesigns for multi-jurisdiction deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Lighting Controls Market |
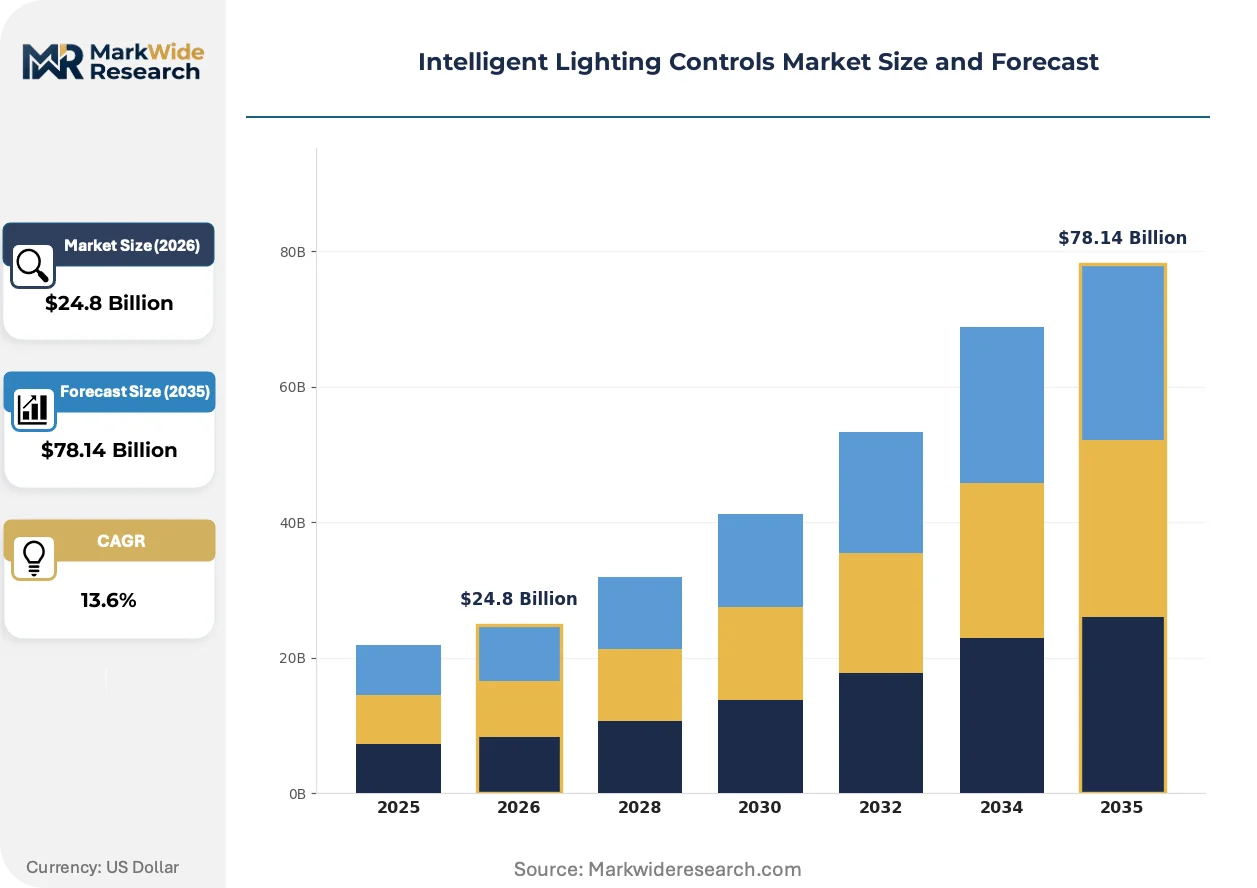
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $78.14 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Bulbs, Dimming Switches, Motion Sensors, Lighting Control Systems Application: Residential, Commercial, Industrial, Outdoor Technology: Wi-Fi, Zigbee, Bluetooth, KNX End User: Homeowners, Office Buildings, Warehouses, Hotels |
| Companies Covered | Signify Holding, Acuity Brands, Lutron Electronics, Schneider Electric, Legrand, Eaton Corporation, Honeywell International, ams-OSRAM, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Lighting Controls Market Strategic Shifts & Innovations
Digital twin architectures are collapsing the boundary between physical lighting infrastructure and software-based control logic. This convergence is compressing specification cycles and enabling predictive maintenance models that shift vendor value toward recurring service relationships.
LiFi (light fidelity) modulation technology is virtualizing the data transmission layer within luminaire networks. Corporate campuses in Singapore and Dubai are piloting systems that embed high-bandwidth communication within existing lighting infrastructure. The technology is virtualizing the separate cabling runs for Wi-Fi access points, reducing both capital expenditure and electromagnetic interference in dense building environments.
The US Department of Energy's efficacy standards enforcement through EPA and state-level stretch codes is mandating sensor-based controls in new commercial construction. California Title 24 and ASHRAE 90.1 updates are effectively prohibiting manual switching in buildings above specified floor areas. Large-format retail and warehouse developers are responding by specifying networked dimming systems during pre-construction to avoid post-occupancy retrofit penalties.
Building owners are unbundling lighting control procurement from general electrical contracts and awarding directly to specialized integrators. This disintermediation is concentrating specification authority with facility managers and energy procurement teams rather than traditional construction channels. The pattern is most visible in US and German commercial office markets where long-term operating cost accountability sits with owner-occupiers rather than developers.
Intelligent Lighting Controls Market Segmentation
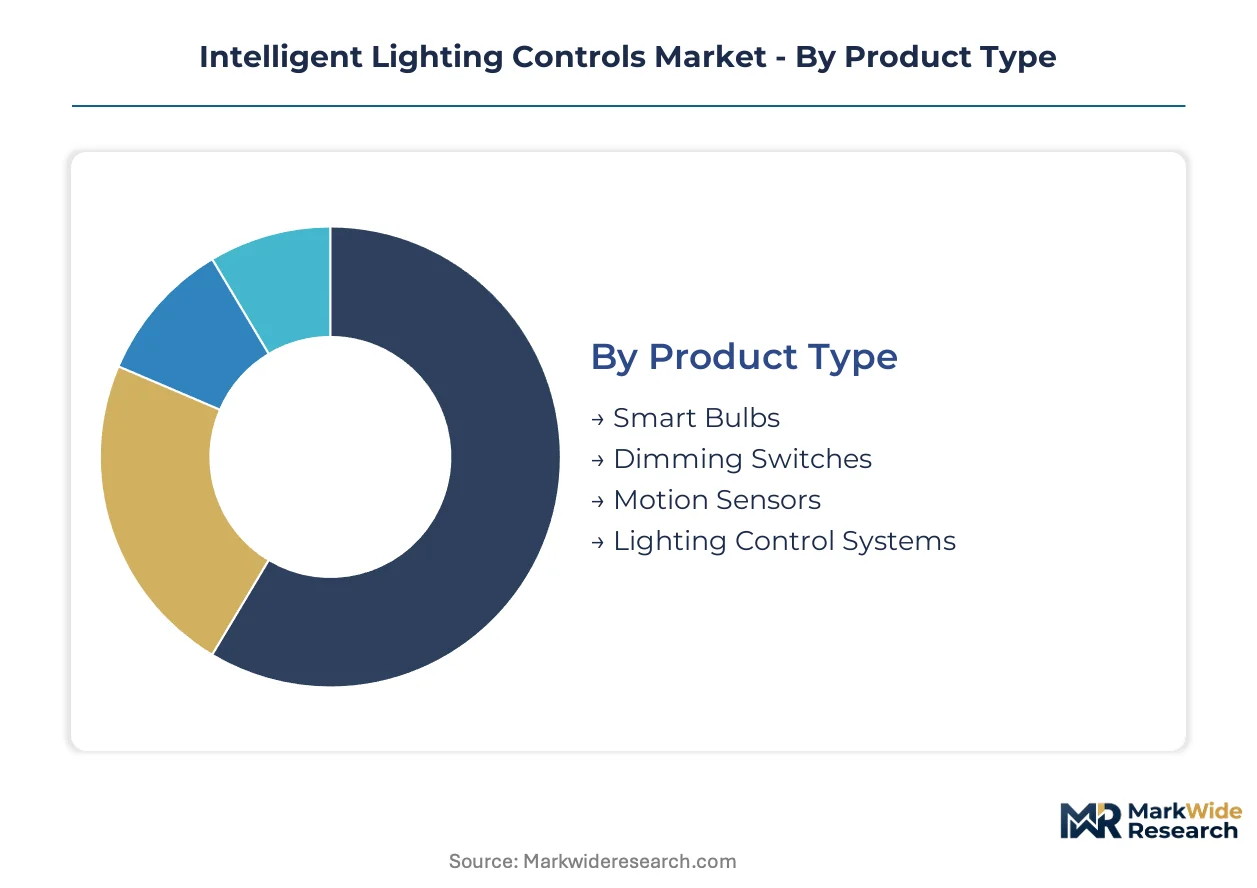
Product architecture in intelligent lighting controls fragments across hardware form factors, communication protocols, and installation contexts. Each segmentation dimension carries distinct margin profiles and specification authority, reshaping how vendors allocate R&D and channel investment.
Product Type:
Cost tier determines integration complexity and recurring revenue potential across hardware categories.
- Lighting Control Systems:Networked hardware and software platforms orchestrating multiple luminaire zones through centralized or distributed architectures. Demand concentrates in German and US commercial office retrofits where EU Green Deal mandates and ASHRAE 90.1 updates require sensor-based automation. These systems command premium specification through recurring software licensing and commissioning services.
- Motion Sensors:Passive infrared and microwave detection modules triggering illumination based on occupancy states. Code mandates in France, Italy, and California are accelerating deployment beyond commercial into residential and outdoor applications. This segment is climbing the fastest as regulatory thresholds expand across building typologies.
- Smart Bulbs:LED sources with embedded wireless connectivity enabling individual addressability and color tuning. Consumer-facing channels in Shenzhen-Dongguan manufacturing clusters dominate volume production.
- Dimming Switches:Wall-mounted controllers modulating light output via 0-10V, DALI, or phase-cut protocols. Hospitality and high-end residential specifications in Dubai and Singapore favor proprietary wireless implementations.
Lighting Control Systems holds installed capacity. Motion Sensors is rotating up the share rankings.
Application:
Building typology dictates protocol sophistication and procurement channel structure.
- Commercial:Office, retail, and institutional buildings requiring networked dimming, daylight harvesting, and occupancy-responsive automation. Germany's retrofit mandates and California Title 24 enforcement are pulling advanced control platforms into existing stock. Procurement is shifting toward specialized integrators disintermediated from general electrical contracts.
- Residential:Single-family and multi-family dwellings where installation simplicity overrides DALI sophistication. Wi-Fi and Zigbee mesh protocols from Shenzhen-Dongguan clusters dominate this price-sensitive volume tier.
- Industrial:Manufacturing facilities and warehouses specifying high-bay luminaires with motion-activated controls. Texas and California utility demand response programs are creating revenue streams for networked lighting as dispatchable load assets.
- Outdoor:Street lighting, parking structures, and facade illumination requiring weather-hardened sensors and long-range wireless backhaul. Smart city investments in Singapore and Dubai are piloting LiFi-embedded infrastructure.
Commercial anchors specification value. Residential is expanding most quickly through consumer channel penetration.
Technology:
Protocol selection locks in ecosystem compatibility and certification burden.
- KNX:Twisted-pair and IP-based building automation standard with mandatory interoperability certification across European specification channels. ETSI compliance and 12-18 month approval timelines create switching costs favoring established vendors in German and French commercial projects.
- Wi-Fi:IP-native connectivity leveraging existing infrastructure for consumer and light commercial deployments. Installation simplicity drives adoption in residential segments where smartphone-based commissioning overrides protocol sophistication.
- Zigbee:Mesh networking protocol optimized for low-power sensor networks and battery-operated endpoints. Competes aggressively with Wi-Fi in smart home ecosystems.
- Bluetooth:Point-to-point and mesh implementations enabling direct smartphone control without hub infrastructure. Emerging in hospitality and small-format retail where guest-facing interfaces matter.
KNX holds specification authority in European commercial channels. Wi-Fi is gaining share fastest through residential volume expansion.
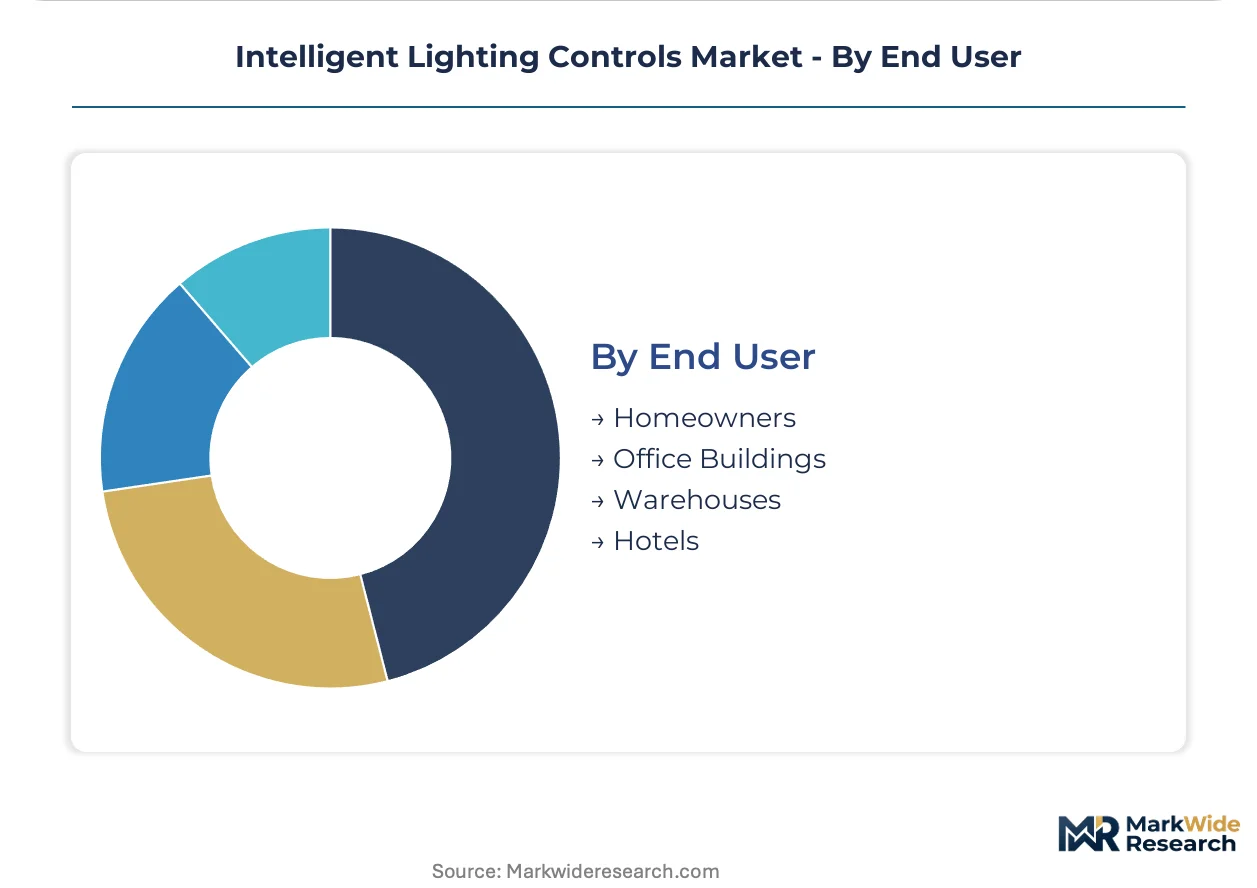
End User:
Customer type determines procurement sophistication and total cost of ownership horizon.
- Office Buildings:Owner-occupiers and institutional landlords prioritizing operating cost reduction and workplace experience platforms. Germany and US markets are unbundling lighting control procurement from general electrical contracts, concentrating authority with facility managers and energy procurement teams.
- Hotels:Hospitality operators specifying tunable white and circadian lighting programs to align artificial spectra with guest photobiological needs. High-end properties in Dubai and Singapore favor proprietary wireless protocols that reduce commissioning complexity.
- Homeowners:Individual consumers purchasing through retail and e-commerce channels, prioritizing smartphone integration and voice assistant compatibility. Shenzhen-Dongguan manufacturing clusters supply this price-sensitive segment.
- Warehouses:Logistics operators and third-party fulfillment providers responding to ASHRAE 90.1 and state-level stretch codes mandating sensor-based controls in large-format facilities above specified floor areas.
Office Buildings holds contract value concentration. Warehouses is rotating up the share rankings through code mandate expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European regulatory momentum for intelligent lighting controls, while manufacturing gravity concentrates in Chinese coastal clusters and specification authority remains concentrated in German and US commercial channels.
Germany
Retrofit mandates and smart city investments pull advanced dimming and daylight harvesting systems into both new construction and existing building upgrades. The EU Green Deal and tightening building energy codes mandate sensor-based controls across member states. Bavaria and North Rhine-Westphalia host specification-intensive commercial office projects where networked lighting systems dominate procurement decisions.
United States
California Title 24 and ASHRAE 90.1 updates effectively prohibit manual switching in buildings above specified floor areas. The EPA enforces efficacy standards through state-level stretch codes that mandate sensor-based controls in new commercial construction. Texas and California utility demand response programs create revenue streams for networked lighting as dispatchable load assets in large-format retail and warehouse developments.
China
Domestic production tilts toward intelligent lighting modules with expanding LED driver and sensor assembly capacity. MIIT guidelines and GB standards establish domestic interoperability requirements that favor locally certified control platforms. Shenzhen and Dongguan manufacturing clusters compress hardware costs and accelerate product refresh cycles for export markets.
India
BIS and CEA building codes incorporate mandatory daylight harvesting provisions in commercial structures above specified floor areas. The central electricity regulator mandates automatic dimming systems in new construction above 2,000 square meters. Maharashtra and Karnataka concentrate early adoption as commercial real estate developers respond to code compliance deadlines.
Singapore
Smart city investments pilot LiFi-embedded infrastructure that embeds high-bandwidth communication within existing lighting networks. Corporate campuses deploy systems that virtualize separate cabling runs for Wi-Fi access points. The city-state's dense building environment favors electromagnetic interference reduction through light-based data transmission.
Intelligent Lighting Controls Market Key Industry Players
Capability concentration sits with specification-anchored integrators; scale advantage sits with vertically integrated hardware manufacturers. The vendor base stratifies across three tiers: premium-tier specialists commanding proprietary protocol ecosystems, mid-tier fixture manufacturers bundling controls with luminaire sales, and volume-driven module suppliers serving consumer channels. Dominant competitive moves include backward integration into LED driver production and strategic partnerships with building automation platforms.
Within the premium-tier specification channel, Signify Holding, Acuity Brands, and Lutron Electronics exemplify divergent competitive positions. Signify leverages European commercial project penetration through captive LED sourcing and control software integration. Acuity Brands anchors North American market presence through specification relationships with electrical contractors and architects. Lutron Electronics occupies a distinct position in high-end residential and hospitality deployments through proprietary wireless protocol differentiation that reduces commissioning complexity.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Lutron Electronics |
| Schneider Electric |
| Legrand |
| Eaton Corporation |
| Honeywell International |
| ams-OSRAM |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
Semiconductor input volatility from Taiwan foundry concentration compresses margin spreads between premium KNX-certified systems and consumer-grade Wi-Fi alternatives while forcing control module assemblers into dual-sourcing strategies that reshape tiered pricing structures across German commercial and Shenzhen export markets.
Pricing Analysis
German commercial office projects command three to five times the unit pricing of comparable residential deployments in Shenzhen-Dongguan export channels. Three-tier pricing structure across premium, standard, and economy levels separates KNX-certified European specification holders from mid-tier fixture bundlers and volume-driven module suppliers. Cost compression in the residential tier is intensifying because Wi-Fi and Zigbee mesh protocols displace DALI sophistication in price-sensitive consumer segments. Facility managers and energy procurement teams in owner-occupied US and German office buildings demonstrate the lowest price sensitivity, prioritizing operating cost reduction and workplace experience integration over upfront hardware expenditure.
Supply Chain Analysis
Extended payment terms from European specification integrators now stretch to ninety days, forcing LED driver and wireless module assemblers in Shenzhen and Dongguan to rely on supply-chain finance facilities anchored in Hong Kong banking channels. Manufacturing gravity draws from China, Taiwan, and Germany, with MCU and RF chip fabrication concentrated in Taiwanese foundries while final assembly clusters populate Guangdong province. Raw material dependencies rest on silicon wafers, rare-earth phosphors for LED tuning, and copper for twisted-pair KNX cabling. Single-source vulnerability in Taiwan semiconductor fabrication creates inventory risk during foundry allocation cycles. Distribution runs through specialized lighting integrators disintermediated from general electrical contractors in US and German commercial markets, alongside direct OEM relationships for consumer-grade smart bulb volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating with facility managers and energy procurement teams unbundling lighting control procurement from general electrical contracts, fragmenting traditional construction channel authority across US and German commercial office markets.
For Market Incumbents: Pre-empt Wi-Fi and Zigbee substitution pressure in residential and light commercial segments by accelerating proprietary wireless protocol roadmaps that preserve commissioning complexity advantages. Defend specification authority in German commercial channels through deeper KNX certification investments that extend 12-18 month approval timelines against emerging entrants. Prioritize backward integration into LED driver production to sustain margin compression resistance against Shenzhen-Dongguan manufacturing clusters. For New Entrants and Emerging Players: Pursue daylight harvesting mandate compliance in Indian commercial construction above 2,000 square meters as the most penetrable regulatory-driven entry point. Target warehouse and logistics operator segments in Texas and California where utility demand response programs create dispatchable load revenue streams that offset upfront system costs. Lead with smartphone-based commissioning interfaces that override DALI sophistication barriers in price-sensitive residential deployments. For Investors and Strategic Acquirers: EU Green Deal retrofit mandates reshaping the acquisition landscape toward specification-anchored integrators with recurring software licensing revenue models rather than hardware-only module suppliers. Long-term viability over the next decade hinges on digital twin and predictive maintenance service relationships that shift vendor value beyond transactional equipment sales. Target acquisition archetypes include mid-tier fixture manufacturers with dormant control software capabilities requiring platform integration. Monitor cybersecurity certification fragmentation across FCC, ETSI, and MIIT regimes as the critical inflection signal forcing hardware redesigns and consolidation pressure on multi-jurisdiction deployment capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| KNX Certification Investment | ETSI compliance timelines create 12-18 month switching costs favoring established European specification holders. |
| Proprietary Wireless Protocol Development | Lutron Electronics demonstrates how reduced commissioning complexity captures high-end residential and hospitality procurement decisions. |
| Backward Integration into LED Drivers | Signify Holding leverages captive sourcing to sustain margin advantages across EU Green Deal-mandated commercial retrofits. |
| Utility Demand Response Partnership | Texas and California grid-edge programs create recurring revenue streams for networked lighting as dispatchable load assets. |
| Digital Twin Platform Integration | Predictive maintenance models compress specification cycles and shift vendor value toward service relationships in German office markets. |
Research Approach
Initial hypotheses were tested against primary input from lighting control system integrators, facility managers at owner-occupied commercial offices, electrical contractors in German and North American specification channels, and procurement leads at hospitality operators, then refined through secondary validation against EU Green Deal implementation timelines, EPA efficacy standard enforcement patterns, MIIT guideline updates, and ASHRAE 90.1 code adoption databases. Bottom-up segment sizing across product types, applications, technologies, and end users was triangulated with top-down macroeconomic and regulatory scenario analysis.
Demand-supply balance modeling across the projection horizon incorporated segmentation dimensions including protocol certification tier, building typology, procurement channel structure, and regional regulatory framework clusters. CAGRs were derived from installed base growth trajectories, replacement cycle compression, and code mandate expansion patterns. Industry-specific forecast inputs encompassed KNX interoperability certification timelines, Shenzhen-Dongguan manufacturing capacity utilization, and utility demand response program enrollment curves in California and Texas.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese LED driver manufacturers or accelerated proprietary protocol development by residential-focused entrants would shift outcomes. Macroeconomic deviation in semiconductor foundry allocation, regulatory acceleration of cybersecurity mandates across jurisdictions, or technological breakthrough in LiFi commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
UV Lamps Market
Lighting
US Indoor LED Lighting Market
Lighting
Plasma Lighting Market
Lighting
Lighting Product Market
Lighting
Europe Lighting Control Systems Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Xenon Headlights Market
Lighting
Digital Light Processing Technology Market
Lighting
Cleanroom Lighting Market
Lighting
Architectural Lighting Market
Lighting
Illuminating Signs Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Photography Light Box Market
Lighting
LED Eye Protection Lamp Market
Lighting
Explosion Proof Lighting Market