
 Human Centric Lighting Market | 2026-2036
Human Centric Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Human Centric Lighting Market Analysis
The capital-intensity divergence between integrated semiconductor-lighting manufacturers and assembly-focused fixture producers is redrawing competitive boundaries in human centric lighting. Signify Holding leverages captive LED chip production to control spectral tuning architectures across healthcare and education verticals. ams-OSRAM AG anchors its position through deep vertical integration into sensor-driven circadian modulation systems. Zumtobel Group competes via specialized architectural channel relationships in European commercial fit-outs.
Human centric lighting denotes illumination systems engineered to synchronize artificial light spectra and intensity with human circadian rhythms, typically employing tunable white LED engines with correlated color temperature ranges from 2700K to 6500K and melanopic lux calibration. The technology serves primarily to enhance occupant alertness, sleep quality, and cognitive performance in built environments. LED product types dominate installed value due to spectral programmability and energy efficiency, while fluorescent segments retreat in share as retrofit cycles accelerate. Smart lighting technology captures expanding margin pools through software-enabled circadian scheduling and occupancy-responsive dimming protocols.
EU Green Deal efficiency directives and F-Gas Regulation phaseouts shape product specifications across European installations, while FDA guidelines on healthcare environmental design influence spectral requirements in US hospital construction. China's GB standards and MIIT smart city frameworks mandate interoperable lighting controls in public building retrofits. Stakeholders must monitor convergence between building automation certification and circadian health claims as regulatory bodies develop formal efficacy testing protocols.
Market Dynamics
The convergence of tunable white LED engines with building automation systems is restructuring competitive boundaries, as spectral programmability becomes a mandatory specification rather than a premium feature in healthcare and education procurement.
Growth Catalysts
- EU Green Deal efficiency mandates:Healthcare facilities across Germany and France must retrofit lighting systems to meet carbon reduction targets, accelerating replacement cycles for fluorescent installations.
- Melanopic lux calibration standards:Emerging WELL Building certification requirements in commercial office construction specify circadian-effective illumination, pulling tunable white systems into mainstream specification.
- China MIIT smart city frameworks:Public building retrofits in tier-one cities mandate interoperable lighting controls, creating standardized demand for sensor-integrated human centric systems.
Market Restraints
- Phosphor and rare earth input volatility:Tunable white LED engines depend on cerium-doped yttrium aluminum garnet phosphors concentrated in Chinese processing facilities, exposing manufacturers to supply disruption.
- Qualified circadian lighting designers:The specialized knowledge required for melanopic-effective system specification creates a bottleneck in project execution, particularly in secondary metropolitan markets.
- Fluorescent legacy infrastructure:Existing ballast-compatible wiring in aging commercial buildings imposes retrofit friction that slows LED conversion despite operational cost advantages.
Strategic Opportunities
- Residential wellness integration:Smart home platforms in North American and European markets are adding circadian scheduling modules, opening consumer channels previously dominated by commercial contractors.
- GB standards convergence:China's evolving national standards for healthy building design are incorporating spectral requirements that favor domestic tunable white manufacturers with local certification relationships.
- Aging care facility specialization:Dementia care and assisted living operators in Japan and Western Europe are specifying dawn-dusk simulation systems to address sleep disruption in elderly populations.
Industry Challenges
- Circadian efficacy validation:Absence of standardized testing protocols for melanopic lux claims forces manufacturers to fund proprietary clinical studies, raising R&D overhead and creating liability exposure.
- Building management system integration:Proprietary control protocols from established automation vendors fragment the specification landscape, requiring lighting suppliers to maintain multiple software certification tracks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Centric Lighting Market |
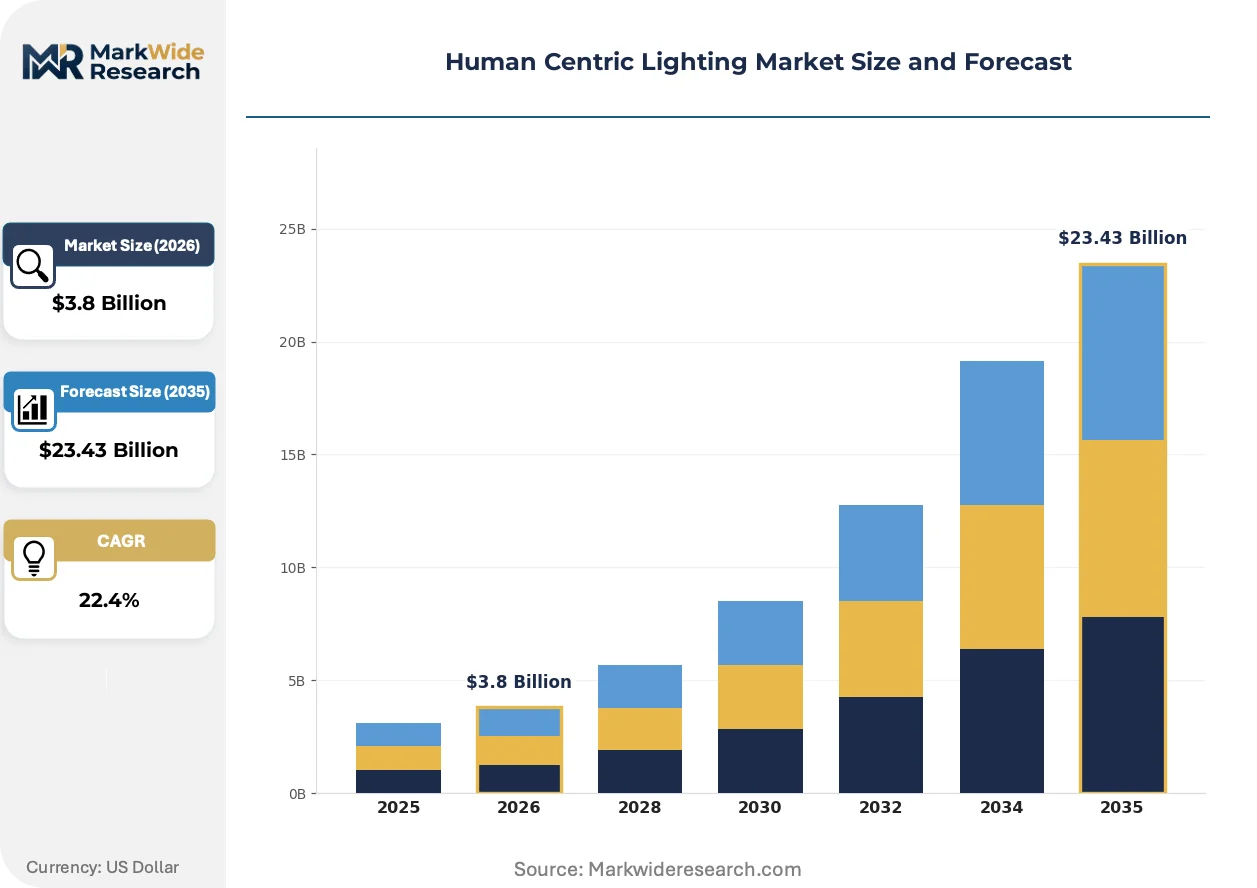
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.43 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Halogen, HID Technology: Smart Lighting, Cloud-Based Systems, IoT Integration, Dimming Solutions Application: Commercial Spaces, Residential Areas, Healthcare Facilities, Educational Institutions End User: Architects, Interior Designers, Facility Managers, Homeowners |
| Companies Covered | Signify Holding, Zumtobel Group, ams-OSRAM AG, Acuity Brands Inc, Hubbell Inc, Lutron Electronics Co., Inc, Legrand S.A., Trilux GmbH & Co. KG, Wipro Lighting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Centric Lighting Market Emerging Trajectories
Spectral tuning architectures are fragmenting into modular component ecosystems, enabling new entrants to compete without captive semiconductor fabrication while forcing integrated manufacturers to defend through software differentiation.
Chip-on-board LED arrays with integrated driver electronics are decomposing the traditional luminaire value chain. Healthcare facility engineers in the Netherlands and Sweden specify these compact engines for surgical suite retrofits where space constraints prohibit separate driver housings. The technology is compressing margins for conventional fixture assemblers while transferring value capture upstream to semiconductor packaging specialists.
EU F-Gas Regulation phaseouts are eliminating mercury-containing fluorescent lamp options from 2027, hard-coding LED transition timelines into procurement planning. Hospital construction consortia in Italy and Spain now specify tunable white systems as baseline rather than upgrade options. The regulatory compression is most acute in public sector tenders where lifecycle cost accounting methods previously favored fluorescent first-cost advantages.
Facility managers in US academic medical centers are unbundling lighting specification from general electrical contracting, engaging directly with circadian lighting specialists for patient room and staff area designs. The purchasing pattern displaces traditional distributor relationships in favor of manufacturer-direct consulting models. This channel restructuring is most visible in NIH-funded research hospital expansions where environmental design grants require documented circadian performance outcomes.
Human Centric Lighting Market Segmentation
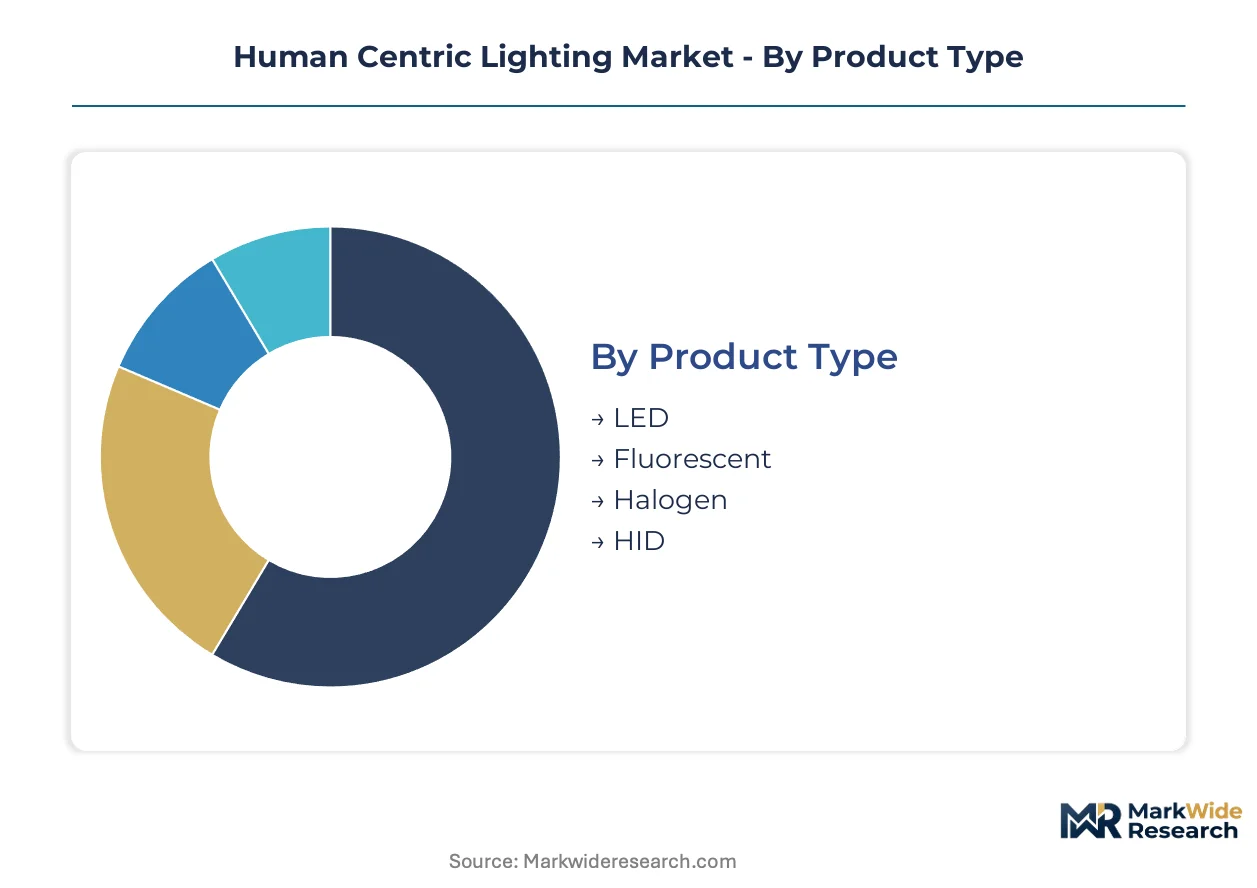
Human centric lighting segmentation reveals how spectral programmability, control intelligence, and specification authority distribute value across the value chain. Category boundaries are blurring as tunable white engines merge with building automation platforms.
Product Type:
LED products capture the deepest margin pools through captive phosphor chemistry and spectral calibration capabilities, while legacy technologies compete on replacement cycle timing.
- LED:Tunable white engines with correlated color temperature ranges from 2700K to 6500K dominate specification. Healthcare facilities in Germany and France mandate LED retrofits under EU Green Deal efficiency directives, displacing fluorescent alternatives through lifecycle cost accounting.
- Fluorescent:Mercury-containing lamps face regulatory phaseout under EU F-Gas Regulation elimination from 2027. Aging commercial buildings with ballast-compatible wiring impose retrofit friction that slows conversion despite operational cost penalties.
- Halogen:Residential accent lighting retains niche demand where warm dimming characteristics override efficiency concerns.
- HID:Industrial high-bay applications maintain installed base where spectral quality requirements remain secondary to lumen output per watt.
LED holds installed capacity. Fluorescent is rotating down the share rankings as regulatory deadlines harden.
Technology:
Software-enabled control layers are extracting value from hardware commoditization, with cloud connectivity and circadian scheduling commanding premium positioning.
- Smart Lighting:Sensor-integrated systems with occupancy-responsive dimming and melanopic lux calibration capture expanding margin pools. US academic medical centers unbundle lighting specification from general electrical contracting, engaging directly with circadian specialists for patient room designs.
- Cloud-Based Systems:Remote spectral scheduling and energy analytics platforms enable subscription revenue models. China's MIIT smart city frameworks mandate interoperable lighting controls in tier-one city public building retrofits.
- IoT Integration:Building management system protocols require multi-vendor certification tracks from lighting suppliers.
- Dimming Solutions:Analog and digital dimming architectures serve as baseline specifications in cost-constrained commercial fit-outs.
Smart Lighting commands specification authority. Cloud-Based Systems are climbing the fastest as facility managers prioritize remote diagnostics.
Application:
Healthcare and education verticals concentrate specification complexity where circadian efficacy claims justify premium pricing.
- Healthcare Facilities:Patient room and surgical suite designs require melanopic-effective illumination with documented performance outcomes. NIH-funded research hospital expansions in the United States mandate environmental design grants with circadian validation.
- Educational Institutions:Classroom and administrative spaces specify tunable white systems to enhance student alertness and cognitive performance. WELL Building certification requirements pull circadian-effective systems into mainstream specification.
- Commercial Spaces:Office fit-outs balance first-cost constraints against productivity claims from spectral tuning.
- Residential Areas:Smart home platforms in North American and European markets add circadian scheduling modules, opening consumer channels.
Healthcare Facilities anchor premium pricing. Educational Institutions are gaining share fastest as certification standards proliferate.
End User:
Professional specification authority determines product positioning, with technical knowledge gaps creating channel control opportunities.
- Facility Managers:Direct procurement authority in US academic medical centers displaces traditional distributor relationships. Unbundled specification patterns favor manufacturer-direct consulting models with documented circadian performance outcomes.
- Architects:European commercial fit-outs channel relationships determine specification success, particularly in Netherlands and Swedish surgical suite retrofits.
- Interior Designers:Residential wellness integration projects specify dawn-dusk simulation systems for aging care applications.
- Homeowners:Consumer channel expansion through smart home platforms remains price-sensitive with limited technical specification capability.
Facility Managers control procurement budgets. Architects are rotating up the influence rankings as building automation integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare retrofit intensity in Germany diverges sharply from smart city deployment patterns in China, while US academic medical centers pioneer specification unbundling that other geographies have yet to replicate.
United States
NIH-funded research hospital expansions mandate circadian performance documentation in environmental design grants. FDA guidelines on healthcare environmental design shape spectral requirements in new hospital construction. Facility managers in academic medical centers across Massachusetts and California now procure lighting directly from specialists, bypassing traditional electrical distributors.
Germany
Healthcare facilities accelerate LED retrofits under EU Green Deal carbon reduction mandates. F-Gas Regulation phaseouts eliminate mercury-containing fluorescent options from 2027 procurement cycles. Hospital construction consortia in Bavaria and North Rhine-Westphalia specify tunable white systems as baseline rather than upgrade specifications.
China
Tier-one city public building retrofits drive standardized demand for sensor-integrated human centric systems. MIIT smart city frameworks mandate interoperable lighting controls in municipal construction. Beijing and Shanghai construction authorities embed spectral requirements into healthy building certification protocols.
Netherlands
Surgical suite retrofits specify chip-on-board LED arrays with integrated driver electronics where space constraints prohibit separate housings. ECHA chemical safety assessments influence phosphor chemistry selection in luminaire manufacturing. Healthcare engineers in Amsterdam and Rotterdam medical clusters lead adoption of compact spectral tuning engines.
Japan
Dementia care and assisted living operators specify dawn-dusk simulation systems to address sleep disruption in elderly populations. METI energy efficiency standards accelerate fluorescent replacement in institutional settings. Osaka and Tokyo metropolitan aged-care facility networks pilot circadian rhythm modulation for cognitive health outcomes.
Human Centric Lighting Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in human centric lighting, with captive LED chip production conferring spectral calibration advantages. Semiconductor-lighting manufacturers with in-house phosphor chemistry control margin pools in healthcare verticals, while assembly-focused fixture producers compete on channel relationships and retrofit execution speed. Three archetypes dominate: vertically integrated semiconductor specialists, architectural channel specialists with regional specification authority, and smart controls integrators extracting value from software layers. Consolidation pressure operates through M&A targeting circadian scheduling software capabilities, while geographic expansion into Asian smart city frameworks represents the second dominant competitive move.
Among European-anchored integrated manufacturers, Signify Holding and ams-OSRAM AG occupy positions reflecting captive production of spectral tuning components, while Zumtobel Group exemplifies the architectural channel specialist archetype with concentrated relationships in European commercial fit-outs.
| Leading Market Players |
|---|
| Signify Holding |
| Zumtobel Group |
| ams-OSRAM AG |
| Acuity Brands Inc |
| Hubbell Inc |
| Lutron Electronics Co., Inc |
| Legrand S.A. |
| Trilux GmbH & Co. KG |
| Wipro Lighting |
| Others |
Supply Flow & Price Mechanics
Phosphor substitution from cerium-doped yttrium aluminum garnet to alternative chemistries is redrawing supply geography and compressing margin structures for tunable white LED engines. This input transition simultaneously exposes manufacturers to Chinese processing concentration risks while creating pricing leverage for captive chemistry holders.
Pricing Analysis
After-sales revenue from spectral recalibration services and extended circadian scheduling contracts drives lifetime value capture. The dominant pricing model stratifies across premium certified healthcare tiers, standard commercial fit-outs, and economy residential channels. Price differentiation rests on WELL Building certification status and melanopic lux validation depth. Cost compression in standard-tier fixture assembly is intensifying due to modular chip-on-board engine proliferation. Residential smart home buyers exhibit highest price sensitivity, while NIH-funded academic medical centers demonstrate lowest sensitivity given grant-backed procurement authority.
Supply Chain Analysis
China dominates phosphor processing and rare earth refinement for LED spectral tuning components. Taiwan and South Korea anchor semiconductor wafer fabrication for tunable white driver electronics. Raw material dependencies center on cerium, yttrium, and gallium nitride substrates. Single-source vulnerability concentrates in Chinese rare earth processing facilities subject to export licensing variability. Distribution runs through architectural specification channels in European commercial markets and direct manufacturer engagement in US healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Human centric lighting sits in early-cycle expansion as EU F-Gas Regulation deadlines and WELL Building certification proliferation accelerate retrofit specifications beyond early-adopter healthcare verticals.
For Market Incumbents: Consolidate circadian scheduling software capabilities through targeted acquisition of building automation integration specialists. Deepen captive phosphor chemistry control to defend margin pools against modular engine commoditization. Prioritize certification maintenance across multiple BMS protocol tracks to preserve specification authority in fragmented control landscapes.
For New Entrants and Emerging Players: Differentiate on residential wellness platform integration where smart home circadian modules remain underpenetrated relative to commercial channels. Target North American and European consumer markets through direct-to-installer partnerships bypassing established distributor relationships. Pursue white-label spectral engine supply to architectural fixture assemblers lacking semiconductor capabilities.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed smart controls integrators possessing multi-vendor BMS certification libraries but lacking spectral calibration expertise. Five-to-ten year viability favors platforms combining hardware-agnostic software layers with validated melanopic efficacy protocols. Monitor EU regulatory enforcement intensity on F-Gas phaseout timelines as inflection indicator for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Circadian Software Acquisition | Captures building automation integration capabilities essential for multi-vendor BMS certification. |
| Phosphor Chemistry Backward Integration | Secures spectral tuning input supply against Chinese rare earth processing concentration risks. |
| WELL Building Partnership Program | Locks specification authority through certified designer training and validation documentation. |
| Residential Platform Integration | Opens consumer channels via smart home ecosystem partnerships with circadian scheduling modules. |
| Healthcare Direct Engagement Model | Displaces distributor relationships through manufacturer-direct consulting for NIH-funded expansions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across facility management, architectural specification, and semiconductor manufacturing domains. Primary interviews captured procurement directors at German hospital consortia, lighting designers in Netherlands medical clusters, and LED packaging engineers in Taiwan. Secondary validation drew from EU F-Gas Regulation filings, MIIT smart city framework documents, WELL Building certification databases, and SEC disclosures from listed lighting manufacturers. Bottom-up installed base modeling and top-down regulatory mandate sizing were triangulated for cross-verification.
Across the analysis window, volume projections incorporated retrofit cycle timing under EU Green Deal mandates and melanopic lux calibration adoption curves in healthcare construction. Segmentation dimensions spanned product type, control technology, application vertical, and end-user specification authority. CAGRs were derived from regression analysis of historical LED penetration rates adjusted for circadian efficacy premium capture. Industry-specific inputs included phosphor chemistry cost curves and BMS protocol certification lag times.
Decision-makers should treat outputs as directional under stable regulatory enforcement and phosphor supply continuity assumptions; material deviation in rare earth export policy or F-Gas phaseout delays would warrant model refresh. Specific risks include qualified circadian lighting designer scarcity, proprietary control protocol fragmentation, and clinical validation protocol absence for melanopic claims. Recalibration cycles align with material shifts in EU Green Deal implementation intensity and MIIT smart city deployment pacing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Industrial LiDAR Integrated Lighting Market
Lighting
Wireless Lighting Market
Lighting
Specialty Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Plasma Lighting Market
Lighting
Flexible Lighting Foils Market
Lighting
Connected Lighting Platform Market
Lighting
Global Lighting Control System Market
Lighting
OLED Lightening Panels Market
Lighting
Lighting As a Service (Laas) Market
Lighting
Industrial UV-C Disinfection Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Miniature Bulbs Market
Lighting
North America Street Lighting Market
Lighting
Intelligent Lighting Controls Market
Lighting
Malaysia LED Lighting Controllers Market