
 Residential Lighting Fixtures Market | 2026-2036
Residential Lighting Fixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Lighting Fixtures Market Intelligence
The division between custom, designer-grade fixtures and mass-market commodity products is hardening, creating distinct competitive arenas. Philips Lighting leverages its global scale and brand recognition to compete across multiple price points. Meanwhile, specialists like Lutron focus on high-margin smart home integration and control systems, while Visual Comfort & Co. differentiates through exclusive designer collaborations.
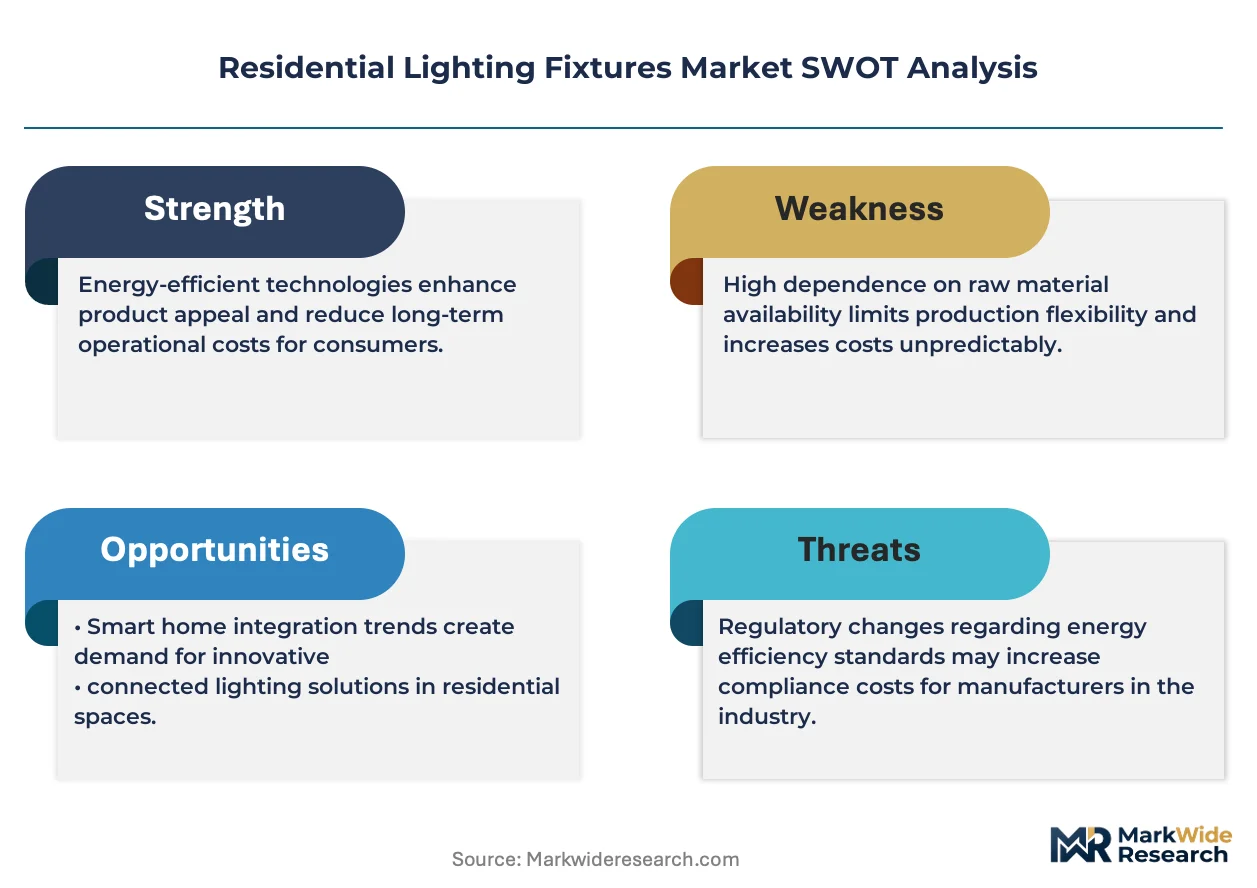
Residential lighting fixtures are devices designed to hold and power electric lamps, engineered for standard household voltages and interior use. These fixtures provide ambient, task, or accent illumination while contributing to the aesthetic of a living space. The LED technology segment now dominates new sales, displacing older incandescent and CFL options due to superior efficiency and longevity. Within product types, ceiling lights remain the volume leader, but wall sconces are gaining share with interior designers.
The US Environmental Protection Agency’s ENERGY STAR program sets voluntary efficiency standards that influence consumer choice. In parallel, the EU’s RoHS directive restricts hazardous materials like lead and mercury in electronic components, impacting supply chain sourcing. Navigating the fragmentation of smart home communication protocols and ensuring interoperability represents a critical decision point for fixture manufacturers.
Market Dynamics
The fundamental transition from incandescent and fluorescent sources to solid-state LED technology is the central force shaping the residential lighting fixture market. This shift redefines product engineering, supply chain logistics, and the integration of digital controls into formerly analog devices.
Growth Catalysts
- Energy Efficiency Mandates:Government programs like the US Environmental Protection Agency's ENERGY STAR certification create strong consumer pull for certified, energy-efficient fixtures, steering manufacturer product development toward higher performance standards.
- New Construction Activity:Concentrated residential construction projects, particularly in the urban centers of India and Southeast Asia, generate significant, localized demand for a full range of lighting fixtures, from basic to high-end.
- Smart Home Ecosystems:The expanding adoption of smart home platforms by homeowners is a primary growth vector, creating demand for fixtures with integrated connectivity that can be controlled via voice assistants and mobile applications.
Market Restraints
- Component Supply Volatility:Fixture manufacturing is dependent on a global supply chain for electronic components like LED drivers and microcontrollers, which is subject to price fluctuations and potential shortages, impacting production schedules.
- Protocol Fragmentation:The lack of a single, universally adopted communication standard for smart home devices creates interoperability challenges, forcing manufacturers to support multiple protocols or risk excluding potential customers.
- Regulatory Material Restrictions:Directives such as the EU's RoHS, which restricts hazardous substances in electronic equipment, impose strict compliance and sourcing requirements on manufacturers, adding complexity and cost to supply chain management.
Strategic Opportunities
- Human-Centric Lighting:There is a growing opportunity to develop fixtures that support health and wellness, such as tunable systems that mimic natural circadian rhythms, creating a new premium category focused on biological benefits.
- Designer Collaboration Models:Expanding on the success of high-end brands, there is an opportunity for mid-market players to use exclusive collaborations with regional designers and architects to create differentiated product lines.
- Retrofit and Renovation Market:A significant opportunity exists in developing easy-to-install smart lighting kits and modular fixtures specifically designed for the residential renovation market, targeting homeowners upgrading existing spaces.
Industry Challenges
- Compliance Across Jurisdictions:Manufacturers face the operational challenge of ensuring products meet a complex and divergent web of international safety certifications, energy efficiency labels, and material regulations to access different geographic markets.
- Software Development Talent:As fixtures become smarter, manufacturers increasingly compete for software engineers and user experience designers, a skill set not traditionally core to the lighting industry, creating talent acquisition challenges.
- Ensuring Interoperability:A critical challenge is the technical and financial burden of testing and certifying fixtures for compatibility with a constantly changing landscape of smart home hubs, apps, and voice control platforms from major tech companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Lighting Fixtures Market |
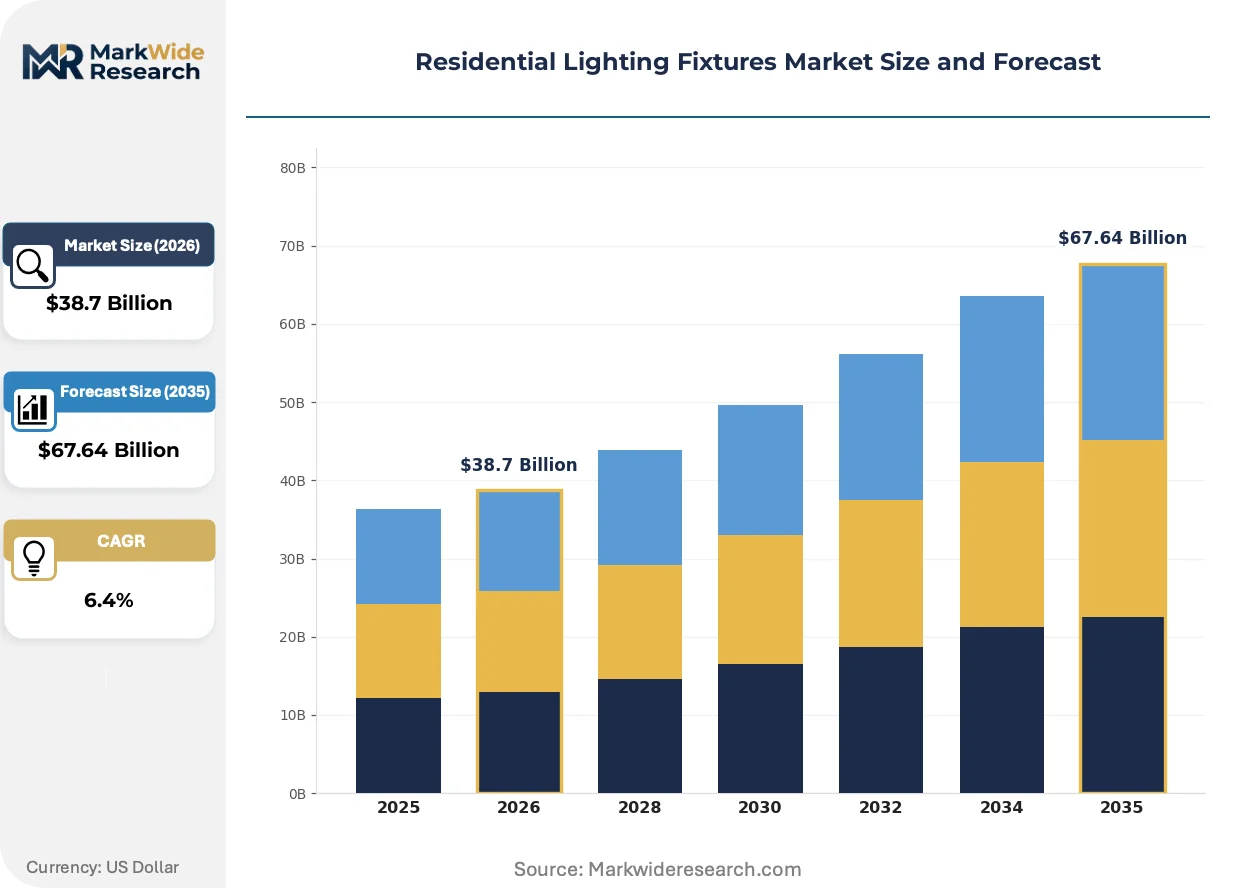
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Lights, Wall Sconces, Table Lamps, Floor Lamps Technology: LED, Incandescent, CFL, Halogen End User: Homeowners, Contractors, Interior Designers, DIY Enthusiasts Style: Modern, Traditional, Rustic, Minimalist |
| Companies Covered | Cree Lighting, Lutron, Philips Lighting, Minka-Lavery, Visual Comfort & Co., Acuity Brands, Leviton Lighting, Juno Lighting Group, Cooper Lighting Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Lighting Fixtures Market Strategic Shifts & Innovations
The evolution of lighting fixtures is marked by their transformation from static hardware into dynamic, connected endpoints within the home. This shift is driven by advancements in solid-state lighting, embedded software, and a deeper understanding of light's effect on human well-being.
Tunable LED Systems
Tunable-white LED technology provides the ability to adjust the color temperature of light, from warm to cool, via a controller or application. High-end residential and architectural specifier segments are rapidly adopting this for its ability to alter the mood and function of a space. This technology is modularizing fixture design, allowing a single hardware platform to serve multiple aesthetic and functional applications by changing software-defined light characteristics.
Circular Economy Regulations
The European Union's Ecodesign for Sustainable Products Regulation (ESPR) is setting new standards for product longevity and repairability. This policy forces a shift away from sealed, disposable units toward fixtures with replaceable light sources and drivers. Manufacturers selling into the EU are most affected, prompting redesigns of integrated LED products to ensure compliance with circular economy principles.
Ecosystem-First Purchasing
A distinct behavioral shift sees consumers selecting lighting fixtures based on their native compatibility with a preferred smart home ecosystem like Google Home or Apple HomeKit. This prioritizes software certification and seamless integration over traditional hardware metrics, disrupting established sales channels that focused on physical product attributes. This trend is most visible in the North American and European renovation markets among tech-savvy homeowners.
Residential Lighting Fixtures Market Segmentation
Understanding the distinct segments within the residential lighting fixtures market reveals varied demand drivers, technological adoption rates, and competitive landscapes. Each segment responds differently to regulatory shifts, consumer trends, and economic factors, necessitating tailored strategic approaches from manufacturers.
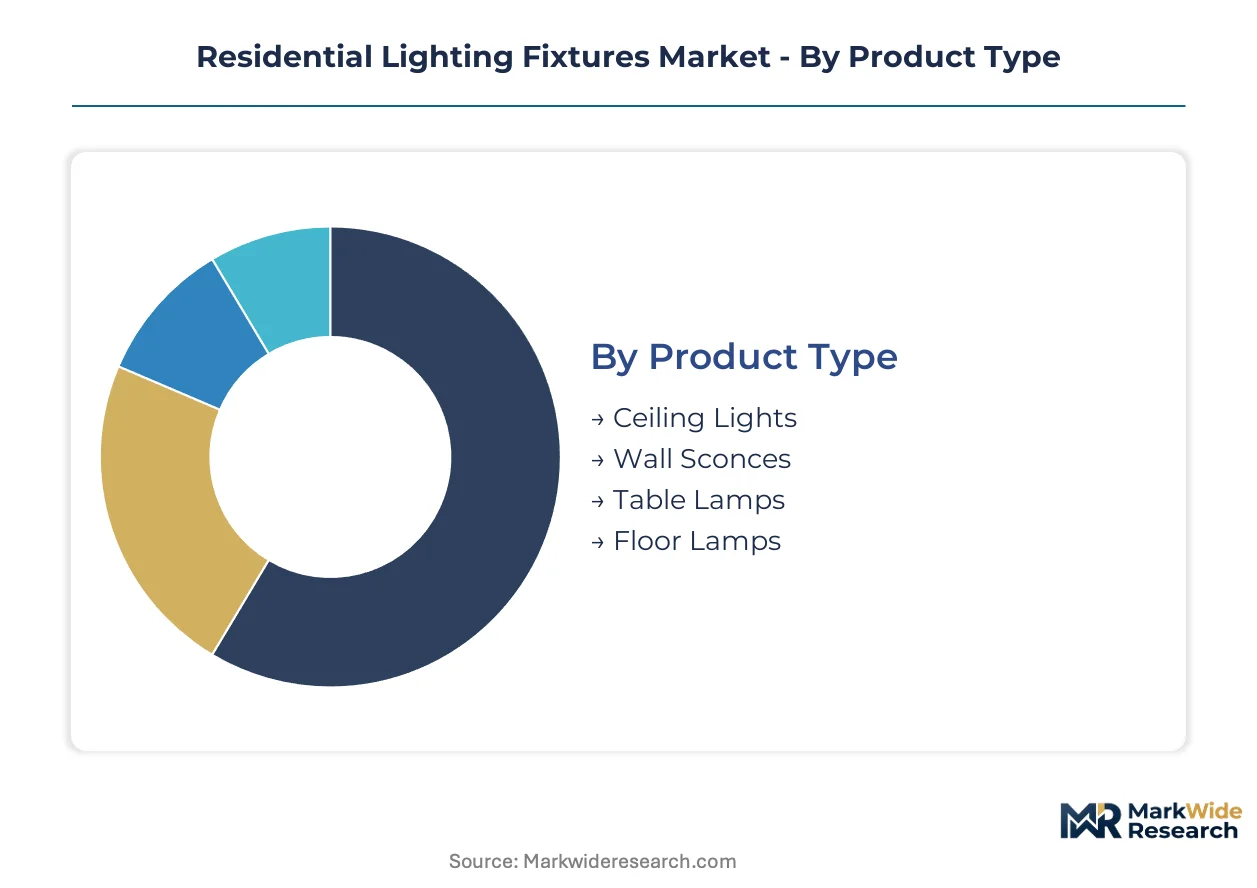
Product Type:
The varying regulatory compliance burden significantly influences product type segmentation, with fixed installations often subject to more stringent safety and electrical standards.
- Ceiling Lights:These fixtures are permanently installed and hardwired, providing primary ambient illumination from above. Concentrated demand arises from new residential construction projects in urban centers like India, where they serve as the volume leader in fixture installations.
- Wall Sconces:Designed for accent or supplementary lighting, these fixtures are mounted directly to walls, often enhancing architectural features or providing task lighting. Gaining significant share with interior designers, particularly in the renovation market, due to their aesthetic integration capabilities.
- Table Lamps:Portable and versatile, these fixtures offer localized task or accent lighting.
- Floor Lamps:Standalone lighting units, providing ambient or accent illumination without permanent installation.
Leading the category by volume: Ceiling Lights. Growing fastest: Wall Sconces.
Technology:
The technological maturity of light sources fundamentally differentiates segments, driving shifts in manufacturing investment and consumer preference.
- LED:Solid-state lighting technology offering superior energy efficiency, extended lifespan, and design flexibility. This technology now dominates new sales, fundamentally displacing older options due to its efficiency and longevity across global markets.
- Incandescent:Traditional filament-based light sources that produce light through heat, known for their warm color temperature. Continued displacement by energy-efficient LED technology fundamentally alters product design and consumer availability, driven by energy efficiency mandates.
- CFL:Compact fluorescent lamps containing mercury, offering better efficiency than incandescent but less than LED.
- Halogen:A type of incandescent lamp using a halogen gas to improve light output and lifespan.
LED technology dominates new sales, while incandescent sources continue their phase-out.
End User:
Distinct customer types drive demand for different fixture attributes, influencing design, distribution channels, and marketing strategies.
- Homeowners:Direct consumers purchasing fixtures for personal residences, often prioritizing smart home integration, aesthetics, and energy efficiency. The expanding adoption of smart home platforms by these users is a primary growth vector, creating demand for connected fixtures.
- Contractors:Professionals involved in new construction or large-scale renovation projects, often purchasing in bulk and prioritizing cost-effectiveness and ease of installation. Concentrated residential construction in urban centers generates significant demand for a full range of lighting fixtures.
- Interior Designers:Professionals who specify fixtures based on aesthetic, functional, and client-specific design requirements.
- DIY Enthusiasts:Consumers who undertake home improvement projects themselves, seeking easy-to-install and accessible lighting solutions.
Homeowners represent the largest direct purchasing segment, with interior designers influencing high-value specifications.
Style:
Consumer aesthetic preferences shape product design cycles and material choices across different style segments.
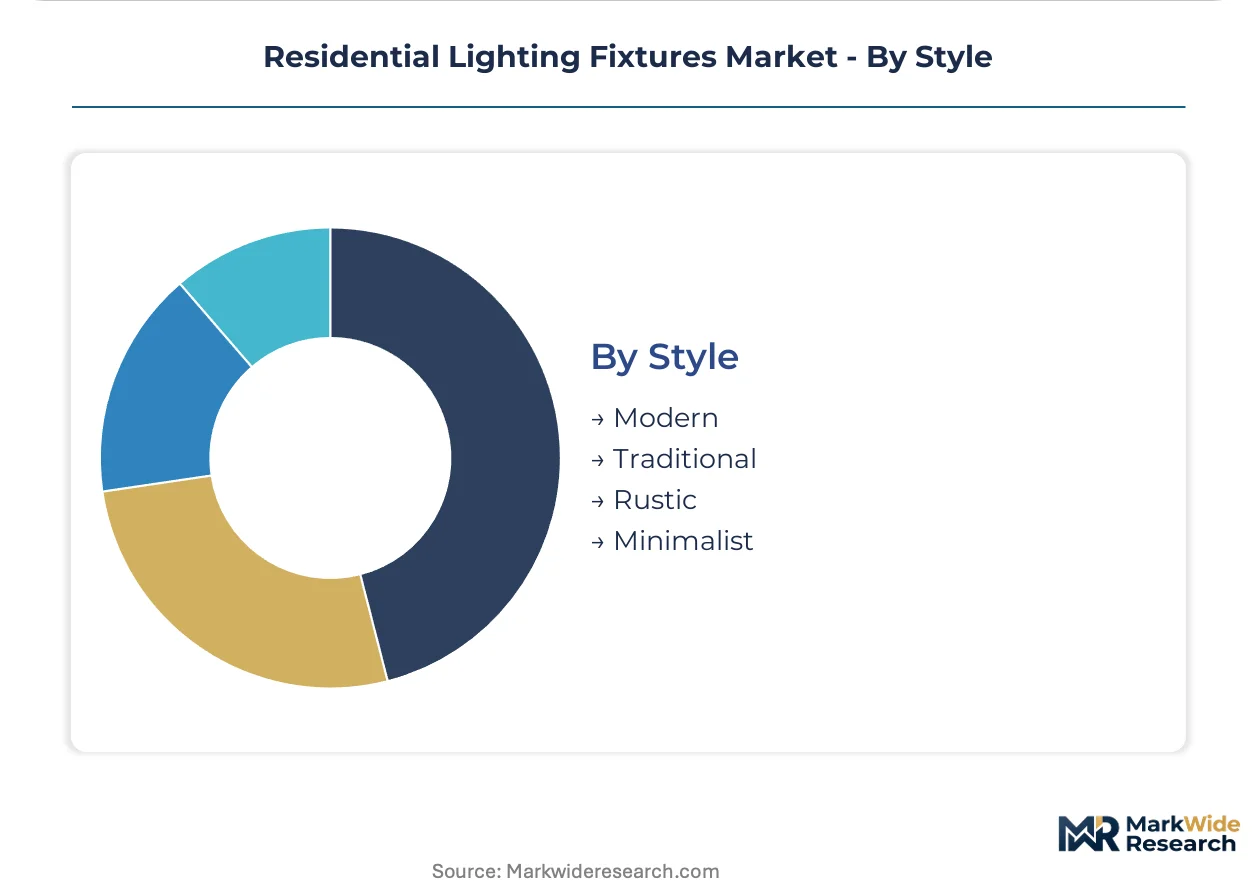
- Modern:Characterized by clean lines, minimalist forms, and often incorporating integrated LED technology and smart features. This style appeals to urban residential markets and tech-savvy homeowners seeking contemporary aesthetics and functionality.
- Traditional:Encompasses classic designs, often with ornate details, historical influences, and conventional materials like brass or crystal. Demand for this style remains consistent in established residential areas and for specific architectural contexts.
- Rustic:Features natural textures, earthy tones, and materials such as wood, wrought iron, or distressed finishes.
- Minimalist:Emphasizes simplicity, functionality, and an absence of excessive ornamentation, often blending seamlessly into the architectural environment.
Modern and minimalist styles are gaining traction in new residential projects, reflecting contemporary design trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Delhi's burgeoning residential construction sector, alongside other major urban centers, drives significant demand for residential lighting fixtures. These regional dynamics reflect varied consumer preferences, regulatory environments, and economic growth patterns across key global markets. Manufacturers must navigate these distinct market characteristics to optimize their distribution and product strategies.
United States
Homeowner demand for integrated smart lighting systems and energy-efficient solutions fuels market expansion across the United States. The US Environmental Protection Agency's ENERGY STAR program significantly influences consumer choice for certified products. Concentrated residential development in metropolitan areas like Dallas-Fort Worth and Atlanta creates consistent demand for a full range of fixture types.
India
Concentrated residential construction projects in urban centers like Mumbai and Bengaluru generate substantial demand for lighting fixtures, from basic to high-end. The Bureau of Indian Standards (BIS) sets quality and safety standards that manufacturers must meet for market access. Major cities such as Chennai and Hyderabad are experiencing rapid urbanization, driving localized fixture sales.
Germany
Consumers in Germany prioritize energy efficiency and high-quality design, leading to strong adoption of advanced LED and tunable lighting systems. The EU's Ecodesign for Sustainable Products Regulation (ESPR) mandates product longevity and repairability, impacting fixture design. Munich and Berlin's affluent residential markets show strong preference for human-centric lighting solutions.
China
Rapid urbanization and a growing middle class in China drive demand for modern and smart lighting solutions in new residential developments. China's GB standards regulate product safety and energy efficiency for all lighting products sold domestically. Manufacturing hubs in the Pearl River Delta, including Guangzhou and Shenzhen, serve as major production and consumption centers.
Japan
Japan's market emphasizes innovative, space-saving designs and advanced smart home integration for residential lighting. The Ministry of Economy, Trade and Industry (METI) promotes energy conservation through various initiatives and regulations. Tokyo and Osaka's dense urban environments create specific demand for compact, high-performance lighting fixtures.
Residential Lighting Fixtures Market Key Industry Players
Capital-heavy producers compete with asset-light designers within the residential lighting fixtures market, creating a diverse competitive environment. The market exhibits a tiered structure, with global conglomerates operating alongside specialized niche players and design-focused brands. Strategic archetypes include scale-driven manufacturers, technology innovators, and design-led specialists. Dominant competitive moves involve portfolio diversification into smart home ecosystems and strategic partnerships with interior designers.
Leading global players like Philips Lighting occupy a position across multiple price points, leveraging extensive distribution networks and brand recognition. Specialists such as Lutron exemplify the high-margin smart home integration segment, focusing on advanced control systems and interoperability. Visual Comfort & Co. represents the design-led archetype, anchoring its strategy through exclusive collaborations with renowned designers to create differentiated product lines.
| Leading Market Players |
|---|
| Cree Lighting |
| Lutron |
| Philips Lighting |
| Minka-Lavery |
| Visual Comfort & Co. |
| Acuity Brands |
| Leviton Lighting |
| Juno Lighting Group |
| Cooper Lighting Solutions |
| Others |
Cost & Logistics Intelligence
Homeowner demand for integrated smart lighting systems drives fixture manufacturers to incorporate advanced digital controls, influencing component sourcing and overall product pricing. This shift creates a premium segment within the residential lighting fixtures market.
Pricing Analysis
Value-based pricing anchors premium segments, reflecting advanced smart home integration and exclusive designer collaborations. Price differentiation also stems from energy efficiency certifications like the US Environmental Protection Agency's ENERGY STAR and established brand premium. Cost compression in the mass market intensifies due to component supply volatility and intense competition. Contractors exhibit higher price sensitivity compared to homeowners prioritizing integrated smart features.
Supply Chain Analysis
Circular economy regulations like the EU's Ecodesign for Sustainable Products Regulation are forcing manufacturers to consider reverse logistics for repairable and replaceable components. Supply concentration for electronic components centers on manufacturing hubs in China and Southeast Asia, with key dependencies including LED drivers and microcontrollers. Regulatory material restrictions, such as the EU's RoHS directive, pose a significant structural supply chain risk. Distribution runs through both large retail networks and specialized smart home integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential lighting fixtures market increasingly operates as a cost-of-compliance story, where adherence to directives like the EU's Ecodesign for Sustainable Products Regulation forms a significant barrier to entry. This regulatory environment favors manufacturers capable of navigating complex sustainability and material requirements.
For Market Incumbents: Acquire software development talent and user experience design capabilities to counter the talent acquisition challenge. Diversify product portfolios into comprehensive smart home ecosystems, mitigating the risk of protocol fragmentation. Reinforce channel control by strengthening relationships with contractors and interior designers. Invest in certification for interoperability across major smart home platforms to defend market share.
For New Entrants and Emerging Players: Begin with targeted product development for the residential retrofit and renovation market, offering easy-to-install smart lighting kits. Focus on human-centric lighting solutions to establish a premium niche for health and wellness benefits. Forge exclusive collaborations with regional designers and architects to differentiate product lines. The mid-market segment in North American renovation markets presents a penetrable entry point.
For Investors and Strategic Acquirers: Re-rating potential sits with technology innovators and design-led specialists given the market's shift towards integrated smart and human-centric lighting. Long-term viability favors companies with strong intellectual property in tunable LED systems and robust interoperability solutions. Monitor the consolidation of smart home communication protocols as a key inflection indicator. Acquisition targets should exhibit proven capabilities in software integration and designer collaborations.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Expands market reach into smart home ecosystems, leveraging existing brand recognition. |
| Designer Collaborations | Differentiates product lines and captures high-value segments through unique aesthetic appeal. |
| Interoperability Certification | Ensures seamless integration with diverse smart home platforms, enhancing customer experience. |
| Tunable LED R&D | Develops human-centric lighting solutions, opening new premium categories focused on wellness. |
| Supply Chain Resilience | Mitigates risks from component supply volatility and regulatory material restrictions like RoHS. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market intelligence. Primary research involved in-depth interviews with fixture manufacturers, interior designers, contractors, and smart home integrators. This approach combined bottom-up market sizing with top-down validation against industry reports. Data triangulation ensured robust and comprehensive market insights.
Market dimensions were modeled at granular levels, including product type, technology, end user, style, and key geographic markets across the analysis window. Compound annual growth rates were derived through historical trend extrapolation and regression analysis. New residential construction starts in urban centers and smart home adoption rates served as critical forecast inputs. This framework provided detailed projections for the residential lighting fixtures market.
Geopolitical shifts, supply chain disruptions, and rapid technological advancements are the dominant revision risks for market forecasts. These projections reflect assumptions regarding future economic conditions and consumer behavior. Practitioners should monitor smart home protocol standardization and new material regulations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Gesture Control Light Market
Lighting
Portable Lamps Market
Lighting
North America Outdoor Lighting Market
Lighting
Intelligent Lighting Controls Market
Lighting
Plasma Lighting Market
Lighting
Dimmer and Color Tunable Market
Lighting
LED Eye Protection Desk Lamp Market
Lighting
Connected Lighting Platform Market
Lighting
Europe Lighting Control Systems Market
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Global Lighting Control System Market
Lighting
Eye-Illuminating Gadgets Market
Lighting
Photocell Market
Lighting
Connected (Smart) Street Lighting Market
Lighting
Lighting Product Market