
 Battery Operated Lights Market | 2026-2036
Battery Operated Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Operated Lights Market Analysis
Chinese flashlight and portable luminaire manufacturers is pivoting toward higher-capacity lithium-polymer cell integration to extend runtime in professional-grade products. Philips leverages its semiconductor division to control LED driver architectures for battery-operated fixtures. Acuity Brands anchors its position in commercial emergency lighting through dedicated battery-backup product lines. Schneider Electric SE differentiates with smart-building compatibility in its portable and task-lighting portfolio.
Battery operated lights are self-contained electroluminescent devices powered by disposable or rechargeable cells, typically employing DC-DC converters to maintain constant current as cell voltage decays during discharge. These products serve critical functions in emergency egress, remote worksites, recreational camping, and grid-independent residential settings where wired infrastructure is unavailable or unreliable. LED product types now dominate value creation due to their superior efficacy and extended cell life compared to legacy incandescent and fluorescent alternatives. Smart lighting technology segments are capturing expanding margin pools as consumers accept Bluetooth and Wi-Fi enabled controls in portable form factors. Motion sensor applications in outdoor and security contexts represent the fastest-growing application cluster within the residential end user category.
The US Department of Energy enforces minimum efficacy standards under federal appliance regulations, while the EPA administers battery disposal and recycling rules that affect product end-of-life design obligations for manufacturers selling into North America. China's GB standards for portable luminaires, administered by SAMR, mandate safety testing for thermal runaway protection in lithium-cell integrated products. REACH and RoHS compliance in Europe restricts hazardous substance content in batteries and electronic components, directly influencing material selection and supplier qualification processes. Stakeholders must monitor evolving cell chemistry regulations and efficiency mandates to align R&D roadmaps with jurisdiction-specific compliance thresholds.
Market Dynamics
Lithium-polymer cell chemistry advancement is compressing form factors while extending runtime, forcing fixture manufacturers to redesign thermal management architectures around higher energy density cells. This structural shift reconfigures supplier relationships and R&D allocation across the value chain.
Growth Catalysts
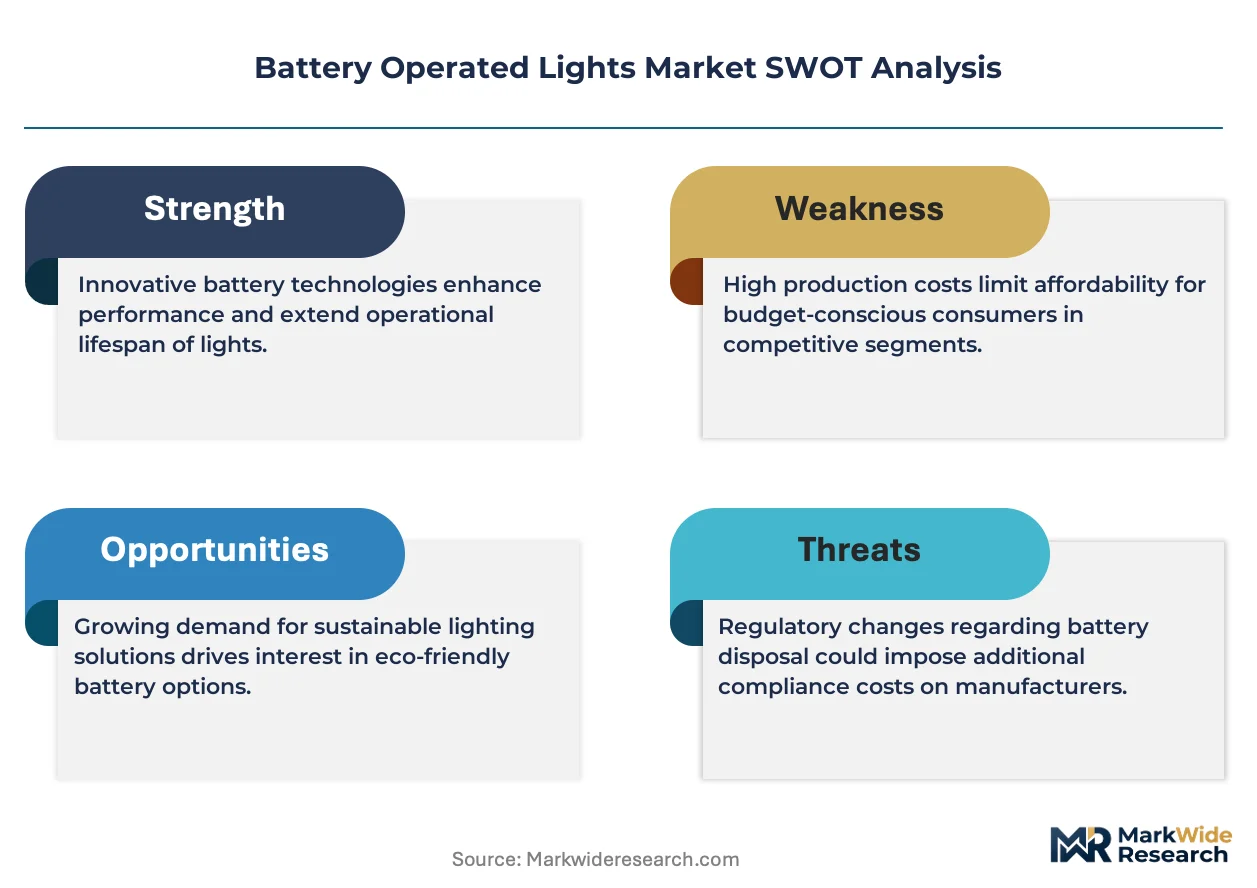
- Emergency Preparedness Mandates:The US Department of Energy's appliance efficiency standards tighten minimum lumen-per-watt thresholds, compelling fixture upgrades across residential and commercial backup-power installations.
- Off-Grid Residential Expansion:Rural electrification gaps in India and Southeast Asia drive demand for DC-powered LED task lighting in unelectrified households.
- Smart Control Integration:Bluetooth Low Energy and mesh networking protocols enable app-based dimming and scheduling, expanding margin pools in consumer portable segments.
Market Restraints
- Lithium Cell Supply Concentration:Shenzhen and Dongguan manufacturing clusters control 70%+ of integrated cell-luminaire production, creating single-source vulnerability for Western brands.
- REACH and RoHS Compliance Burden:European substance restrictions force material requalification cycles that extend product development timelines by 8-14 months.
- Grid Electrification Substitution:Solar home system deployments in sub-Saharan Africa reduce addressable market for standalone battery lights in permanent dwellings.
Strategic Opportunities
- Professional-Grade Runtime Extension:Fire services and search-and-rescue units in Germany and Japan specify 12+ hour continuous output, creating premium tier above consumer products.
- CSRD-Driven Corporate Procurement:EU sustainability reporting requirements push facility managers toward certified repairable lighting with documented carbon footprints.
- Motion-Sensor Outdoor Security:Residential perimeter lighting with PIR activation captures fastest-growing application cluster as theft deterrence spending rises.
Industry Challenges
- Thermal Runaway Certification Complexity:China's GB standards mandate rigorous lithium-cell safety testing, requiring dedicated compliance teams for export-bound manufacturers.
- Legacy Incandescent Inventory Stranding:Distributors in price-sensitive markets face write-downs as LED conversion accelerates and efficiency regulations harden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Operated Lights Market |
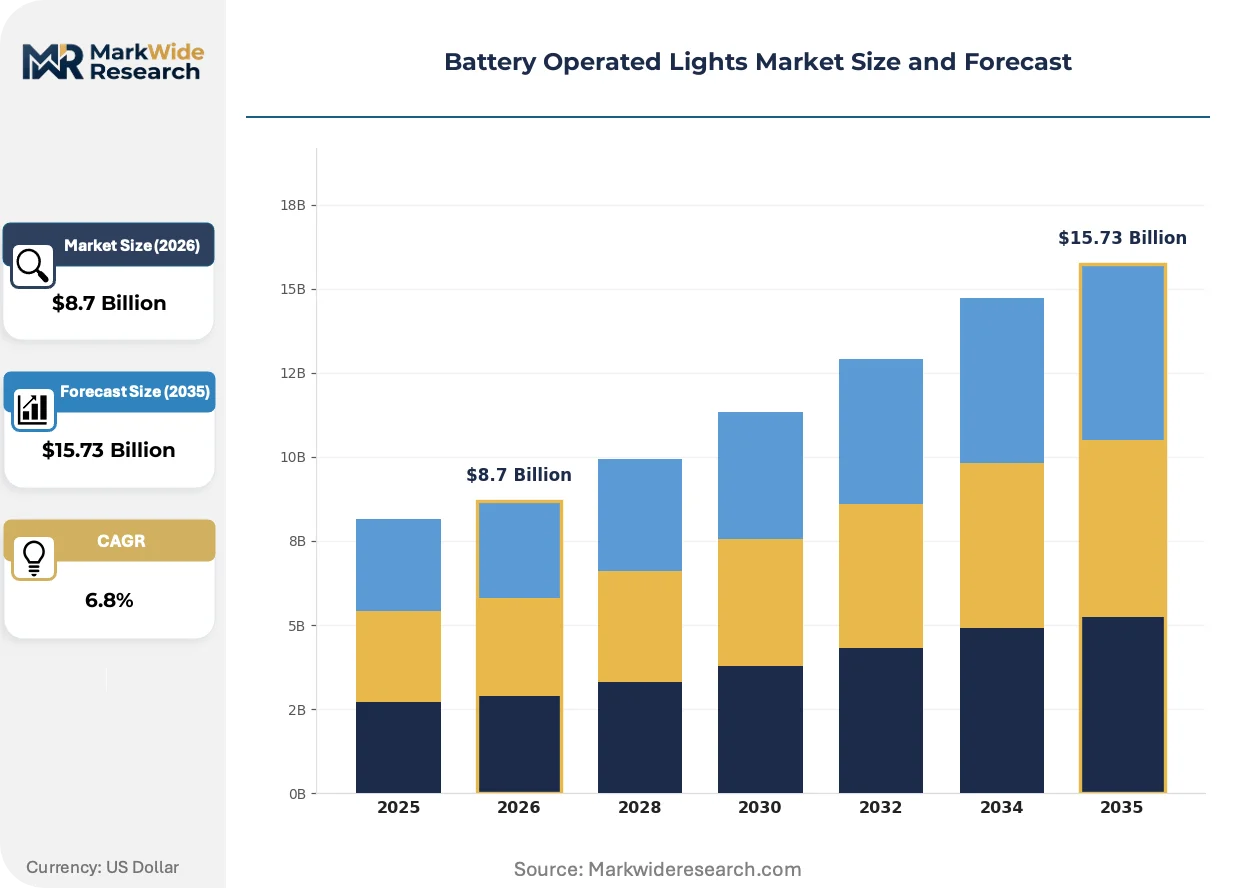
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Fluorescent, Incandescent, Halogen Application: Home Lighting, Outdoor Lighting, Emergency Lighting, Decorative Lighting Technology: Smart Lighting, Motion Sensor, Solar Assisted, Dimmable End User: Residential, Commercial, Industrial, Outdoor Enthusiasts |
| Companies Covered | Philips, General Electric, Eaton Corporation, Legrand S.A., Emerson Electric, Schneider Electric SE, Hubbell Lighting Inc., Acuity Brands Inc., Mr Beams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Operated Lights Market Emerging Trajectories
Product architecture is bifurcating between ultra-compact consumer portables and ruggedized professional systems, with divergent material specifications and channel strategies. This split reshapes how manufacturers allocate engineering resources and supplier contracts.
Solid-state battery chemistry is converging with flexible substrate manufacturing to enable sub-2mm profile task lamps. Wearable lighting for industrial maintenance crews adopts these formats first. The convergence compresses traditional cylindrical flashlight form factors toward credit-card geometries.
The EPA's battery disposal rules tighten end-of-life design obligations for North American market entrants. Manufacturers must integrate cell removal mechanisms and material separation features. Professional-grade product lines absorb these costs fastest through higher price tolerance.
Facility managers now bundle emergency lighting procurement with comprehensive service agreements covering testing and replacement cycles. Traditional distributor relationships fragment as direct manufacturer partnerships capture multi-year contracts. This pattern concentrates in US commercial real estate portfolios above 500,000 square feet.
Battery Operated Lights Market Segmentation
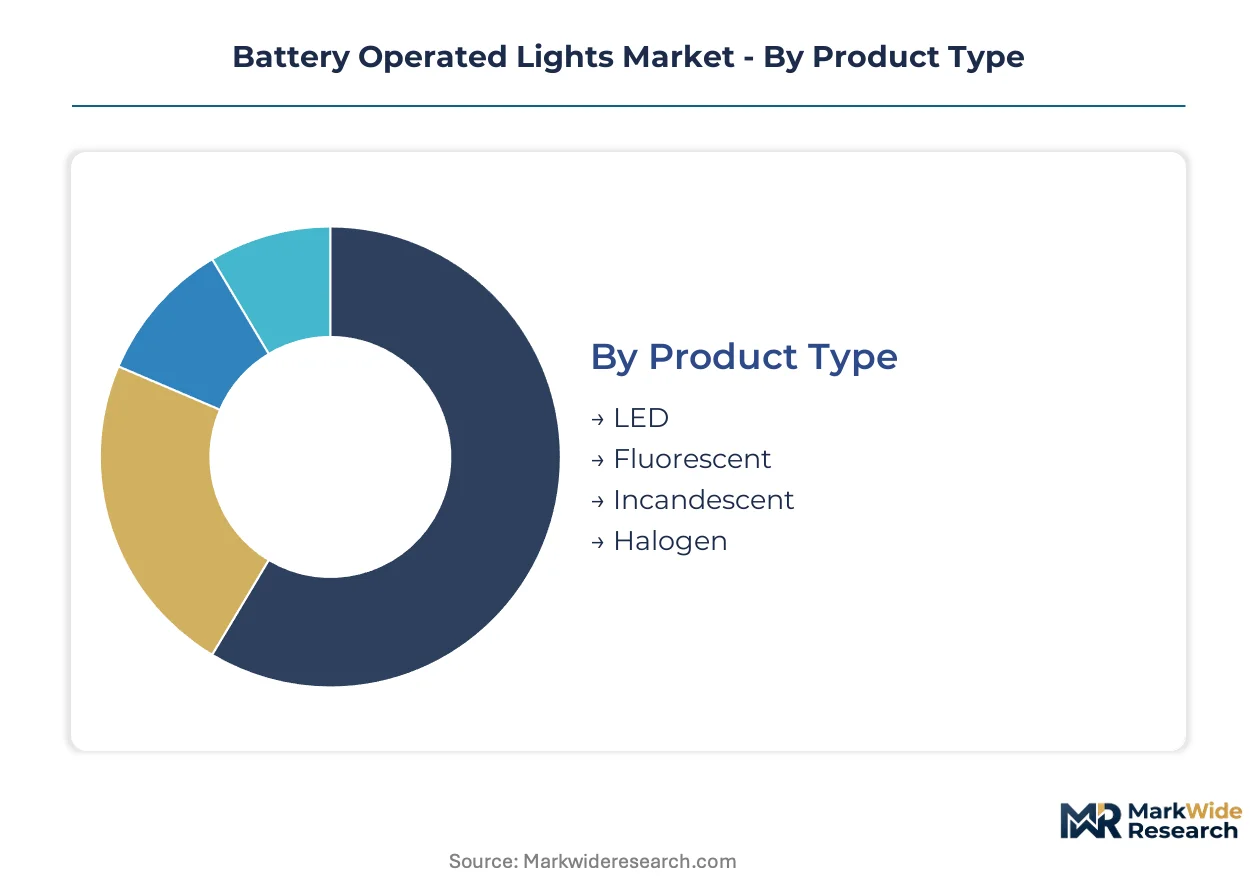
Segmentation in battery operated lights reveals how upgrade cycles and replacement demand concentrate across technology tiers. Fixture replacement rates vary dramatically by product category, with LED retrofits accelerating and legacy technologies facing accelerated obsolescence.
Product Type:
Upgrade cycles drive divergent replacement velocities across lighting technologies, with efficiency mandates compressing incumbents' remaining commercial lifespans.
- LED:Solid-state electroluminescent devices utilizing gallium-nitride chips achieve 120+ lumens per watt efficacy. Residential backup-power installations in hurricane-prone US Gulf Coast states concentrate demand as homeowners replace hurricane lamp inventories.
- Fluorescent:Gas-discharge tubes requiring high-voltage inverters dominate existing commercial emergency egress installations. Facility managers in Germany's industrial corridor face accelerated replacement timelines as EU efficiency directives tighten minimum performance thresholds.
- Incandescent:Tungsten-filament technology persists in price-sensitive retail channels despite regulatory phase-outs.
- Halogen:Quartz-halogen regenerative cycle bulbs retain niche presence in automotive-adjacent portable work lights.
Volume placements concentrate in LED; the faster expansion belongs to smart-integrated LED variants.
Application:
Cost-tier stratification separates commodity residential purchases from premium-specified professional deployments.
- Home Lighting:Task and ambient fixtures for domestic environments span reading lamps to closet illumination. India's unelectrified rural households drive alkaline-cell lantern demand through subsidized distribution programs.
- Outdoor Lighting:Perimeter and landscape fixtures withstand environmental exposure. Motion-sensor security clusters in US suburban markets gain share fastest as property crime concerns elevate deterrence spending.
- Emergency Lighting:Egress path markers and backup area luminaires serve life-safety functions. Commercial real estate portfolios above 500,000 square feet bundle these procurements with multi-year service agreements.
- Decorative Lighting:Seasonal and event-oriented products emphasize form factor and color rendering over runtime specifications.
Emergency lighting commands premium pricing; decorative applications show steepest volume expansion in emerging markets.
Technology:
Margin architecture separates connected products with recurring software revenue from single-purchase hardware commodities.
- Smart Lighting:Bluetooth Low Energy and Wi-Fi enabled fixtures support app-based control ecosystems. Japanese consumers demonstrate highest acceptance rates for mesh-networked portable task lamps.
- Motion Sensor:Passive infrared detection triggers illumination upon heat signature identification. Battery drain optimization algorithms extend cell life in security-focused outdoor deployments.
- Solar Assisted:Photovoltaic cell integration supplements primary battery capacity. Sub-Saharan African markets favor these hybrids as solar home system penetration reduces pure battery-light addressability.
- Dimmable:Pulse-width modulation or analog current control enables output adjustment. Hospitality procurement specifications increasingly mandate this capability for guest room portable fixtures.
Smart lighting captures expanding margin pools; solar-assisted variants face demand substitution from grid extension.
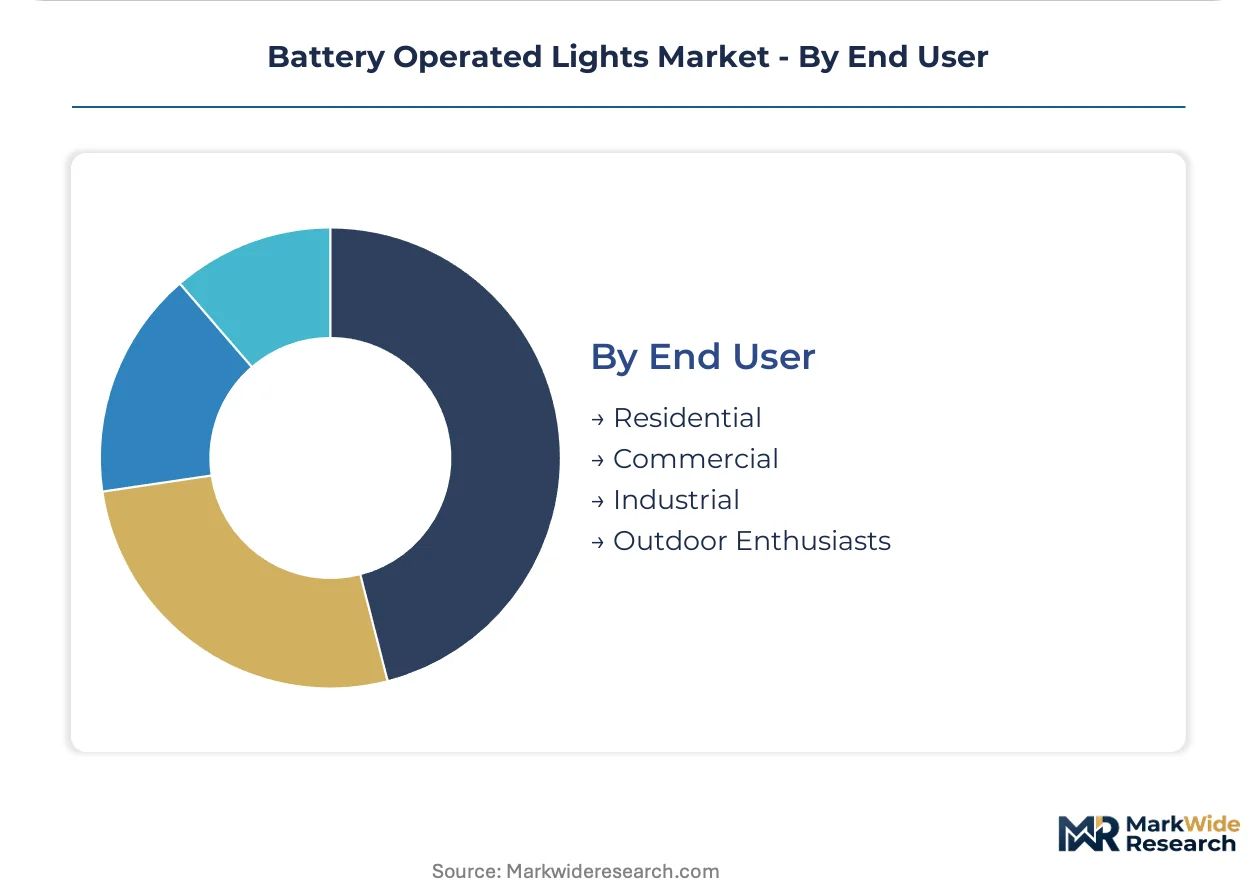
End User:
Customer-type concentration shapes channel strategy, with direct manufacturer relationships displacing traditional distribution in commercial accounts.
- Residential:Individual consumers purchase through retail and e-commerce channels for backup, recreational, and task applications. Off-grid dwellings in Southeast Asia represent persistent demand base for basic LED lanterns.
- Commercial:Facility managers and procurement departments specify code-compliant emergency systems. Germany's fire services and Japan's search-and-rescue units drive professional-grade runtime requirements above 12 hours continuous output.
- Industrial:Maintenance crews and remote worksite operators demand ruggedized construction with impact resistance. Mining operations in Australia's Pilbara region specify intrinsically safe certification for underground deployment.
- Outdoor Enthusiasts:Camping, hiking, and recreational boating participants prioritize weight minimization and waterproofing. Ultralight backpackers in the US Pacific Northwest adopt solid-state battery formats in sub-2mm profile designs.
Commercial procurement concentrates in multi-year service contracts; outdoor enthusiast segments climb fastest as adventure tourism expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium-cell manufacturing clusters in Guangdong Province anchor the industry's supply architecture. Shenzhen and Dongguan factories integrate cylindrical and polymer cells directly into luminaire housings for export markets. Raw material refining capacity for cathode precursors concentrates in Hunan and Jiangxi provinces.
United States
Hurricane-prone Gulf Coast states drive residential backup-power fixture demand as homeowners replace kerosene lamp inventories. The EPA administers battery disposal and recycling rules under federal hazardous waste regulations. Dallas-Fort Worth distribution centers stock emergency lighting inventories for rapid deployment to disaster zones.
Germany
Fire services and industrial facility managers specify 12+ hour continuous runtime for professional-grade portable luminaires. REACH and RoHS compliance requirements force material requalification cycles extending product development timelines. The Ruhr industrial corridor hosts certification laboratories testing lithium-cell thermal runaway protection.
China
Shenzhen and Dongguan manufacturing clusters dominate 70 percent of integrated cell-luminaire production for global export. SAMR-administered GB standards mandate rigorous safety testing for lithium-cell integrated portable luminaires. Dongguan fixture assemblers are pivoting toward higher-capacity lithium-polymer cell integration for professional-grade product lines.
India
Unelectrified rural households in Bihar and Uttar Pradesh drive alkaline-cell lantern demand through subsidized distribution programs. The Bureau of Indian Standards enforces safety protocols for battery-operated lighting products sold domestically. Mumbai-based trading houses coordinate import logistics for lithium cells sourced from East Asian suppliers.
Japan
Search-and-rescue units and disaster response agencies specify extended-runtime portable lighting for earthquake preparedness. METI oversees industrial standards for battery safety and energy efficiency in consumer electronics applications. Osaka-area electronics assemblers specialize in compact LED driver modules for premium portable fixtures.
Battery Operated Lights Market Vendor Landscape
Global majors compete with regional champions across certification expertise and channel access. The vendor base stratifies into three tiers: diversified electrical conglomerates with captive semiconductor divisions, specialized lighting fixture manufacturers with dedicated emergency product lines, and contract assemblers serving private-label retail programs. Dominant competitive moves include vertical integration into cell supply chains and geographic expansion through distributor acquisition.
Within the diversified electrical conglomerate tier, Schneider Electric SE and Eaton Corporation exemplify scale-driven positioning through smart-building compatibility and code-compliant emergency systems. Philips anchors the semiconductor-integrated segment through LED driver architecture control. Acuity Brands occupies a position in the specialized fixture tier with dedicated battery-backup product lines for commercial real estate portfolios.
| Leading Market Players |
|---|
| Philips |
| General Electric |
| Eaton Corporation |
| Legrand S.A. |
| Emerson Electric |
| Schneider Electric SE |
| Hubbell Lighting Inc. |
| Acuity Brands Inc. |
| Mr Beams |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between professional emergency fixtures and consumer portables manifests in both component sourcing and final pricing. Professional-grade lines absorb thermal runaway testing costs and multi-year warranty bundling through higher price tolerance, while commodity channels strip out service components to hit alkaline-cell price floors.
Pricing Analysis
Warranty and service bundling separates commercial emergency lighting from retail consumer products. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and runtime specifications. Price differentiation stems from UL-listed thermal protection tiers and volume procurement scale. Cost compression in consumer alkaline-cell segments intensifies because Dongguan contract assemblers compete on cell integration speed. Commercial facility managers show lowest price sensitivity due to code-compliance liability exposure.
Supply Chain Analysis
Lithium-polymer cell supply rests on Chinese cathode precursor refining in Hunan and Jiangxi provinces. Raw material dependencies include cobalt sulfate, lithium carbonate, and gallium-nitride LED substrates. Single-source vulnerability concentrates in Shenzhen and Dongguan fixture integration, where 70 percent of global cell-luminaire assembly occurs. Distribution runs through Dallas-Fort Worth disaster-response stockpiles for North American emergency deployment and Mumbai trading houses for Indian rural subsidy programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. China's GB standards and EU REACH substance restrictions create barrier-to-entry moats that favor incumbents with dedicated certification teams and qualified supplier networks.
For Market Incumbents: Extend service-contract penetration in US commercial real estate portfolios above 500,000 square feet to lock out distributor competition. Deepen backward integration into lithium-polymer cell supply through captive relationships with Hunan precursor refiners. Solid-state battery substitution threatens runtime advantages in premium professional lines. For New Entrants and Emerging Players: Solid-state battery chemistry offers a technology-first wedge into ultralight outdoor enthusiast segments where weight minimization commands premium pricing. Target Japanese mesh-networked portable task lamp demand through Bluetooth Low Energy platform partnerships. Rural Indian unelectrified households represent the most penetrable volume segment via subsidized alkaline-cell lantern distribution. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified electrical conglomerates seeking emergency lighting certification expertise. Long-term viability favors specialized fixture manufacturers with SAMR-compliant testing infrastructure and documented carbon footprints for EU CSRD procurement. Watch for lithium-cell thermal runaway incidents triggering regulatory acceleration as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Supply | Hunan precursor refining relationships secure lithium-polymer capacity for professional-grade runtime extension. |
| Smart Control Platform Partnership | Bluetooth mesh networking adoption in Japanese consumer segments expands margin pools through app ecosystems. |
| Multi-Year Service Contract Capture | Direct manufacturer relationships with US facility managers fragment traditional distributor channels. |
| REACH-Compliant Material Requalification | European substance restriction compliance extends product development timelines but locks out unqualified competitors. |
| Solid-State Battery Format Launch | Sub-2mm profile designs for ultralight backpackers compress traditional cylindrical flashlight geometries. |
Methodological Framework
Independent corroboration across fixture manufacturer executives, lithium-cell procurement leads, and commercial facility managers underwrites the qualitative findings. Primary interviews with SAMR certification specialists, EPA hazardous waste administrators, and German TÜV thermal testing engineers combined with secondary validation. Secondary sources include US Department of Energy appliance efficiency filings, ECHA REACH substance restriction updates, and Shenzhen customs export records. Bottom-up channel volume estimates and top-down macroeconomic triangulation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product technology tier, application use case, end-user category, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation against historical replacement cycle data. Industry-specific forecast inputs incorporate lithium-cell energy density improvement curves and efficiency mandate implementation schedules.
Several conditions sit outside the modeled scope, including abrupt lithium supply disruptions, solar home system substitution acceleration in sub-Saharan Africa, and emergency preparedness mandate revisions. Forecasts reflect documented assumptions about technology adoption rates and regulatory enforcement intensity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Industrial OLED Lighting Market
Lighting
Solid State Lighting System Market
Lighting
Indicator Lights Market
Lighting
Programmable Stage Lighting Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Solid-State Lighting Source Market
Lighting
COB Photo Light Market
Lighting
Solar Outdoor LED Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Global Work Lights Market
Lighting
Specialty Lighting Market
Lighting
Architectural Lighting Market
Lighting
Europe Lighting Control Systems Market
Lighting
Smart Lighting Market
Lighting
North America Street Lighting Market
Lighting
GCC Smart Lighting Market