
 Industrial Lighting Lifecycle Services Market | 2026-2036
Industrial Lighting Lifecycle Services Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lighting Lifecycle Services Market Insights
Asset-light lighting-as-a-service contracting is reconfiguring capital deployment across industrial facilities. Signify Holding leverages its Philips brand infrastructure to bundle installation with long-term energy management contracts. Acuity Brands anchors its position through deep control of specification channels in North American manufacturing plants. Eaton Corporation competes by extending its electrical distribution expertise into predictive maintenance offerings for hazardous-location fixtures.
Industrial lighting lifecycle services encompass the full technical stewardship of luminaire assets from initial photometric design through decommissioning, typically managing color temperatures of 4000K-5000K for task areas and maintaining illuminance levels per IES RP-7 for industrial environments. LED technology dominates current retrofit volumes while smart lighting systems represent the fastest-expanding margin pool as IoT-enabled controls shift pricing from hardware to recurring software layers. Maintenance services remain the most mature revenue category with predictable cash flows, whereas energy management contracts capture premium returns by guaranteeing measured kilowatt-hour reductions.
OSHA workplace illumination standards and the EPA Energy Star program shape baseline compliance requirements for US facilities, while the EU Ecodesign Directive and F-Gas Regulation drive accelerated replacement cycles for inefficient legacy systems across European industrial parks. Stakeholders must monitor how evolving building performance standards in multiple jurisdictions shift procurement criteria from upfront fixture cost to verified lifecycle operational expenditure.
Market Dynamics
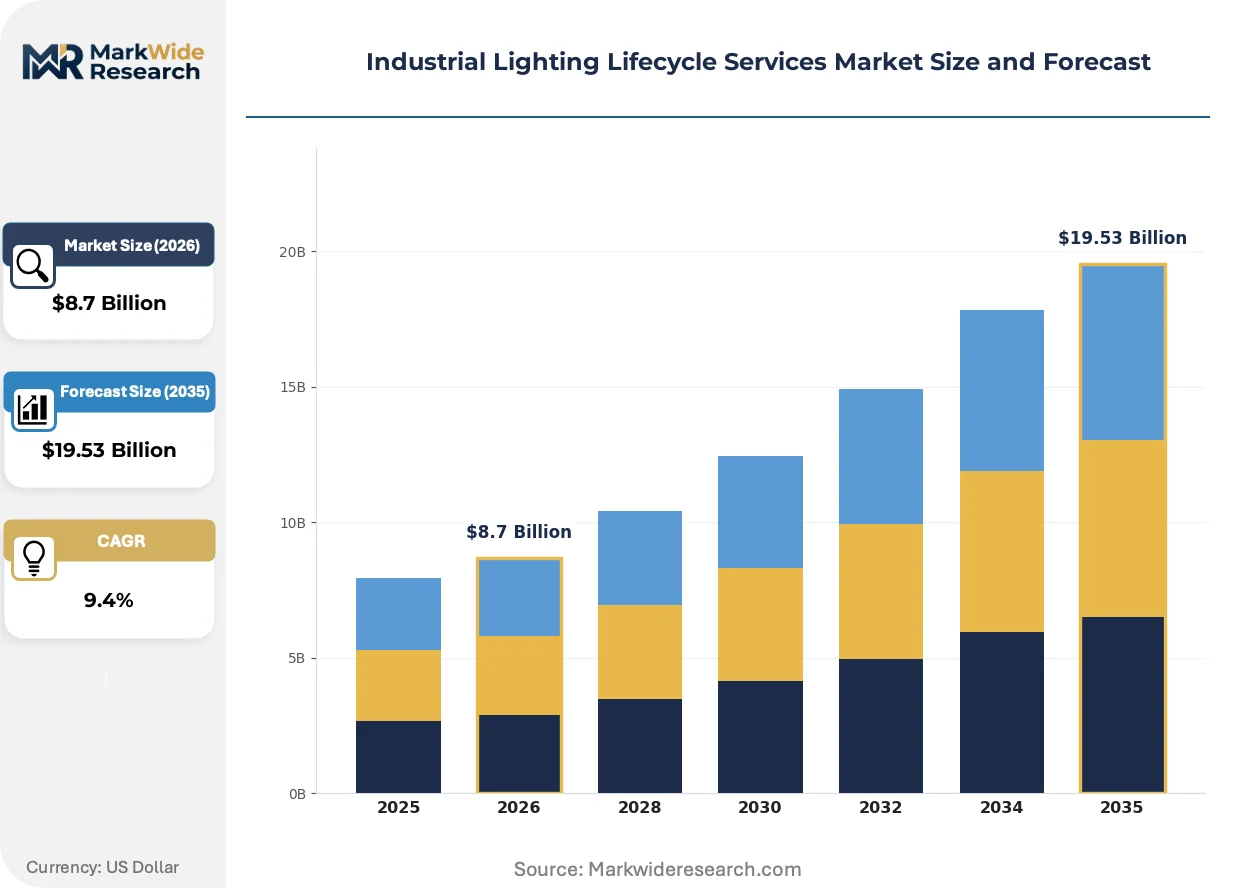
Asset-light service contracting is compressing capital cycles for industrial lighting assets, shifting facility managers from fixture ownership toward performance-guaranteed subscriptions that bundle hardware, installation, and ongoing technical stewardship into single operational expenditure lines.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Warehouse operators across Germany and the Netherlands are accelerating LED retrofit schedules to comply with tightening commercial building performance standards, expanding multi-year service agreements.
- Automotive manufacturing cluster density:Recurring maintenance contracts concentrate in the American Midwest where tier-one suppliers and OEM assembly plants require continuous illuminance compliance for precision assembly operations.
- IoT-enabled control convergence:Smart lighting systems with embedded sensors generate recurring software revenue streams, transforming vendor economics from hardware margins to subscription-based energy management layers.
Market Restraints
- Semiconductor input volatility:LED driver ICs and sensor microcontrollers face supply concentration risks from East Asian foundries, creating cost unpredictability for fixture manufacturers.
- Lithium battery chemistry constraints:Emergency lighting backup systems remain tethered to cell supply chains with raw material exposure to cobalt and nickel price swings.
- Legacy fluorescent disposal friction:The EPA's Universal Waste Rule and state-level mercury handling requirements impose compliance costs on decommissioning programs for high-bay installations.
Strategic Opportunities
- India industrial corridor expansion:The PLI scheme for manufacturing and dedicated freight corridor development create greenfield specification opportunities for lifecycle service providers entering underpenetrated heavy industry zones.
- Predictive maintenance algorithm deployment:Machine learning models applied to lumen depreciation curves and thermal degradation patterns enable preemptive relamping before catastrophic failure.
- CSRD disclosure requirements:European sustainability reporting mandates drive demand for verified energy reduction documentation, positioning lighting-as-a-service vendors as compliance infrastructure partners.
Industry Challenges
- IES RP-7 photometric certification bottlenecks:Qualified lighting designers capable of industrial illuminance calculations remain scarce relative to retrofit project pipelines, extending design-phase timelines.
- Legacy control protocol fragmentation:Integration complexity between proprietary building management systems and new wireless mesh networks demands specialized commissioning expertise that strains field engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lighting Lifecycle Services Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Retrofit, Inspection, Energy Management Application: Manufacturing Facilities, Warehouses, Transportation Hubs, Agricultural Sites, Data Centers End User Industry: Manufacturers, Logistics Operators, Farmers, IT Infrastructure Providers, Mining Companies Technology: LED, Fluorescent, High-Intensity Discharge, Induction, Smart Lighting |
| Companies Covered | Signify Holding, Acuity Brands, Eaton Corporation, Hubbell, Zumtobel Group, Legrand, Emerson Electric, Trilux, Glamox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lighting Lifecycle Services Market Trends and Innovations
Digital service layers are displacing hardware-centric business models across industrial lighting, reconfiguring vendor-customer relationships around measured outcomes rather than product shipments.
Human-centric lighting is migrating from circadian research facilities into 24-hour manufacturing operations. Automotive plants in Michigan and Ohio are adopting tunable white LED systems that shift color temperature across shifts to maintain alertness. This technology is migrating from premium office installations into cost-sensitive industrial environments as sensor costs decline and energy management platforms standardize spectral control.
The EU F-Gas Regulation is accelerating phase-out timelines for mercury-containing lamps across industrial parks in Belgium and northern France. Facility managers face compressed replacement windows that favor turnkey service contracts over capital procurement cycles. German chemical processors are responding by bundling hazardous-location fixture upgrades with long-term maintenance agreements to transfer regulatory compliance risk.
Specification influence is consolidating around electrical contractors with energy performance contracting capabilities. Industrial buyers in Texas and Louisiana now delegate photometric design and ongoing optimization to installation partners rather than maintaining in-house lighting expertise. This pattern is most visible in oil and gas processing facilities where operational priorities favor single-vendor accountability over fragmented supply relationships.
Industrial Lighting Lifecycle Services Market Segmentation
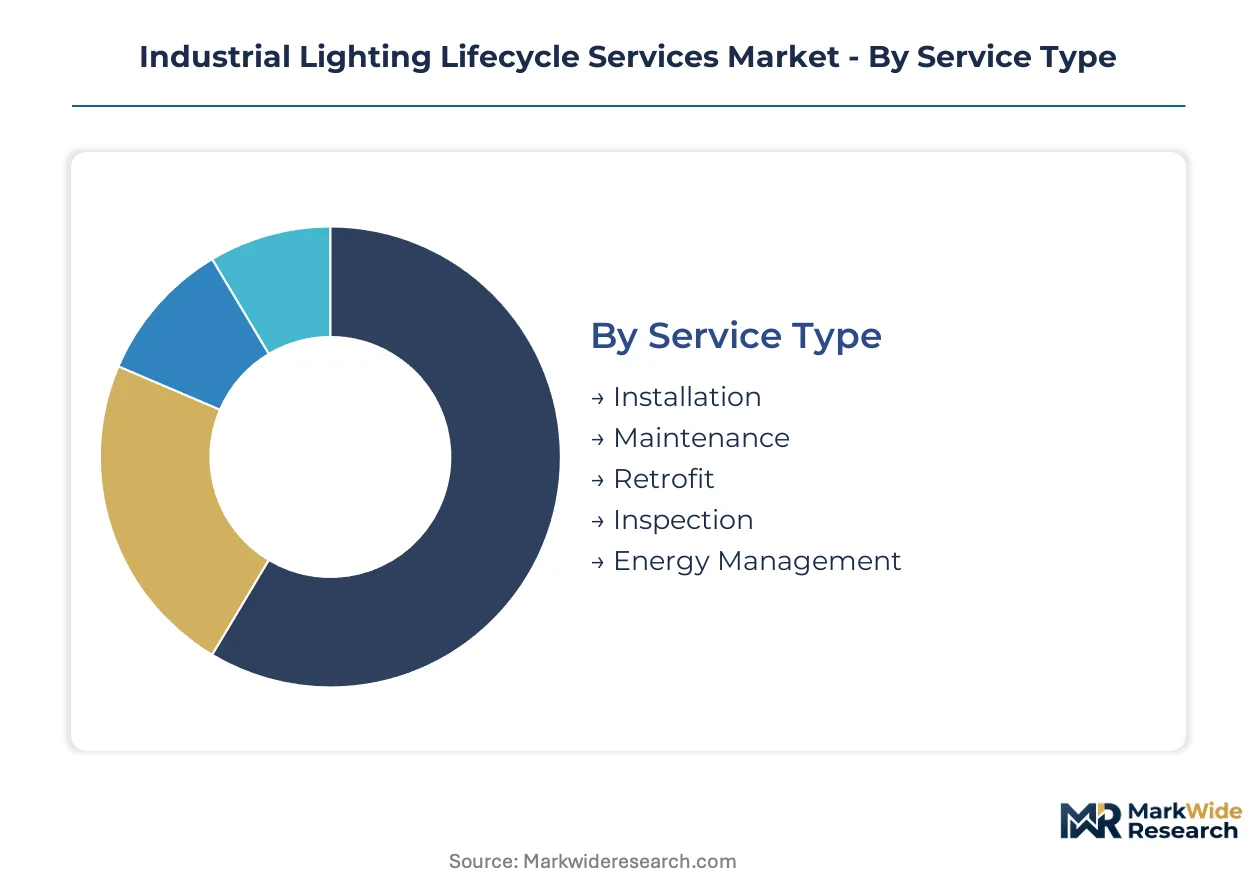
Service differentiation in industrial lighting lifecycle markets determines contract duration, margin profile, and customer stickiness. Procurement patterns diverge sharply between capital-intensive retrofit programs and recurring operational maintenance agreements.
Service Type:
Maintenance contracts turn over fastest with monthly or quarterly billing cycles, while energy management agreements lock in decade-long performance commitments. Installation and retrofit services occupy intermediate positions with project-based revenue recognition.
- Installation:Covers initial luminaire deployment including photometric layout, electrical termination, and commissioning verification against IES RP-7 standards. German automotive plants in Bavaria and Baden-Württemberg drive concentrated demand as OEMs expand electric vehicle assembly capacity.
- Maintenance:Encompasses scheduled relamping, driver replacement, and illuminance auditing to sustain OSHA compliance. American Midwest manufacturing clusters generate the densest contract density where tier-one suppliers require continuous uptime guarantees for precision assembly lines.
- Retrofit:LED conversion of legacy fluorescent and HID systems with waste handling under EPA Universal Waste Rule protocols.
- Inspection:Periodic compliance auditing against workplace illumination standards and hazardous-location certification requirements.
- Energy Management:Performance-contracting structures guaranteeing measured kilowatt-hour reductions with shared savings mechanisms.
Maintenance anchors the volume base while energy management gains share at the steepest rate.
Application:
Cost tiering separates mission-critical environments with 24/7 uptime requirements from seasonal or intermittent-use facilities where lighting loads fluctuate.
- Manufacturing Facilities:Continuous-process environments demanding color temperature stability between 4000K-5000K for defect detection. Michigan and Ohio automotive plants are adopting tunable white systems that shift spectral output across shifts to maintain worker alertness.
- Warehouses:High-bay installations with motion-activated controls and daylight harvesting algorithms. Dutch and German distribution centers are accelerating LED retrofits ahead of EU Green Deal tightening on commercial building performance standards.
- Transportation Hubs:Airports, rail terminals, and port facilities requiring emergency backup systems with lithium battery chemistry.
- Agricultural Sites:Poultry and greenhouse operations with extended photoperiod controls and humidity-resistant fixture specifications.
- Data Centers:Aisle-specific task lighting with minimal heat generation to reduce cooling loads on server environments.
Warehouses concentrate procurement volume while manufacturing facilities command premium pricing through technical complexity.
End User Industry:
Customer type determines contract structure, with asset-heavy operators preferring ownership models and capital-constrained users gravitating toward lighting-as-a-service subscriptions.
- Manufacturers:Continuous-process industrial operators with internal maintenance capabilities and preference for performance-guaranteed energy contracts.
- Logistics Operators:Third-party warehouse and fulfillment providers with standardized facility portfolios favoring turnkey service bundles over fragmented procurement.
- Farmers:Seasonal cash-flow patterns driving demand for subscription-based models that convert capital expenditure to operational expenditure.
- IT Infrastructure Providers:Hyperscale data center operators with in-house engineering teams and preference for direct fixture procurement with minimal service overlay.
- Mining Companies:Hazardous-location requirements with specialized explosion-proof fixture specifications and stringent relamping protocols.
Logistics operators are consolidating vendor relationships fastest while mining companies retain the most fragmented procurement patterns.
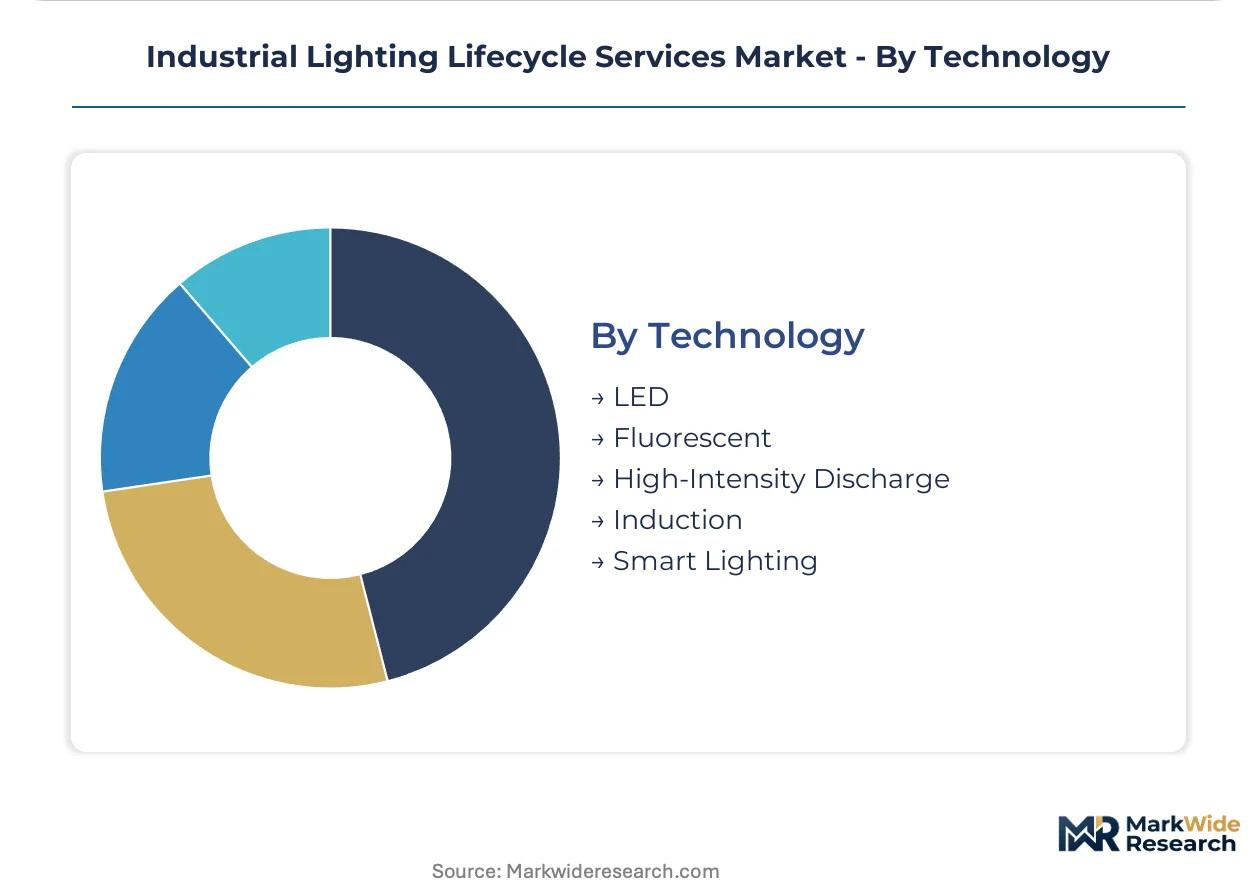
Technology:
Technology maturity separates legacy systems in replacement phase from emerging platforms still accumulating field reliability data.
- LED:Dominant technology with driver IC supply concentration in East Asian foundries creating input cost volatility. Current retrofit volumes concentrate in EU industrial parks facing F-Gas Regulation accelerated phase-out timelines.
- Smart Lighting:IoT-enabled controls with embedded sensors generating recurring software revenue streams. Texas and Louisiana oil and gas processors are delegating specification authority to electrical contractors with energy performance contracting capabilities.
- Fluorescent:Legacy systems with mercury content triggering disposal friction under EPA Universal Waste Rule and state-level handling requirements.
- High-Intensity Discharge:Metal halide and high-pressure sodium systems with long lumen depreciation curves but poor instant-restart characteristics.
- Induction:Electrodeless lamp technology with extended lifespan claims but limited specification channel presence.
LED commands the installed base while smart lighting platforms are climbing the fastest through new specification channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial lighting lifecycle services trade flows reflect divergent retrofit maturity across major economies. The United States maintains net service export capacity through specialized energy performance contracting expertise. Germany and China import technical design capabilities while building domestic installation scale.
United States
OSHA workplace illumination standards and EPA Energy Star certification drive compliance spending across manufacturing facilities. The Inflation Reduction Act tax incentives accelerate LED retrofit adoption in industrial parks. Michigan and Ohio automotive plants generate dense maintenance contract clusters for precision assembly operations requiring continuous illuminance guarantees.
Germany
EU Green Deal energy efficiency mandates compress replacement timelines for legacy fluorescent systems in warehouse and chemical processing facilities. The F-Gas Regulation accelerates mercury-containing lamp phase-outs across industrial parks. Bavarian automotive OEMs expanding electric vehicle assembly capacity drive concentrated demand for photometric design and commissioning services.
China
Dual carbon goals and GB standards for building energy efficiency expand LED retrofit volumes in coastal manufacturing zones. The Ministry of Ecology and Environment enforces accelerated decommissioning of mercury-based lighting. Yangtze River Delta industrial corridors generate specification demand for smart lighting systems with IoT-enabled energy management platforms.
India
PLI scheme incentives for manufacturing and dedicated freight corridor development create greenfield installation opportunities in underpenetrated heavy industry zones. Bureau of Indian Standards certification requirements shape procurement criteria for industrial luminaires. Maharashtra and Gujarat industrial belts concentrate early maintenance contract formation as foreign lifecycle service providers establish local partnerships.
Netherlands
EU Ecodesign Directive tightening on commercial building performance standards accelerates LED conversion in distribution centers serving European logistics networks. The national sustainable building certification framework rewards verified operational expenditure reductions. Rotterdam port facilities and Eindhoven-region high-tech manufacturing drive demand for hazardous-location fixture upgrades bundled with long-term technical stewardship agreements.
Industrial Lighting Lifecycle Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower specification influence. The vendor base organizes around three tiers: diversified electrical conglomerates with energy management platforms, pure-play lighting specialists with deep photometric expertise, and regional installation contractors consolidating specification authority. Consolidation pressure intensifies as facility managers delegate accountability to single-vendor partners. Competitive moves cluster on strategic partnerships between fixture manufacturers and electrical contractors, plus geographic expansion through acquisition of local commissioning capabilities.
Among diversified electrical conglomerates, Signify Holding and Eaton Corporation exemplify platform-scale positioning with bundled hardware-installation-service offerings. Acuity Brands occupies a position within the specification-channel tier, anchoring influence through control of North American industrial plant design flows. These three entities represent distinct archetypes: the Dutch-integrated energy management platform, the American electrical distribution-extended service provider, and the specification-channel specialist respectively.
| Leading Market Players |
|---|
| Signify Holding |
| Acuity Brands |
| Eaton Corporation |
| Hubbell |
| Zumtobel Group |
| Legrand |
| Emerson Electric |
| Trilux |
| Glamox |
| Others |
Pricing and Supply Chain Analysis
East Asian foundry clusters in Taiwan and South Korea concentrate LED driver IC and sensor microcontroller production, granting upstream suppliers substantial leverage over fixture manufacturers negotiating annual contract renewals. This supply concentration compresses margins for lighting-as-a-service providers bundling hardware with long-term energy management subscriptions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels based on certification grade and after-sales service bundling. Premium tiers command spreads for UL-certified hazardous-location fixtures with predictive maintenance algorithms, while economy tiers serve price-sensitive warehouse operators in India accepting basic LED retrofits without IoT controls. Cost compression in the standard tier is intensifying because German automotive plants are consolidating vendor relationships and demanding volume discounts for multi-facility rollouts.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows to Chinese foundries are reshaping component sourcing strategies for lighting OEMs. Taiwan, South Korea, and Japan concentrate LED epitaxy wafer and driver IC production, drawing from gallium nitride substrates and rare earth phosphor dependencies. Single-source vulnerability persists for automotive-grade microcontrollers with extended temperature ratings. Distribution runs through authorized electrical distributor networks in North America and direct OEM relationships in European industrial parks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where interoperability between proprietary building management systems and wireless mesh networks determines vendor lock-in potential. The shift from hardware shipments to recurring software revenue layers rewards ecosystem orchestrators over component specialists.
For Market Incumbents: Insulate specification channel control by acquiring regional electrical contractors with energy performance contracting capabilities in the American Midwest and Germany. Deepen backward integration into LED driver IC design to reduce exposure to East Asian foundry pricing volatility. Prioritize certification investment for CSRD disclosure tooling to capture compliance infrastructure partnerships with European chemical processors.
For New Entrants and Emerging Players: Build out commissioning expertise for legacy control protocol integration, targeting Indian industrial corridors where PLI scheme manufacturing expansion outpaces qualified lighting designer supply. Focus on Maharashtra and Gujarat greenfield facilities where foreign lifecycle service providers lack established local partnerships. Deploy machine learning-based predictive maintenance algorithms as a differentiated entry wedge against hardware-centric incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because lighting-as-a-service contracts generate decade-long operational expenditure streams with high switching costs. Target acquisition profiles emphasizing electrical contractors with embedded specification influence in automotive manufacturing clusters. Monitor IoT-enabled control convergence rates as the inflection signal indicating which vendors have successfully shifted from transactional hardware margins to subscription-based energy management layers.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Electrical contractors with energy performance contracting capabilities capture specification authority in Texas oil and gas facilities. |
| Platform Integration | Interoperability between wireless mesh networks and proprietary building management systems reduces customer switching propensity. |
| Geographic Expansion | Local commissioning capabilities in Indian industrial corridors address qualified lighting designer scarcity relative to retrofit pipelines. |
| Strategic Partnership | Collaboration with semiconductor foundries secures automotive-grade microcontroller supply for hazardous-location fixture lines. |
| Product Launch | CSRD disclosure tooling positions vendors as compliance infrastructure partners for European sustainability reporting mandates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association reports covering the industrial lighting sector. Primary interviews engaged facility managers at German automotive plants, maintenance directors in Michigan manufacturing clusters, procurement leads at Dutch logistics operators, and specification engineers at Texas oil and gas processors. Secondary validation drew from OSHA workplace illumination standards documentation, EPA Energy Star certification databases, EU Ecodesign Directive implementation guidance, and SEC filings from diversified electrical conglomerates. Bottom-up service contract value estimates triangulated against top-down market size assessments.
Forecast inputs span service type segmentation across installation, maintenance, retrofit, inspection, and energy management agreements, plus technology tiering between LED, smart lighting, and legacy fluorescent systems. End-use industry differentiation separates continuous-process manufacturers from seasonal agricultural operators with distinct cash-flow patterns. CAGRs were derived through driver elasticity modeling against regulatory mandate timelines and replacement cycle compression effects. Industry-specific inputs include IES RP-7 photometric compliance cost curves and F-Gas Regulation phase-out velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive platform integration moves by pure-play lighting specialists or electrical distributor conglomerates would shift outcomes. Material shifts in semiconductor export-control regime stringency, lithium battery raw material price trajectories, or EU building performance standard enforcement velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Global Headlight Control Module Market
Lighting
Human Centric Lighting Market
Lighting
North America Street Lighting Market
Lighting
Portable Lamps Market
Lighting
Bulb Market
Lighting
South America Outdoor LED Lighting Market
Lighting
Recessed Lighting Market
Lighting
Ultra Violet (UV) Lamps Market
Lighting
Specialty Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Global Work Lights Market
Lighting
North America Smart Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Industrial Lighting Market
Lighting
Battery Operated Lights Market
Lighting
Global Plasma Lamp Market