
 Solar Rope Light Market | 2026-2036
Solar Rope Light Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Rope Light Market Insights
Skilled photovoltaic assembly labor is rotating toward flexible lighting manufacturers as solar module costs decline and consumer demand diversifies. Jiawei Solar Lighting Co., Ltd. leverages integrated cell-to-assembly operations to control input costs across long LED strip runs. Philips Lighting sustains brand recognition in premium outdoor segments through channel partnerships with home improvement retailers. SEPCO anchors municipal procurement channels with heavy-duty solar rope configurations engineered for public pathway installations.
Solar rope light denotes a flexible, weather-sealed linear luminaire incorporating photovoltaic cells, rechargeable battery storage, and solid-state LED emitters arranged along a polymer substrate, typically rated between 12 V and 24 V DC for safe outdoor deployment. The assembly serves decorative and functional illumination in gardens, patios, and commercial landscapes without grid connection. LED product types dominate unit economics due to lumen-per-watt efficiency and extended cycle life under daily charge-discharge stress. Application demand tilts toward outdoor decoration as consumers prioritize ambient aesthetics over pure utility, though pathway illumination commands higher per-meter pricing through reinforced jacketing and ground-mount hardware.
EPA Energy Star guidelines and EU RoHS substance restrictions shape material selection and efficiency claims across export-bound production. CE marking and REACH compliance create tiered market access, with certified suppliers occupying retail shelf space in European markets while uncertified competitors remain confined to direct-to-consumer e-commerce. Stakeholders must monitor evolving battery chemistry regulations, as lithium-ion transport classifications and end-of-life directives increasingly influence supply chain design and regional fulfillment strategies.
Market Dynamics
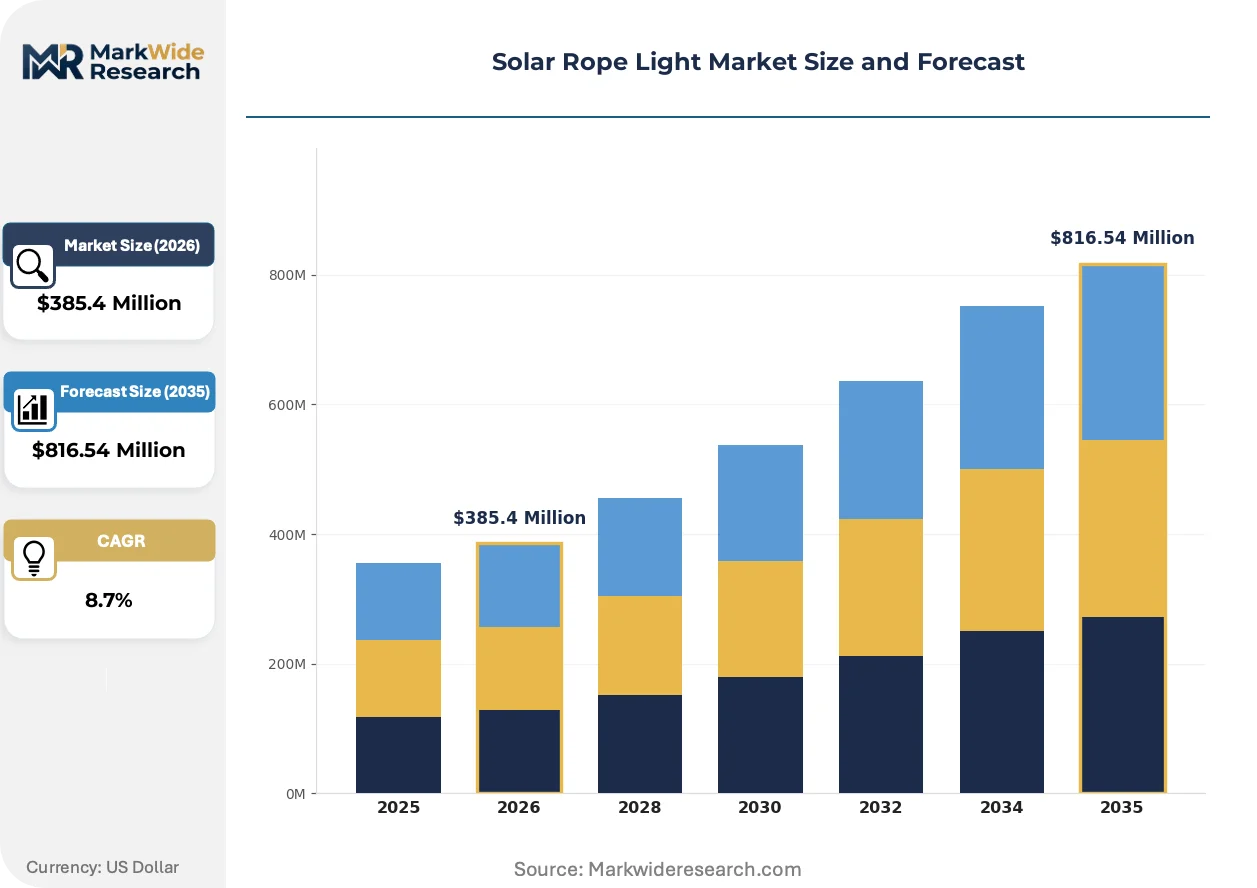
The solar rope light market is being reshaped by the convergence of declining photovoltaic module costs and tightening European energy efficiency mandates, which together compress payback periods for residential and municipal buyers while fragmenting competitive advantage across integrated versus modular supply chains.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants in conventional outdoor lighting systems accelerates displacement by solar-powered alternatives in German and French municipal procurement.
- Residential garden renovation:Post-pandemic outdoor living investment in suburban United States and Australian markets drives replacement of grid-tied string lighting with autonomous solar configurations.
- Lithium iron phosphate chemistry:Improved cycle stability under daily deep discharge conditions extends product lifespan and reduces warranty claims for manufacturers targeting premium outdoor decoration segments.
Market Restraints
- Polysilicon supply concentration:Refining and ingot production clusters in Xinjiang create input cost volatility and due diligence complications for Western brands seeking clean supply chain certification.
- Battery transport classification:UN 38.3 lithium-ion testing requirements and IATA shipping restrictions inflate logistics costs and complicate cross-border e-commerce fulfillment for direct-to-consumer sellers.
- Seasonal irradiance mismatch:Northern European latitudes experience extended winter charge deficits that degrade user experience and elevate return rates for entry-tier products with undersized PV arrays.
Strategic Opportunities
- Indian smart city mandates:AMRUT 2.0 urban renewal funding creates procurement channels for solar pathway lighting in Tier-2 municipal corporations seeking grid-independent public infrastructure.
- Agrivoltaic integration:Dual-use solar rope configurations for greenhouse supplemental lighting and crop monitoring represent an emerging application with premium pricing potential in Dutch horticulture.
- Home improvement retail partnerships:Dedicated aisle placement and seasonal promotional calendars at Lowe's, Bunnings, and Leroy Merlin accelerate consumer education and trial conversion versus pure online discovery.
Industry Challenges
- Photovoltaic assembly technician scarcity:Competition from electric vehicle and utility-scale solar manufacturers drains experienced labor from flexible lighting producers in Guangdong and Zhejiang manufacturing clusters.
- CE marking timeline compression:Evolving EN 60598-2-1 safety standards and updated EMC directives extend certification cycles by four to six months, delaying seasonal product launches.
- Interoperability fragmentation:Proprietary app ecosystems and non-standard wireless protocols from major smart home platforms complicate integration for mid-tier manufacturers lacking dedicated software engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Rope Light Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Neon, Incandescent, Fiber Optic Application: Outdoor Decoration, Landscape Lighting, Event Lighting, Pathway Illumination Power Source: Solar, Battery, Plug-in, Hybrid Length: 10 Feet, 20 Feet, 50 Feet, 100 Feet |
| Companies Covered | Jiawei Solar Lighting Co., Ltd., Philips Lighting, Ring, Greenshine New Energy, Gama Sonic, SEPCO, Sunna Design, Bajaj Electricals Limited, Crompton Greaves Consumer Electricals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Rope Light Market Trends and Innovations
Product architecture and buyer expectations are diverging as solar rope lighting evolves from decorative novelty toward functional infrastructure, with three distinct vectors reshaping competitive positioning and value capture across the supply chain.
Perovskite-silicon tandem cell research is fragmenting the efficiency frontier for flexible photovoltaic substrates, enabling higher energy harvest per unit surface area in diffuse light conditions. Residential buyers in cloudy maritime climates are prioritizing these advanced configurations despite 40-60% price premiums over conventional monocrystalline alternatives. The technology is fragmenting manufacturer R&D budgets between incremental silicon optimization and next-generation thin-film development.
REACH substance restrictions and updated RoHS thresholds are forcing reformulation of solder alloys and encapsulant polymers across export-bound production lines. Suppliers serving European retail channels are absorbing compliance costs through specification engineering rather than price increases, compressing margins for non-integrated assemblers. German garden center chains and French hypermarket buyers are now requiring full material disclosure documentation as a condition of shelf access.
Subscription-based lighting-as-a-service models are emerging in commercial landscape maintenance, with facility management firms outsourcing hardware refresh and battery replacement cycles to specialist providers. This displaces capital purchase patterns among hospitality and retail property portfolios in California and Florida. The shift is most visible in resort and hotel verticals where aesthetic consistency and uptime guarantees override ownership preferences.
Solar Rope Light Market Segmentation
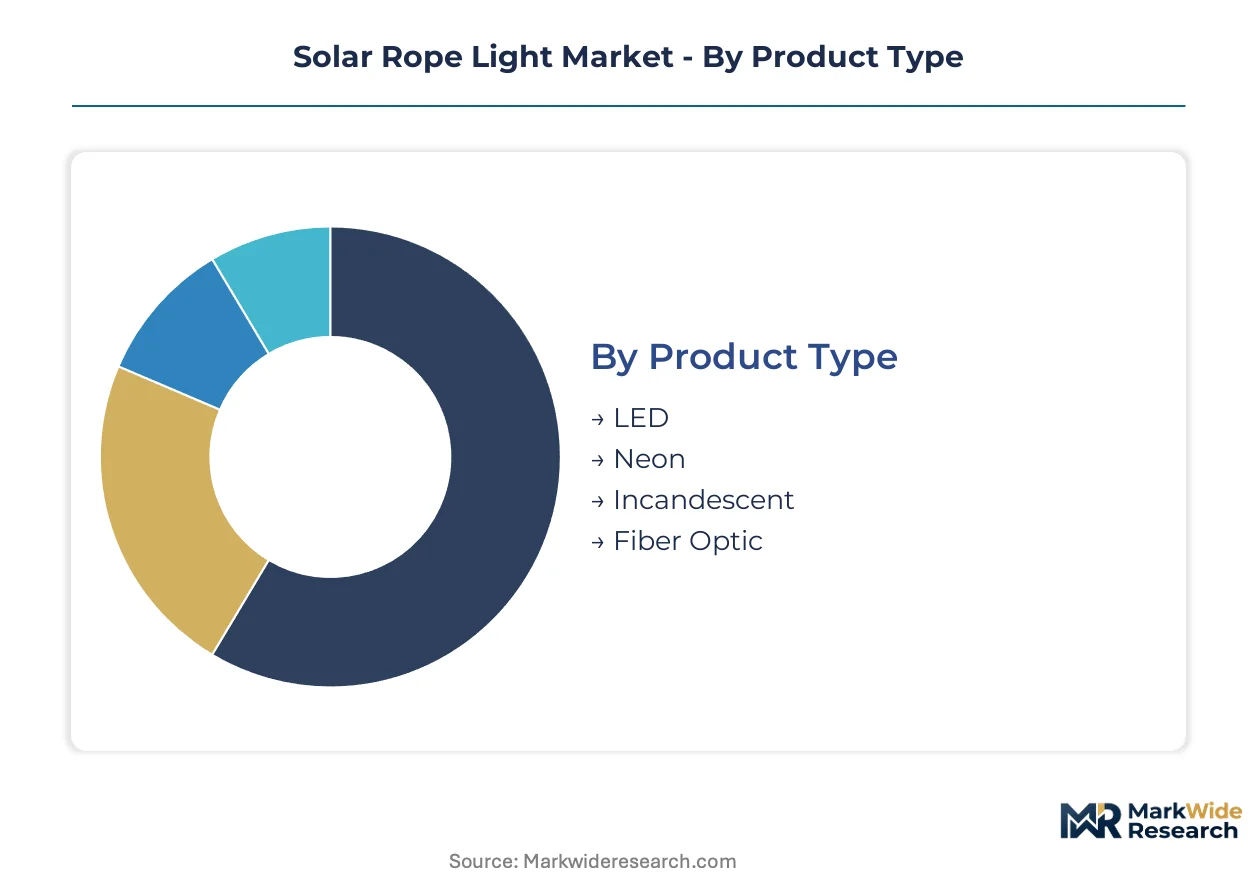
Solar rope light purchasing decisions fragment across technical specifications and deployment contexts. Regulatory thresholds for outdoor electrical safety and energy efficiency reshape which configurations qualify for municipal procurement versus residential retail channels.
Product Type:
EU RoHS substance restrictions and EPA Energy Star guidelines create divergent compliance burdens across emitter technologies, with certified variants commanding shelf placement in regulated markets.
- LED:Solid-state emitters on flexible polymer substrates deliver 80-120 lumens per watt with 50,000-hour rated lifespans. German garden centers and French hypermarkets prioritize these for residential outdoor decoration under REACH-compliant supply chains. CE marking requirements favor LED configurations for European retail penetration.
- Neon:Elastomer-sheathed electroluminescent strips produce continuous 360-degree glow without discrete diode visibility. Event lighting specialists in California and Florida specify these for hospitality installations where aesthetic continuity overrides pure efficiency metrics.
- Incandescent:Tungsten filament technology persists in price-sensitive direct-to-consumer channels lacking efficiency mandates.
- Fiber Optic:Side-emitting polymer fibers enable intricate routing through water features and landscape contours without electrical conductivity at termination points.
LED handles the majority of throughput; Neon is expanding most quickly on share.
Application:
End-use economics determine hardware reinforcement levels and battery sizing, with pathway installations requiring ground-mount anchoring and crush-resistant jacketing that decorative deployments omit.
- Outdoor Decoration:Ambient perimeter lighting for residential patios and balconies emphasizes color temperature consistency and app-controlled dimming. Australian suburban renovation demand concentrates here, with Bunnings and Lowe's seasonal promotions driving trial conversion. Lithium iron phosphate chemistry extends cycle life for daily charge-discharge stress.
- Pathway Illumination:Reinforced polymer jackets with IP67 ingress protection and ground stakes for soil anchoring. Municipal procurement in German cities favors these for public park installations under EU Green Deal funding, with per-meter pricing premiums reflecting durability specifications.
- Landscape Lighting:Concealed uplighting and tree-wrapping configurations for commercial property maintenance contracts.
- Event Lighting:Temporary deployment with rapid installation hardware for festival and wedding rental markets.
Outdoor Decoration captures the dominant revenue position; Pathway Illumination shows the steepest expansion trajectory.
Power Source:
Autonomy levels determine addressable market scope, with grid-independent configurations qualifying for F-Gas Regulation displacement incentives in European municipal tenders.
- Solar:Integrated photovoltaic cells with rechargeable battery storage eliminate cabling infrastructure. Indian AMRUT 2.0 smart city mandates specify these for Tier-2 municipal pathway projects. UN 38.3 lithium-ion testing requirements complicate cross-border fulfillment for direct-to-consumer sellers.
- Battery:Removable cell packs for seasonal use patterns where permanent solar mounting is impractical.
- Plug-in:Grid-dependent configurations retain share in permanent residential installations with reliable outdoor receptacle access.
- Hybrid:Dual-input architecture switching between solar and grid charging based on irradiance availability.
Solar dominates unit economics; Hybrid is gaining share fastest among commercial landscape portfolios.
Length:
Standardized spool dimensions align with retail packaging constraints and installation labor efficiency, with longer runs requiring voltage drop compensation and reinforced conductor gauges.
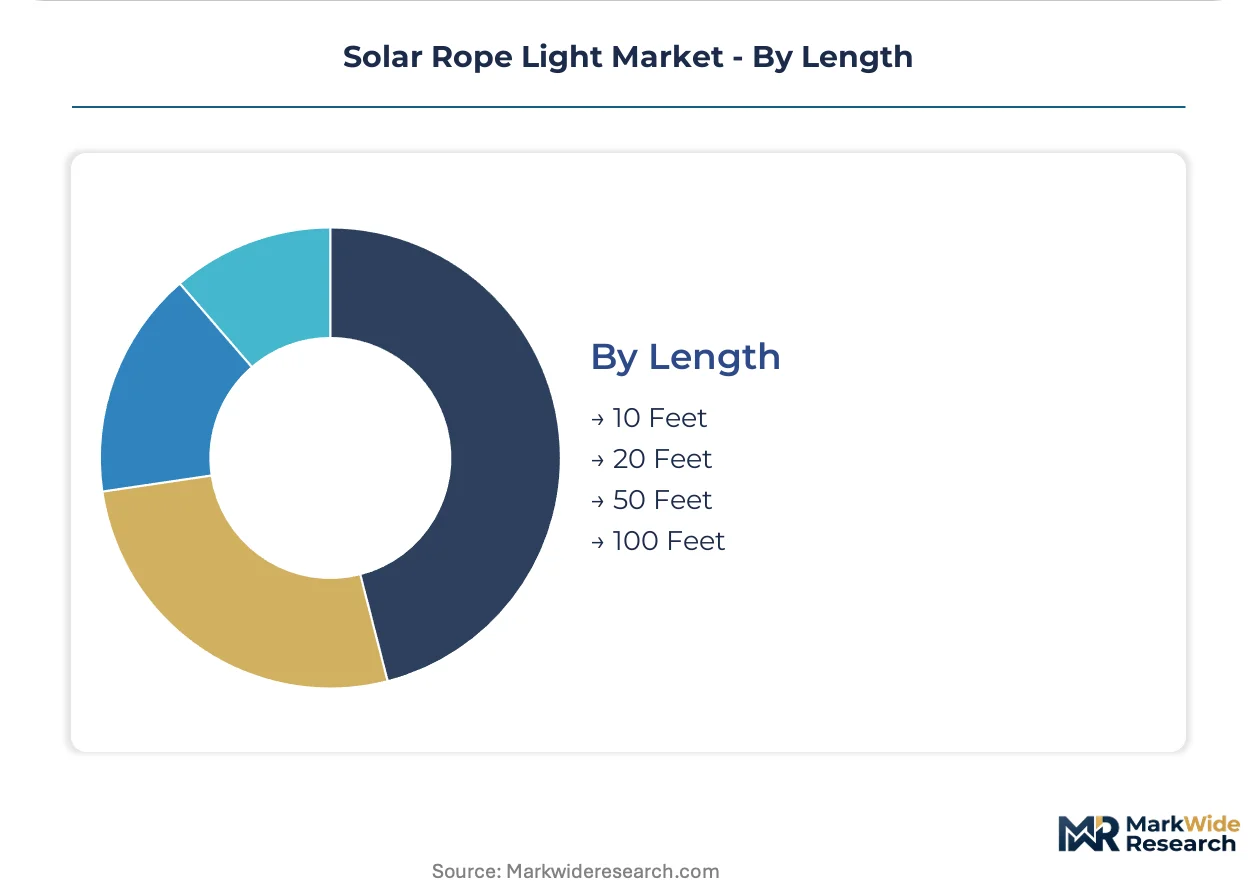
- 50 Feet:Mid-scale spools balance coverage area with handling logistics for residential garden perimeter installations. Dutch horticulture greenhouse operators specify these for supplemental crop lighting in agrivoltaic configurations. Perovskite-silicon tandem cell research enables higher harvest density per unit surface area.
- 100 Feet:Extended runs with parallel conductor architecture for commercial property boundaries and municipal pathway networks. California resort maintenance contracts favor these for lighting-as-a-service subscription models where capital ownership shifts to specialist providers.
- 10 Feet:Compact spools for balcony railing and small patio accent applications.
- 20 Feet:Intermediate coverage for single-feature highlighting in residential settings.
50 Feet handles the majority of throughput; 100 Feet is climbing the fastest on volume contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU F-Gas Regulation anchors European procurement patterns for solar rope lighting, with German municipal tenders setting technical specifications that ripple through adjacent markets. National energy efficiency mandates and outdoor living investment cycles determine adoption velocity across major economies.
Germany
EU Green Deal funding accelerates public pathway installations in Berlin and Hamburg municipal parks. The F-Gas Regulation phases out hydrofluorocarbon-dependent conventional lighting, displacing grid-tied fixtures with autonomous solar configurations. Bavarian manufacturing clusters supply reinforced jacketing and ground-mount hardware for heavy-duty municipal specifications.
United States
Post-pandemic suburban renovation in California and Florida drives replacement of grid-tied string lighting with autonomous solar configurations. EPA Energy Star guidelines shape efficiency claims for retail-bound production. Home improvement retail partnerships in the Southeast concentrate seasonal promotional calendars and consumer education programs.
India
AMRUT 2.0 urban renewal funding creates procurement channels for solar pathway lighting in Tier-2 municipal corporations. BIS certification requirements and state-level smart city mandates prioritize grid-independent public infrastructure. Maharashtra and Gujarat manufacturing hubs assemble integrated photovoltaic cells for domestic and export-bound production.
Australia
Suburban garden renovation demand concentrates in New South Wales and Victoria, with Bunnings seasonal promotions driving trial conversion for residential outdoor decoration. The country's national energy regulator emphasizes lithium-ion transport classifications for cross-border e-commerce fulfillment. Queensland horticulture operators experiment with agrivoltaic supplemental lighting configurations.
Netherlands
Dutch greenhouse operators pioneer dual-use solar rope configurations for crop monitoring and supplemental lighting in agrivoltaic installations. REACH substance restrictions and RoHS thresholds force reformulation of encapsulant polymers across export-bound production lines. Eindhoven-region technical universities collaborate with manufacturers on perovskite-silicon tandem cell research for diffuse light conditions.
Solar Rope Light Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the solar rope light supply chain. The vendor base fragments between integrated cell-to-assembly operators controlling input costs and modular assemblers dependent on spot-market photovoltaic procurement. Three strategic archetypes dominate: vertically integrated Chinese manufacturers, European premium brands leveraging channel partnerships, and municipal-focused specialists engineering heavy-duty public infrastructure configurations. Competitive moves concentrate on backward integration into photovoltaic cell production and strategic partnerships with home improvement retail chains.
Among Asia-Pacific-based fabricators, Jiawei Solar Lighting Co., Ltd. exemplifies integrated manufacturing archetypes with captive supply of core components. Philips Lighting occupies a position within premium-tier outdoor segments through established retail channel relationships. SEPCO anchors the municipal procurement specialist archetype, engineering configurations for public pathway durability requirements. These three represent distinct competitive vectors rather than direct substitutes, with each sitting within non-overlapping buyer segments and technical specification tiers.
| Leading Market Players |
|---|
| Jiawei Solar Lighting Co., Ltd. |
| Philips Lighting |
| Ring |
| Greenshine New Energy |
| Gama Sonic |
| SEPCO |
| Sunna Design |
| Bajaj Electricals Limited |
| Crompton Greaves Consumer Electricals Limited |
| Others |
Pricing and Supply Chain Analysis
Lithium iron phosphate chemistry displacing lithium cobalt oxide in battery packs simultaneously shifts procurement geography toward Chinese cathode manufacturers and compresses per-unit battery costs by fifteen to twenty percent for premium solar rope configurations. This substitution dynamic reshapes margin structures across tiered product lines as manufacturers absorb chemistry transitions into specification engineering rather than price increases.
Pricing Analysis
Per-meter pricing spreads fifty to seventy percent between German retail shelves and direct-to-consumer e-commerce channels serving Southeast Asian markets. Three-tier pricing structure across premium, standard, and economy levels dominates, with CE marking and REACH-compliant material disclosure separating premium tiers from uncertified economy alternatives. Cost compression in economy segments intensifies as Xinjiang polysilicon volatility feeds through to module pricing. Municipal procurement in Berlin and Hamburg shows lowest price sensitivity due to EU Green Deal funding availability, while Australian residential buyers through Bunnings seasonal promotions exhibit highest elasticity.
Supply Chain Analysis
China and Vietnam anchor photovoltaic cell and flexible polymer substrate production, with Guangdong and Zhejiang manufacturing clusters supplying integrated cell-to-assembly operations. Polysilicon ingots, lithium iron phosphate cathode powder, and IP67-rated polymer jacketing materials draw from concentrated upstream sources. Single-source vulnerability in Xinjiang polysilicon refining creates due diligence complications for Western brands seeking clean supply chain certification. Distribution runs through home improvement retail partnerships in developed markets and direct-to-consumer e-commerce in price-sensitive regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from smart home platform ecosystems integrating lighting control into proprietary app architectures, requiring defensive positioning around interoperability and standalone functionality.
For Market Incumbents: Shield core revenue in municipal procurement channels by accelerating CE marking timeline management and pre-positioning inventory ahead of seasonal demand windows. Prioritize backward integration into lithium iron phosphate battery pack assembly to offset module cost volatility and warranty claim exposure from charge-cycle degradation. Counter smart home platform substitution by maintaining open-protocol compatibility with major home automation standards.
For New Entrants and Emerging Players: BIS certification fast-track for Indian AMRUT 2.0 municipal tenders opens procurement access in Tier-2 cities with limited incumbent presence. Target agrivoltaic greenhouse lighting in Dutch horticulture as the most penetrable premium segment, where technical collaboration with Eindhoven-region research institutions substitutes for brand recognition. Pursue lighting-as-a-service subscription models in California and Florida resort portfolios to bypass upfront capital competition with established hardware suppliers.
For Investors and Strategic Acquirers: EU F-Gas Regulation phasedown completion reshapes the acquisition landscape by eliminating conventional lighting alternatives and locking in solar displacement trajectory across European municipal budgets. Five-to-ten year viability favors vertically integrated manufacturers with captive photovoltaic cell production and established retail channel partnerships. Monitor perovskite-silicon tandem cell commercialization timelines as the critical inflection signal for next-generation efficiency leadership and premium pricing capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | In-house lithium iron phosphate pack production reduces warranty exposure and input cost volatility for premium outdoor decoration lines. |
| CE Marking Pre-Certification Investment | Accelerated EN 60598-2-1 compliance cycles capture seasonal retail shelf placement ahead of competitor submissions. |
| Home Improvement Retail Partnership Expansion | Dedicated aisle placement at Lowe's and Leroy Merlin accelerates consumer trial conversion versus pure online discovery channels. |
| Agrivoltaic Technical Collaboration | Partnerships with Dutch greenhouse operators open premium pricing in dual-use crop monitoring and supplemental lighting applications. |
| Lighting-as-a-Service Platform Launch | Subscription models displace capital purchase patterns among California and Florida hospitality property portfolios seeking uptime guarantees. |
Research Methodology
Operator-level perspectives from municipal procurement officers, home improvement retail category managers, flexible lighting manufacturing plant directors, and photovoltaic cell sourcing specialists anchored the qualitative base for this study. Primary interview findings triangulated against secondary validation from EU F-Gas Regulation implementation reports, EPA Energy Star certification databases, BIS standards documentation, and customs trade data tracking polysilicon and lithium-ion battery cross-border flows. Bottom-up unit economics modeling and top-down market sizing approaches converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across polysilicon price volatility scenarios, battery chemistry transition timelines, and regulatory implementation delays. Segmentation dimensions modeled include emitter technology, application context, power source architecture, and length specification alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves applied to disclosed manufacturer capacity expansion plans and procurement pipeline visibility across the projection horizon. Solar irradiance data by latitude and seasonal charge deficit patterns informed regional adoption trajectory assumptions.
Decision-makers should treat outputs as directional under stable polysilicon supply geography and phased EU F-Gas Regulation implementation; material deviation in either assumption would warrant model refresh. Forecasts embed assumptions regarding lithium iron phosphate cost curves and REACH substance restriction enforcement intensity. Recalibration cycles align with material shifts in photovoltaic module pricing and municipal procurement funding authorization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Photocell Market
Lighting
Ring Lights Market
Lighting
North America Outdoor Lighting Market
Lighting
Global Work Lights Market
Lighting
Street Lighting Market
Lighting
Xenon Headlights Market
Lighting
Plasma Lighting Market
Lighting
Global Lighting Control System Market
Lighting
Vintage Bulb Market
Lighting
Global Flame Proof Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Hazardous Lighting Market
Lighting
Hazardous Location LED Lighting Market
Lighting
Street and Roadway Lighting Market
Lighting
Inspection Lighting Fixture Market
Lighting
LED Eye Protection Desk Lamp Market