
 Marine Sensors Market | 2026-2036
Marine Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Sensors Market Analysis
Acoustic engineer shortages across NATO naval bases is unwinding deployment timelines for next-generation sonar arrays. Kongsberg Maritime leverages its Norwegian manufacturing base to sustain dominance in multibeam echo sounders for seabed mapping. Teledyne Marine anchors North American supply through its specialized underwater connectors and pressure-rated housings. Thales Group competes on integrated combat system architectures that bundle sonar with electronic warfare modules.
Marine sensors are electromechanical or photonic devices engineered to measure physical, chemical, or biological parameters in saline environments, typically rated for pressures exceeding 600 bar and corrosion resistance per ASTM G48 protocols. Their primary purpose spans navigation safety, resource exploration, and environmental compliance tracking across sovereign waters. Sonar sensors occupy the largest revenue pool given naval modernization cycles and offshore energy survey activity. Digital technology segments are expanding fastest as vessel operators replace analog bridge instruments with Ethernet-backbone sensor networks. Wireless architectures remain niche but carry above-average margins where retrofitting legacy hulls demands minimal structural penetration.
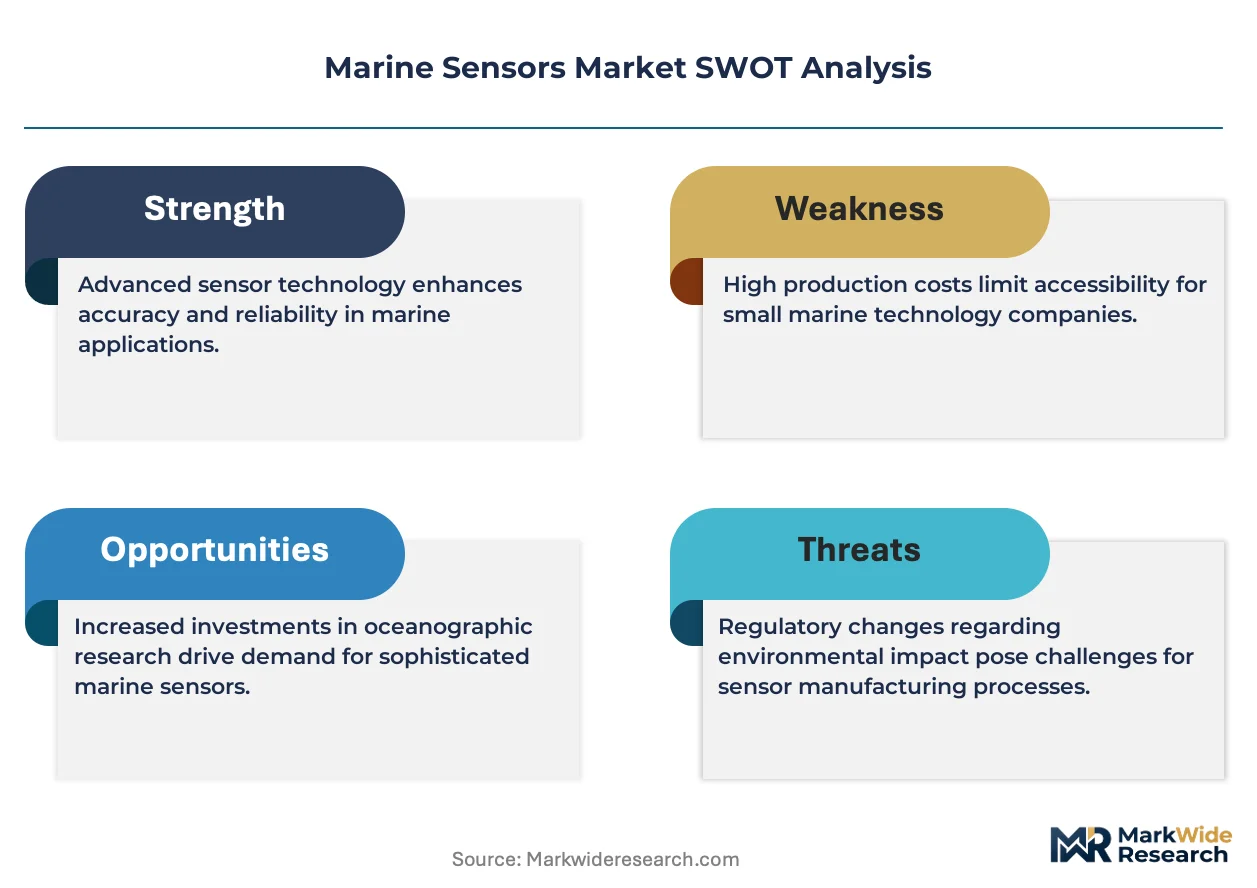
The International Maritime Organization's Polar Code mandates redundant environmental sensing for vessels operating in ice-class waters, while EPA and MEE discharge regulations force ports to deploy real-time water quality sensor grids. Classification societies including DNV and Lloyd's Register now embed sensor reliability standards directly into vessel construction rules. Stakeholders must weigh sovereign content requirements against interoperability protocols when selecting suppliers for dual-use naval-civilian programs.
Market Dynamics
Naval procurement cycles and environmental compliance mandates are compressing sensor refresh timelines while acoustic engineering talent shortages constrain deployment velocity across NATO maritime commands.
Growth Catalysts
- EU Marine Strategy Framework Directive:Member states must deploy real-time water quality monitoring networks in port zones, mandating multi-parameter sensor procurement for environmental compliance tracking.
- Unmanned underwater vehicles:Naval defense programs are integrating multibeam sonar and chemical sensors into autonomous platforms for mine countermeasures and seabed warfare operations.
- Norway's maritime technology cluster:Kongsberg-led manufacturing concentration around Horten and Oslofjord anchors specialized supplier ecosystems for pressure-rated housings and underwater connectors.
Market Restraints
- Titanium and niobium price volatility:Pressure vessel alloys face supply concentration from Russian and Chinese smelters, inflating raw material costs for deep-rated sensor housings.
- Acoustic engineer scarcity:NATO naval bases report 18-month deployment delays for next-generation sonar arrays due to specialized signal processing talent gaps.
- ITAR and dual-use export controls:US State Department licensing friction restricts trans-Atlantic transfer of high-frequency sonar modules to civilian survey operators.
Strategic Opportunities
- Arctic ice-class vessel mandates:The International Maritime Organization's Polar Code requires redundant environmental sensing for ships operating in polar waters, opening retrofit markets for Norwegian and Finnish shipyards.
- Wireless hull sensor architectures:Retrofit demand from legacy vessel fleets is creating above-margin niches where minimal structural penetration preserves hull integrity.
- Digital bridge instrumentation:Ethernet-backbone sensor networks are displacing analog instrument clusters, enabling integrated combat system architectures that bundle sonar with electronic warfare modules.
Industry Challenges
- Classification society certification timelines:DNV and Lloyd's Register reliability testing for vessel construction rules extends product validation cycles by 14-22 months.
- Interoperability protocol fragmentation:Sovereign content requirements in dual-use naval-civilian programs force redundant engineering for national variants of otherwise standard sensor interfaces.
- Legacy analog system integration:Hybrid architectures bridging Ethernet-backbone networks with existing vessel instrumentation demand specialized protocol translation hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Sensors Market |
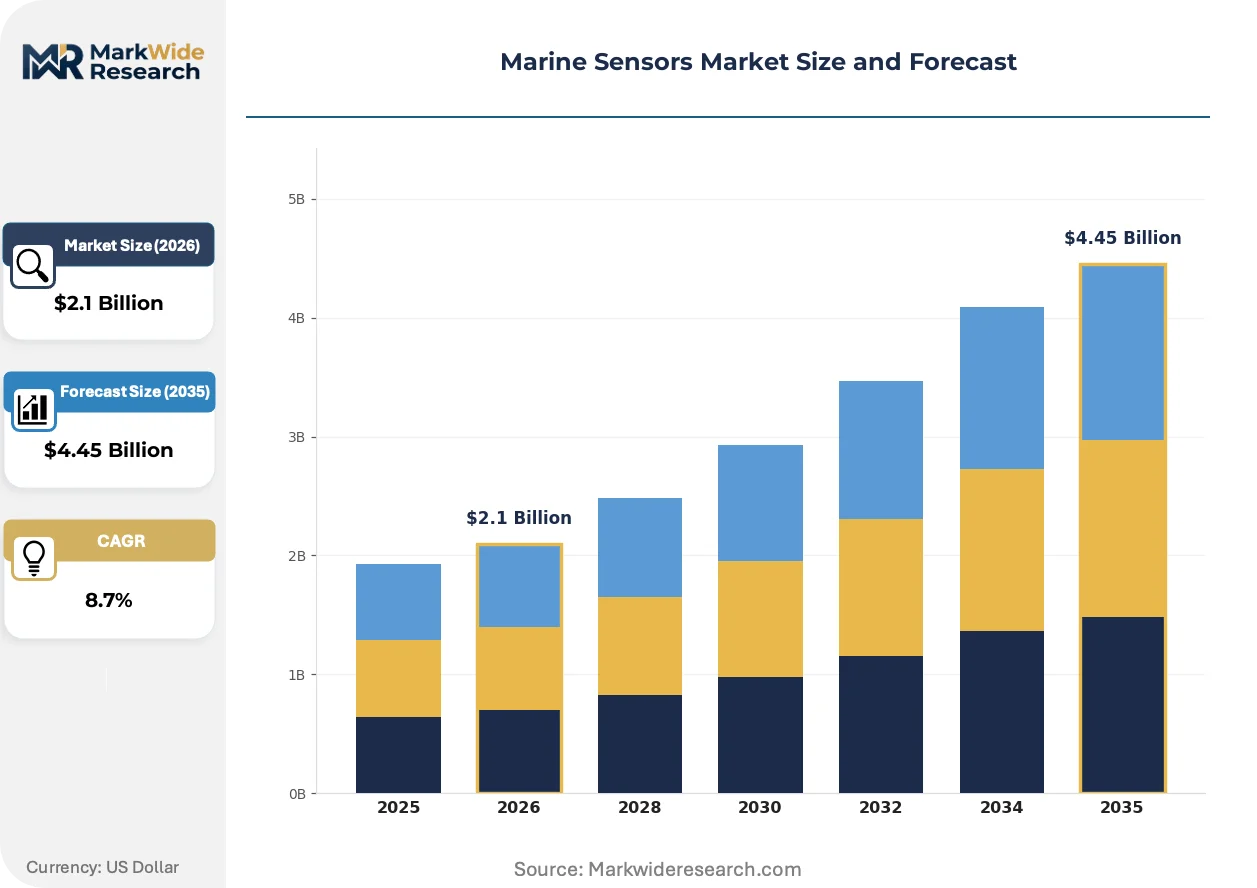
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sonar Sensors, Temperature Sensors, Pressure Sensors, Motion Sensors Application: Environmental Monitoring, Navigation, Fishery Management, Aquaculture Technology: Analog, Digital, Wireless, Optical End User: Shipping Companies, Research Institutions, Government Agencies, Environmental NGOs |
| Companies Covered | Kongsberg Maritime, Teledyne Marine, Thales Group, Garmin Ltd., Furuno Electric, BAE Systems, Honeywell International Inc., Lockheed Martin Corporation, Raytheon Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Sensors Market Emerging Trajectories
Digital sensor architectures and regulatory mandates are restructuring how marine instrumentation is procured, certified, and deployed across naval and commercial fleets.
Photonic sensor platforms is bifurcating the traditional electromechanical sensor market. Fiber-optic pressure and temperature transducers eliminate electromagnetic interference vulnerabilities in high-RF naval environments. French and British naval procurement offices are accelerating pilot programs for photonic gyroscopes and hydrophones. This displacement is compressing margins for legacy piezoelectric sensor suppliers while creating captive demand for specialized optical interrogator hardware.
REACH and RoHS substance restrictions are forcing reformulation of sensor potting compounds and connector sealants used in subsea housings. European manufacturers must eliminate hexavalent chromium coatings and specific phthalate plasticizers from pressure-rated assemblies by regulatory deadlines. The offshore energy survey segment is responding fastest, with Norwegian and UK North Sea operators demanding pre-certified green material specifications in tender documents.
Sensor-as-a-service contracting is displacing capital purchase models in commercial shipping fleets. Greek and Singaporean tanker operators now lease calibrated environmental monitoring packages with embedded maintenance and recertification obligations. This shift transfers obsolescence risk to sensor OEMs while locking in multi-year revenue streams. The model is most visible in ballast water treatment system monitoring, where real-time compliance verification is mandatory under EPA and MEE discharge regulations.
Marine Sensors Market Segmentation
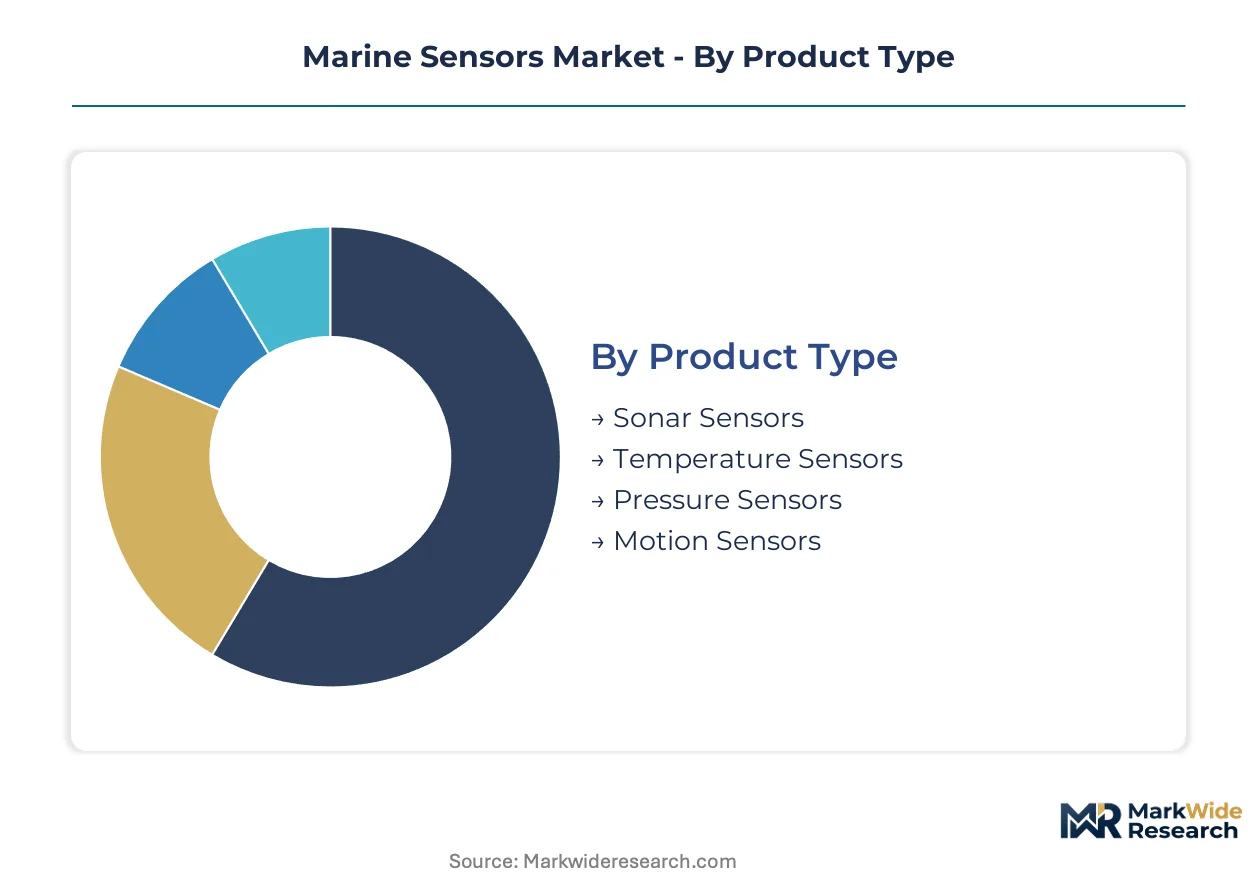
Segmentation in marine sensors reveals how pressure ratings, signal processing architectures, and end-use certification requirements fragment procurement decisions across naval, commercial, and scientific fleets. Understanding these splits exposes where specification premiums concentrate and where standardization pressures erode margins.
Product Type:
Sonar sensors command the widest margin spreads due to dual-use naval-civilian certification overhead and acoustic engineering scarcity, while pressure sensors compete on titanium alloy sourcing efficiency.
- Sonar Sensors:Multibeam and side-scan arrays dominate seabed mapping contracts, with Kongsberg Maritime anchoring supply from its Norwegian manufacturing base. NATO naval programs are compressing deployment timelines for next-generation mine countermeasures systems.
- Temperature Sensors:Fiber-optic thermistors are displacing electromechanical units in ice-class vessels under IMO Polar Code mandates. Finnish and Norwegian shipyards are retrofitting redundant sensing packages for Arctic routes.
- Pressure Sensors:Quartz resonant and piezoresistive transducers rated beyond 600 bar serve offshore energy survey operators. Raw material volatility in titanium and niobium supply chains is inflating housing costs.
- Motion Sensors:MEMS-based inertial units and ring laser gyroscopes support dynamic positioning systems. Photonic gyroscope pilot programs by French and British naval offices are bifurcating legacy supplier margins.
Sonar sensors hold installed capacity. Motion sensors are rotating up the share rankings as autonomous platforms proliferate.
Application:
Environmental monitoring applications are climbing fastest as EU Marine Strategy Framework Directive mandates force port infrastructure upgrades, while navigation retains the deepest specification lock-in through classification society rules.
- Environmental Monitoring:Real-time water quality grids in EU port zones combine pH, dissolved oxygen, and hydrocarbon sensors. EPA and MEE discharge regulations are transferring procurement risk to sensor-as-a-service leasing models.
- Navigation:DNV and Lloyd's Register embed reliability standards directly into vessel construction certification. Bridge instrumentation refresh cycles are accelerating as Ethernet-backbone networks displace analog clusters.
- Fishery Management:Acoustic biomass assessment and net monitoring systems serve North Sea and Barents Sea fleet operators. Scientific echo sounder calibration requirements fragment standardization.
- Aquaculture:Dissolved oxygen and turbidity sensors protect salmon pen yields in Norwegian fjord operations. Wireless architectures are penetrating here due to minimal hull penetration requirements.
Navigation holds installed capacity. Environmental monitoring is expanding most quickly on regulatory enforcement timelines.
Technology:
Digital architectures are displacing analog instrument clusters fastest where vessel operators prioritize Ethernet-backbone integration, while wireless commands above-average margins in retrofit markets.
- Analog:Legacy 4-20mA signal loops persist in aging commercial fleets where certification renewal economics delay replacement. Hybrid protocol translation hardware bridges these systems to modern networks.
- Digital:Ethernet-backbone sensor networks enable integrated combat system architectures bundling sonar with electronic warfare modules. Naval procurement programs are mandating these specifications.
- Wireless:Hull-mounted transducers with inductive or acoustic data links preserve structural integrity in legacy vessel retrofits. Greek and Singaporean tanker operators are adopting leased compliance packages.
- Optical:Fiber-optic pressure and temperature transducers eliminate electromagnetic interference in high-RF naval environments. Specialized optical interrogator hardware is creating captive supplier demand.
Analog holds installed capacity. Optical is gaining share fastest on photonic displacement of piezoelectric platforms.
End User:
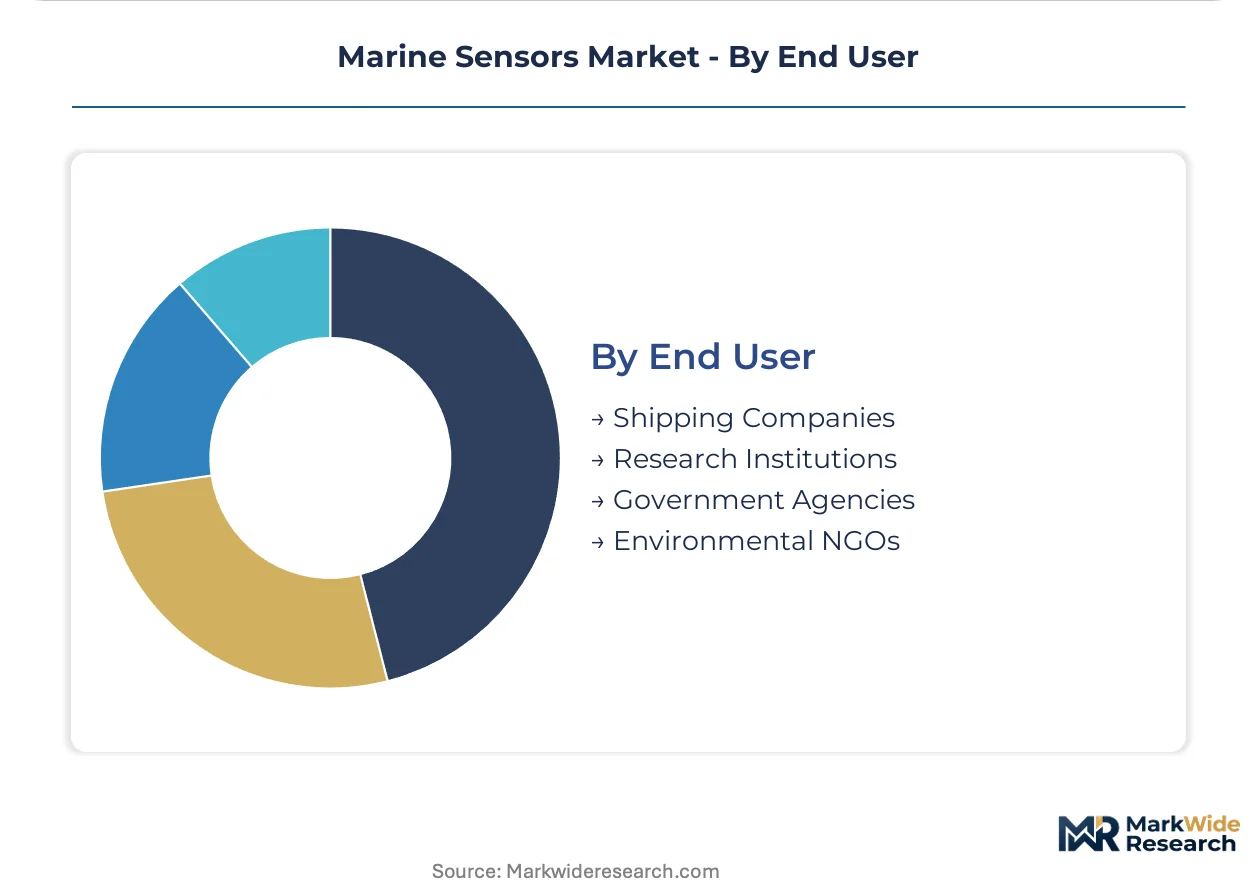
Government agencies concentrate procurement volume through sovereign content requirements, while research institutions drive specification innovation that later diffuses to commercial markets.
- Shipping Companies:Greek and Singaporean tanker fleets are shifting to sensor-as-a-service contracts with embedded maintenance obligations. Ballast water treatment monitoring mandates lock in multi-year revenue streams.
- Research Institutions:Academic and oceanographic programs specify calibrated multibeam systems for seabed mapping. Norwegian and UK North Sea operators are demanding pre-certified green material specifications.
- Government Agencies:Naval defense programs integrate multibeam sonar and chemical sensors into autonomous platforms. ITAR licensing friction restricts trans-Atlantic transfer of high-frequency modules.
- Environmental NGOs:Non-governmental monitoring coalitions deploy citizen-science sensor networks for pollution tracking. REACH and RoHS substance restrictions are forcing reformulation of potting compounds in their procurement.
Government agencies hold installed capacity. Shipping companies are rotating up the share rankings on operational expenditure preferences.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian suppliers command 15-20% price premiums over Asian competitors for pressure-rated sensor housings, while US manufacturers absorb ITAR compliance costs that inflate trans-Atlantic transfer prices for dual-use sonar modules.
Norway
Naval modernization programs and offshore energy survey contracts drive multibeam sonar procurement from Kongsberg Maritime's manufacturing base. The EU Marine Strategy Framework Directive mandates real-time water quality monitoring in port zones. The Horten-Oslofjord cluster anchors specialized supplier ecosystems for titanium pressure housings and underwater connectors.
United States
EPA discharge regulations and Coast Guard ballast water treatment mandates force port infrastructure sensor upgrades. ITAR licensing friction restricts civilian access to high-frequency sonar modules. Teledyne Marine anchors North American supply chains through its specialized underwater connectors and pressure-rated housing production.
France
Naval procurement offices accelerate photonic gyroscope pilot programs for high-RF environments. The ANSM enforces REACH substance restrictions on sensor potting compounds and connector sealants. Thales Group competes on integrated combat system architectures bundling sonar with electronic warfare modules from its domestic engineering centers.
United Kingdom
North Sea offshore operators demand pre-certified green material specifications in tender documents. Lloyd's Register embeds sensor reliability standards directly into vessel construction certification rules. Scottish and English shipyards retrofit redundant environmental sensing packages for IMO Polar Code compliance on Arctic routes.
Japan
Commercial shipping fleets shift toward sensor-as-a-service contracts with embedded maintenance obligations. METI oversees standards alignment for fiber-optic sensor platforms displacing legacy piezoelectric units. Furuno Electric occupies a position within the bridge instrumentation tier serving domestic and export vessel operators.
Marine Sensors Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with Norwegian specialists commanding specification premiums while Asian fabricators compete on volume production of standard pressure transducers. The market structures around three tiers: integrated defense contractors bundling multi-sensor combat systems, mid-cap maritime specialists dominating seabed mapping instrumentation, and component suppliers capturing recurring demand for underwater connectors and housings. M&A activity concentrates on photonic sensor platforms and wireless hull architectures, while strategic partnerships bridge sovereign content requirements with interoperability protocols.
Within the integrated defense tier, Thales Group and BAE Systems exemplify archetypes competing on system-level architectures rather than discrete sensor sales. Kongsberg Maritime anchors the maritime specialist tier through its Norwegian manufacturing concentration. Among component suppliers, Teledyne Marine occupies a position representing North American supply chain anchoring for pressure-rated housings and specialized underwater connectors.
| Leading Market Players |
|---|
| Kongsberg Maritime |
| Teledyne Marine |
| Thales Group |
| Garmin Ltd. |
| Furuno Electric |
| BAE Systems |
| Honeywell International Inc. |
| Lockheed Martin Corporation |
| Raytheon Company |
| Others |
Supply Flow & Price Mechanics
Eighteen-month deployment delays for NATO sonar arrays signal how acoustic engineering scarcity concentrates pricing power with Norwegian specialists while compressing margins for titanium-dependent housing fabricators. This lead-time distortion separates configured-to-order multibeam systems from standard pressure transducers, embedding supply chain shape directly into buyer procurement economics.
Pricing Analysis
Configured-to-order multibeam sonar systems command 40-60% premiums over catalog pressure transducers, with price differentiation driven by DNV certification grade and Kongsberg brand positioning. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration complexity, with naval combat system bundles anchoring the top tier. Cost compression in standard pressure sensors is intensifying because titanium and niobium supply concentration from Russian and Chinese smelters inflates raw material costs. Greek and Singaporean tanker operators exhibit highest price sensitivity through sensor-as-a-service leasing, while French and British naval procurement offices show lowest sensitivity for photonic pilot programs.
Supply Chain Analysis
Eighteen-month acoustic engineering lead times reflect supply concentration in Norway, the United States, and France for specialized underwater connectors and pressure-rated housings. Titanium alloy sourcing draws from Russian and Chinese smelters, optical interrogator hardware feeds from French photonics specialists, and inductive coupling components hinge on Japanese fabrication. Single-source vulnerability in high-frequency sonar modules stems from ITAR licensing friction restricting trans-Atlantic transfer. Distribution runs through sovereign defense procurement offices for naval programs and through sensor-as-a-service providers for commercial shipping retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic signal processing expertise functions as the binding constraint across NATO maritime commands, with specialized talent shortages creating defendable positions for incumbents while opening white-space for photonic platform disruptors.
For Market Incumbents: Compound defensive positioning through backward integration into titanium pressure housing production and captive acoustic engineering training pipelines. Photonic sensor displacement threatens legacy piezoelectric margins, making certification investment in Lloyd's Register ice-class standards the priority lever for Arctic retrofit capture. For New Entrants and Emerging Players: Lead with wireless hull architectures targeting Greek and Singaporean tanker fleets where minimal structural penetration requirements create above-margin retrofit opportunities. Environmental monitoring applications under EU Marine Strategy Framework Directive enforcement timelines represent the most penetrable segment, with ballast water treatment compliance packages as the specific go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from defense conglomerates divesting non-core maritime sensor divisions to focus on integrated combat system platforms. Long-term viability centers on photonic platform transitions and sensor-as-a-service recurring revenue models. Watch for REACH and RoHS enforcement accelerating green material specification mandates as the inflection indicator for pre-certified supplier premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Sensor Platform Development | French and British naval offices accelerate fiber-optic gyroscope pilots for high-RF environments. |
| Backward Integration into Titanium Housing Production | Norwegian manufacturers secure supply chain control over pressure-rated alloy sourcing. |
| Sensor-as-a-Service Contracting Model | Greek and Singaporean tanker operators transfer obsolescence risk to OEMs through leased compliance packages. |
| Wireless Hull Architecture Deployment | Retrofit demand from legacy vessels creates above-margin niches preserving structural integrity. |
| Green Material Certification Investment | Norwegian and UK North Sea operators demand pre-certified REACH and RoHS compliant assemblies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across naval procurement officers, commercial fleet technical managers, acoustic engineering specialists, classification society surveyors, and underwater connector procurement leads. Primary interview insights triangulated against Lloyd's Register certification databases, DNV vessel construction rule filings, EPA discharge regulation enforcement records, EU Marine Strategy Framework Directive implementation reports, and customs trade data for titanium alloy imports. Bottom-up segment sizing and top-down macro validation converged on market estimates.
Across the analysis window, the analytical framework modeled product type splits, application end-uses, technology architectures, and end-user procurement patterns. CAGRs were derived from segment-level growth trajectories weighted by naval modernization cycle timing, environmental compliance enforcement schedules, and autonomous platform proliferation curves. Forecast inputs incorporated acoustic engineering talent pipeline constraints and photonic displacement adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained NATO defense spending, REACH enforcement continuity, or titanium supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding regulatory timelines and technology substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Global Smart Biosensors Market