
 Asia-Pacific Lighting Control Market | 2026-2036
Asia-Pacific Lighting Control Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lighting Control Market Insights
CE marking under the EU-originated framework is unwinding competitive access for Asian manufacturers exporting to affiliated markets, forcing domestic certification realignment. Infineon Technologies leverages its power semiconductor portfolio to anchor controller module supply for industrial automation clients. Panasonic Corporation dominates Japan's building systems channel through integrated BEMS-to-lighting architectures. Signify Holding competes across ASEAN commercial projects with its Interact platform, while Schneider Electric SE extends its Wiser ecosystem into Australian residential new-build specifications.
Lighting control systems govern the intensity, timing, and spectral output of electric illumination through networked switches, dimmers, sensors, and centralized controllers, typically operating via 0-10V analog, DALI-2 digital, or wireless mesh protocols to achieve target lux levels while minimizing wattage draw. Their primary purpose spans energy code compliance, occupant wellbeing optimization, and operational cost reduction in built environments. Wireless technology leads retrofit deployment across aging commercial stock where conduit replacement proves cost-prohibitive, while Zigbee captures specification share in multi-vendor smart home ecosystems requiring interoperability. Sensors represent the fastest-expanding product category as daylight harvesting mandates proliferate across Australian NCC-compliant developments and Singapore BCA Green Mark projects.
China's MIIT enforces GB/T standards for intelligent building systems, compelling controller interoperability with state-backed IoT platforms, while Japan's METI administers Top Runner efficiency benchmarks that disqualify non-adaptive luminaire drivers. Australia's NCC Section J provisions mandate automated lighting shutdown in commercial tenancies, directly stimulating sensor and controller procurement. Facility managers and systems integrators must monitor harmonization gaps between national electromagnetic compatibility regimes and emerging cybersecurity labeling requirements for networked devices.
Market Dynamics
Networked luminaire retrofits across Southeast Asian commercial stock are compressing replacement cycles as building operators prioritize energy code compliance over capital preservation, while China's state-backed IoT platform mandates force controller interoperability redesigns.
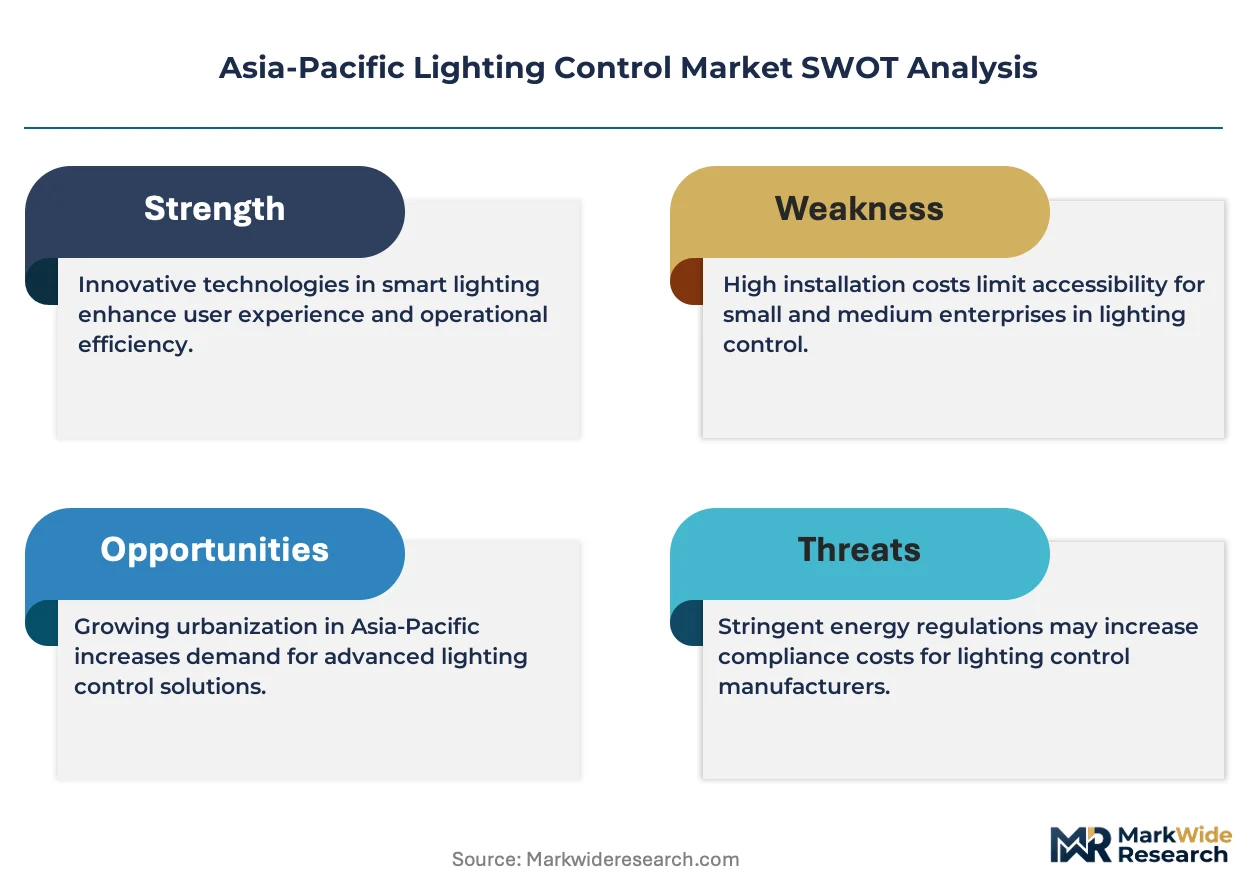
Growth Catalysts
- Japan's METI Top Runner program:Adaptive driver mandates are disqualifying static luminaire systems, forcing wholesale controller upgrades across commercial and industrial facilities.
- Daylight harvesting mandates:Australia's NCC Section J and Singapore's BCA Green Mark specifications are accelerating sensor deployment in new commercial developments.
- Yangtze River Delta smart city infrastructure:Municipal-scale controller and sensor procurement is absorbing production capacity at volumes unmatched elsewhere in the region.
Market Restraints
- Silicon carbide substrate supply concentration:Power semiconductor fabrication for dimming modules relies on concentrated upstream material sources, creating input cost volatility.
- CE marking framework unwinding:Asian manufacturers face domestic certification realignment costs as EU-originated competitive access mechanisms erode in affiliated export markets.
- Legacy 0-10V analog infrastructure:Aging commercial stock with embedded analog wiring limits wireless retrofit penetration where conduit replacement is cost-prohibitive.
Strategic Opportunities
- Indonesian commercial building stock:Underpenetrated networked lighting systems in Jakarta and Surabaya office complexes offer first-mover specification advantages.
- DALI-2 and wireless mesh convergence:Hybrid protocol architectures are opening specification paths in multi-vendor smart home ecosystems requiring interoperability guarantees.
- Australian residential new-build channel:Integrated BEMS-to-lighting architectures are capturing specification share ahead of mandatory efficiency thresholds.
Industry Challenges
- Cybersecurity labeling compliance:Harmonization gaps between national electromagnetic compatibility regimes and emerging networked device security requirements are extending product approval timelines.
- Systems integrator skill scarcity:Shortage of technicians proficient in both DALI-2 commissioning and wireless mesh troubleshooting is constraining deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lighting Control Market |
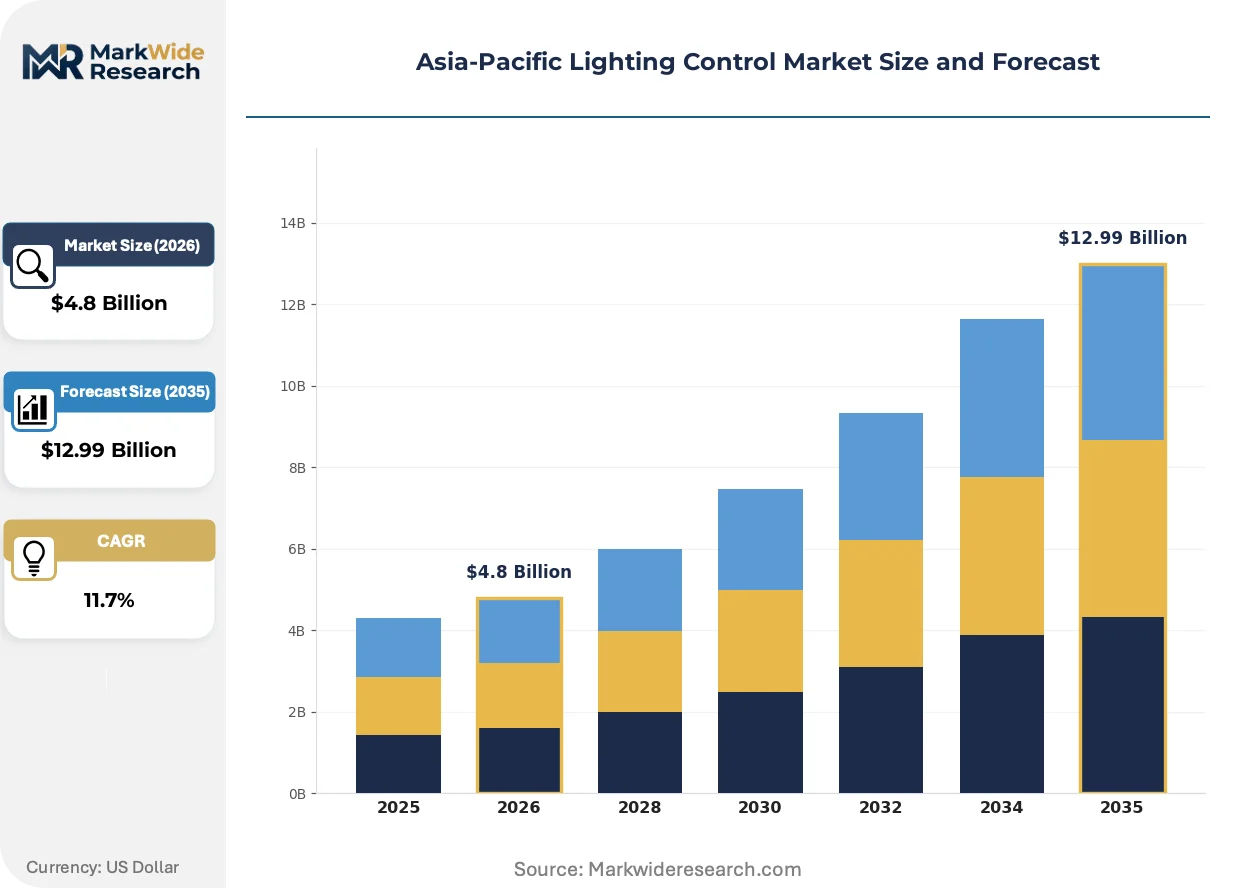
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Switches, Dimmers, Sensors, Controllers Application: Residential, Commercial, Industrial, Architectural Technology: Wireless, Wired, Bluetooth, Zigbee End User: Homeowners, Businesses, Contractors, Facility Managers |
| Companies Covered | Infineon Technologies, Philips NV, Texas Instruments Incorporated, Cisco Systems Inc., Panasonic Corporation, Schneider Electric SE, Toshiba Corporation, Taiwan Semiconductor, Signify Holding, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lighting Control Market Trends and Innovations
Protocol convergence and regulatory tightening are compressing technology lifecycles, forcing vendors to architect for interoperability rather than proprietary lock-in.
Wireless mesh protocols are supplanting wired DALI-2 in Southeast Asian retrofit deployments where conduit replacement costs exceed controller hardware outlays. Facility managers in Singapore and Bangkok commercial towers are specifying Zigbee and Thread-based systems to avoid tenant disruption. This shift is compressing margins for traditional wired infrastructure specialists while elevating software-defined lighting platform valuations.
Australia's NCC Section J automated shutdown mandates are forcing sensor-integrated luminaire specifications across commercial tenancies. The regulation eliminates static switching in favor of occupancy-responsive architectures, directly stimulating controller procurement. Victorian and New South Wales developers are front-loading sensor deployment to preempt enforcement phase-ins.
Building operators are unbundling after-sales service contracts from initial hardware procurement, favoring third-party facility management platforms over manufacturer-captive maintenance. This pattern concentrates in China's Yangtze River Delta manufacturing corridor where smart city operators aggregate multi-site lighting networks under independent systems integrators. The shift is compressing recurring revenue streams for hardware vendors while elevating software subscription valuations.
Asia-Pacific Lighting Control Market Segmentation
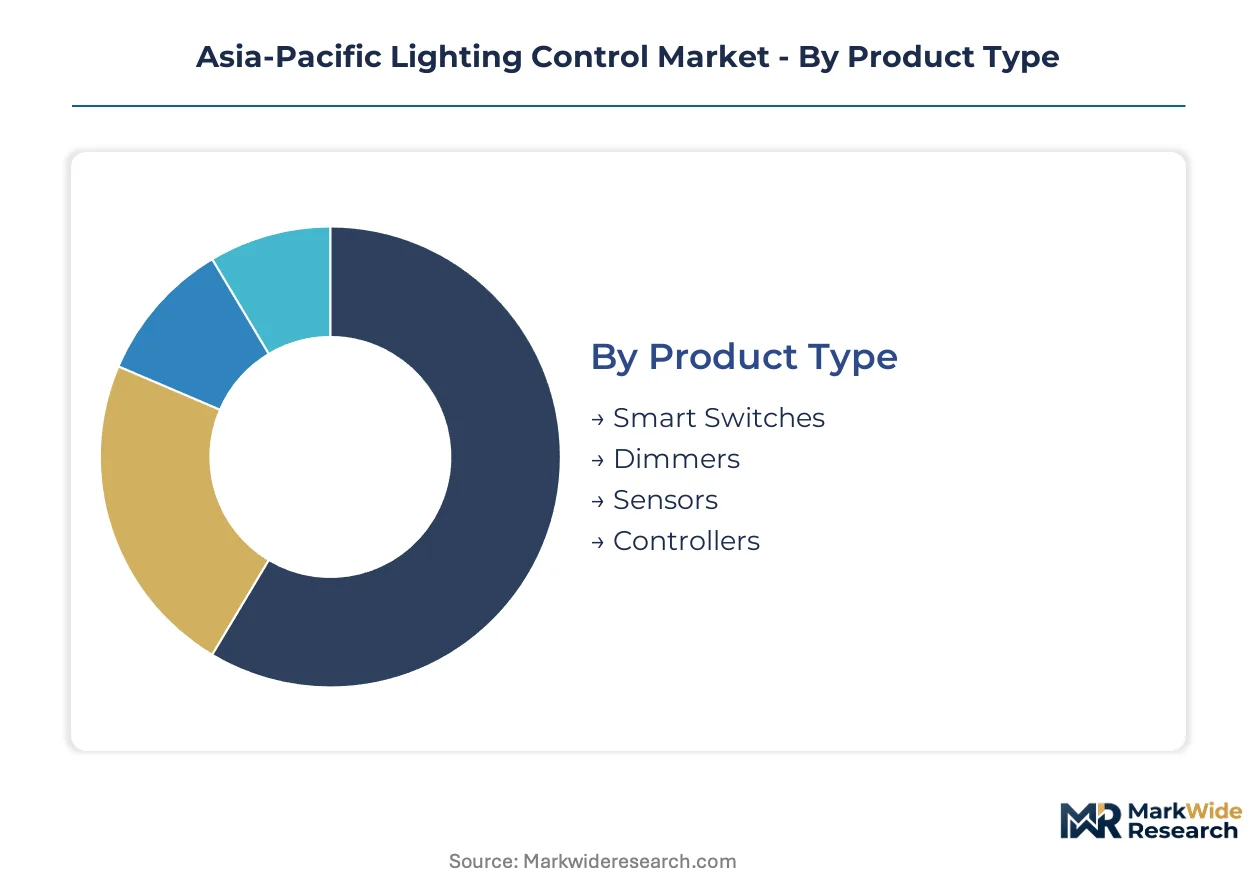
Segmentation in lighting control systems reveals how protocol choices and procurement authority reshape competitive positioning. Product architecture and installation channel determine margin capture across retrofit versus new-build deployment cycles.
Product Type:
Wireless-enabled sensors face the strongest substitution pressure as standalone daylight harvesting units displace integrated luminaire designs across Australian NCC-compliant commercial developments.
- Sensors:Photocell and occupancy detection modules combine passive infrared, ultrasonic, or dual-technology sensing elements. Australian NCC Section J mandates and Singapore BCA Green Mark specifications are accelerating procurement across commercial tenancies in Sydney, Melbourne, and Singapore CBD towers.
- Controllers:Centralized command units coordinate zone-level dimming and switching through DALI-2 or wireless mesh backbones. China's MIIT GB/T interoperability requirements are forcing firmware redesigns for state-backed IoT platform integration across Yangtze River Delta smart city rollouts.
- Smart Switches:Wall-mounted user interfaces enable manual override and scene selection in residential and light commercial settings.
- Dimmers:Phase-cut or 0-10V analog modules modulate forward current to LED drivers.
Sensors anchor the volume base while controllers gain share at the steepest rate.
Application:
Cost tier stratification separates specification-grade architectural systems from mass-market residential hardware across procurement channels.
- Commercial:Networked luminaire systems serving office towers, retail chains, and hospitality properties. Southeast Asian building operators in Jakarta and Bangkok are prioritizing retrofit programs over capital preservation as energy code compliance deadlines tighten.
- Residential:Single-family and multi-unit dwelling installations spanning new construction and renovation. Australian developers in Victorian and New South Wales markets are front-loading integrated BEMS-to-lighting specifications ahead of mandatory efficiency thresholds.
- Industrial:High-bay and hazardous-location controls for manufacturing floors and warehousing operations.
- Architectural:Custom-programmed dynamic lighting for monuments, bridges, and cultural institutions.
Commercial applications dominate absolute spend while residential climbs fastest among end-use categories.
Technology:
Volume concentration in wireless mesh procurement is displacing wired infrastructure share across Southeast Asian retrofit deployments.
- Wireless:Radio-frequency control layers operating on proprietary or open-standard protocols. Facility managers in Singapore and Bangkok commercial towers specify Zigbee and Thread to avoid tenant disruption where conduit replacement exceeds controller hardware costs.
- Wired:DALI-2 and 0-10V analog signaling through dedicated control conductors. Japan's METI Top Runner program disqualifies static luminaire drivers, forcing controller upgrades across commercial and industrial facilities.
- Zigbee:IEEE 802.15.4-based mesh networking for multi-vendor smart home interoperability.
- Bluetooth:Point-to-point and mesh configurations leveraging smartphone-centric commissioning.
Wired technology retains specification share in new Japanese construction while wireless expands most quickly across retrofit-dominant Southeast Asian markets.
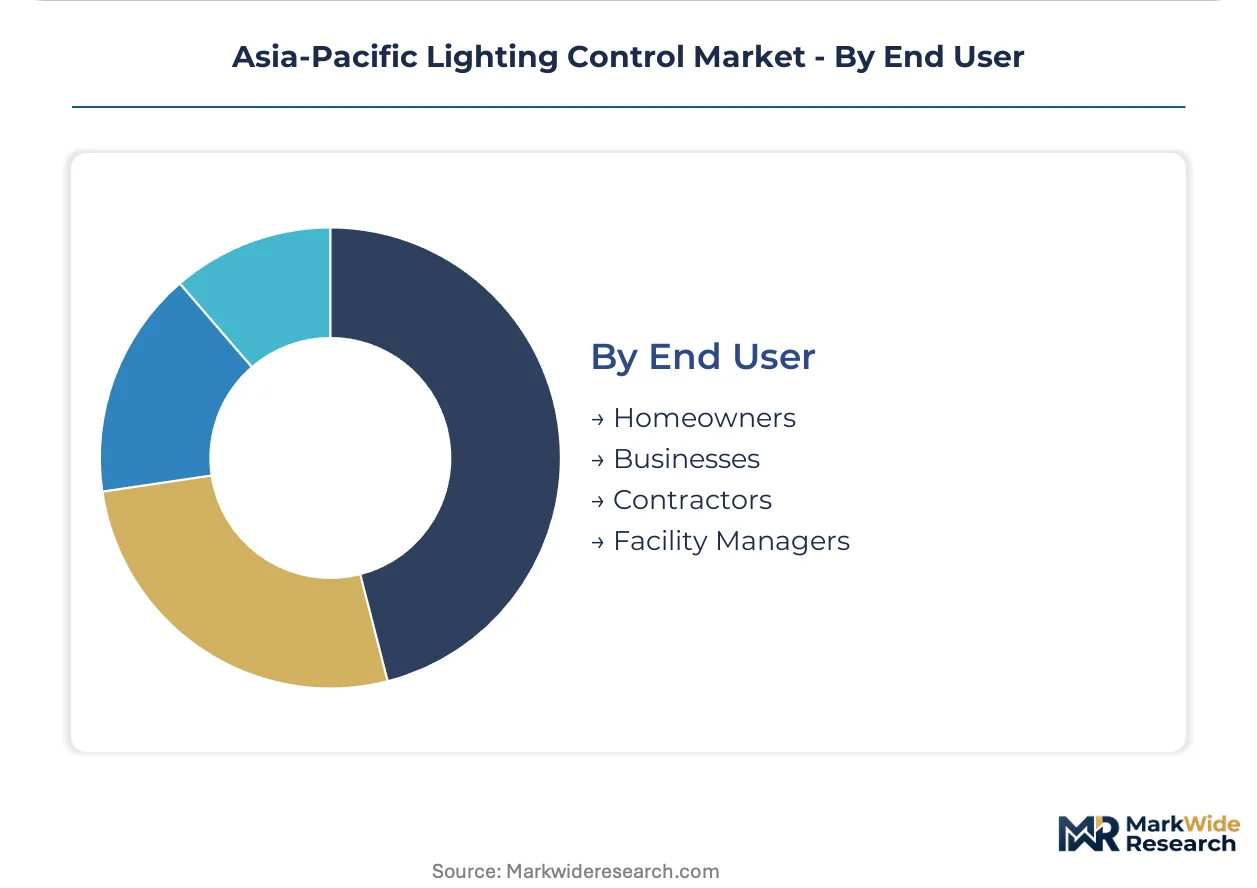
End User:
Customer type determines procurement authority concentration and after-sales service bundling preferences across the region.
- Facility Managers:Multi-site building operators aggregating lighting networks under independent systems integrators. Yangtze River Delta smart city operators are unbundling hardware procurement from maintenance contracts, compressing recurring revenue for manufacturers.
- Businesses:Corporate tenants and owner-occupiers specifying tenant improvement and base building systems. Australian commercial developers face NCC Section J automated shutdown mandates that eliminate static switching in favor of occupancy-responsive architectures.
- Contractors:Electrical installation firms serving residential and small commercial projects.
- Homeowners:Individual consumers purchasing through retail and e-commerce channels.
Facility managers command the largest project scale while businesses drive fastest adoption of subscription-based management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's high-voltage grid interconnect underwrites China's dominance in smart city infrastructure absorption, while Japan's METI regulatory apparatus and Australia's NCC energy codes reshape procurement patterns across the region.
China
MIIT's GB/T interoperability mandates force controller firmware redesigns for state-backed IoT platform integration. Yangtze River Delta municipalities absorb sensors and controllers at volumes unmatched elsewhere. Shanghai and Suzhou smart city rollouts aggregate multi-site lighting networks under independent systems integrators.
Japan
METI's Top Runner program disqualifies static luminaire drivers, compelling wholesale controller upgrades across commercial and industrial facilities. Adaptive driver mandates compress replacement cycles in Tokyo and Osaka building stock. Kansai region manufacturers face interoperability redesigns for BEMS-to-lighting architectures.
Australia
NCC Section J automated shutdown mandates eliminate static switching in favor of occupancy-responsive architectures. Victorian and New South Wales developers front-load sensor deployment to preempt enforcement phase-ins. Sydney and Melbourne CBD towers drive specification-grade procurement for daylight harvesting systems.
Singapore
BCA Green Mark specifications accelerate sensor deployment in new commercial developments. Facility managers in Raffles Place and Marina Bay towers specify Zigbee and Thread to avoid tenant disruption. The city-state's building stock prioritizes energy code compliance over capital preservation in retrofit decisions.
Indonesia
Underpenetrated networked lighting systems in Jakarta and Surabaya office complexes offer first-mover specification advantages. Energy code compliance deadlines tighten across commercial building operators. Java-based facility managers unbundle hardware procurement from manufacturer-captive maintenance contracts.
Asia-Pacific Lighting Control Market Competitive Landscape
Listed leaders compete with private specialists across technology platform differentiation, creating a tiered structure where scale-driven semiconductor fabricators coexist with building systems integrators. The vendor base separates into three strategic archetypes: power semiconductor suppliers anchoring controller module production, integrated BEMS-to-lighting architects, and software-defined lighting platform operators. Dominant competitive moves include strategic partnerships for protocol interoperability and geographic expansion into underpenetrated Southeast Asian commercial stock.
Among Germany-based semiconductor specialists, Infineon Technologies occupies a position exemplifying power semiconductor anchoring for industrial automation controller supply. Netherlands-origin Signify Holding and France-based Schneider Electric SE represent contrasting archetypes in platform competition, with the former competing across ASEAN commercial projects and the latter extending residential ecosystem specifications. Japanese incumbents Panasonic Corporation and Toshiba Corporation anchor integrated building systems channels through METI-aligned efficiency architectures.
| Leading Market Players |
|---|
| Infineon Technologies |
| Philips NV |
| Texas Instruments Incorporated |
| Cisco Systems Inc. |
| Panasonic Corporation |
| Schneider Electric SE |
| Toshiba Corporation |
| Taiwan Semiconductor |
| Signify Holding |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Yangtze River Delta controller fabs shapes both supply concentration and price floors across the Asia-Pacific lighting control market. China's MIIT-mandated GB/T interoperability requirements force firmware redesign costs that transmit downstream, while Japan's METI Top Runner program compresses replacement cycles and elevates specification-grade pricing power.
Pricing Analysis
Certification level creates the primary spread between premium DALI-2 controllers and economy-grade 0-10V analog modules. Project-based pricing dominates commercial retrofit procurement, with volume scale and after-sales service bundling as secondary differentiation drivers. Pricing pressure stems from silicon carbide substrate cost volatility in power semiconductor fabrication. Facility managers in Southeast Asian commercial towers exhibit highest price sensitivity, while Australian NCC-compliant developers prioritize specification-grade sensor integration with lower elasticity.
Supply Chain Analysis
Inventory cycles at Taiwanese power semiconductor foundries extend lead times for dimming module components during Yangtze River Delta smart city procurement surges. Controller manufacturing concentrates in China, Taiwan, and South Korea, with silicon carbide substrates and LED driver ICs as critical input dependencies. Single-source vulnerability in wide-bandgap semiconductor supply creates structural risk exposure. Distribution runs through independent systems integrators in China's manufacturing corridor and electrical contractors in Australian residential new-build channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific lighting control market represents a high-growth disruption as wireless mesh protocols displace wired infrastructure across Southeast Asian retrofit deployments and Australia's NCC Section J mandates force sensor-integrated specifications.
For Market Incumbents: Secure backward integration into silicon carbide substrate supply to dampen input cost volatility from concentrated upstream sources. Lock DALI-2 commissioning expertise through certified technician training programs to constrain deployment velocity for wireless-first competitors. Panasonic Corporation's integrated BEMS-to-lighting architectures demonstrate channel control leverage against pure-play controller vendors.
For New Entrants and Emerging Players: Differentiate on hybrid protocol architectures combining DALI-2 backbone reliability with wireless mesh tenant convenience for Jakarta and Surabaya office complexes. Target Indonesian commercial building stock where networked lighting penetration remains underdeveloped and facility managers unbundle hardware from manufacturer-captive maintenance. Pursue direct specification relationships with Yangtze River Delta smart city operators ahead of state-backed IoT platform consolidation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined lighting platform operators over hardware-centric incumbents as building operators aggregate multi-site networks under independent systems integrators. Acquisition candidates with captive DALI-2 commissioning capabilities and Zigbee/Thread protocol stacks offer longest viability across the projection horizon. Monitor harmonization progress between national electromagnetic compatibility regimes and emerging cybersecurity labeling requirements as inflection signal for product approval timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Protocol Interoperability Partnership | DALI-2 and wireless mesh convergence opens specification paths in Singapore BCA Green Mark projects. |
| Certified Technician Training Program | Systems integrator skill scarcity in Bangkok commercial towers constrains deployment velocity for competitors. |
| Backward Integration into SiC Supply | Power semiconductor fabrication cost volatility threatens margin stability for dimming module producers. |
| Smart City Operator Direct Engagement | Yangtze River Delta municipalities absorb controllers at volumes unmatched elsewhere in the region. |
| Cybersecurity Labeling Pre-Compliance | Australia's emerging networked device security requirements extend approval timelines for non-compliant vendors. |
Research Methodology
Desk research of regulatory filings from China's MIIT, Japan's METI, and Australia's NCC preceded structured interviews with facility managers, systems integrators, and electrical contractors across the Asia-Pacific region. Secondary validation drew from smart city procurement databases, building code compliance records, and power semiconductor trade flow data. Bottom-up sensor and controller shipment analysis triangulated against top-down construction spending and energy efficiency mandate enforcement timelines.
Variance decomposition across product type, application, technology, and end-user dimensions anchored the analytical framework throughout the projection horizon. CAGRs derived from segment-level growth rate synthesis weighted by procurement authority concentration and regulatory enforcement phase-in schedules. Modeled inputs included DALI-2 commissioning capacity expansion, Zigbee certification velocity, and silicon carbide substrate supply elasticity.
Material uncertainties — tariff exposure on Taiwanese semiconductor imports, cybersecurity labeling harmonization gaps, and METI Top Runner efficiency threshold revisions — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and technology substitution elasticities. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Art and Museum Lighting Market
Lighting
Street Lighting Market
Lighting
Softbox Lighting Kit Market
Lighting
Graphene Lighting Market
Lighting
Smart Street Lighting Systems Market
Lighting
Solid State Lighting System Market
Lighting
LED Solar Lighting Market
Lighting
Ultraviolet Lamps Market
Lighting
Ring Lights Market
Lighting
Saudi Arabia Smart Lighting Market
Lighting
Miniature Bulbs Market
Lighting
Xenon Lights Market
Lighting
Smart Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
North America Street Lighting Market