
 COB Photo Light Market | 2026-2036
COB Photo Light Market Size, Share, and Industry Trends Forecast 2026-2036
COB Photo Light Market Insights
Modular kit configurations is broadening buyer choice across the COB photo light landscape. COLBOR leverages compact power-brick designs to serve run-and-gun videographers. Godox anchors its position through deep manufacturing scale in Guangdong. Aputure differentiates via high-CRI output and wireless ecosystem integration.
COB photo light denotes chip-on-board LED arrays where multiple diodes mount directly onto a thermally conductive substrate, enabling high lumen density with minimal optical loss and superior color rendering index values above 95. These fixtures serve cinematographers and studio operators requiring consistent, flicker-free illumination for digital acquisition workflows. LED product types now dominate volume as thermal management advances cut fixture weight and operating cost. Professional photographers represent the deepest margin pool within end users, while color temperature adjusting technology captures premium positioning across rental houses and broadcast facilities.
European Ecodesign directives and REACH substance restrictions shape material selection and disposal pathways for COB modules sold across EU member states. China's GB standards and NMPA-equivalent quality certifications govern export eligibility from Shenzhen and Dongguan manufacturing zones. Stakeholders must track how efficiency benchmarks and circular-economy mandates in multiple jurisdictions reshape component sourcing and product-service bundling decisions.
Market Dynamics
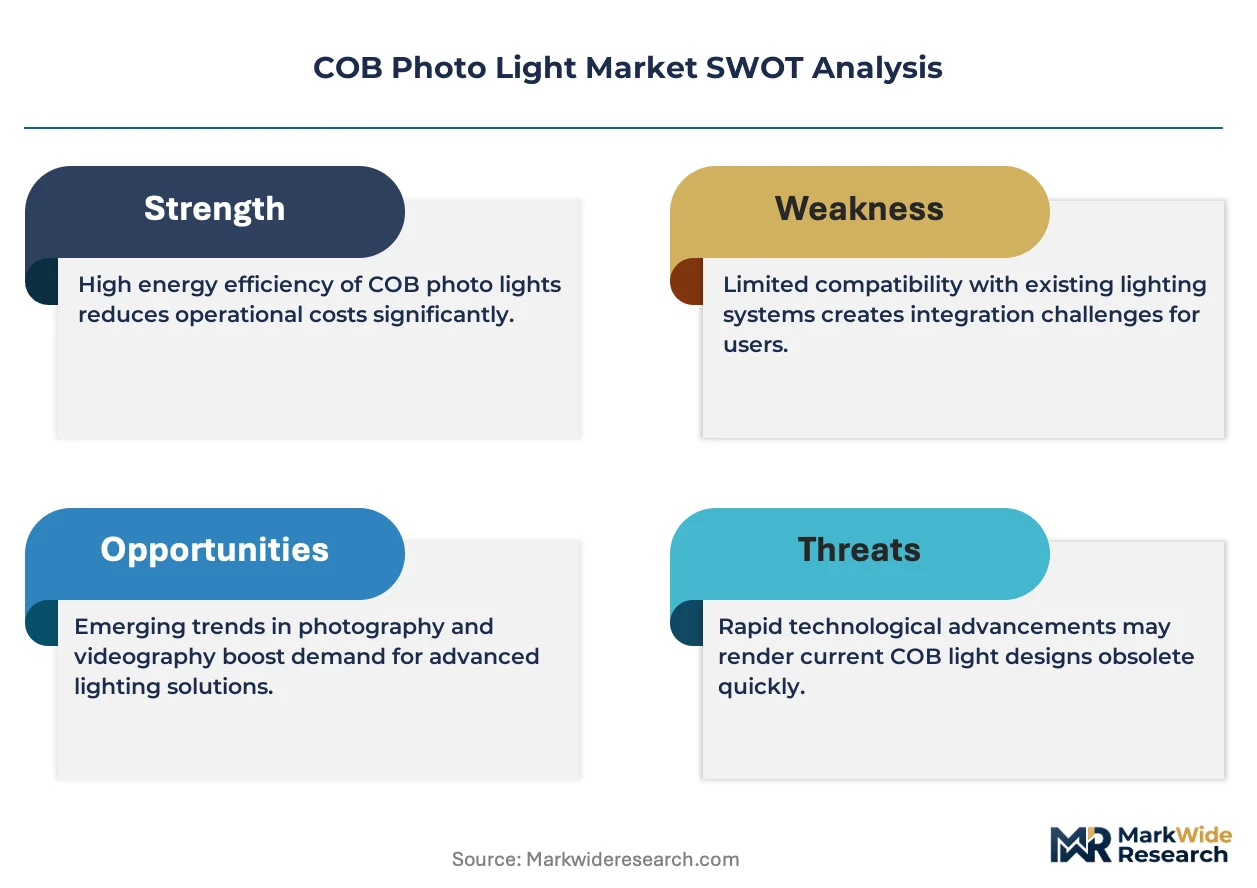
Thermal management breakthroughs in chip-on-board architectures are compressing fixture weights while preserving output fidelity, redirecting capital toward compact professional-grade units and away from legacy tungsten-halogen infrastructure.
Growth Catalysts
- Content creation surge:Independent videographers and streaming studios in China and the United States are standardizing high-CRI LED arrays for digital acquisition workflows.
- REACH substance mandates:European ECHA restrictions on mercury and hazardous materials are accelerating mercury-free LED module adoption across EU member states.
- Shenzhen electronics clustering:Concentrated COB die bonding and substrate manufacturing in Guangdong Province feeds global supply chains with compressed lead times.
Market Restraints
- Phosphor and rare-earth input volatility:Yttrium and cerium price swings destabilize phosphor-converted white LED cost structures for mid-tier manufacturers.
- Single-source substrate dependency:Aluminum nitride and ceramic substrate supply concentrates among Japanese and German specialty materials suppliers.
- Heat dissipation ceiling:Passive thermal limits in compact form factors constrain lumen density scaling for run-and-gun applications.
Strategic Opportunities
- India broadcast infrastructure:TRAI-mandated HD transition and studio modernization create demand for flicker-free, color-tunable fixtures in Mumbai and Delhi production hubs.
- Wireless ecosystem convergence:Integration of DMX512 and Bluetooth mesh control protocols enables smartphone-based lighting orchestration for solo operators.
- EU circular-economy mandates:Ecodesign directive repairability requirements favor modular, field-serviceable COB architectures with swappable LED engines.
Industry Challenges
- Color science talent scarcity:Spectral engineering and CRI optimization expertise concentrates among legacy cinema lighting specialists, constraining product development pipelines.
- Multi-jurisdiction certification timelines:Parallel FCC, CE, and GB standard compliance testing extends product launch cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | COB Photo Light Market |
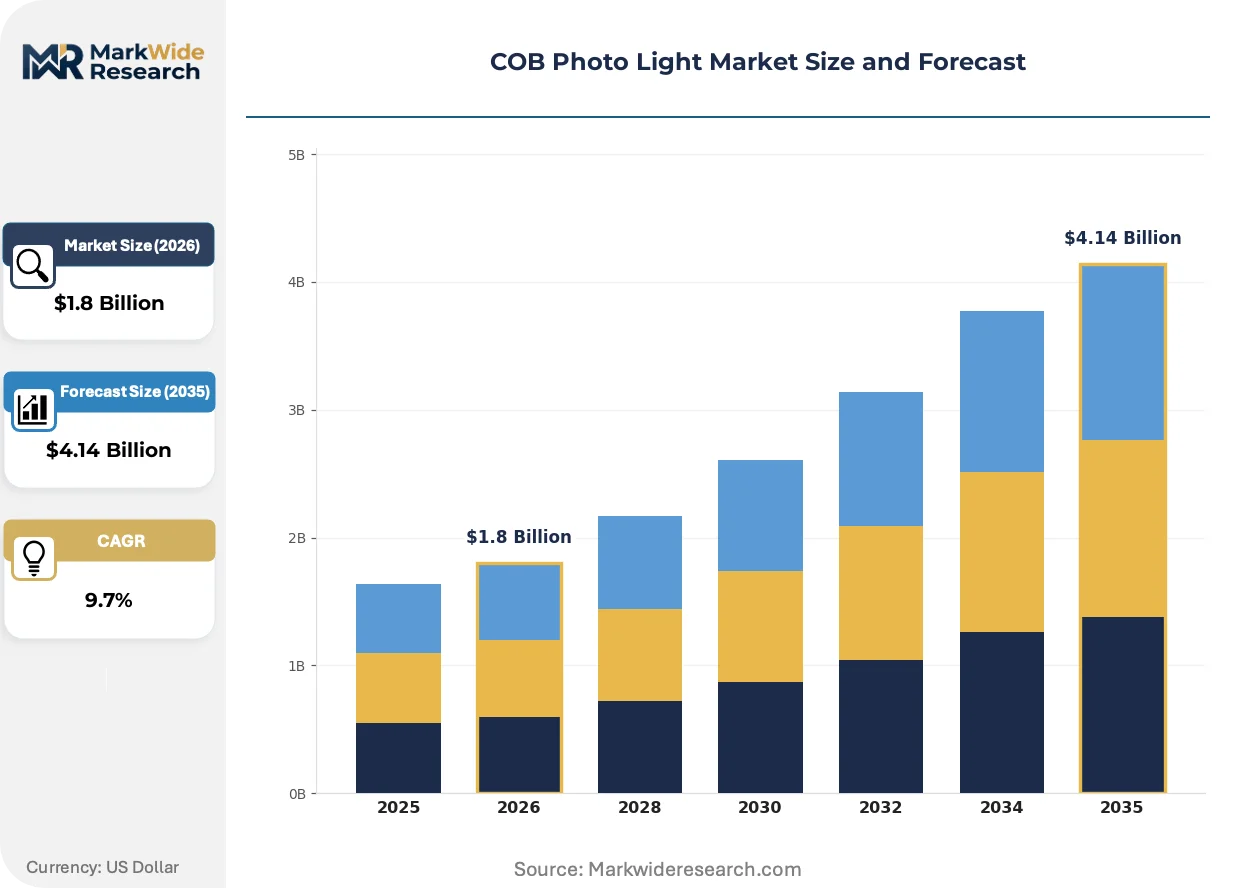
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
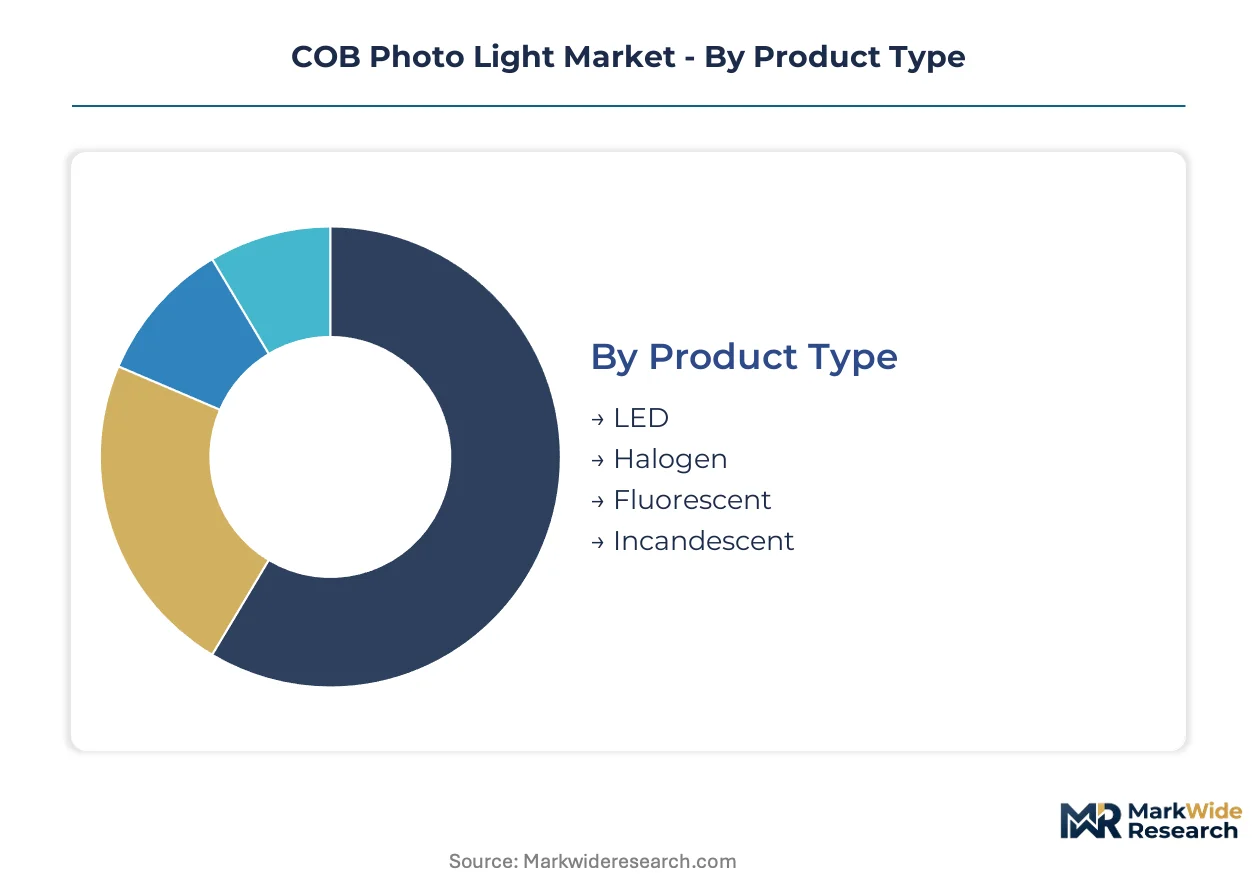
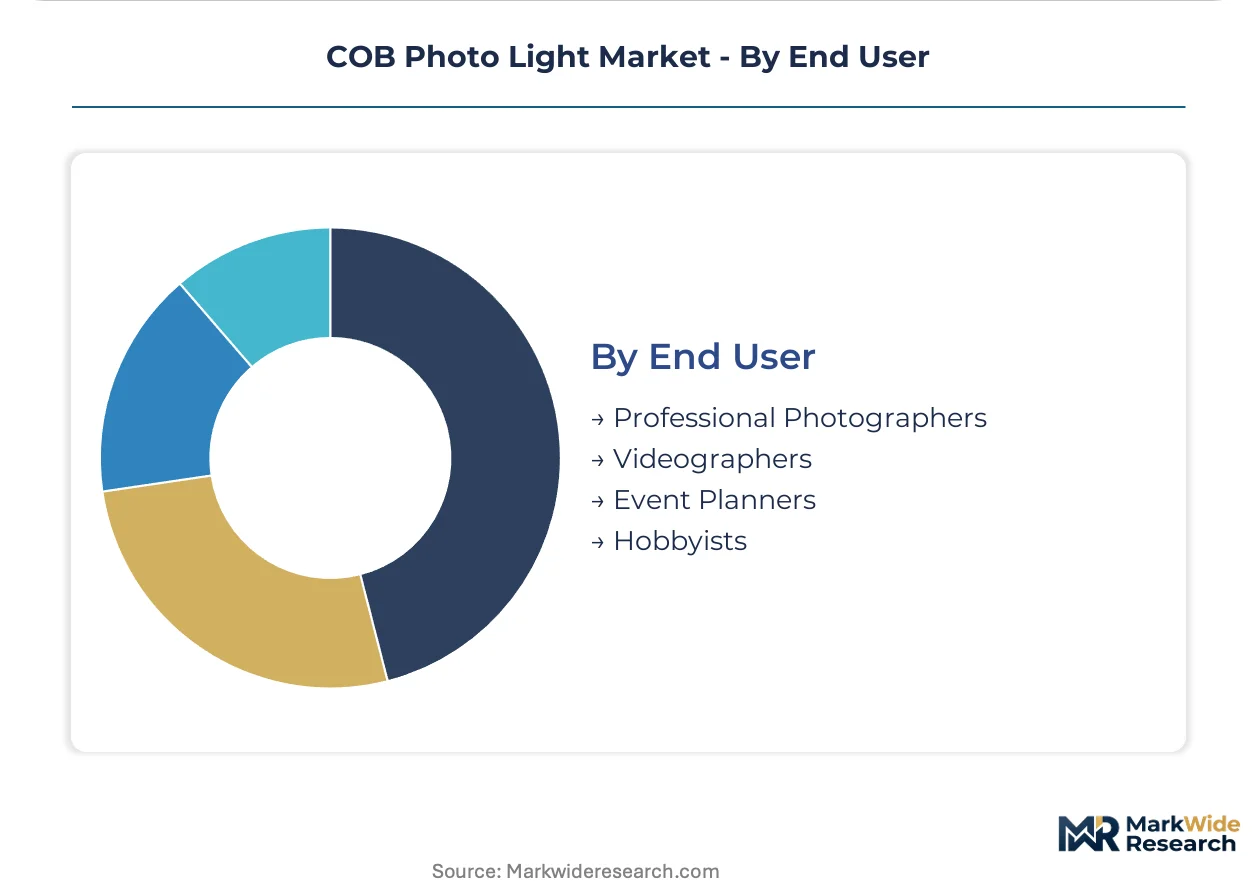
| Segmentation | Product Type: LED, Halogen, Fluorescent, Incandescent Application: Photography, Videography, Studio Lighting, Events Technology: Smart Lighting, Dimmable, Color Temperature Adjusting, Continuous End User: Professional Photographers, Videographers, Event Planners, Hobbyists |
| Companies Covered | COLBOR, Aputure, Godox, NanLite, Jinbei, Arri, Falcon Eyes, Prolycht, Litepanels, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
COB Photo Light Market Trends and Innovations
Active cooling miniaturization and spectral tuning algorithms are compressing the performance gap between studio fixtures and portable units, enabling new deployment scenarios for location cinematography.
Micro-channel liquid cooling is consolidating thermal management in high-output COB modules. Rental houses and broadcast facilities in Germany and California are adopting these systems to sustain 500W+ output in compact housings. The technology is consolidating fixture categories by eliminating the historical trade-off between portability and sustained luminance.
EU F-Gas Regulation phase-down schedules are restricting refrigerant-based cooling options for high-power LED systems. Manufacturers are pivoting toward thermoelectric and phase-change materials to maintain thermal budgets without hydrofluorocarbon dependency. Studio operators in France and the Netherlands face accelerated equipment refresh cycles as legacy cooled fixtures lose serviceability.
Subscription-based lighting-as-a-service models are emerging among production equipment lessors in London and Los Angeles. Freelance cinematographers now access premium COB arrays through weekly rental tiers rather than capital purchase, compressing ownership cycles and elevating utilization rates for rental house inventories. The shift is most visible in commercial advertising and music video verticals with project-based budgeting.
COB Photo Light Market Segmentation
COB photo light purchasing patterns diverge sharply across technical specifications and operator sophistication. Supply chain configuration in Guangdong Province directly shapes which product configurations achieve manufacturing scale and export eligibility.
Product Type:
Die bonding capacity in Shenzhen clusters heavily favors solid-state architectures over legacy filament and gas-discharge alternatives.
- LED:Chip-on-board arrays mount multiple diodes directly onto thermally conductive substrates, achieving lumen densities above 500W equivalent in housings under 3kg. Professional videographers in Los Angeles and Mumbai now specify these fixtures for location shoots where generator power is limited.
- Halogen:Tungsten-halogen filaments still serve rental houses maintaining legacy grip inventories for color temperature consistency with archival footage. Studios in Germany face accelerated replacement timelines as Ecodesign directive efficiency benchmarks render these fixtures non-compliant for new purchases.
- Fluorescent:Compact fluorescent fixtures retain niche presence in educational institutions with constrained capital budgets.
- Incandescent:Residual demand concentrates in theatrical applications requiring specific filament flicker signatures.
LED absorbs the bulk of installed capacity; Halogen is expanding most quickly in retrofit scenarios before regulatory phase-out.
Application:
End-use intensity determines thermal management requirements and control protocol sophistication.
- Videography:Run-and-gun operators demand flicker-free output below 1% at frame rates up to 240fps, driving adoption of high-frequency drivers and active cooling miniaturization. Content creators on YouTube and TikTok represent the steepest expansion trajectory for compact bi-color units.
- Photography:Still-image capture prioritizes CRI values above 95 and short flash durations, with wedding photographers in São Paulo and Jakarta driving demand for battery-powered location kits.
- Studio Lighting:Broadcast facilities require DMX512 integration and consistent output over 8+ hour production days.
- Events:Temporary installations favor rapid deployment and wireless control over color precision.
Videography commands the largest share of unit volume; Photography is climbing the fastest as mirrorless camera adoption expands the addressable base.
Technology:
Control layer differentiation separates premium positioning from commodity replacement markets.
- Color Temperature Adjusting:Bi-color and RGBWW architectures enable 2700K-6500K tuning without gel filtration, commanding rental premiums in London and Los Angeles production equipment pools. The capability requires dual-channel phosphor deposition and precision current balancing that concentrates among Guangdong manufacturers with in-house spectral engineering.
- Smart Lighting:Bluetooth mesh and Wi-Fi enabled fixtures allow smartphone-based orchestration, penetrating solo operator segments in Shenzhen and Austin.
- Dimmable:Phase-cut and 0-10V protocols remain standard for theatrical and architectural integration.
- Continuous:Unregulated output serves basic illumination requirements in developing markets.
Color Temperature Adjusting captures the deepest margin pool; Smart Lighting is gaining share fastest through ecosystem convergence with camera and audio peripherals.
End User:
Operator sophistication dictates service bundling and certification requirements.
- Professional Photographers:Commercial studios and editorial operators specify CRI 95+ output with calibration certificates traceable to NIST or equivalent national standards. This segment absorbs the highest per-unit spend and drives specification conversations at NAB and IBC trade events.
- Videographers:Documentary and commercial cinematographers prioritize weight reduction and battery interoperability, with independent creators in Nigeria and Vietnam representing emerging volume.
- Event Planners:Corporate and wedding producers favor rental flexibility over capital ownership.
- Hobbyists:Entry-level purchasers respond to online tutorial recommendations and bundle pricing.
Professional Photographers anchor manufacturer margin structures; Videographers are expanding most quickly as streaming platform monetization democratizes production access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Guangdong Province while consumption spreads across content creation hubs in North America, Europe, and Asia. Shenzhen's COB die bonding clusters supply global rental houses and broadcast facilities. Import regulations and studio infrastructure investments determine regional adoption velocity.
United States
Los Angeles and New York production studios drive premium fixture demand for streaming content. FCC equipment authorization requirements shape wireless control protocol adoption timelines. Austin and Atlanta emerging as secondary content creation clusters for independent videographers.
Germany
Berlin and Munich rental houses prioritize REACH-compliant mercury-free LED architectures for commercial production. Ecodesign directive efficiency benchmarks accelerate legacy halogen phase-out schedules. Bavaria-based broadcast integrators specify modular field-serviceable COB engines for studio modernization.
China
Shenzhen electronics clustering feeds global supply chains with compressed lead times for COB modules. GB standards and NMPA-equivalent certifications govern export eligibility from Dongguan manufacturing zones. Beijing and Shanghai content creators standardize high-CRI arrays for domestic streaming platform production.
India
Mumbai and Delhi production hubs modernize under TRAI-mandated HD transition requirements. BIS certification timelines influence import sourcing decisions for rental equipment pools. Bangalore post-production facilities drive specification conversations for flicker-free illumination at high frame rates.
United Kingdom
London production equipment lessors pilot subscription-based lighting-as-a-service models for freelance cinematographers. CE marking and post-Brexit UKCA conformity assessment reshape import pathways from EU suppliers. Manchester and Glasgow studios expand capacity for commercial advertising verticals.
COB Photo Light Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the COB photo light landscape. The vendor base spans three tiers: integrated lighting conglomerates with cinema heritage, Guangdong-based manufacturing scale players, and compact specialist innovators. Strategic moves concentrate on wireless ecosystem convergence and modular architecture development. Technology licensing partnerships and geographic distribution agreements dominate competitive dynamics.
Among China-based fabricators, Godox and COLBOR occupy distinct positioning archetypes. Godox exemplifies manufacturing scale advantages rooted in Guangdong production clustering. COLBOR represents compact power-brick specialization for run-and-gun videography segments. Aputure anchors premium-tier positioning through high-CRI output specialization. These three players collectively illustrate how spectral engineering capability and thermal management miniaturization separate margin tiers.
| Leading Market Players |
|---|
| COLBOR |
| Aputure |
| Godox |
| NanLite |
| Jinbei |
| Arri |
| Falcon Eyes |
| Prolycht |
| Litepanels |
| Others |
Pricing and Supply Chain Analysis
Die bonding specialists concentrated in Shenzhen's Bao'an district feed Guangdong's COB module clusters, where labor-cost differentials between tier-one cities and Dongguan manufacturing zones generate 40-60% spreads between premium spectral-engineered fixtures and economy-tier commodity arrays.
Pricing Analysis
Cost compression in mid-tier bi-color fixtures accelerates as Shenzhen manufacturers scale dual-channel phosphor deposition, forcing three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on CRI certification grade and wireless ecosystem integration depth. Pricing pressure stems from rare-earth phosphor volatility. Hobbyist segments exhibit highest price sensitivity; broadcast rental houses absorb premium tiers with minimal elasticity.
Supply Chain Analysis
China's GB standards and domestic-content preferences for NMPA-equivalent certifications are reshaping substrate sourcing, pushing manufacturers toward local aluminum nitride suppliers. Production gravity centers on China, Japan, and Germany for ceramic substrates and phosphor materials. Yttrium and cerium dependencies create single-source vulnerability. Distribution runs through Guangdong export hubs to Los Angeles, London, and Mumbai rental equipment pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH compliance costs and spectral engineering talent scarcity force sub-scale Guangdong fabricators toward acquisition or exit.
For Market Incumbents: Anticipate margin compression from compact power-brick specialists by deepening backward integration into ceramic substrate supply and securing captive phosphor deposition capacity. Prioritize CE marking and FCC authorization investments to compress multi-jurisdiction launch cycles. Defensive patent positioning around active cooling miniaturization protects against emerging thermal-management disruptors. For New Entrants and Emerging Players: Independent Nigerian and Vietnamese videographers represent an underserved buyer archetype with minimal incumbent service infrastructure. Penetrable white space exists in battery-interoperable location kits for 240fps mirrorless workflows. Go-to-market through Shenzhen cross-border e-commerce channels bypasses traditional rental house gatekeepers. For Investors and Strategic Acquirers: The window for entry favors spectral-engineering boutiques with NIST-traceable calibration capabilities and modular field-serviceable architectures. Long-term viability rests on circular-economy compliance and repairability certification positioning. Watch EU Ecodesign directive enforcement velocity as inflection indicator for equipment refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Wireless Ecosystem Integration | Bluetooth mesh and DMX512 convergence enables smartphone-based orchestration for solo operators in Austin and Shenzhen. |
| Modular Field-Serviceable Architecture | Swappable LED engines satisfy EU Ecodesign repairability mandates while compressing rental house maintenance downtime. |
| Phosphor Supply Agreement | Long-term cerium and yttrium offtake contracts stabilize cost structures against rare-earth price volatility. |
| Active Cooling Miniaturization | Micro-channel liquid cooling patents consolidate 500W+ output categories previously split between studio and portable segments. |
| Subscription Lighting-as-a-Service | Weekly rental tiers for London and Los Angeles freelancers elevate utilization rates and compress ownership cycles. |
Research Methodology
Trade customs databases, SEC filings from listed lighting conglomerates, and GB standard certification registries formed the secondary backbone. Primary fieldwork incorporated cinematography equipment rental managers in Los Angeles and Mumbai, spectral engineering leads at Guangdong COB die bonding facilities, broadcast facility procurement officers in Berlin and London, and independent videography content creators across Nigeria and Vietnam. Bottom-up unit economics triangulated against top-down market sizing from production volume and fixture replacement cycle analysis.
Historical trendline analysis of LED lumen density improvements and thermal management cost curves informed projection modeling across the analysis window. Segmentation dimensions included product architecture, application intensity, control protocol sophistication, and end-user certification requirements. CAGRs derived from fitted adoption curves for high-CRI arrays in streaming content production and TRAI-mandated HD transition timelines in Indian broadcast infrastructure.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth export restrictions and F-Gas Regulation phase-down schedules. Forecasts reflect documented assumptions on phosphor deposition yield improvements and wireless protocol standardization velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Softbox Lighting Kit Market
Lighting
High Bay Lighting Market
Lighting
High-End Lighting Market
Lighting
Cleanroom Lighting Market
Lighting
Plasma Lighting Market
Lighting
Circadian Lighting Market
Lighting
Studio Lighting Equipment Market
Lighting
Residential Lighting Fixtures Market
Lighting
Smart Street Lighting Systems Market
Lighting
Global Headlight Control Module Market
Lighting
Europe Decorative Lighting Market
Lighting
Solar Lights Market
Lighting
US Indoor LED Lighting Market
Lighting
Dimmers Market
Lighting
GCC Smart Lighting Market
Lighting
Solar Outdoor LED Lighting Market